Category: Market News

  • Amaroq Begins Maiden Drilling at High-Grade Minturn Prospect in Northwest Greenland

    Amaroq Begins Maiden Drilling at High-Grade Minturn Prospect in Northwest Greenland

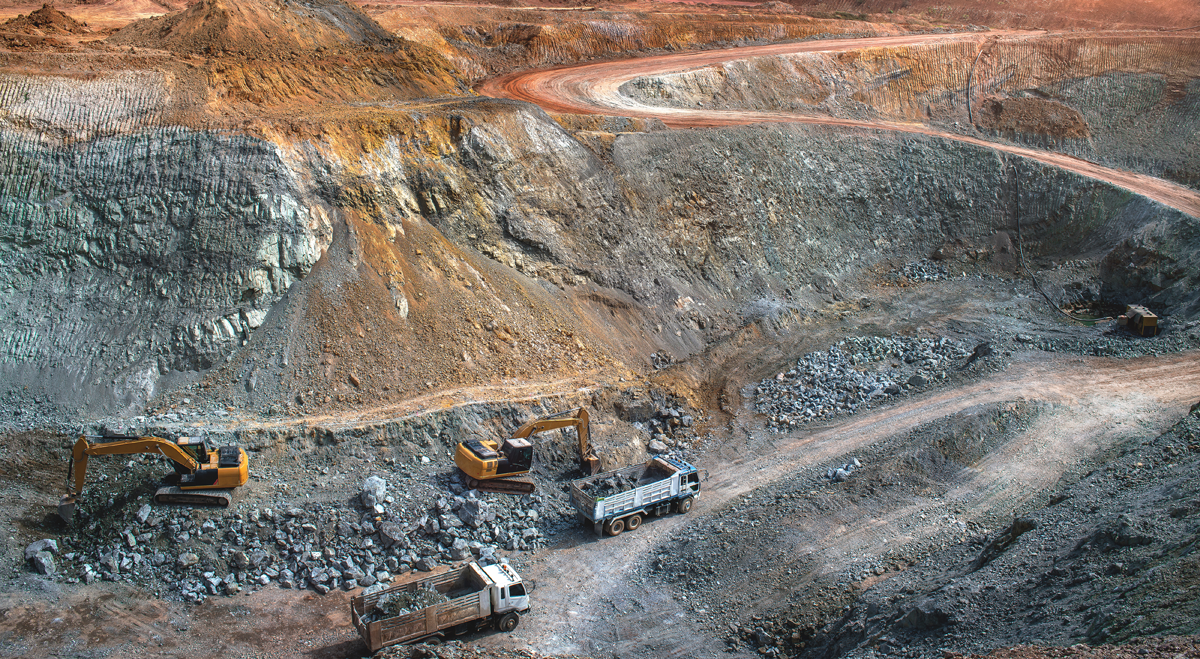
    Amaroq Ltd. (LSE:AMRQ) has commenced its first diamond drilling programme at the Minturn iron-copper-gold prospect in Inglefield Land, Northwest Greenland, marking the initial effort to test the mineralised system below surface. The campaign follows encouraging surface sampling completed in 2025, which returned iron grades of up to 69.5% Fe. The company is targeting what it believes to be Greenland’s strongest regional magnetic anomaly, associated with a magnetic body extending for around nine kilometres within a broader 80-kilometre mineralised corridor.

    Drilling to Accelerate Understanding of Mineral System

    Amaroq has opted to prioritise drilling ahead of previously planned ground geophysical surveys in order to overcome the logistical challenges of operating in the remote region and obtain direct geological information more quickly. The initial drill holes are designed to evaluate both the high-grade iron mineralisation and the associated copper and gold potential. Results will be combined with existing geophysical datasets to refine the geological model, assess the scale of the mineral system and determine whether it shares characteristics with IOCG or Kiruna-style deposits, helping to guide future exploration across the project.

    Exploration Expands Company’s Greenland Strategy

    The Minturn programme represents an important step in Amaroq’s strategy to expand exploration activities into northern Greenland while building technical knowledge and operational experience in the region. The work also supports the company’s broader objective of developing a diversified portfolio of mineral assets across Greenland, strengthening its long-term growth pipeline beyond its existing mining operations.

    About Amaroq Ltd.

    Amaroq Ltd. is an independent mining company focused on the exploration, development and production of gold and strategic metals in Greenland. Its flagship asset is the producing Nalunaq Gold Mine in southern Greenland, while its wider exploration portfolio includes projects targeting gold, copper, nickel, rare earth elements, zinc, lead, silver, germanium and gallium across South and West Greenland, in addition to the Minturn iron-copper-gold prospect in the country’s northwest.

    The company is working to establish an integrated mining business in Greenland through investments in mining services and infrastructure, including its Suliaq logistics business and Imeq ApS, Greenland’s first privately developed hydroelectric project. Amaroq is listed on the London Stock Exchange and Nasdaq Iceland under the ticker AMRQ, and also trades on the OTCQX market in the United States under the symbol AMRQF.
  • Stelrad Delivers Higher Profits and Margins Despite Weaker Market Conditions

    Stelrad Delivers Higher Profits and Margins Despite Weaker Market Conditions

    Stelrad Group PLC (LSE:SRAD) reported resilient interim results for the six months ended 30 June 2026, with higher profitability despite lower sales as challenging construction markets continued to weigh on demand. The radiator manufacturer, which operates across the UK, Europe and Turkey, benefited from its broad geographic presence, disciplined cost management and strong market position in European steel panel radiators.

    Margin Improvement Offsets Lower Revenue

    Group revenue declined 9.1% to £124 million as sales volumes fell 14.6%, reflecting weaker construction activity, the planned withdrawal from a loss-making customer contract and lower sales in Turkey. Despite the softer top-line performance, adjusted operating profit increased 4.9% to £16.7 million, with the operating margin improving to 13.5% as a result of tighter cost controls and a more favourable product mix. The company also reduced net debt, increased its return on capital employed to 29% and raised its interim dividend by 5%. Management said trading during the early part of the second half has been in line with expectations and maintained its full-year guidance despite ongoing market weakness and inflationary pressures.

    Outlook Supported by Strong Balance Sheet

    Stelrad’s outlook is underpinned by a stronger financial position, supported by significant debt reduction and solid cash generation. These strengths help offset weaker earnings quality following the sharp decline in net margins during 2025 and continued pressure on revenue. Technical indicators remain constructive, with the shares trading in a positive long-term trend, although valuation remains demanding due to a relatively high price-to-earnings ratio despite an attractive dividend yield.

    About Stelrad Group PLC

    Stelrad Group PLC is one of Europe’s leading manufacturers and distributors of steel panel radiators and other heating products. Its portfolio includes designer radiators, hydronic, hybrid, dual-fuel and electric heat emitters, alongside towel rails and low surface temperature solutions. The company markets its products under brands including Stelrad, Henrad, Termo Teknik, DL Radiators and Hudevad, supplying more than 500 customers in over 40 countries while holding leading market positions across several European regions.

  • Pan African Resources Reports Lower ASX Depositary Interest Holdings in July

    Pan African Resources Reports Lower ASX Depositary Interest Holdings in July

    Pan African Resources PLC (LSE:PAF) has announced a notable reduction in the number of CHESS Depositary Interests (CDIs) quoted on the Australian Securities Exchange during July 2026. The balance declined from 102,641,421 at the end of June to 71,610,794 by 31 July, representing a net decrease of 31,030,627 CDIs over the month.

    Transfers Reflect Movement Between Listing Venues

    The company said the reduction was the result of investors transferring holdings between ASX-listed CDIs and ordinary shares traded on the London Stock Exchange and the Johannesburg Stock Exchange. Pan African Resources emphasised that the movement does not affect its total issued share capital, instead reflecting changes in where investors choose to hold and trade their shares across the group’s multiple listing venues.

    Outlook Supported by Strong Operations Despite Technical Weakness

    Pan African Resources continues to benefit from strong profitability and a healthy balance sheet, supported by recent operational updates highlighting rapid debt reduction and expectations for further production growth. However, these strengths are partly offset by weaker free cash flow generation and negative technical indicators, with the share price continuing to trade below key moving averages.

    About Pan African Resources

    Pan African Resources is a precious metals producer with primary listings in London, Johannesburg and the Australian Securities Exchange, where it trades under the ticker PAF. The company operates gold mining assets in South Africa through Pan African Resources Funding Company and provides investors with access to its shares across multiple international markets.

  • Potentially AI Expands Free Access as Consumer App Waitlist Reaches 25,000

    Potentially AI Expands Free Access as Consumer App Waitlist Reaches 25,000

    Potentially AI PLC (LSE:AGI) has announced that registrations for early access to its upcoming consumer application have climbed to 25,000, with more than two-thirds of those sign-ups recorded during the past 72 hours. In response to the strong demand, the company has increased the availability of its free Protect plan, allowing every current registrant to receive a one-year licence at no cost. Management said the rapid growth supports its strategy of bringing together multiple leading AI models and tools within a single platform and confirmed that users will be onboarded in stages over the coming weeks.

    Growing User Base Supports Commercial Strategy

    The expanding waitlist provides Potentially AI with an established community of early adopters before the product’s full launch, helping to strengthen its position in the increasingly competitive artificial intelligence software market. By extending free access to all 25,000 registered users, the company is investing in user acquisition while creating opportunities to gather product feedback, refine the platform and encourage long-term engagement. Management believes this early user base will support the wider rollout of its consumer, professional and marketplace AI products throughout 2026.

    Outlook Reflects Strong Momentum but Ongoing Financial Challenges

    Potentially AI continues to face financial headwinds, including recurring losses, inconsistent revenue and negative operating and free cash flow, with cash burn increasing during 2025. However, technical indicators remain supportive, with the shares trading above key moving averages, although momentum measures suggest the stock may be overbought and vulnerable to short-term volatility. Valuation also remains difficult to assess given the company’s negative earnings and the absence of a dividend.

    About Potentially AI PLC

    Potentially AI PLC is a London-based technology company developing a collective artificial intelligence platform that provides access to more than 1,000 open-source AI models alongside systems from leading frontier AI developers. The company aims to serve both consumer and professional users by offering greater control over data, AI model selection and token usage, while enabling customers to build, customise and commercialise AI-powered applications through its planned ecosystem of consumer products, workplace tools and marketplace services.

  • Wynnstay to Double Scottish Fertiliser Production Capacity with Montrose Investment

    Wynnstay to Double Scottish Fertiliser Production Capacity with Montrose Investment

    Wynnstay Group PLC (LSE:WYN) has announced plans to significantly expand its Glasson Fertilisers operations in Montrose, Scotland, by securing a long-term lease on a larger facility on Barrack Road. The investment will create one of Europe’s largest fertiliser blending plants, enabling the company to double its production capacity in Scotland while improving operational efficiency to meet growing customer demand. Part of the project will be financed through the sale of the existing Cobden Street site.

    Expansion Supports Long-Term Growth Strategy

    The new facility is expected to generate a return on net assets of at least 10%, in line with Wynnstay’s capital allocation objectives and its wider Strategy Genesis growth programme. Blending operations will continue at the current Montrose site throughout the construction and transition period, ensuring uninterrupted customer supply. Full commissioning of the new plant is targeted for the first half of the 2027 financial year, strengthening the group’s manufacturing network following the recent expansion of its Avonmouth facility and enhancing its presence in the Scottish agricultural market.

    Outlook Reflects Stable Finances Despite Earnings Pressure

    Wynnstay continues to benefit from a solid financial position, supported by low leverage and a stable balance sheet. However, this is balanced by weaker earnings and a decline in cash flow during 2025. Technical indicators remain moderately positive rather than strongly bullish, while the valuation presents a mixed picture, with an attractive dividend yield offset by a relatively high price-to-earnings ratio following softer profitability. Recent insider share purchases provide an additional, albeit secondary, signal of management confidence.

    About Wynnstay

    Wynnstay Group PLC is a leading UK supplier of agricultural products and services, providing farmers with a broad range of inputs, manufacturing capabilities and technical support. The company supplies products and expertise designed to improve farm productivity, sustainability and profitability, supporting the UK’s food production sector through its integrated manufacturing, distribution and on-farm service network.

  • Gelion Signs £2 Million Development Agreement to Advance Sulfur Battery Technology

    Gelion Signs £2 Million Development Agreement to Advance Sulfur Battery Technology

    Gelion PLC (LSE:GELN) has entered into a funded joint development agreement with Japan’s Mitsui Kinzoku to accelerate the commercial development of its Nano-Encapsulated Sulfur (NES™) cathode active material. Valued at £2 million in milestone-based payments, the collaboration will evaluate the technology in both liquid and solid-state sulfur battery cells for applications spanning electric vehicles, stationary energy storage, consumer electronics, aerospace and defence. The project aims to replace conventional critical-mineral cathodes with sulfur, a lower-cost and more abundant material that can be produced using existing lithium battery manufacturing infrastructure.

    Partnership Creates Route to Commercial Manufacturing

    Under the agreement, Mitsui Kinzoku has secured an option to negotiate manufacturing and distribution rights for Gelion’s NES™ cathode material across selected Asian markets. The arrangement provides a potential pathway towards large-scale commercial production if development milestones are successfully achieved. The partnership also expands Gelion’s network of industrial collaborators, complementing existing relationships with companies including TDK, Nissan and QinetiQ, and further strengthens the company’s strategy of bringing its battery technology to market through established industry partners.

    Commercialisation Strategy Gains Momentum

    Gelion views the agreement as an important milestone in scaling production of its sulfur cathode technology ahead of broader commercial deployment. The project also supports the company’s ongoing pilot-scale development work with the US National Laboratory of the Rockies. The latest collaboration highlights increasing industry interest in sulfur-based battery materials as a potential lower-cost, higher-energy alternative to traditional cathode technologies and provides further evidence of a developing commercial pathway across multiple end markets.

    Outlook Reflects Technology Progress Despite Financial Challenges

    The company’s outlook continues to be influenced by ongoing operating losses, negative earnings and continued cash investment in technology development. These financial pressures are partly balanced by improving technical indicators, with the share price trading above key moving averages and supported by positive momentum. Recent corporate updates have also demonstrated meaningful technical and commercial progress, alongside a reduced EBITDA loss, although execution and commercial timing remain key risks as the technology moves towards market adoption.

    About Gelion PLC

    Gelion PLC is a UK-listed battery technology company specialising in advanced cathode materials for lithium-ion and lithium-sulfur batteries. Its proprietary Nano-Encapsulated Sulfur (NES™) technology is designed to replace conventional critical-mineral cathodes with sulfur, delivering the potential for higher energy density while remaining compatible with existing battery manufacturing processes. The technology is aimed at sectors including automotive, defence, consumer electronics and stationary energy storage.

    The company follows a partnership-driven commercialisation model, collaborating with leading industrial and research organisations including Mitsui Kinzoku, TDK, Nissan, QinetiQ, the US National Laboratory of the Rockies and Germany’s Max Planck Institute of Colloids and Interfaces to accelerate the adoption of its next-generation battery technologies.

  • Young & Co.’s Brewery Issues Shares Under Employee Bonus Scheme

    Young & Co.’s Brewery Issues Shares Under Employee Bonus Scheme

    Young & Co.’s Brewery PLC (LSE:YNGA) has admitted 21,918 new A ordinary shares, each with a nominal value of 12.5 pence, to trading on the London Stock Exchange’s Main Market. Following the admission, the company now has 38,048,005 A ordinary shares in issue, with a proportion of those shares held in treasury. The new shares were issued under a block admission established on 28 May 2026 to satisfy awards granted through the company’s deferred annual bonus scheme.

    Share Issuance Supports Employee Incentives

    The newly issued shares rank equally with the existing A ordinary shares and are fully interchangeable with stock already in circulation. While the issuance results in a slight increase in the number of shares available to investors, it primarily reflects the company’s ongoing use of equity-based incentives to reward employees and align their interests with those of shareholders.

    Outlook Supported by Improving Financial Performance

    Young & Co.’s Brewery continues to benefit from improving profitability and stronger free cash flow generation, although earnings, operating margins and cash conversion have remained somewhat uneven. Technical indicators present a more cautious picture, with the shares trading below key longer-term moving averages and a negative MACD suggesting weaker momentum. From a valuation perspective, the stock remains reasonably priced and is supported by a dividend yield of around 3.1%.

    About Young & Co.’s Brewery

    Young & Co.’s Brewery PLC is a UK hospitality company operating a portfolio of pubs alongside its brewing activities. Listed on the London Stock Exchange’s Main Market, the business provides investors with exposure to a well-established pub estate and beer-focused operations serving customers across its core UK markets.

  • Chesnara Issues New Shares Under Employee Incentive Schemes

    Chesnara Issues New Shares Under Employee Incentive Schemes

    Chesnara plc (LSE:CSN) has issued new ordinary shares with a nominal value of 5 pence each under its 2023 short-term and long-term incentive plans, together with its 2022 savings-related share option scheme. The newly issued shares have been admitted to trading on the London Stock Exchange and rank equally with the company’s existing ordinary shares. Following the latest allotments, Chesnara’s total issued share capital has increased to 231,709,059 shares, resulting in modest dilution for existing shareholders while supporting employee participation in the group’s incentive programmes.

    Equity Awards Support Long-Term Incentive Strategy

    The share issuances were completed through a series of admissions between late April and early August 2026, reflecting Chesnara’s continued use of equity-based remuneration to reward and retain employees. By issuing the shares through an established admission process that did not require a prospectus, the company continues to align management incentives with shareholder interests while supporting its long-term growth and acquisition strategy in the European life and pensions sector.

    Outlook Reflects Strong Balance Sheet but Mixed Earnings Performance

    Chesnara’s outlook remains supported by a strengthened balance sheet, although profitability has been volatile and cash flow has been inconsistent, including a significant cash outflow during 2025. Technical indicators remain constructive, with the shares trading above key moving averages and supported by positive momentum. The investment case also benefits from an attractive dividend yield, although the company’s recent losses have resulted in a negative price-to-earnings ratio, tempering the overall valuation.

    About Chesnara

    Chesnara plc is a FTSE 250 life insurance, pensions and investment group specialising in the acquisition and management of life and pension businesses across Europe. The company administers approximately 1.4 million policies through operations in the UK, the Netherlands and Sweden, combining efficient policy administration with selective new business opportunities and value-enhancing acquisitions.

    Chesnara has built a long track record of returning capital to shareholders, having increased its dividend for 21 consecutive years, while continuing to pursue growth through insurance consolidation across its core European markets.

  • Sanderson Design Group Delivers Revenue Growth Driven by U.S. Expansion and Digital Sales

    Sanderson Design Group Delivers Revenue Growth Driven by U.S. Expansion and Digital Sales

    Sanderson Design Group PLC (LSE:SDG) reported a 6% increase in first-half revenue to £51.4 million, supported by strong performances across its North American operations, manufacturing business and licensing activities. Brand sales in North America rose 19%, manufacturing revenue increased by 19% and licensing income advanced 13%. The group’s direct-to-consumer business also continued to gain momentum, with online sales through its brand websites surging 137% to £1.6 million. Net cash improved to £10.2 million despite ongoing share buybacks, and the board said it expects full-year results to meet current market expectations.

    North America and Manufacturing Continue to Drive Performance

    The company highlighted the United States as its strongest-performing and highest-margin market, benefiting from continued demand for its heritage British brands, high-profile collaborations including Morris & Co. x The Huntington and Highgrove by Sanderson, and stronger relationships with leading interior designers. Manufacturing also delivered a robust performance, helped by restructuring initiatives, the rollout of its Future Factory programme and sustained third-party demand. Continued investment in digital platforms for both retail and trade customers remains a key part of the group’s strategy to support long-term international growth.

    Diversified Business Offsets Softer UK Trading

    Although UK brand revenue declined by 8% during the period, growth in North America and manufacturing more than compensated for the weakness, demonstrating the benefits of the group’s increasingly diversified geographic and operational footprint. Supported by premium design brands, strategic partnerships and continued digital expansion, Sanderson Design Group remains focused on strengthening its international presence while delivering profitable growth.

    Outlook Supported by Balance Sheet Strength

    The company’s outlook reflects a mixed financial profile. A strong balance sheet and improved cash generation during 2026 provide solid support, although earnings have remained volatile and operating margins are relatively thin. Technical indicators remain positive, with the shares continuing to trade in an established uptrend supported by improving momentum. Valuation is somewhat constrained by a relatively high price-to-earnings ratio and a modest dividend yield.

    About Sanderson Design Group PLC

    Sanderson Design Group PLC is a UK-based designer, manufacturer and marketer of luxury wallpapers, fabrics, paints and interior furnishings. The company also licenses its designs for a broad range of home products, including bedding, rugs, blinds and tableware. Its manufacturing operations are based in Loughborough and Lancaster, while its showrooms are located in London, New York and Chicago.

    The group’s portfolio includes well-known brands such as Sanderson, Morris & Co., Zoffany, Harlequin, Clarke & Clarke and Scion. Employing around 500 people worldwide, Sanderson Design Group is listed on AIM under the ticker SDG and continues to expand its presence in the global premium home furnishings market.

  • Goodwin Begins Strategic Review of Mechanical Engineering Business

    Goodwin Begins Strategic Review of Mechanical Engineering Business

    Goodwin PLC (LSE:GDWN) has announced the launch of a strategic review of its Mechanical Engineering division following recent market speculation regarding a possible disposal of assets. The review is intended to assess a range of strategic options that could enhance shareholder value while ensuring the continued stability of the group’s operations and supporting the long-term development of its businesses.

    Potential Asset Sale Among Options Under Review

    As part of the review, Goodwin is considering the possible sale of a significant portion of its Mechanical Engineering division, including several of its principal subsidiaries. The company has appointed Rothschild & Co as its financial adviser to oversee the process and confirmed that discussions are ongoing. Shareholders will be updated as the review progresses, with the outcome expected to influence the group’s future portfolio structure and strategic direction.

    Outlook Supported by Strong Fundamentals

    Goodwin’s investment outlook continues to be underpinned by solid financial performance, including revenue growth, healthy profit margins, low leverage and improving free cash flow. The valuation also remains attractive, supported by a reasonable price-to-earnings ratio and a relatively high dividend yield. However, technical indicators remain weak, with the share price trading below key moving averages and momentum continuing to lag.

    About Goodwin

    Goodwin PLC is a diversified engineering group operating across the mechanical engineering sector through businesses including GSC, GI, Noreva, Easat and Pumps. The company designs and manufactures specialist engineered products while providing industrial services to customers across a variety of end markets. Its broad portfolio supports a diversified business model focused on delivering long-term value for customers and shareholders.