Category: Market News

  • Quilter shares fall as higher tax charge overshadows strong operating performance

    Quilter shares fall as higher tax charge overshadows strong operating performance

    Quilter (LSE:QLT) shares fell around 4.5% after the FTSE 250 wealth manager released its interim results for 2026, with a higher UK policyholder tax rate weighing heavily on reported earnings despite solid underlying business performance.

    For the six months ended 30 June, the company reported IFRS profit after tax of £45 million, broadly unchanged from £46 million a year earlier but well below analyst expectations of roughly £61.6 million. The weaker-than-expected bottom-line performance prompted a sharp decline in the share price during early trading.

    The results highlighted a clear contrast between operating momentum and reported earnings. Revenue increased 12% to £379 million, exceeding market forecasts, while Quilter delivered record client inflows during the period. Pre-tax profit reached £222 million, but a significantly higher policyholder tax charge reduced the final after-tax figure, creating the earnings shortfall that disappointed investors.

    Alongside the results, the company announced an interim dividend of 2.1 pence per ordinary share, which will be paid in September. However, the dividend announcement was insufficient to offset concerns over the weaker reported earnings and the impact of taxation on profitability.

    The market reaction was particularly notable given the strength of the wider UK mid-cap market. The FTSE 250 had recently reached record levels after moving above the 24,000-point mark, but the positive backdrop offered little support as investors focused on Quilter’s earnings miss.

    The results have also renewed attention on the effect of UK tax policy on wealth managers offering policyholder products. While the company’s underlying business continues to perform well, supported by strong revenue growth and record net inflows, investors are reassessing the potential for higher policyholder tax rates to continue weighing on reported earnings in future reporting periods.

    About Quilter

    Quilter is a UK-based wealth management and financial advice group providing investment management, financial planning and platform services to advisers and individual clients. The company offers a broad range of savings, investment and retirement solutions, helping customers build and manage long-term wealth.

    With a nationwide adviser network and integrated investment platform, Quilter focuses on growing assets under management, attracting new client inflows and delivering long-term value through a combination of advice, investment expertise and technology.
  • Wizz Air expands capacity despite higher costs weighing on first-quarter earnings

    Wizz Air expands capacity despite higher costs weighing on first-quarter earnings

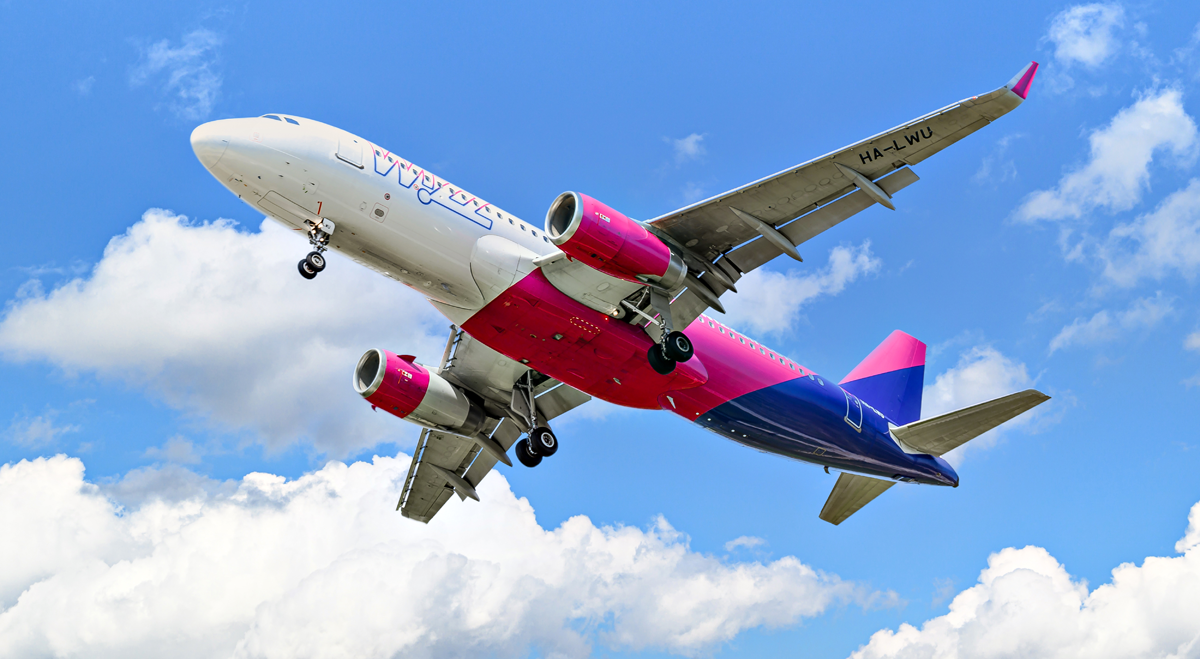
    Wizz Air (LSE:WIZZ) delivered strong passenger growth during the first quarter, with traffic increasing 25% year on year as the airline continued to expand capacity through its predominantly Airbus A321neo fleet. Despite the increase in demand, higher fuel prices and pressure on ticket yields resulted in a net loss of €198.2 million. The airline nevertheless maintained one of the strongest liquidity positions in the European aviation sector, continued returning aircraft affected by Pratt & Whitney GTF engine inspections to service, expanded its network with new bases in Spain and Kosovo, and confirmed plans to introduce satellite-based in-flight internet to enhance the customer experience.

    Operational performance also improved during the period, with stronger on-time performance and a completion rate close to 100%. While higher fuel costs increased unit costs (CASK) and rapid capacity expansion weighed on unit revenues, management continued to focus on disciplined cost control and careful capacity allocation. Wizz Air remains committed to further double-digit capacity growth, supported by extensive fuel hedging, a substantial aircraft order book and a strategy designed to capture additional market share as European airline supply and demand continue to rebalance.

    The investment outlook remains mixed. Recent profitability has been affected by higher operating costs, while the company’s relatively high debt levels increase financial risk within the cyclical airline industry. However, improving cash generation, an attractive valuation based on earnings multiples and technical indicators pointing to a moderately positive share price trend provide support for the longer-term investment case.

    About Wizz Air Holdings

    Wizz Air Holdings is one of Europe’s leading ultra-low-cost airlines, operating short- and medium-haul routes across Central and Eastern Europe as well as major Western European markets. The company operates one of the youngest and most fuel-efficient fleets in the industry, centred on the Airbus A321neo aircraft.

    Its business model focuses on maintaining low operating costs through high aircraft utilisation, efficient point-to-point networks and disciplined capacity management, enabling the airline to offer competitive fares while pursuing long-term market share growth.

  • Serco delivers higher first-half profit as defence growth supports margins and shareholder returns

    Serco delivers higher first-half profit as defence growth supports margins and shareholder returns

    Serco Group plc (LSE:SRP) reported a solid first-half performance, with revenue increasing 4% to £2.5 billion and underlying operating profit rising 9% at constant currency to £157 million. The improvement was driven by 10% organic growth in the Defence division and a more favourable mix of higher-margin contracts. Underlying operating margin increased to 6.2%, while the company maintained a strong balance sheet with leverage of 0.75 times EBITDA. Reflecting confidence in its financial position, Serco increased its 2026 share buyback programme to £150 million and raised its interim dividend by 10%.

    Management reaffirmed its full-year guidance, forecasting revenue of around £5 billion, organic growth of approximately 3% and underlying operating profit of about £300 million. Free cash flow is expected to reach around £160 million for the full year despite lower cash generation during the first half. Serco also highlighted a £12.8 billion bid pipeline, with significant opportunities across the defence sector and North America. The company continues to simplify its operations by focusing on its three core markets—Defence, Justice & Immigration, and Citizen Services—while making progress on major contracts that are expected to support long-term profitability and sustainable growth.

    The investment outlook remains positive, supported by strong cash generation, a healthy balance sheet and an attractive valuation based on a low price-to-earnings ratio. Technical indicators also remain favourable, with the shares continuing to trade in an upward trend. Management’s outlook is supported by a robust pipeline and expectations for further profit growth, although exposure to immigration-related contracts, higher financing costs and the execution of large projects remain potential risks.

    About Serco Group plc

    Serco Group plc is an international provider of outsourced public services, employing more than 50,000 people across sectors including defence, space, migration, justice, healthcare, transport and customer services. The company partners with governments around the world to deliver essential public services through long-term contracts.

    Its capabilities include programme management, systems integration, engineering, advisory services, asset management and operational support, enabling governments to improve service delivery while managing complex infrastructure and public sector operations.

  • Persimmon reports higher first-half earnings as home completions continue to grow

    Persimmon reports higher first-half earnings as home completions continue to grow

    Persimmon (LSE:PSN) delivered a strong first-half performance, increasing home completions by 13% to 5,189 while new housing revenue also rose 13% to £1.48 billion. Underlying operating profit climbed 10% to £189.1 million despite a modest reduction in operating margin. Management attributed the performance to gains in market share, stronger brand positioning and the benefits of greater vertical integration, although affordability pressures and higher construction costs continue to present challenges across the UK housing market.

    The housebuilder now expects to complete around 12,500 homes during 2026, placing delivery at the upper end of its previous guidance range. Profit expectations remain in line with market forecasts, supported by a 5% increase in the private forward order book to £1.31 billion. Looking ahead, Persimmon plans to expand its cost-efficiency initiatives and maintain a disciplined approach to land investment in preparation for anticipated build cost inflation in 2027. Over the medium term, the company aims to increase housing volumes, strengthen cash generation and deliver sustainable shareholder returns while maintaining a robust balance sheet and meeting its building safety and remediation commitments.

    The investment outlook remains mixed. Although Persimmon benefits from a strong balance sheet with low levels of debt, recent cash flow performance has weakened and profitability remains below the peak levels achieved in previous years. Technical indicators also remain subdued, with the shares trading below key moving averages and negative momentum signals. However, a reasonable valuation and a dividend yield of around 4.7% continue to provide support for the investment case.

    About Persimmon

    Persimmon is one of the UK’s largest residential property developers, building homes through its Persimmon Homes, Charles Church and Westbury Partnerships brands. The company develops both private and affordable housing across the UK, supported by a nationwide land portfolio and a vertically integrated operating model.

    By combining efficient construction processes with disciplined land acquisition and broad geographic coverage, Persimmon aims to deliver high-quality homes while generating sustainable long-term returns in the UK’s structurally undersupplied housing market.

  • Harbour Energy raises production outlook and unveils $250 million share buyback

    Harbour Energy raises production outlook and unveils $250 million share buyback

    Harbour Energy (LSE:HBR) delivered record first-half production of 509,000 barrels of oil equivalent per day (boepd), supported by the acquisition of LLOG’s U.S. assets and strong operational performance in Norway. Reflecting this momentum, the company increased its full-year production guidance to between 490,000 and 500,000 boepd. Revenue climbed to $6.4 billion, while free cash flow reached $1.8 billion, enabling accelerated debt reduction and reinforcing Harbour’s position as one of the largest independent producers of European natural gas and offshore oil.

    During the period, Harbour completed three significant portfolio transactions that expanded its presence in the U.S., strengthened its UK asset base and exited non-core operations in Indonesia. The company also continued to advance a range of development projects, including subsea developments in Norway, LNG initiatives in Argentina and offshore fields in Mexico. Supported by stronger commodity prices and robust cash generation, Harbour reaffirmed its capital expenditure plans, declared an interim dividend and launched a new $250 million share buyback programme. These measures increase planned shareholder distributions for 2026 to at least $800 million, highlighting management’s confidence in the company’s financial outlook.

    Harbour also refinanced its $3.0 billion revolving credit facility, extending its maturity to 2031 on improved terms while maintaining investment-grade credit ratings. This strengthens the company’s financial flexibility to support future investment and manage changing market conditions. Operational performance remained strong, with high asset reliability, although unit operating costs edged higher during the period. The company also continued to lower the greenhouse gas emissions intensity of its operations, reflecting its focus on efficient and responsible production.

    The investment outlook remains favourable, supported by strong cash flow generation, a healthier balance sheet and a clearly defined shareholder returns policy. Management’s upgraded production guidance and disciplined capital allocation provide additional confidence, although technical indicators suggest the shares may be approaching overbought territory. Valuation remains mixed, with an attractive dividend yield balanced against a negative price-to-earnings ratio resulting from previous earnings volatility.

    About Harbour Energy

    Harbour Energy is an independent oil and gas exploration and production company with operations spanning the UK, Norway, the United States, Argentina, Mexico and Southeast Asia. Its portfolio is weighted towards offshore oil production and European natural gas, while its growing presence in the U.S. Gulf of Mexico and infrastructure-led developments provides additional long-term production opportunities.

    The company focuses on maintaining reliable production, improving operational efficiency and recycling capital through acquisitions, divestments and organic growth projects. By combining disciplined investment with a commitment to shareholder returns, Harbour aims to strengthen its position as a leading independent energy producer while supporting long-term cash flow generation.

  • PZ Cussons returns to profit growth as balance sheet strengthens and dividends increase

    PZ Cussons returns to profit growth as balance sheet strengthens and dividends increase

    PZ Cussons (LSE:PZC) delivered a strong performance for the 2026 financial year, with like-for-like revenue increasing 5.8% and growth recorded across each of its four core markets as well as its ten largest brands. Adjusted operating profit rose 24.5%, excluding the contribution from the divested PZ Wilmar joint venture, while the company reduced net debt to £25 million through improved cash generation and asset disposals. Reflecting the stronger financial position, the board increased the dividend by 2.8%, marking a return to dividend growth, although management cautioned that macroeconomic uncertainty remains. Trading at the start of the 2027 financial year has been in line with expectations.

    During the year, the company completed a strategic review of its African operations and decided to retain and develop the business while introducing tighter risk management measures. PZ Cussons also completed the £51.2 million sale of its interest in the PZ Wilmar joint venture, simplifying the group’s portfolio and reducing its exposure to fluctuations in the Nigerian naira. Elsewhere, the company refreshed the growth strategy for its premium St.Tropez brand, increased marketing investment behind major product launches in key markets and introduced a new capital allocation framework focused on maintaining moderate leverage while supporting progressive dividend growth. It also announced that two non-executive directors will step down at the next annual general meeting.

    The investment outlook remains mixed. While underlying profitability and cash flow quality continue to present challenges, the company’s improving balance sheet and debt reduction provide greater financial flexibility. Technical indicators remain supportive, with the shares continuing to trade in an upward trend, although momentum appears relatively stretched. Valuation is balanced by an attractive dividend yield but offset by a negative price-to-earnings ratio, while management’s updated guidance and deleveraging progress are encouraging despite ongoing foreign exchange risks and execution challenges during the second half of the financial year.

    About PZ Cussons

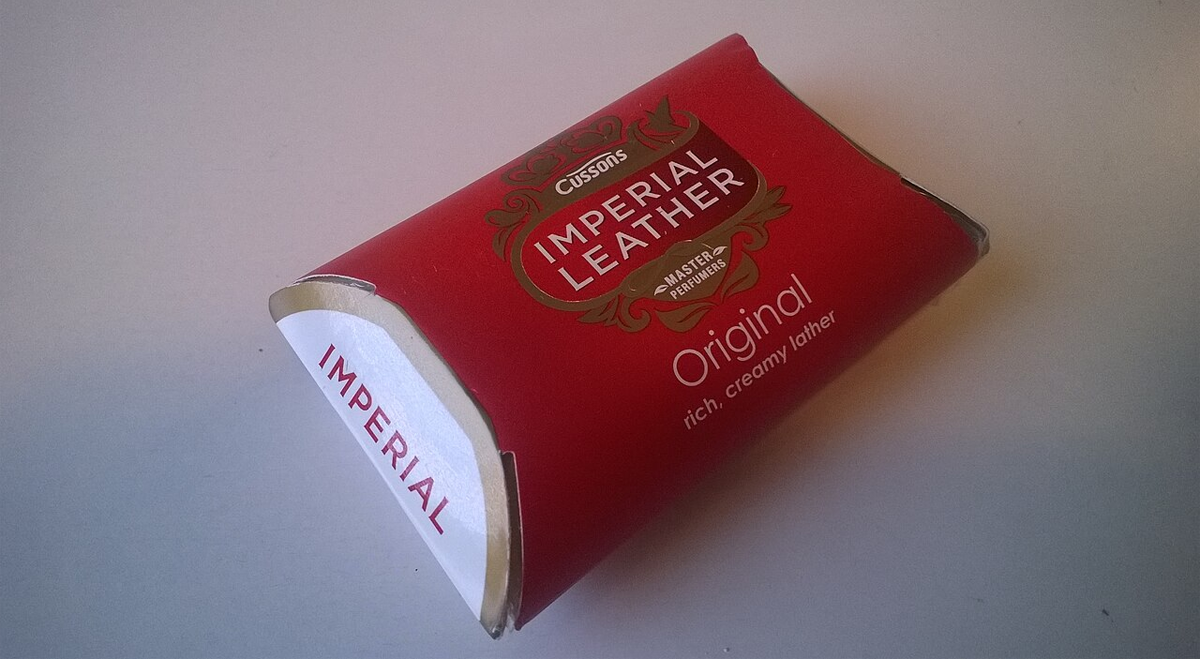
    PZ Cussons is a Manchester-based consumer goods company that develops and markets personal care, home care and baby care products across the UK, Australia and New Zealand, Nigeria and Indonesia. Its portfolio includes well-known brands such as Carex, Cussons Baby, Imperial Leather, Morning Fresh and St.Tropez, serving consumers in both developed and emerging markets.

    The company continues to focus on building strong local brands while embedding sustainability into its long-term strategy. Through targeted investment, portfolio optimisation and disciplined capital allocation, PZ Cussons aims to deliver sustainable growth and long-term value for shareholders.

  • WPP improves margins as Elevate28 transformation progresses despite lower first-half revenue

    WPP improves margins as Elevate28 transformation progresses despite lower first-half revenue

    WPP (LSE:WPP) reported first-half 2026 revenue of £6.37 billion, down 4.4% on a reported basis and 3.2% on a like-for-like basis. Revenue less pass-through costs declined 4.7% like for like, reflecting the impact of legacy client losses and softer demand across sectors including consumer packaged goods and technology. Despite the weaker top-line performance, the group delivered higher operating profit and improved margins, supported by lower impairment charges and ongoing cost-saving initiatives. WPP also maintained its interim dividend, reduced adjusted net debt and said it expects trading to improve during the second half of the year, with stronger like-for-like performance and higher headline margins.

    Management said the first phase of its Elevate28 transformation programme has been successfully implemented, completing the transition to a single integrated operating model. As part of this strategy, WPP has established new business units including WPP Enterprise Solutions, alongside unified WPP Production and WPP Creative divisions, with the aim of increasing collaboration and capturing demand for AI-driven business transformation. The company continues to expand its WPP Open and Open Intelligence platforms while strengthening partnerships with Google, Meta and Amazon Web Services to embed artificial intelligence across its marketing services. Strong new business wins, improved client retention, targeted cost reductions and selective portfolio optimisation remain central to the group’s plan to improve competitiveness and long-term profitability.

    Regional performance remained mixed, with weaker trading across North America, EMEA and Asia-Pacific partly offset by growth in production services and improving demand from automotive, healthcare and government clients. While revenue pressures persist, WPP’s ability to expand margins highlights the progress being made in simplifying the business and repositioning the company as a technology-enabled marketing partner focused on integrated services, data and artificial intelligence.

    The investment outlook remains balanced. Financial performance continues to be affected by lower revenue, previous losses and higher leverage, while management has cautioned that trading conditions are likely to remain challenging in the near term. However, resilient cash generation, a favourable technical share price trend and an attractive dividend yield provide support, although valuation remains difficult to assess because of the company’s negative price-to-earnings ratio.

    About WPP

    WPP is one of the world’s largest advertising and marketing services companies, providing media, creative, production and enterprise solutions to global brands across industries including consumer goods, technology, retail, automotive, healthcare and the public sector. The company is transforming from a traditional holding company into a fully integrated organisation built around four operating divisions supported by its WPP Open artificial intelligence and data platform.

    Through its Elevate28 strategy, WPP is focused on simplifying its structure, accelerating organic growth, improving operational efficiency and embedding AI-powered technologies across its services. By combining creative expertise with advanced data analytics and strategic technology partnerships, the group aims to strengthen client relationships and deliver sustainable long-term growth.

  • Tritax Big Box REIT secures £350 million to expand data centre development pipeline

    Tritax Big Box REIT secures £350 million to expand data centre development pipeline

    Tritax Big Box REIT (LSE:BBOX) has completed a £350 million equity raise through the issue of approximately 213.4 million new ordinary shares. The shares were placed at 164 pence each, representing around 7.9% of the company’s issued share capital before the transaction. Offered to institutional, retail and management investors at a discount to both the prevailing market price and net tangible asset value (NTA), the new shares are expected to be admitted to trading on the London Stock Exchange’s Main Market later in August, increasing the company’s total issued share capital to roughly 2.93 billion shares.

    The capital raised will be invested in an expanded data centre development programme supported by 507MW of secured grid capacity. This includes two proposed developments in Greater London that are targeted for completion during 2030 and 2031. Management believes deploying the new funds into these projects will enhance both EPRA earnings and net tangible asset value per share over time, reflecting the company’s strategic focus on growing its exposure to digital infrastructure and capturing increasing demand for data centre capacity.

    The investment outlook remains broadly positive, underpinned by solid operating performance, although weaker free cash flow conversion during 2025 and higher debt levels remain areas to monitor. Technical indicators continue to point to a favourable share price trend, while valuation appears attractive, supported by a relatively modest price-to-earnings ratio and a dividend yield of around 4.6%. Management has also highlighted the strength of its development pipeline and disciplined capital allocation, although execution risks and the normalisation of near-term income remain important considerations.

    About Tritax Big Box REIT

    Tritax Big Box REIT plc is a UK-listed real estate investment trust specialising in large-scale logistics and industrial properties. The company is increasingly expanding into the data centre sector, targeting modern, power-secured facilities that support the growing demands of digital infrastructure alongside traditional supply chain operations.

    By raising capital through the London Stock Exchange and investing in high-quality development opportunities, Tritax aims to deliver long-term growth in EPRA earnings and net tangible asset value while providing shareholders with a combination of income and capital appreciation.

  • NextEnergy Solar Fund declares first quarterly dividend under new distribution policy

    NextEnergy Solar Fund declares first quarterly dividend under new distribution policy

    NextEnergy Solar Fund (LSE:NESF) has announced a first interim dividend of 1.77p per share for the quarter ended 30 June 2026, in accordance with its revised policy of distributing 75% of operating cash flow to ordinary shareholders. The board noted that dividend payments are expected to reflect the seasonal nature of solar power generation, meaning quarterly distributions are likely to vary throughout the year rather than remain at a fixed level.

    The dividend is scheduled to be paid on 30 September 2026 to shareholders on the register in mid-August. The company also confirmed that the declaration has been treated as a profit estimate under the UK Takeover Code, with directors stating that it has been prepared using accounting principles consistent with previous financial reporting. The announcement reinforces NextEnergy Solar Fund’s focus on delivering sustainable income to investors while maintaining its position as an income-oriented renewable infrastructure investment with inflation-linked cash flows.

    The investment outlook remains mixed. While the company has reported losses and weaker revenue over recent years, these challenges are offset by improving cash generation and a strengthened balance sheet with no reported debt. Technical indicators remain relatively subdued, reflecting weak share price momentum, although the fund’s attractive dividend yield continues to support its investment appeal despite negative earnings.

    About NextEnergy Solar Fund Limited

    NextEnergy Solar Fund Limited is a London-listed investment company specialising in utility-scale solar power and energy storage assets. The fund seeks to generate attractive long-term returns for shareholders through a diversified portfolio of renewable energy investments, with much of its income supported by UK government-backed, inflation-linked subsidy arrangements.

    The company is managed by NextEnergy Capital, part of the wider NextEnergy Group, which also includes WiseEnergy, an operating asset manager, and Starlight, a solar project developer. Together, the group oversees large-scale solar assets across multiple international markets.

  • Serica Energy increases production and returns to net cash as expansion gathers pace

    Serica Energy increases production and returns to net cash as expansion gathers pace

    Serica Energy (LSE:SQZ) delivered a strong first-half performance in 2026, with average production rising to 44,700 barrels of oil equivalent per day (boepd), compared with 24,700 boepd in the same period last year. The increase was driven by improved operational reliability, particularly at the Triton hub, together with the contribution from newly acquired West of Shetland assets. Revenue more than doubled to $677 million, while free cash flow climbed to $184 million. The company also strengthened its balance sheet, moving from net debt of $200 million at the end of 2025 to a net cash position of $26 million. Reflecting this improved financial position, the board maintained its interim dividend at 6p per share.

    To support future growth, Serica secured additional financing through a $300 million five-year Nordic bond and new six-year reserve-based lending facilities worth $750 million. These arrangements provide pro forma liquidity of approximately $784 million, giving the company financial flexibility to fund investment in UK operations, decommissioning obligations and selective acquisition opportunities. Management is preparing a 400-day drilling campaign targeting up to six wells, alongside shorter-cycle projects that could add around 30,000 boepd of production. The group is also integrating its Greater Laggan Area acquisition, progressing the acquisition of Spirit Energy’s assets and its planned move to the Main Market, while the proposed Pharos Energy transaction is intended to support its broader international expansion strategy.

    The investment outlook remains balanced. While the company’s recent financial history includes weaker revenue, a net loss and negative free cash flow during 2025, these factors have been offset by stronger operational momentum, a significant improvement in the balance sheet and management’s reaffirmation of its 2026 guidance. The shares also benefit from positive technical momentum and an attractive dividend yield, although valuation is constrained by a negative price-to-earnings ratio resulting from previous losses.

    About Serica Energy

    Serica Energy plc is a UK-based independent oil and gas exploration and production company with operations focused on the UK North Sea. The company operates key production hubs including Bruce and Triton and has expanded its asset base through acquisitions in the West of Shetland region, one of the UK’s most prospective offshore basins.

    Alongside growing its domestic production portfolio, Serica is pursuing international diversification through strategic acquisitions, including its recommended takeover of Pharos Energy, as it seeks to broaden its geographical footprint and support long-term production growth.