Category: Market News

  • GetBusy grows ARR as SmartVault strengthens position in US tax workflows (GETB)

    GetBusy grows ARR as SmartVault strengthens position in US tax workflows (GETB)

    GETB GetBusy (LSE:GETB) reported group annualised recurring revenue of £23.4 million for the four months ended 30 April 2026, representing an 11% increase year-on-year. The company said stronger adoption of artificial intelligence features across its software platforms helped drive the improved performance. Management added that the results support confidence in continued growth and reaffirmed its guidance for 2026, highlighting ongoing operational progress for investors and stakeholders.

    SmartVault, which is now integrated with all leading US tax preparation software platforms, recorded ARR growth of 19% to $18.5 million alongside a 36% increase in new business activity. The company said this further establishes SmartVault as a key component within US tax workflows, supported by high switching costs and the scale of its document management infrastructure. Meanwhile, Workiro returned to growth following a renewed emphasis on professional services customers and an expanded collaboration with UK tax software provider TaxCalc. Continued migrations from the legacy Virtual Cabinet platform are also contributing to higher average revenue per user and lower churn, supporting GetBusy’s wider move toward AI-enabled cloud workflow products.

    Management expects the upcoming launch of SmartProposals, together with additional SmartVault upgrades, to extend the platform’s role further into customer engagement and pricing functions. Alongside planned integration partnerships for Workiro across the UK and ANZ markets, the company believes these initiatives will strengthen GetBusy’s standing as a core infrastructure provider for tax and document workflow services, with AI increasingly positioned as a major driver of value creation across its platforms.

    The company’s outlook is held down primarily by balance-sheet risk (negative equity) and volatile profitability despite strong gross margins. Improving cash flow provides some support, but technicals remain weak-to-neutral and valuation is constrained by a negative P/E and no dividend data.

    More about GetBusy Plc

    GetBusy plc is a UK-listed provider of specialist SaaS document workflow software serving professional and financial services industries. The business focuses on securing and automating workflows linked to more than 1.3 billion high-value documents. Its strategy is centred on generating near-term cash returns from SmartVault, its expanding US tax workflow platform, while continuing to develop Workiro, a collaboration and content management solution integrated with professional services and cloud ERP ecosystems and used by more than 60,000 paying customers globally.

    The Group positions its AI-enabled software as mission-critical tools embedded in customers’ day-to-day operations, particularly for regulated industries requiring secure, compliant and automated document management. Through integrations with leading tax and compliance software providers in the US, UK and ANZ regions, GetBusy aims to establish itself as the preferred independent workflow engine for tax and professional services firms, supporting recurring revenues through long customer retention and high switching barriers.
  • Panther Metals completes final Winston tailings assays and advances toward resource modelling (PALM)

    Panther Metals completes final Winston tailings assays and advances toward resource modelling (PALM)

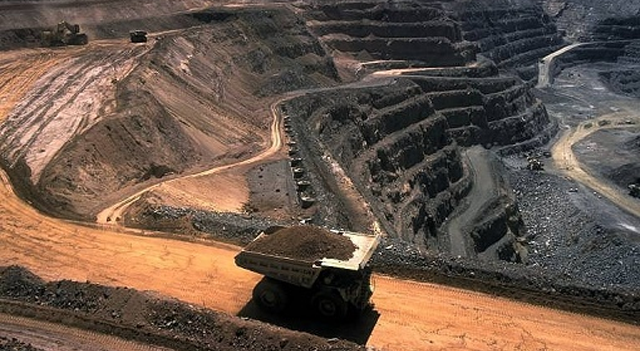
    PALM Panther Metals (LSE:PALM) has released the sixth and concluding set of Vibracore assay results from its Winston Tailings Project in Ontario, marking the completion of the core sampling program that will support a future mineral resource estimate for the historic Winston Lake Mine tailings site. The newest assay data, which include additional samples from 49 collar positions, demonstrated consistent mineral grades and significant tailings depth throughout the storage area, reinforcing — and in some instances surpassing — the preliminary findings reported during 2025 and 2026.

    According to management, the completed Vibracore dataset is now being incorporated into mineral resource modelling, estimation studies and metallurgical recovery analysis. The project will next move into engineering and design work focused on low-cost tailings reprocessing and exploitation, which is intended to support a future mining recovery permit application. With most of the major sampling expenditures already completed and access to established infrastructure including power, transport and water systems operated by First Quantum, Panther Metals believes the project now has a more defined route toward potential development. The company also noted increasing interest from prospective investment partners.

    The company’s outlook is held down primarily by weak financial performance (pre-revenue, recurring losses, and persistent negative free cash flow), partially offset by a strong technical uptrend (price above major moving averages and positive MACD). Valuation remains constrained by negative earnings (negative P/E) and no provided dividend yield.

    More about Panther Metals Plc

    Panther Metals PLC is a mineral exploration business listed on the London Stock Exchange and incorporated in the Isle of Man. The company is focused on Canadian resource projects, with particular attention on recovering valuable minerals from historic mine tailings. Its activities include the Winston Lake Mine tailings facility in Ontario, where it is targeting the recovery of gold, gallium, silver, zinc, copper, indium, cobalt and other metals.

  • Guardian Metal broadens Tempiute project area as tungsten tailings evaluation progresses (GMET)

    Guardian Metal broadens Tempiute project area as tungsten tailings evaluation progresses (GMET)

    GMET Guardian Metal Resources (LSE:MET) has uncovered an extensive area of historic tungsten-rich mine tailings at its Tempiute Tungsten Project in Nevada and is now advancing studies to determine both the resource potential and environmental remediation value of the material. Recent field mapping and sampling work suggest the tailings extend across roughly 550 acres, with surface testing confirming the presence of tungsten alongside other metals.

    To capitalize on the discovery, the company has added 193 new mining claims, increasing the overall Tempiute land package by more than 375%. At the same time, environmental assessment work is continuing. Subject to permitting, Guardian Metal plans to begin an auger drilling campaign in June 2026, while an independent metallurgical review will assess the tonnage, grade and recovery characteristics of the tailings. The work is aimed at supporting Tempiute’s potential as a near-term U.S.-based tungsten supply source with comparatively lower development costs and possible reclamation advantages.

    The score is held down primarily by weak financial performance (minimal revenue, widening losses, and sharply worse free cash flow) and a bearish technical trend (price below key moving averages with negative MACD). A debt-free balance sheet with growing equity provides some support but does not offset the current cash burn and lack of profitability.

    More about Guardian Metal Resources PLC

    Guardian Metal Resources PLC is focused on restarting U.S. tungsten production through its flagship Pilot Mountain and Tempiute projects in Nevada. The company is targeting critical mineral supply chains tied to defense and industrial demand and has benefited from U.S. government backing, including support from the Department of War and its recent NYSE American listing.

  • U.S. Futures Retreat as Oil Spike Revives Market Anxiety: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. Futures Retreat as Oil Spike Revives Market Anxiety: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. stock futures traded lower early Tuesday, signaling a softer start for Wall Street after the major indexes ended Monday’s uneven session with modest gains.

    Investor sentiment weakened as oil prices extended their recent rally, heightening concerns that renewed instability in the Middle East could pressure both economic growth and inflation.

    U.S. crude futures climbed more than 3% on Tuesday following a 2.8% surge in the previous session.

    The continued rise in energy prices comes as negotiations between the United States and Iran remain deadlocked, with both sides struggling to finalize an agreement aimed at ending the conflict and reopening the Strait of Hormuz, one of the world’s most important oil shipping routes.

    President Donald Trump told reporters Monday evening that the ceasefire between Washington and Tehran was on “life support,” describing the truce as “unbelievably weak.”

    Inflation Report Helps Ease Some Concerns

    Futures recovered part of their earlier declines after new U.S. inflation figures came in broadly in line with expectations.

    Data released by the Labor Department showed consumer prices rose at a slower pace in April.

    Monthly inflation eased to 0.6% from 0.9% in March, helping calm fears that rising oil prices could trigger a sharper acceleration in consumer costs.

    Markets appeared relieved that the inflation data did not exceed analyst forecasts.

    Wall Street Closes Slightly Higher Despite Choppy Trading

    Stocks struggled to maintain direction throughout Monday’s session following the strong rally seen last week.

    Major indexes repeatedly swung between gains and losses before ending the day modestly higher.

    The Dow Jones Industrial Average rose 95.31 points, or 0.2%, to finish at 49,704.47. The Nasdaq Composite added 27.05 points, or 0.1%, closing at 26,274.13, while the S&P 500 gained 13.91 points, or 0.2%, to end at 7,412.84.

    Despite the muted performance, both the Nasdaq and S&P 500 posted fresh record closing highs.

    Middle East Developments Continue to Dominate Market Focus

    The cautious tone across markets reflected lingering uncertainty over the near-term outlook following recent gains.

    Although investor sentiment remains generally optimistic, traders continue to closely follow developments surrounding the Middle East conflict.

    Oil prices remained central to market attention after crude futures rose more than 2% on Monday.

    The latest rally accelerated after Trump rejected Iran’s response to a U.S. peace proposal, describing it as “totally unacceptable” in a Truth Social post.

    Iranian state media reported that Tehran’s counterproposal included demands for compensation over war-related damage and recognition of the country’s sovereignty over the Strait of Hormuz.

    Even so, stronger-than-expected corporate earnings have recently helped support U.S. equities despite ongoing geopolitical uncertainty.

    Energy, Gold and Chip Stocks Lead Gains

    Gold mining shares advanced sharply as gold prices moved moderately higher.

    The NYSE Arca Gold Bugs Index climbed 3.7% during Monday’s session.

    Oil-related stocks also gained ground alongside crude prices, with the Philadelphia Oil Service Index advancing 2.6%.

    Semiconductor, networking and oil services companies also posted solid gains.

    Airline and Consumer Stocks Under Pressure

    Airline shares fell sharply as rising oil prices increased concerns over higher fuel expenses.

    The NYSE Arca Airline Index dropped 3.1%.

    Retail, housing and banking shares also moved lower, offsetting some of the strength seen in commodity-linked and technology sectors.

  • European Stocks Decline as Iran Tensions and German Inflation Weigh on Markets: DAX, CAC, FTSE100

    European Stocks Decline as Iran Tensions and German Inflation Weigh on Markets: DAX, CAC, FTSE100

    European equity markets moved lower on Tuesday as fading optimism over a potential peace agreement between the United States and Iran dampened investor sentiment, while fresh inflation data from Germany added to concerns over rising energy costs linked to the conflict.

    U.S. President Donald Trump said the fragile ceasefire between Washington and Tehran was on “massive life support,” casting doubt on the prospects for a durable resolution.

    Meanwhile, final data from Germany’s statistics office Destatis showed that annual consumer price inflation accelerated to 2.9% in April from 2.7% in March. The figure matched preliminary estimates released on April 29 and marked the highest inflation reading since December 2023.

    The increase was largely driven by another rise in energy prices tied to the ongoing Iran conflict.

    Major European Indexes Trade Lower

    Germany’s DAX index declined 1.2% during the session, while France’s CAC 40 fell 0.7%. In London, the FTSE 100 slipped 0.4%.

    Salzgitter and Jenoptik Rally After Strong Updates

    Shares in Salzgitter (TG:SZG) surged 6% after the steelmaker raised its fiscal 2026 earnings outlook following improved first-quarter results.

    Technology company Jenoptik (BIT:1JEN) jumped 10% after reporting a 74% increase in first-quarter order intake.

    Douglas and Munich Re Decline

    Beauty retailer Douglas (TG:DOU) fell 3.7% after posting a wider second-quarter loss linked to impairment charges.

    Reinsurance group Munich Re (TG:MUV2) dropped 4.6% after disclosing private credit investments of up to €2.5 billion ($2.9 billion).

    Bayer Gains While Siemens Energy Slips

    Bayer (TG:BAYN) advanced 6.2% after reporting stronger first-quarter earnings, supported by solid performance in its crop science division.

    Meanwhile, Siemens Energy (TG:SIE) declined 1.6% despite increasing its fiscal 2026 guidance.

    Imperial Brands Rises as Vodafone and Wizz Air Fall

    Imperial Brands (LSE:IMB) gained 1.2% after the tobacco group maintained its full-year outlook following stronger adjusted earnings and solid cash generation during the first half of 2026.

    Vodafone (LSE:VOD) fell 3% after the telecom operator reported customer losses in its core German market during the previous quarter.

    Budget carrier Wizz Air (LSE:WIZZ) dropped nearly 2% after stating that it expects earnings for fiscal 2025/26 to range from break-even to slightly positive.

  • Market Open: Vodafone earnings growth, Lloyds deposit mortgage

    Market Open: Vodafone earnings growth, Lloyds deposit mortgage

    FTSE 100 slips as Vodafone forecasts earnings growth and Lloyds unveils a £5,000 deposit mortgage while Brent crude rises.

    Market Overview

    European markets traded lower at the open, with the FTSE 100 down 0.26 per cent to 10,211.77 and the CAC40 falling 0.69 per cent, while Germany’s DAX edged 0.05 per cent higher. In the US, the Nasdaq lost 0.75 per cent and the S&P 500 declined 0.30 per cent as investors weighed corporate earnings, central bank expectations and renewed trade policy uncertainty. Market sentiment was also shaped by updates from Europe’s chemicals sector and continued focus on US tariff policy.

    Commodity markets remained mixed, with Brent crude rising 2.30 per cent amid supply concerns and geopolitical uncertainty linked to US policy comments. Gold fell 1.25 per cent while copper added 0.35 per cent, reflecting uneven demand expectations across industrial markets. Sterling weakened against the US dollar, euro and yen, while Bitcoin traded lower against the pound.


    Market Numbers

    FTSE 100: Down (-0.26%), 10,211.77
    CAC40: Down (-0.69%), 8,056.380
    DAX: Up (0.05%), 24,350.28
    NASDAQ: Down (-0.75%), 29,114.1
    S&P 500: Down (-0.30%), 7,389.1


    In the Headlines

    Earnings outlook – Vodafone (LSE:VOD)

    Vodafone said it expects further earnings growth in the year ahead as the telecoms group continues restructuring efforts and operational changes under its “new chapter” strategy. The update is significant for investors monitoring cost reductions, market competitiveness and cash generation across the European telecoms sector.

    Deposit mortgage launch – Lloyds Banking Group (LSE:LLOY)

    Lloyds Banking Group is preparing to launch a new mortgage product requiring a £5,000 deposit aimed at helping first-time buyers enter the housing market. The move highlights growing competition among lenders as banks respond to affordability pressures and demand for lower-deposit borrowing options.


    Currencies (vs GBP)

    USD: Down (-0.49%), $1.3539
    EUR: Down (-0.17%), €1.1522
    JPY: Down (-0.30%), ¥213.360
    AUD: Down (-0.08%), $1.874550
    Bitcoin (BTC/GBP): Down (-0.69%), £59,667.7


    Commodities

    Brent Crude: Up (2.30%), 105.275
    Gold: Down (-1.25%), 4,706.575
    Copper: Up (0.35%), 6.525
    Natural Gas: Flat (0.00%), 3.0745

  • Barclays Upgrades LVMH (MC) and Kering (KER) as Luxury Sector Outlook Improves

    Barclays Upgrades LVMH (MC) and Kering (KER) as Luxury Sector Outlook Improves

    Barclays has upgraded its recommendations on LVMH (EU:MC) and Kering (EU:KER), saying both luxury groups are well positioned to outperform a slowing sector through internal restructuring efforts and brand recovery initiatives.

    The bank raised its rating on LVMH to Overweight from Equal Weight and increased its price target to €600 from €575. Kering was upgraded to Equal Weight from Underweight, while its target price was lifted to €300 from €255.

    Shares in both companies advanced in Paris trading, with LVMH gaining 1% and Kering rising 1.3%.

    Barclays also announced that analyst Viktoria Petrova has taken over primary coverage of the two luxury groups.

    Barclays Sees Moderate Luxury Market Growth Ahead

    The bank expects the broader luxury sector to expand by around 3% in 2026 before stabilising near 4% growth levels in the longer term.

    Against that backdrop, Barclays said it is favouring companies capable of outperforming the sector through brand-specific and operational improvements rather than relying solely on industry-wide demand recovery.

    For LVMH, Barclays highlighted recovery potential at Tiffany and Dior, which together represent more than 15% of group revenue.

    The bank expects Tiffany to generate annual revenue growth of roughly 10% through 2029, eventually reaching around €7 billion in sales, supported by store renovations and product assortment improvements.

    Dior, meanwhile, is projected to return to its 2023 sales peak of €8.9 billion by 2029 as the brand’s creative repositioning gains momentum.

    Barclays also noted that after falling 26% since the start of the year — compared with a 5% gain for MSCI Europe — LVMH is currently trading at roughly 20 times forward earnings, representing an estimated 16% discount to its historical valuation average.

    “With near-term potential catalysts pointing to an acceleration in growth, we see current levels as an attractive buying opportunity,” Petrova wrote.

    The analyst added that she expects growth momentum to improve from the second quarter of 2026 as year-on-year comparisons become more favourable.

    Barclays Expects Gucci Restructuring to Support Kering Recovery

    Barclays’ outlook for Kering is centred more heavily on cost control measures and operational restructuring at Gucci.

    The bank forecasts revenue compound annual growth of around 8% between fiscal years 2027 and 2029, implying annual outperformance of roughly four percentage points relative to the wider luxury sector.

    Barclays also expects Kering’s EBIT margin to almost double from fiscal 2025 levels to 21.7% by fiscal 2029, reaching that target a year earlier than management’s own guidance.

    According to the bank, store closures and restructuring efforts are expected to reduce fixed costs related to staffing, leases and administrative expenses.

    Petrova also projected earnings per share compound annual growth of approximately 55% over the same period, while noting that Barclays’ 2030 forecasts still assume sales productivity, revenues and margins below previous peak levels.

    At the same time, the analyst warned that market expectations for Kering in fiscal years 2026 and 2027 remain “too high,” indicating that additional downward revisions may still be necessary before a broader recovery takes hold.

    “We see ’26E as a reset year as the company needs to stabilise performance,” Petrova said.

  • Intertek (ITRK) Shares Surge After EQT Tables Final £9.4 Billion Bid

    Intertek (ITRK) Shares Surge After EQT Tables Final £9.4 Billion Bid

    Shares in Intertek (LSE:ITRK) climbed more than 5% on Tuesday after Swedish private equity firm EQT AB submitted a fourth and final takeover proposal for the British testing and certification group, valuing the company at approximately £9.4 billion ($12.7 billion).

    The London-listed company confirmed it is reviewing the latest approach after previously rejecting three earlier offers from EQT.

    Under the revised proposal, Intertek shareholders would receive 60 pounds per share in cash, alongside a potential fiscal 2025 dividend of 1.1 pounds per share. EQT’s previous proposals had been set at 51.5 pounds, 54 pounds and 58 pounds per share respectively.

    The latest cash offer alone represents a premium of roughly 59% compared with Intertek’s share price before market speculation around a possible takeover first emerged, although the valuation remains below the stock’s highs reached during the pandemic period.

    EQT said the proposal provides “certain and accelerated cash value at a full valuation for Intertek shareholders, superior to the range of outcomes associated with Intertek’s standalone prospects.”

    EQT Faces Deadline Under UK Takeover Rules

    Under UK takeover regulations, EQT has until Thursday to either submit a formal bid or withdraw its interest.

    If Intertek rejects the latest proposal, the private equity group would generally be prevented from making another offer for at least six months, except under limited conditions.

    Analysts at RBC Capital Markets said shareholders may now push the company’s board to engage more actively with EQT.

    “We believe ITRK investors, some of whom have expressed that any offer would need to start with a ’6’, should encourage the board to seriously engage with EQT,” the analysts wrote.

    “We see EQT’s bid as a fair balance between compensating ITRK shareholders for future upside potential, and creating a cushion of safety for EQT as it likely plans to prepare ITRK for the next stage on it strategic journey,” they added.

    Strategic Review Continues Despite Bid Interest

    Intertek has repeatedly rejected EQT’s approaches over recent weeks while continuing with its own strategic review process, which could potentially lead to a breakup of the business into separate units.

    The company has argued that a full takeover could involve considerable execution risks and has also indicated that it has received encouraging interest in its energy and infrastructure operations.

    Meanwhile, two shareholders — PrimeStone Capital and Palliser — have publicly urged Intertek’s board to open discussions with the buyout group.

  • Copper Extends Rally to Multi-Month High as Supply Tightness Remains in Focus

    Copper Extends Rally to Multi-Month High as Supply Tightness Remains in Focus

    Copper prices surged on Tuesday, touching their strongest levels in over three months as concerns over constrained supply and bullish technical signals continued to support the market.

    Three-month copper contracts on the London Metal Exchange climbed 2.7% to $13,943 per metric ton by 1013 GMT, following Monday’s record settlement.

    The advance came despite ongoing geopolitical uncertainty linked to the conflict involving Iran. U.S. President Donald Trump said Tuesday that the ceasefire with Tehran was “on life support,” dampening hopes that a peace deal could be reached quickly.

  • Gold Prices Weaken as Investors Track Iran Developments and Upcoming Trump-Xi Talks

    Gold Prices Weaken as Investors Track Iran Developments and Upcoming Trump-Xi Talks

    Gold prices moved lower in Asian trading on Tuesday as investors closely followed developments surrounding the fragile ceasefire between the United States and Iran, while also awaiting a highly anticipated meeting between Donald Trump and Chinese President Xi Jinping later this week.

    Spot gold declined 0.7% to $4,702.84 per ounce by 02:52 ET (06:52 GMT), while U.S. gold futures slipped 0.4% to $4,710.66 per ounce.

    Other precious metals also traded lower, with spot silver falling 2.4% to $84.03 per ounce and platinum declining 3.2% to $2,067.19 per ounce.

    Trump Says Iran Truce Remains Under Pressure

    Market sentiment remained cautious after Trump criticised Iran’s latest response to a U.S.-supported peace proposal, calling it “a piece of garbage” and warning that the ceasefire remained at risk after weeks of indirect negotiations.

    The U.S. president described the truce as being on “massive life support,” raising concerns that tensions in the Gulf could intensify again.

    Iranian officials responded by saying the country’s military was prepared to respond forcefully to any “act of aggression.”

    Tehran also defended its negotiating position, arguing that demands related to sanctions relief, restoring oil exports and recognition of Iran’s authority over the Strait of Hormuz were justified.

    Oil prices stayed elevated on Tuesday amid concerns that additional disruption around the Strait of Hormuz could impact global crude supply flows.

    Higher energy prices have limited support for gold, as investors worry that persistent inflationary pressure could prompt the Federal Reserve to keep interest rates elevated for an extended period. Higher rates generally reduce the attractiveness of non-yielding assets such as bullion.

    Focus Turns to U.S. Inflation Figures and Trump-Xi Discussions

    Investors are also watching closely for Trump’s expected meeting with Xi Jinping in Beijing later this week.

    The discussions are expected to cover a range of geopolitical and economic topics, including Iran, Taiwan, trade disputes, artificial intelligence and energy security.

    Attention is also shifting toward upcoming U.S. inflation data, especially the Consumer Price Index report due later Tuesday, which could offer additional clues about the Federal Reserve’s future monetary policy direction.

    The U.S. Dollar Index gained 0.2% during Asian trading hours, making gold more expensive for investors using foreign currencies.

    In base metals trading, benchmark copper futures on the London Metal Exchange slipped 0.3% to $13,848.13 per ton, while U.S. copper futures declined 0.6% to $6.45 per pound.