Hydrogen Utopia International PLC (LSE:HUI) has appointed London-based io consulting to provide engineering and strategic advisory services as the company looks to accelerate its UK Sustainable Aviation Fuel and waste plastic-to-hydrogen projects.
Under a newly signed Master Services Agreement, io consulting will support Hydrogen Utopia across project development, applying its capital value process from initial feasibility work through to project definition. The aim is to establish the technical and commercial foundations required to move projects towards financing and eventual development.
Io consulting is a joint venture between McDermott and Baker Hughes, bringing engineering and energy-sector expertise to the partnership. Its work with HUI is expected to focus particularly on the company’s UK Sustainable Aviation Fuel opportunity, including potential funding pathways and engagement with relevant stakeholders.
The agreement comes as the UK develops its domestic SAF industry through measures including the government’s Sustainable Aviation Fuel mandate and the Low Carbon Fuels Fund. Hydrogen Utopia intends to use this policy environment to explore public and private financing opportunities for its low-carbon fuel projects.
The collaboration follows HUI’s recent licensing of InEnTec’s Plasma Enhanced Melter, or PEM, gasification technology for the production of SAF in the UK. By combining access to the technology with io consulting’s project development expertise, the company is seeking to strengthen its ability to advance its pipeline and establish a position in the emerging British SAF market.
More about Hydrogen Utopia International PLC
Hydrogen Utopia International PLC is a UK-listed clean energy company developing technology-led projects designed to convert non-recyclable mixed waste plastics into hydrogen, Sustainable Aviation Fuel and other advanced low-carbon fuels.
Its proposed facilities process waste plastic into syngas, which can subsequently be converted into fuels or used to generate power and heat. The business model also offers the potential for revenue from waste-processing gate fees alongside the sale of energy and fuel products.
HUI focuses on jurisdictions where its projects could benefit from supportive decarbonisation policies and access to government grants, loans or private investment. Through its waste-to-fuels strategy, the company is seeking to participate in the circular economy while addressing demand for lower-carbon energy solutions in sectors including aviation.
IG Design Group (LSE:IGR) has appointed Ari Bensoussan as its new Chief Financial Officer as part of a planned change to the company’s senior leadership team.
Bensoussan will take up the CFO position and join the board as an executive director on 1 September 2026. He replaces Rohan Cummings, who will step down from the board on 31 August but remain with the business until the end of the year to help ensure a smooth handover.
The incoming finance chief brings almost three decades of experience spanning finance, strategy and mergers and acquisitions, with much of his career spent at international consumer businesses. His previous roles include senior positions at Thai Union and Nestlé, giving him extensive exposure to global operations and commercial strategy.
IG Design Group’s board highlighted Cummings’ contribution to the recent restructuring and simplification of the business. During his tenure, the group completed the disposal of DG Americas and renegotiated its banking arrangements, helping strengthen its balance sheet and create a more focused operating structure.
Chair Stewart Gilliland said Bensoussan’s international financial and commercial expertise would be valuable as the company seeks to expand its customer reach and strengthen its commercial capabilities while retaining financial discipline. The appointment indicates that improving operational resilience and pursuing sustainable growth will remain central priorities following the group’s recent restructuring.
IG Design Group’s investment outlook nevertheless continues to face pressure from uneven financial performance. Revenue declined sharply in 2026, profitability has been inconsistent and free cash flow was negative across 2025 and 2026, although the strengthened balance sheet provides some financial resilience.
The technical picture is more positive, with the shares trading comfortably above their major moving averages and indicating strong underlying price momentum. Valuation remains a less supportive factor, however, given the negative price-to-earnings ratio and the absence of dividend yield data.
More about IG Design Group
IG Design Group plc is a global designer, innovator and manufacturer of products including gift packaging, greeting cards, stationery, creative play ranges and other celebration-related goods. Its vertically integrated operations include manufacturing facilities in Wales, the Netherlands and Poland, with the company supplying more than 550 million units annually across approximately 70 countries.
The group has operations spanning the UK, Europe and Australia and supplies major retailers and supermarkets including Tesco, Costco and Aldi, alongside discount chains, e-commerce platforms and independent retailers. Its heritage Tom Smith brand holds a Royal Warrant for Christmas crackers and wrapping paper, while IG Design Group is listed on the AIM market of the London Stock Exchange.
Focus keyphrase: IG Design Group CFO appointment
Meta description: IG Design Group appoints Ari Bensoussan as CFO from September as Rohan Cummings prepares to leave following the group’s restructuring.
Rome Resources (LSE:RMR) has highlighted further exploration potential at its Kalayi tin deposit in the Democratic Republic of Congo after independent modelling identified two previously unrecognised mineralised zones.
Modelling carried out by MSA Group outlined the new MINZ8 and MINZ9 zones, as well as a substantial undrilled extension of a high-grade tin trend towards the southeast. While additional drilling will be needed to establish the continuity of these areas, the targets could provide scope for future resource expansion.
The newly identified zones will not form part of the upcoming Kalayi Mineral Resource Estimate, which Rome Resources is currently finalising with MSA. Instead, they have been earmarked as priority areas for subsequent drilling and potential additions to the resource base.
Exploration is also continuing across the wider Bisie North Project, where the company is progressing an airborne geophysical survey. Data from the programme is being interpreted by Southern Geoscience as Rome Resources looks to identify further prospective targets across the project area.
Outside the DRC, the company is advancing its tin-tungsten-indium project in New Brunswick, Canada. Initial grab sampling has returned encouraging results, prompting follow-up trenching as Rome evaluates the project’s mineralisation potential. The Canadian work forms part of the group’s broader strategy of developing a portfolio of critical mineral assets across multiple jurisdictions.
Financial considerations remain a key risk for the exploration-stage company. Rome Resources currently has no established revenue stream and continues to record net losses and cash outflows, leaving it exposed to future funding requirements and project execution risks. This is partly offset by low debt levels and its existing equity base.
From a technical perspective, the shares also face some near-term pressure, with weak price momentum reflected in a negative MACD reading and an RSI below 50. Conventional valuation measures offer limited support because ongoing losses result in a negative price-to-earnings ratio, while the absence of a dividend means there is currently no income component to the investment case.
More about Rome Resources plc
Rome Resources plc is an AIM-listed mineral exploration company focused primarily on critical metals. Its principal interests include the Kalayi tin deposit and the broader Bisie North Project in the Democratic Republic of Congo, alongside an optioned tin-tungsten-indium project in New Brunswick, Canada. The company is targeting the discovery and development of metals considered increasingly important to global industrial and strategic supply chains.
Focus keyphrase: Rome Resources Kalayi tin deposit
Meta description: Rome Resources identifies two new mineralised zones and an undrilled high-grade tin trend at Kalayi as it prepares an updated resource estimate.
Matt Schwab is a proven mine-finder who now believes that he has another major discovery in his sights.
This accomplished geologist has considerable credibility to back up his confidence: he led the exploration team that made the multi-billion-dollar Arrow uranium deposit in 2014 in the remote southwestern portion of Saskatchewan’s famed Athabasca Basin. This allowed a low-capitalized penny-stock uranium explorer – NexGen Energy – to become a multi-billion-dollar company with a share price that has since traded nearly as high as CDN $20.
Why Investors are Betting on a Proven Winner
Fast forward a dozen years and Schwab believes he is about to do it all over again with another junior exploration company – once again in the remote western Athabasca Basin. He is excited about what is proving to be a technically successful inaugural drill program (which is still ongoing) – one that his Vancouver-based company began a few weeks ago in virgin territory that has never seen drilling before.
This article is disseminated in partnership with Stallion Uranium’s media advisor, Capital Markets Media Inc. It is intended to inform investors and should not be taken as a recommendation or financial advice.
He is especially equally excited about the Big Picture potential of the Coyote target within the Moonlite project area – now that drill results are starting to validate his exploration team’s extensive, multi-faceted geological detective work It is worth noting here that his team has impressive collective experience with drilling uranium discovery holes
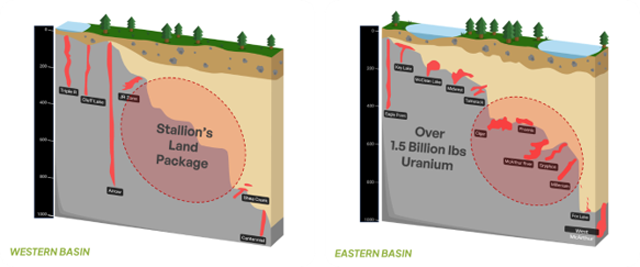
Coyote is one of his company’s main prospects among an expansive land package that covers 1,700 square kilometres, covering much of the most under-explored areas in the Western frontier of the Athabasca Basin (see image).
“Frankly, it’s shaping up to be what is undeniably one of the best greenfields uranium projects on the planet,” Schwab says.
This is a bold statement. But Schwab has amassed plenty of experience over the years while being involved in several major discoveries – not just Arrow. So, he knows a really good thing when he sees it thanks to his finely-honed geological instincts and his talent for picking drill targets that get the desired results.
In fact, his past Arrow deposit discovery made him realize that he had the necessary skill set and technological knowhow to do it all over again one day if he got his hands on the right properties – which is now the case.
How Drilling is “Delivering the Goods”
Now Schwab feels he is on the brink of a new career high as his small publicly-traded exploration company zeroes-in on a new discovery – one that he feels is well within his reach.
The CEO of Stallion Uranium (USOTC: STLNF) (TSX.V:STUD) says his company’s inaugural drill program shows that his proven geological team is fast zeroing-in on a “company-maker” discovery. It is worth repeating that his team includes fellow geologists who have a comparable track record for being involved in making world-class uranium discoveries among the world’s richest uranium fields – where grades run as high as 20% U₃O₈.
Historically, it has typically taken successful companies at least a couple of dozen drill holes to find anomalously elevated amounts of radioactivity – the key to zeroing-in on high-grade deposits in Saskatchewan’s Athabasca Basin.
Schwab says it took NexGen Energy 14 drill holes before finding elevated radioactivity in the ideal type of rock formation. And then the main discovery hole did not come until the 30th attempt, where the most elevated radioactivity was encountered. This all took place over the span of several sequential drill programs spread over nearly two years.
This time around, Schwab is even more excited than he was with the Arrow discovery. This is because his company’s inaugural drill program is achieving comparable drill results at its Coyota prospect – but at a much faster pace and over a much larger target area.
“In terms of drilling success to date, we’re also well ahead of the game. We’ve found definable mineralization in five out of our six drill holes. To make this happen, we have hit all four of the criteria that we looked for at the Coyote target area,” he says.
“We looked for the right lithography. We looked for conductors with a break. We looked for fault zones, and we looked for alteration. We hit all four of those in all six drill holes. And in five holes, we actually hit elevated radioactivity. In particular, drill hole ML26-005 intersected the highest anomalous radioactivity reading, registering above 1,400 cps.
I think all of these findings are significant. And it shows that we are in the right spot… We even have the same kind of gravity geophysical signature outlining the alteration as we did with Arrow. Only with Coyote, it’s five times bigger.
All told, we’ve delivered on every promise we’ve made so far. Our drilling as so far is delivering the goods. I call this a success.”
Schwab emphasises how the exploration methods that Stallion is using are the same ones that proved successful in revealing the Arrow deposit. They involve using a variety of different techniques to produce anomalous targets. When these targets “stack” on top of one another, they are shown to corroborative one another. In other words, this is where all the geological clues point to the same spot. This is how the top-priority drill targets are selected.
“We even have similar lithology, similarly strong conductors with large breaks, and the same kind of rock structure, and the same kind of alteration… Remember that Arrow is the second highest grade uranium deposit in the world,” Schwab says.
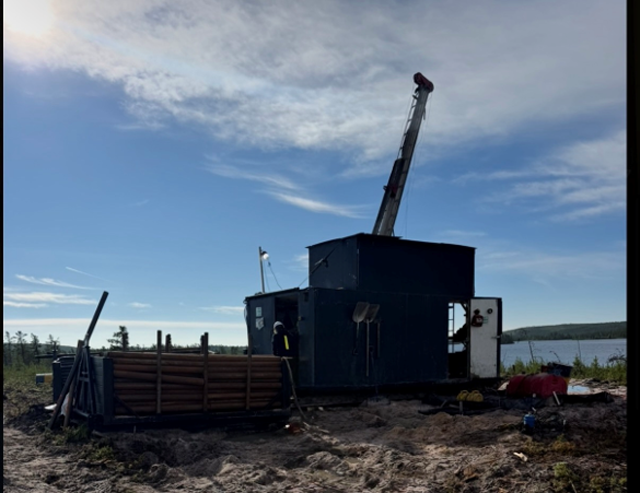
Drill rig at Stallion Uranium’s Coyote target, northern Saskatchewan
The Next Value Drivers
With 4,626 metres completed of the planned 5,500-metre Phase 1 drill program, Stallion intends to drill 2-3 more holes into the Coyote prospect, as well as a single reconnaissance drill hole to also test a high-priority target at the nearby, shallow Fish Hook project area.
Investors should be encouraged by the fact that this involves an expansion fo the current fully-funded drill program to approximately 6,750 metres in total. All of this is expected to get underway in September after a short summer break for the drill crew.
The prospect of outlining more elevated radiation counts at Coyote, as well as a shot at finding a separate deposit at Fish Hook, offer Stallion a couple of powerful drivers for the share price this autumn.
Additionally, a Phase 2 drill program is expected to get underway as early as January, which may yet prove to be a significant discovery-driven catalyst to the upside.
The Big Picture for Investors
Arrow includes 497,000 tonnes of ore at an exceptional 15.90% U₃O₈. This compares to a global average of 0.10% for most uranium deposits. A discovery in Saskatchewan can therefore be analogous to finding a 10-million-ounce, high-grade gold deposit – or even bigger. Remember that we are talking about uranium grades that are more than 100 greater than the global average.
This explains why the stakes are so high in Saskatchewan. And it helps explain why Stallion’s initial drill results suggest it may soon have a tiger by the tail. Continued drilling is sure to add to the excitement.
On a technical note, Stallion has 146 million shares outstanding (235 million fully diluted), which makes for robust daily trading volumes. That said, the stock is more tightly held that it seems because management and insiders own nearly 45% of all the shares outstanding.
Going forward, the prospect of continued success among the remaining several holes of the inaugural drill program should help considerably in the quest to zero-in on a major discovery.
Plus, a Phase 2 drill program in January is expected to capitalize on the technical success of the first round of drilling. This should add further upside impetus to Stallion’s currently undervalued share price. However, if the company’s exploratory drilling continues to encounter success, Stallion’s share price will not stay cheap for much longer. If drilling continues to go well, this could be the next NexGen Energy.
Sponsored Article: InvestorsHub.com Inc. dba The Market Link has been compensated CASH: $1,100 by Stallion Uranium (USOTC:STLNF) for the publication and distribution of this content. This is not independent editorial content. For full compensation disclosure visit investorshub.advfn.com/boards/disclaimer.aspx
U.S. stock futures moved higher on Wednesday, putting Wall Street on course to recover part of its recent decline as investors welcomed a reversal in crude oil prices and a sharp retreat in Treasury yields.
Crude provided some relief after three consecutive sessions of gains. U.S. oil futures turned negative after earlier rising as much as 1.3% to their highest level in almost three weeks.
Treasury Buyback Plans Ease Pressure on Bonds
The improvement in equity futures was accompanied by falling Treasury yields after the U.S. Treasury Department announced a significant expansion of its longer-dated debt buyback programme.
From September 9, liquidity-support buybacks involving longer-term nominal coupon securities will increase by at least twofold.
Lower yields can ease pressure on equity valuations, although investors may remain cautious ahead of the Federal Reserve’s latest meeting minutes, which could provide further insight into policymakers’ thinking on inflation and interest rates.
Tech Sell-Off Weighs on Major Indices
Wednesday’s stronger futures follow a difficult Tuesday session in which all three major U.S. benchmarks finished lower, extending Wall Street’s recent losing streak.
The Nasdaq suffered the largest decline, dropping 355.20 points, or 1.3%, to 26,289.71 as technology shares came under heavy selling pressure.
The S&P 500 lost 53.30 points, or 0.7%, to finish at 7,691.76, while the Dow declined 116.38 points, or 0.2%, to 53,343.40.
The rise in longer-term borrowing costs had become an increasingly important concern for equities, with the 30-year Treasury yield briefly reaching its highest level in nearly 20 years before retreating.
Middle East Conflict Keeps Inflation Risks Elevated
Bond markets have remained sensitive to inflation risks associated with the continuing conflict in the Middle East, particularly as higher energy prices threaten to add to price pressures.
Oil had extended its recent rally after President Donald Trump said there were no current or scheduled talks between Washington and Tehran.
Trump also said on Truth Social that the Strait of Hormuz is “open and operating” and “all water mines have been removed or detonated,” although reports suggested shipping activity through the crucial energy corridor remained constrained.
Daniela Hathorn, Senior Market Analyst at Capital.com, said Treasury yields had risen “despite softer recent economic data reducing expectations for an imminent Fed hike.”
“Instead, the long end is responding to persistent inflation risks, heavy government borrowing and growing competition for capital—including debt issuance associated with the AI investment boom,” Hathorn said.
She added, “That creates an uncomfortable environment for equities because financial conditions can tighten even without the Fed raising rates.”
Industrial Production Falls Short of Forecasts
The latest U.S. economic figures provided another reason for investors to question how aggressively the Federal Reserve may need to approach interest rates.
Industrial production increased 0.2% in July, according to the Fed, falling slightly short of economists’ forecast for 0.3% growth.
June’s increase was revised higher to 0.3% from the previously reported 0.1%.
Chip Stocks Lead Market Decline
Semiconductors were at the centre of Tuesday’s technology sell-off, with the Philadelphia Semiconductor Index plunging 5%.
Computer hardware and networking stocks also suffered substantial declines, adding to pressure on the technology-heavy Nasdaq.
Gold-related shares weakened as bullion prices declined, sending the NYSE Arca Gold Bugs Index down 2.9%. Airlines, housing and steel stocks were also among the weaker areas of the market.
Pharmaceutical, healthcare and energy shares provided some resistance to the broader decline, posting notable gains.
With oil and Treasury yields now retreating, Wall Street has an opportunity to regain some ground, although the Federal Reserve minutes remain a key potential catalyst for the next move in markets.
European equities traded close to unchanged on Wednesday as a retreat in global bond yields provided some relief, while investors turned their attention to the Federal Reserve’s July policy meeting minutes due later in the session.
Sovereign debt markets stabilised after recent volatility. German and French government bond yields steadied, while the 30-year U.S. Treasury yield eased to around 5.27% after reaching 5.3371% on Tuesday, its highest level in almost two decades.
UK Inflation Rises to 2.9%
Sterling was broadly stable after the latest inflation figures showed UK consumer prices accelerating in line with expectations during July, largely because of higher household energy costs.
The consumer price index increased 2.9% year-on-year, compared with a 2.6% rise in June.
European benchmarks were mixed. France’s CAC 40 Index gained 0.3%, while the UK’s FTSE 100 Index and Germany’s DAX Index both slipped 0.1%.
Investors are now waiting for the Federal Reserve minutes for further indications of how policymakers assessed inflation, economic conditions and the outlook for interest rates at their July meeting.
Straumann and Carlsberg Shares Come Under Pressure
Corporate earnings generated some of the session’s largest individual share-price movements.
Straumann (TG:QS51) fell sharply after the Swiss dental implant specialist reported first-half net profit below analyst expectations.
Carlsberg (TG:CBGB) also suffered a significant decline after the Danish brewer’s operating performance for the first half of 2026 missed forecasts.
Smith & Nephew (LSE:SN.) moved lower after the British medical technology group announced that Chief Financial Officer John Rogers had resigned from the board with immediate effect. Rogers is leaving the company to take up a new position in the United States.
Geberit Rallies Following Strong Quarterly Results
Geberit (TG:GBRA) moved in the opposite direction, with shares surging after the sanitary products manufacturer delivered second-quarter results ahead of market expectations.
With European indices showing limited overall movement, attention remains centred on interest-rate expectations and the upcoming Federal Reserve minutes, which could provide the next major signal for global bond and equity markets.
Gold prices edged higher on Wednesday as a weaker U.S. dollar and declining Treasury yields provided some relief for the precious metal ahead of the Federal Reserve’s July meeting minutes.
At 05:42 ET (09:42 GMT), spot gold climbed 0.6% to $4,360.82 an ounce, while gold futures slipped 0.1% to $4,414.30 an ounce.
Bullion has struggled to sustain its recent recovery as elevated bond yields and rising energy prices continue to limit upside momentum. Gold recently regained the psychologically important $4,000-an-ounce level, supported by renewed investor interest and increased central-bank purchases, particularly from China.
David Morrison, Senior Market Analyst at Trade Nation, said: “$4,400 is working like a magnet for the price of gold. Given the ongoing consolidation around this level, the question is if this proves to be ceiling for further gains which raises the likelihood of a retest of $4,000.”
Bond Market Moves Remain Crucial for Bullion
Treasury yields continue to play a significant role in gold’s direction. The yield on the 30-year U.S. Treasury briefly reached its highest level in almost two decades on Tuesday, while the 10-year yield remained close to its strongest levels since early 2025.
High yields tend to reduce the appeal of gold because government bonds provide investors with interest income, while bullion offers no yield. As returns available from fixed-income assets increase, the opportunity cost associated with holding gold also rises.
The modest retreat in Treasury yields on Wednesday therefore helped ease some of that pressure, although rates remain sufficiently elevated to present a challenge for further gains in the precious metal.
Oil Rally Keeps Inflation Risks on the Radar
Strength in crude oil is adding another layer of uncertainty to the outlook for gold as geopolitical tensions in the Middle East remain unresolved.
Higher energy costs can contribute to inflation and potentially discourage the Federal Reserve from lowering borrowing costs. They could also strengthen the case for keeping interest rates elevated for an extended period.
The Strait of Hormuz remains central to the energy-market outlook. Roughly one-fifth of global oil and liquefied natural gas flows passed through the waterway before the Iran war began in late February, leaving energy markets vulnerable to any prolonged disruption.
U.S. President Donald Trump said on Tuesday that there were no negotiations underway with Iran. Meanwhile, the ceasefire framework agreed between Washington and Tehran in June has expired without an extension, adding further uncertainty over the future of the strategically important waterway.
Markets Await Fed Minutes and Warsh at Jackson Hole
Investors are now preparing for the release of minutes from the Federal Reserve’s July meeting later on Wednesday, hoping for additional insight into policymakers’ assessment of inflation and the likely direction of interest rates.
The next major monetary-policy focus will be Fed Chair Kevin Warsh’s appearance at the Jackson Hole symposium next week, where traders will be watching for any signals about the central bank’s policy intentions.
Currency markets offered gold some additional support on Wednesday. The U.S. dollar index fell 0.2% to 99.313 against a basket of major currencies.
Because gold is priced in dollars, a weaker greenback generally reduces its cost for investors holding other currencies, potentially encouraging demand from international buyers.
Oil prices moved higher for a fourth straight session on Wednesday, with the continuing confrontation between the United States and Iran over the Strait of Hormuz fuelling expectations that global crude supplies could remain under pressure.
Brent crude futures advanced 0.3% to $91.32 per barrel by 04:43 ET (08:43 GMT), while U.S. West Texas Intermediate futures gained 0.4% to $85.28 per barrel. Both benchmarks have risen strongly this week and remain close to three-week highs.
The latest gains come as traders closely monitor shipping activity through the Strait of Hormuz, where uncertainty surrounding the Iran conflict has reduced tanker movements through one of the world’s most strategically important energy corridors.
Shipping Activity Through Hormuz Slows
Data cited by Reuters showed that only six commodity vessels passed through the Strait of Hormuz on Tuesday, according to Kpler. That compared with nine vessels on Monday and a 10-day daily average of 11.
Analysts at ING said: “Reports of reduced vessel traffic through the Strait of Hormuz have also raised concerns over potential oil supply disruptions.”
Any prolonged decline in shipping activity could have significant implications for global energy markets, particularly if exporters encounter increasing difficulty moving crude through the waterway.
Al Jazeera reported that U.S. Secretary of State Marco Rubio discussed Gulf security with United Arab Emirates National Security Adviser Sheikh Tahnoon bin Zayed Al Nahyan, with both sides stressing the importance of preserving freedom of navigation through Hormuz.
U.S. and Iran Show Little Sign of Renewing Talks
Diplomatic tensions remain elevated after U.S. President Donald Trump said on Tuesday that negotiations with Iran were neither underway nor scheduled. Trump nevertheless maintained that the Strait of Hormuz was open.
Tehran has also denied that talks with Washington are taking place but disputes the U.S. position on the waterway. Iran says the strait will remain closed until the United States complies with conditions contained in an interim agreement signed in June that has since expired.
The temporary framework lapsed this week, and neither government has indicated that it is prepared to renew the arrangement.
The continued diplomatic deadlock is keeping geopolitical risk firmly embedded in crude prices, with markets increasingly focused on whether reduced shipping activity could translate into tighter physical supplies.
API Data Points to Decline in U.S. Crude Stocks
Oil received another boost from American Petroleum Institute figures indicating that U.S. crude inventories declined modestly last week.
“The oil market also drew support from a slightly bullish API inventory report,” ING analysts said.
Attention now turns to official U.S. inventory figures due later on Wednesday. API data frequently provide an early indication of the direction of the government’s weekly stockpile report.
The apparent decline in commercial inventories comes as broader U.S. supply buffers are also attracting attention. Recent data showed the Strategic Petroleum Reserve falling to its lowest level in more than 40 years amid the Iran conflict.
With diplomatic negotiations stalled, tanker traffic through Hormuz reduced and U.S. inventories showing signs of tightening, oil prices remain highly exposed to further developments in the Persian Gulf.
U.S. stock futures were subdued on Wednesday as markets recovered from the previous session’s semiconductor-led decline and investors prepared for the release of minutes from the Federal Reserve’s July policy meeting.
At 03:11 ET (07:11 GMT), Dow futures advanced 42 points, or 0.1%, while S&P 500 futures were little changed. Nasdaq 100 futures declined 40 points, or 0.1%.
Wall Street closed lower on Tuesday as weakness in semiconductor stocks combined with rising government bond yields to weigh on sentiment. Vital Knowledge analysts linked the chip-sector retreat to profit-taking and concerns about a “tidal wave” of debt issuance associated with the artificial intelligence investment cycle.
Heavy spending on AI infrastructure remains under scrutiny, particularly the enormous capital required to develop advanced data centres. Questions over whether current investment levels can generate sufficient returns have become an increasingly important issue for technology investors.
Deutsche Bank analysts said concerns surrounding fiscal deficits, higher oil prices and the continuing Iran conflict also contributed to the rise in global bond yields. Treasury yields subsequently retreated after weaker U.S. housing and industrial production figures reduced expectations for rapid monetary tightening.
July Fed Minutes Could Clarify Policy Debate
Recent softer employment data and relatively contained inflation figures have reduced market expectations for a Federal Reserve rate increase in the coming months.
Investors will therefore closely examine the minutes from the Fed’s July meeting, when policymakers voted to leave interest rates unchanged.
Fed Chair Kevin Warsh provided little indication of what could come next, saying the central bank will “not waver” in its commitment to returning inflation to the 2% target.
The minutes could provide greater detail about divisions within the Federal Open Market Committee. Warsh characterised the meeting as a “good family fight,” with three policymakers opposing the decision to keep rates unchanged and instead favouring a 25-basis-point increase.
Markets will be looking for evidence of how officials are balancing inflation risks against signs of cooling in parts of the U.S. economy.
Target, Lowe’s and Analog Devices Prepare to Report
Corporate earnings are another major focus, particularly results from retailers that could provide fresh information about consumer spending.
Target (NYSE:TGT) is due to report before the opening bell. The retailer raised its annual sales growth forecast in May for the first time in two years despite acknowledging continued macroeconomic uncertainty.
Chief Executive Michael Fiddelke previously welcomed the company’s 5.6% first-quarter sales increase but cautioned that he would not “confuse this progress with potential.”
Lowe’s (NYSE:LOW) will also release quarterly numbers after rival Home Depot (NYSE:HD) delivered better-than-expected second-quarter sales and profit. Demand for repair and maintenance products helped Home Depot offset weaker spending on major renovation projects.
Semiconductor manufacturer Analog Devices (NASDAQ:ADI) is also scheduled to report. Its previous third-quarter revenue outlook exceeded expectations as growing AI infrastructure investment supported demand for semiconductor and sensor products.
U.S. Delays 50% Canadian Tariffs
Trade tensions eased slightly after President Donald Trump announced a three-day suspension of planned 50% tariffs on selected Canadian imports.
The postponement was announced only hours before the tariffs were scheduled to begin, giving the U.S. and Canada additional time to complete negotiations.
Trump said the two countries have a “deal,” pending “the finalization of documents.”
The proposed tariffs would affect approximately $20 billion of Canadian goods, including furniture, wine, fishing rods and hockey sticks.
The Office of the U.S. Trade Representative said the emerging agreement would provide greater Canadian market access for U.S. products and include “alignment” on digital trade.
Canadian Prime Minister Mark Carney said negotiations had progressed but warned that “important work” remained. He also reiterated his ambition to make Canada’s economy “more independent” and “competitive”.
OpenAI and Anthropic Results Highlight Intensifying AI Competition
Artificial intelligence companies are also in focus following a Wall Street Journal report on the financial performance of OpenAI (NASDAQ:OAI) and Anthropic (NASDAQ:ANTP).
OpenAI reportedly generated second-quarter revenue of $6.7 billion, an increase of 18% from $5.7 billion during the first quarter, although its losses widened.
Anthropic reportedly delivered significantly faster growth, more than doubling quarterly revenue to $11.6 billion while recording a small operating profit.
The figures could point to shifting competitive momentum within the AI industry. Slower growth for ChatGPT and increased developer adoption of Anthropic’s Claude Code are adding pressure on OpenAI to strengthen its growth trajectory as competition across generative AI intensifies.
Consumer prices across the Eurozone increased by 2.9% in the 12 months to July, accelerating slightly from the 2.8% annual rate recorded in June, according to Eurostat data released on Wednesday that confirmed the preliminary estimate.
On a monthly basis, headline consumer prices rose 0.2% in July.
An EU-harmonised underlying inflation measure that excludes volatile components such as food and fuel stood at 2.2% year-on-year. Prices on this measure were unchanged from the previous month.
Core Inflation Accelerates on an Annual Basis
The closely watched “core” CPI measure increased 2.5% from a year earlier, compared with 2.4% in June.
Month-on-month, however, core prices were unchanged, slowing from the 0.2% increase recorded in the previous month. The figures therefore point to some persistence in annual underlying inflation even as shorter-term price momentum remained subdued.
ECB Faces Inflation and Energy Uncertainty
The latest inflation figures are likely to form an important part of the European Central Bank’s assessment when policymakers meet again in September.
At its July meeting, the ECB kept interest rates unchanged but warned that “uncertainty remains high” surrounding the economic consequences of the Iran war. Policymakers also cautioned that the full impact of the associated energy shock “has yet to play out.”
The possibility of further increases in energy costs adds another layer of uncertainty to the inflation outlook, particularly as the ECB evaluates whether price pressures are becoming sufficiently persistent to justify additional monetary tightening.
Markets Increase Bets on Further ECB Rate Hikes
Investors have increasingly begun pricing in further ECB interest-rate increases over the coming months, with expectations also supported by evidence that the Eurozone economy remains relatively resilient.
Economic output expanded by 0.4% during the second quarter, accelerating from the growth recorded between January and March.
The combination of firmer annual inflation, resilient economic activity and uncertainty surrounding energy prices could therefore keep pressure on the ECB as officials weigh their next policy decision in September.