Category: Market News

  • Barclays Delivers Strong H1 2025 Interim Results with Broad-Based Performance

    Barclays Delivers Strong H1 2025 Interim Results with Broad-Based Performance

    Barclays PLC (LSE:BARC) reported strong interim results for the first half of 2025, demonstrating solid financial performance across its core business segments. The bank highlighted effective risk management and a resilient balance sheet, with the use of non-IFRS metrics providing clearer insights into operational trends. Barclays continues to actively engage with investors globally, reinforcing transparency around its strategic priorities and market positioning. The group also maintained a prominent role in the debt capital markets.

    Strong revenue growth, a stable financial foundation, and positive technical indicators suggest continued investor confidence. Despite macroeconomic uncertainties discussed in the earnings call, Barclays’ share buy-back program and upgraded guidance have strengthened its near-term outlook.

    About Barclays

    Barclays PLC is a globally diversified financial services group providing retail and business banking, credit cards, investment banking, and wealth management solutions. The firm operates across key regions including the UK, US, and Europe, offering tailored financial products to individuals, corporates, and institutional clients.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Greggs Sees Sales Growth in H1 2025 Amid Expansion and Product Innovation

    Greggs Sees Sales Growth in H1 2025 Amid Expansion and Product Innovation

    Greggs plc (LSE:GRG) reported a 7% increase in total sales for the first half of 2025, navigating headwinds such as reduced footfall and weather-related disruptions. The company continues to pursue strategic expansion and innovation, opening new shops and evolving its menu to better align with changing consumer preferences. Investments in supply chain infrastructure are underway to support long-term growth, alongside an expanded frozen ‘Bake at Home’ range through a growing partnership with Tesco.

    Greggs demonstrates solid financial health and trades at a reasonable valuation, supporting a positive investment case. However, technical analysis highlights a bearish trend, signaling potential short-term risk. The company’s strong leadership and ongoing strategic initiatives remain important drivers of confidence.

    About Greggs plc

    Greggs plc is a leading UK food-to-go retailer, widely recognized for its affordable, convenient offerings. Originally a bakery chain, Greggs has evolved into a modern convenience food brand with a wide selection of food and beverages, including coffee and breakfast items. Its network spans company-owned and franchise shops across retail and travel locations.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Sylvania Platinum Sets Production Record and Delivers Strong Q4 FY2025 Results

    Sylvania Platinum Sets Production Record and Delivers Strong Q4 FY2025 Results

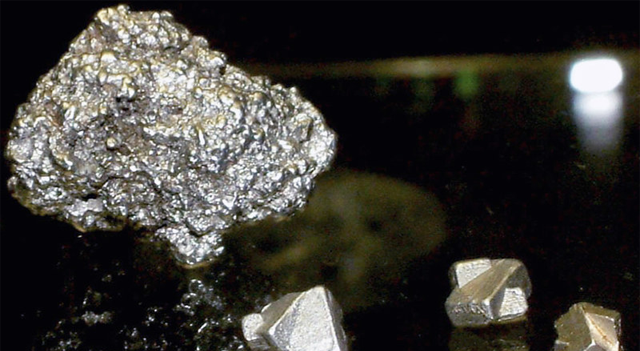
    Sylvania Platinum Limited (LSE:SLP) reported robust results for the fourth quarter ending June 2025, with a 3% increase in 4E PGM ounces produced and a record annual output of 81,002 4E PGM ounces. Net revenue rose 15% quarter-on-quarter, while EBITDA nearly doubled, driven by higher production volumes and rising platinum group metal (PGM) prices. The Thaba Joint Venture project has begun commissioning and is expected to significantly boost future production and revenue. The company also recorded its best-ever safety performance, achieving important milestones in injury-free operations, underscoring its commitment to operational excellence.

    Sylvania Platinum’s strong operational metrics and positive corporate developments contribute to a favorable overall outlook. Despite a stable financial position, some challenges remain, including declining revenue trends and negative free cash flow. However, the company’s attractive valuation and high dividend yield add to its investment appeal.

    About Sylvania Platinum

    Sylvania Platinum Limited is a low-cost producer of platinum group metals—including platinum, palladium, and rhodium—based in South Africa. It specializes in retreating PGM-rich chrome tailings from mines within the Bushveld Igneous Complex, making it the industry leader in chrome tailings reprocessing. The company also holds mining rights in the Northern Limb of the BIC and is actively developing the Thaba Joint Venture, currently in commissioning phase.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Card Factory Acquires Funky Pigeon to Strengthen Digital Growth

    Card Factory Acquires Funky Pigeon to Strengthen Digital Growth

    Card Factory (LSE:CARD) has completed the purchase of Funky Pigeon from WH Smith PLC for £24 million, advancing its digital and omnichannel ambitions. This deal positions Card Factory as the UK’s second-largest online retailer of cards and gifts. By integrating Funky Pigeon’s technology platform, the company aims to boost operational efficiency and enhance customer experience, with expected annual synergies and earnings improvements exceeding £5 million. The acquisition will be financed using existing debt facilities, keeping leverage impact minimal, and is forecasted to deliver solid returns to shareholders.

    Card Factory’s outlook is supported by strong financial results and appealing valuation metrics, offering promising growth and income opportunities. While short-term technical signals indicate some volatility, the company’s long-term prospects remain encouraging thanks to strategic growth initiatives and positive market sentiment.

    About Card Factory

    Card Factory is the UK’s foremost specialist retailer of greeting cards, gifts, and celebration products, catering to a broad range of occasions. The company emphasizes a balanced approach across its physical stores and expanding digital channels.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Games Workshop Boosts Dividend Following Solid Financial Results

    Games Workshop Boosts Dividend Following Solid Financial Results

    Games Workshop Group PLC (LSE:GAW) has declared a dividend of 55 pence per share, raising the total dividend payout for the 2025/26 financial year to £1.40 per share, up from £1.00 the previous year. This increase aligns with the company’s consistent dividend policy and underscores its dedication to delivering shareholder value, which may strengthen investor confidence and enhance its market standing.

    The company’s robust financial performance and favorable corporate developments are key drivers behind the positive outlook for its shares. Although the stock trades at a relatively high price-to-earnings ratio, the attractive dividend yield provides a compelling element for investors. Technical signals show moderate strength, supporting an optimistic market view.

    About Games Workshop

    Games Workshop Group PLC is a leading player in the tabletop miniature wargaming sector, best known for its Warhammer range. The company designs, manufactures, and markets fantasy miniatures and games to a worldwide community of hobbyists and collectors.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • AstraZeneca Reports Strong H1 2025 Performance and Unveils Major US Investment Plan

    AstraZeneca Reports Strong H1 2025 Performance and Unveils Major US Investment Plan

    AstraZeneca (LSE:AZN) delivered impressive financial results for the first half of 2025, driven by robust revenue growth in oncology and biopharmaceutical segments. The company announced a landmark $50 billion investment focused on expanding its US manufacturing and research facilities, including the development of its largest-ever manufacturing plant. This strategic move underscores AstraZeneca’s confidence in its innovative portfolio and its goal to reach $80 billion in revenue by 2030.

    Alongside financial strength, AstraZeneca reported positive Phase III clinical trial results and secured key regulatory approvals, further solidifying its competitive position in the pharmaceutical sector. Despite some caution signaled by technical market indicators, the company’s strong fundamentals and forward-looking initiatives support an optimistic growth outlook.

    About AstraZeneca

    AstraZeneca is a leading global biopharmaceutical firm specializing in the discovery, development, and commercialization of prescription medicines. Its core therapeutic areas include oncology, cardiovascular, renal & metabolism, and respiratory & immunology. The company is recognized for a robust R&D pipeline and is actively enhancing its manufacturing and research capabilities, particularly in the US market.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Gaming Realms Delivers Strong H1 2025 Results Driven by Revenue and EBITDA Growth

    Gaming Realms Delivers Strong H1 2025 Results Driven by Revenue and EBITDA Growth

    Gaming Realms (LSE:GMR) announced a solid first half for 2025, reporting an 18% rise in revenue alongside a 30% increase in adjusted EBITDA. This growth was largely fueled by the expansion of its licensing operations and the strengthening of global partnership networks. The launch of new Slingo game titles and the onboarding of 19 additional distribution partners have bolstered the company’s scalable, high-margin business model, supporting its broader expansion ambitions and setting an optimistic outlook for the rest of the year.

    The company’s robust financial position, combined with strong revenue gains and prudent cash management, underscores its healthy operational performance. While technical indicators reflect positive momentum, investors should be mindful of overbought conditions. The company’s valuation remains fair, although the absence of a dividend yield could be a drawback for some shareholders.

    About Gaming Realms

    Gaming Realms specializes in developing and licensing mobile-centric gaming content, with operations spanning the UK, U.S., Canada, and Malta. Its portfolio includes innovative offerings such as Slingo, bingo, and slot games, all supported by a proprietary data platform designed to engage audiences worldwide.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Journeo Posts Strong H1 2025 Results, Confident in Growth Prospects

    Journeo Posts Strong H1 2025 Results, Confident in Growth Prospects

    Journeo plc (LSE:JNEO) has reported solid first-half results for 2025, highlighting a strategic focus on organic growth complemented by targeted acquisitions. Although group revenue saw a slight dip to £24.5 million, the company experienced notable increases in key areas, with fleet revenue up 46% and passenger revenue rising 17%.

    Supported by a robust order book and growing sales order intake, Journeo anticipates full-year revenue to reach around £52 million, in line with market forecasts. The company is actively evaluating strategic acquisition opportunities to make effective use of its cash reserves, signaling confidence in sustained expansion.

    Journeo’s positive outlook is underpinned by strong financial performance and recent contract wins, despite mixed signals from technical market indicators. The company’s continued investments in growth initiatives across important sectors remain central to its forward-looking strategy.

    About Journeo

    Journeo plc specializes in Intelligent Transport Systems, delivering cutting-edge solutions to improve transport infrastructure across urban centers, airports, and public transit networks. Collaborating with local and combined authorities, Network Rail, and leading multinational transport operators, Journeo enhances efficiency and sustainability. The company operates through five subsidiaries, providing services including CCTV video surveillance, telematics, real-time communications, electronic passenger information, and technical support across the UK, Denmark, Sweden, and Iceland.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Morgan Sindall Posts Record H1 2025 Results with Broad-Based Growth

    Morgan Sindall Posts Record H1 2025 Results with Broad-Based Growth

    Morgan Sindall Group (LSE:MGNS) has delivered its strongest first half performance to date, reporting a 7% increase in revenue to £2.37 billion alongside a 40% jump in adjusted operating profit to £91.8 million. The company’s growth was driven by solid performances across multiple divisions, notably in Fit Out and Construction, buoyed by a healthy order book and supportive market dynamics.

    The group’s strategy, emphasizing partnership-led projects and benefiting from ongoing government infrastructure investments, has led to the upgrading of medium-term growth targets for both its Fit Out and Construction divisions. Additionally, the recent integration of Property Services into the Construction division is anticipated to further enhance Morgan Sindall’s competitive positioning.

    Strong financial results combined with recent positive corporate developments have contributed to the company’s elevated outlook score. Technical indicators reflect bullish momentum, although investors are advised to remain cautious due to signs of an overbought market. The stock continues to offer an attractive valuation complemented by a solid dividend yield.

    About Morgan Sindall

    Morgan Sindall Group plc is a prominent UK construction and regeneration firm operating across diverse sectors, including public, regulated, and private markets. The company operates through six core divisions: Partnership Housing, Mixed Use Partnerships, Fit Out, Construction, Infrastructure, and Property Services. In 2024, Morgan Sindall reported revenues of approximately £4.5 billion and employs over 8,000 people nationwide.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.

  • Blue Star Capital’s SatoshiPay Secures £1 Million Loan and Hits Key Development Milestones

    Blue Star Capital’s SatoshiPay Secures £1 Million Loan and Hits Key Development Milestones

    Blue Star Capital plc (LSE:BLU) has confirmed that its portfolio company, SatoshiPay Ltd, has successfully drawn down a secured loan of £1 million. The loan, backed by the value of SatoshiPay’s digital asset treasury, is intended to strengthen the company’s treasury management capabilities. This arrangement enables Blue Star, as the largest shareholder, to participate in SatoshiPay’s growth while retaining security over the loaned funds.

    In addition, SatoshiPay has reached the second phase of its milestone targets related to a grant from The Web3 Foundation. These achievements support the launch of its Vortex product in strategic markets and the development of a Polkadot offramp. Together, these advancements pave the way for accelerating the rollout of Vortex and expanding its ecosystem.

    About Blue Star Capital

    Blue Star Capital plc is an investment firm specializing in emerging technology sectors such as blockchain, digital payments, and esports. Its portfolio includes SatoshiPay Ltd, a pioneer in blockchain payment solutions; Dynasty Media & Gaming, a business-to-business white label gaming platform; and Paidia, a gaming platform designed for female audiences.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.