Author: Fiona Craig

  • European gas prices reach highest level since March amid Persian Gulf supply risks

    European gas prices reach highest level since March amid Persian Gulf supply risks

    European natural gas prices climbed to their highest levels since March on Tuesday as renewed military exchanges between the United States and Iran increased concerns over LNG shipments through the Persian Gulf.

    The benchmark Dutch front-month gas contract rose 1.3% to €71.30 per megawatt-hour (MWh), extending a gain of almost 5% in the previous session and remaining above €70.

    In Britain, wholesale gas prices recorded a larger move as traders returned following Monday’s public holiday. The NBP contract increased 6.4% to 175.40 pence per therm.

    The increases came as energy markets assessed the potential impact of further disruption to commercial shipping through the Strait of Hormuz, a major transit route for global LNG supplies.

    Strait of Hormuz remains in focus after U.S.-Iran strikes

    U.S. forces carried out air strikes against Iranian rocket launchers on Larak Island, followed by Iranian missile attacks on two U.S. military air bases in Jordan.

    U.S. President Donald Trump has raised the possibility of additional strikes against Iranian infrastructure, adding uncertainty over the duration of the conflict and its potential effect on commercial shipping.

    Approximately one-fifth of global LNG supplies transit the Strait of Hormuz, with Qatar accounting for a significant proportion of those volumes.

    Any extended disruption to the waterway could affect the availability of LNG cargoes for international buyers. European utilities, which have reduced access to pipeline imports compared with previous years, also compete with Asian buyers for spot LNG supplies.

    European gas storage levels remain below seasonal average

    The latest price increase comes as European gas storage levels remain below their recent seasonal norms ahead of the 2026/27 winter heating season.

    According to Gas Infrastructure Europe data cited in the supplied information, regional storage facilities are approximately 62% full, around 17 percentage points below the five-year seasonal average.

    Higher summer electricity demand during periods of elevated temperatures in Southern Europe, together with scheduled maintenance affecting Norwegian offshore pipeline supplies, reduced the pace of storage injections during August.

    These conditions leave European gas markets more exposed to changes in LNG availability as the winter season approaches, although actual winter supply conditions will depend on factors including weather, demand and future import flows.

    Higher energy prices add to inflation considerations

    European natural gas prices have risen alongside crude oil, with Brent holding above $91 a barrel.

    Higher wholesale energy prices could feed into European inflation if sustained, although the extent and timing of any effect on consumer prices remains uncertain.

    Preliminary data released Tuesday showed Eurozone headline inflation accelerating to 3.3% year over year in August, with energy costs contributing to the increase.

    The figures come ahead of the European Central Bank’s September 10 monetary policy meeting. Market participants have increased expectations for another 25-basis-point interest-rate increase, although the ECB has not yet made its policy decision and the outcome remains uncertain.

    European gas markets therefore remain focused on developments in the Persian Gulf, LNG shipping through the Strait of Hormuz and the pace of storage accumulation ahead of the winter heating season.
  • MedPal AI highlights FDA approval of Mounjaro for cardiovascular risk reduction

    MedPal AI highlights FDA approval of Mounjaro for cardiovascular risk reduction

    MedPal AI plc (LSE:MPAL) noted Eli Lilly’s announcement that the U.S. Food and Drug Administration has approved Mounjaro (tirzepatide) to reduce the risk of major adverse cardiovascular events in adults with type 2 diabetes who are at high risk of such events.

    The approval, announced on August 28, 2026, covers cardiovascular death, heart attack and stroke. MedPal said the expanded indication increases the potential patient population for GLP-1 medicines beyond their existing use in diabetes and weight management.

    The company operates New Health, its dedicated GLP-1 weight management clinic, which already dispenses Mounjaro in the UK under the medicine’s existing UK authorisation.

    MedPal estimates potential UK population of around 1.4 million

    Eli Lilly estimates that as many as one in three U.S. adults with type 2 diabetes has undetected cardiovascular disease, according to MedPal.

    In the UK, more than 4.7 million people have been diagnosed with diabetes, approximately 90% of whom have type 2 diabetes, based on Diabetes UK figures for 2024/25.

    Applying the same one-in-three assumption, MedPal’s board estimates that approximately 1.4 million UK adults could fall within the population addressed by the new U.S. indication. The FDA decision does not alter Mounjaro’s current UK prescribing authorisation.

    The European Medicines Agency added cardiovascular outcome data to Mounjaro’s EU product information in June 2026. Eli Lilly has also said regulatory submissions based on the data are under review in other markets. MedPal noted that no equivalent UK label change has been announced and that there is no certainty over whether or when one will occur.

    SURPASS-CVOT included more than 13,000 patients

    The FDA decision followed cardiovascular data from the SURPASS-CVOT study, which tracked 13,299 patients for approximately five years.

    According to Eli Lilly, the study showed an 8% lower rate of cardiovascular death, heart attack or stroke for Mounjaro compared with Trulicity (dulaglutide), another GLP-1 treatment with an established cardiovascular benefit.

    MedPal said the results add cardiovascular risk reduction to the range of applications being considered for GLP-1 medicines.

    Morgan Stanley Research has forecast that the global GLP-1 market could reach approximately £140 billion by 2035, while Grand View Research projects the UK prescription weight-loss medication market will increase from approximately £313 million in 2025 to around £1.85 billion by 2033.

    MedPal previously stated that Mounjaro accounted for approximately 79% of the UK GLP-1 market as of its January 28, 2026 announcement.

    Foundayo available through New Health

    MedPal also said Foundayo (orforglipron), Eli Lilly’s once-daily oral GLP-1 weight-loss medicine, is now available through New Health.

    The medicine was authorised by the UK Medicines and Healthcare products Regulatory Agency on August 10, 2026, making the UK the first European country to grant approval, according to the company. New Health began offering Foundayo during the first days of UK commercial supply.

    MedPal reported on August 4 that New Health generated more than £180,000 in private prescription revenue during July following three weeks of marketing. The company said this represented an annualised run rate of more than £2.2 million, compared with an annualised recurring revenue run rate of approximately £8.6 million for the wider group.

    New Health has direct arrangements as an authorised purchaser of Eli Lilly products and already dispenses Mounjaro under its existing UK authorisation.

    MedPal assesses potential expansion of GLP-1 applications

    MedPal’s board said it believes cardiovascular data could contribute to increased adoption of GLP-1 medicines and that a future UK label expansion, if approved, could increase the population for whom the treatment is clinically relevant.

    The company stressed that the new U.S. indication does not itself change how Mounjaro can currently be prescribed in the UK.

    Jason Drummond, Founder and Chief Executive Officer of MedPal, commented:

    “GLP-1s began as diabetes treatments and became the biggest story in weight loss. Now the FDA has approved Mounjaro to cut the risk of heart attack and stroke. Every time the science widens, the market follows suit and this is the biggest expansion yet.

    “New Health was built for exactly this: direct supply from Eli Lilly and Novo Nordisk, clinician-led prescribing, robotic dispensing, and Foundayo already live on new.co.uk within days of first UK supply. The GLP-1 and peptide opportunity keeps compounding and New Health sits in the middle of it. We are just getting started.”

    MedPal operates digital health and pharmacy services

    MedPal AI operates a vertically integrated digital health and pharmacy business. Its operations include NHS Distance Selling Pharmacy hubs at Sarus Court in Runcorn and Swaffham, the New Health GLP-1 weight management clinic, a B2B care home pharmacy supply operation and eMARx, its electronic medication administration record software for care homes.

    The group also operates Juno, an AI health companion built on Anthropic’s Claude. MedPal is seeking to develop a platform connecting prescribing, dispensing, delivery, medication administration and AI-supported patient services.

  • Reckitt shares rise 4.3% following Mead Johnson court verdict and J.P. Morgan upgrade

    Reckitt shares rise 4.3% following Mead Johnson court verdict and J.P. Morgan upgrade

    Reckitt Benckiser Group (LSE:RKT) shares gained 4.3% on Tuesday after a U.S. jury found in favour of its Mead Johnson unit in litigation concerning its Enfamil preterm infant formula.

    The case alleged that the formula caused necrotizing enterocolitis (NEC), a serious bowel disease. A unanimous jury in the U.S. District Court for the Northern District of Illinois sided with Mead Johnson.

    The trial was the first bellwether case involving Mead Johnson in the federal multidistrict NEC litigation. Reckitt said there are currently no outstanding jury verdicts against Mead Johnson across the broader NEC litigation.

    J.P. Morgan upgrades Reckitt to overweight

    The court decision coincided with an upgrade from J.P. Morgan, which raised its rating on Reckitt to “overweight” from “neutral”.

    The brokerage said attention could increasingly turn towards the valuation of Reckitt’s core operations and the outlook for Mead Johnson.

    J.P. Morgan analyst Celine Pannuti commented, “We see rising prospects for resolution on NEC litigation following Abbott’s partial settlement of some NEC cases, which makes the potential for a resolution closer than feared, along with the elimination of the overhang for Reckitt should allow the market to refocus on the core valuation.”

    The comments followed Abbott’s partial settlement of some NEC cases, which J.P. Morgan cited in assessing the prospects for a broader resolution of the litigation.

    Reckitt continues to assess baby formula business

    Reckitt has been considering options for its baby formula operations as the business remains affected by NEC-related litigation.

    The company has also been concentrating its portfolio around its core brands. Last year, Reckitt sold a majority stake in its Essential Home business to private equity firm Advent for $4.8 billion.

    The infant formula lawsuits have remained a factor for investors in recent months, with Reckitt facing multiple claims relating to its products.

  • Eurozone manufacturing PMI reaches highest level since May 2022

    Eurozone manufacturing PMI reaches highest level since May 2022

    Eurozone manufacturing activity expanded at its fastest pace in more than four years in August, according to the latest S&P Global PMI survey.

    The S&P Global Eurozone Manufacturing PMI increased to 52.7 from 51.9 in July, reaching its highest level since May 2022. The survey data were collected between August 10 and August 21, 2026.

    Factory production increased for a third consecutive month, with the Output Index rising to 53.3 from 52.9 in July, its highest reading in four-and-a-half years. Intermediate goods provided the largest contribution to the increase in production.

    New orders record strongest increase since early 2022

    New factory orders increased at their fastest rate since early 2022, while export business expanded for only the second time in four-and-a-half years.

    Austria, Germany and the Netherlands recorded particularly high rates of growth in overseas sales.

    Germany, the eurozone’s largest economy, reported its strongest month of manufacturing growth in more than four years, while France also contributed to the overall expansion.

    Conditions varied elsewhere in the region. Italy recorded its first contraction since January, while Spain remained in contraction territory.

    Purchasing activity increases as supply delays continue

    Eurozone manufacturers increased purchasing activity during August following modest reductions in June and July.

    Despite the increase in purchases, inventories of inputs continued to decline and did so at a faster rate. Supply-chain pressures also remained evident, with supplier delivery times lengthening sharply during the month.

    Manufacturing employment was broadly unchanged, an improvement compared with more than three years of continuous declines. Outstanding orders were also unchanged from July.

    Cost inflation eases as business confidence improves

    Input costs continued to increase in August, but the rate of inflation slowed to its lowest level in six months.

    Price increases for both manufacturing inputs and finished goods nevertheless remained above levels recorded before the start of the Middle East conflict.

    Business confidence improved for a fourth consecutive month. Manufacturers’ expectations for output growth over the next 12 months also moved above their long-term average.

  • Gold prices retreat as higher yields and oil reshape Fed rate expectations

    Gold prices retreat as higher yields and oil reshape Fed rate expectations

    Gold moved lower on Tuesday as rising U.S. Treasury yields and higher crude prices coincided with increased expectations that the Federal Reserve could raise interest rates at its September meeting.

    At 04:46 ET (08:46 GMT), XAU/USD declined 1.6% to $4,377.84 an ounce, while gold futures fell 1.2% to $4,426.26. XAG/USD was down 2.4% at $64.98 an ounce and XPT/USD declined 1.2% to $1,774.70.

    The U.S. Dollar Index increased 0.2% to 99.59.

    September Fed rate expectations increase

    Gold has fallen approximately $320 from last week’s peak near $4,697. The decline has occurred alongside increases in oil prices and government bond yields.

    On Friday, gold dropped more than 3% after Federal Reserve Chair Kevin Warsh reiterated the central bank’s focus on returning inflation to its 2% target.

    CME FedWatch indicated that markets were assigning around a 66% probability to a 25-basis-point rate increase at the Fed’s September meeting, up from approximately 40% before Warsh’s Jackson Hole address.

    Oil prices have meanwhile moved higher following renewed military exchanges between the United States and Iran. Brent crude rose above $91 per barrel and U.S. crude traded above $86 as markets considered potential risks to energy supplies.

    The benchmark 10-year U.S. Treasury yield increased to around 4.78%, its highest level since early 2025, as government bond yields also rose across major global markets.

    Tony Sycamore, senior market analyst at IG, linked the approximately $300 decline in gold from last week’s high to Warsh’s more hawkish Jackson Hole comments and renewed tensions around the Strait of Hormuz.

    Sycamore said the combination of higher oil prices and rising bond yields had increased pressure on gold ahead of the Federal Reserve’s next meeting. He estimated that markets were pricing around 60 basis points of rate increases through June 2027.

    August rally remains part of gold’s broader performance

    The latest decline follows a gain of nearly 10% for gold during August, when the U.S. Treasury unexpectedly increased purchases of longer-dated government debt.

    Those purchases contributed to lower borrowing costs and a weaker dollar. Concerns about the level of U.S. government debt and the possibility of currency devaluation were also among the factors influencing demand for the precious metal.

    The debasement trade was one factor behind gold’s approximately 65% increase in 2025, as investors sought assets considered potential hedges against expanding government deficits and weaker currencies.

    Gold-backed exchange-traded funds recorded inflows, while central bank purchases also contributed to demand.

    Employment reports could provide further signals for Fed policy

    Gold continued to trade below its 200-day moving average, which stood near $4,526, after moving beneath the technical level following Warsh’s speech.

    Sycamore said the decline had not changed his medium-term view that gold established a base around the late-June low near $3,942. He continues to favour purchases during pullbacks and maintains a longer-term upside target of $5,000.

    Market attention will turn to job openings data, the ADP employment report and Friday’s nonfarm payrolls figures for additional information on U.S. labour market conditions ahead of the Federal Reserve’s September policy meeting.

  • Crude oil advances as U.S.-Iran tensions put Strait of Hormuz supplies in focus

    Crude oil advances as U.S.-Iran tensions put Strait of Hormuz supplies in focus

    Crude oil prices moved higher on Tuesday as renewed military activity involving the United States and Iran increased attention on potential supply disruptions in the Middle East.

    At 0739 GMT, Brent crude futures were up $1.18, or 1.3%, at $91.67 per barrel. U.S. West Texas Intermediate crude increased $1.27, or 1.48%, to $87.03.

    The increase followed comments from U.S. President Donald Trump on Monday indicating the possibility of additional strikes against Iran after the first direct exchange of attacks between the two countries since late July.

    “The tit-for-tat missile exchanges between the US and Iran bring validation to those who believe that even if not a ‘forever war’, this conflict will run and run,” PVM analyst John Evans said.

    Mediation efforts continue as Hormuz traffic remains reduced

    Iranian President Masoud Pezeshkian said Tuesday that Iran would respond immediately if the United States resumed compliance with its commitments under the interim peace agreement signed in June.

    Qatar and Oman are among the countries involved in mediation efforts aimed at reaching an agreement to reopen the Strait of Hormuz. The waterway accounted for approximately one-fifth of global oil supplies before the conflict began in late February.

    Kpler data showed around five visible commodity vessels passing through the strait per day on Monday, compared with an average of approximately 14 over the previous 10 days. None of the five vessels were liquid tankers.

    Shipping risks were also highlighted after the United Kingdom Maritime Trade Operations agency said a tanker reported being struck by three projectiles while leaving the Strait of Hormuz on Tuesday. No casualties or environmental effects were reported.

    “Despite satellite tracking firms suggesting oil flowing through Hormuz is around 6 million barrels per day, that is well below pre-conflict levels,” ANZ analysts said in a note.

    Oil inventories add to market considerations

    ANZ analysts also pointed to global oil inventories as a factor being monitored by the market.

    “In the meantime, the buffers the global oil market has been relying on are becoming exhausted. U.S. inventories are nearing minimum levels, while China’s ability to keep imports low will be tested as seasonal demand picks up.”

    The combination of reduced shipping activity through the Strait of Hormuz and inventory levels remains among the factors being assessed by crude markets.

    Analysts surveyed by Reuters in August expect oil prices to remain above $80 per barrel during 2026 as shipping disruptions continue.

  • U.S. stock futures little changed as oil and global bond yields remain in focus: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. stock futures little changed as oil and global bond yields remain in focus: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. equity futures traded close to unchanged levels early Tuesday as markets monitored the outlook for interest rates, higher crude prices and renewed military activity involving the United States and Iran.

    Investors were also assessing a rise in Japanese government bond yields ahead of several U.S. economic releases, including labour market and manufacturing data.

    Wall Street futures flat ahead of economic releases

    At 03:40 ET, futures linked to the S&P 500, Nasdaq 100 and Dow were broadly unchanged.

    The moves followed declines on Wall Street in the previous session, when higher U.S. Treasury yields and rising oil prices formed part of the market backdrop.

    Attention is turning towards Friday’s nonfarm payrolls report, which will provide another measure of U.S. labour market conditions ahead of the Federal Reserve’s September policy decision.

    Tuesday’s calendar includes the July Job Openings and Labor Turnover Survey and the ISM manufacturing index.

    Japanese 10-year yield moves above 3%

    Japan’s benchmark 10-year government bond yield climbed above 3% on Tuesday, reaching that level for the first time since September 1996.

    The yield has more than tripled since 2024 as the Bank of Japan has shifted away from its previous ultra-loose monetary policy.

    Investors are also monitoring the effect of higher energy costs on Japanese inflation and the potential implications for future Bank of Japan interest rate decisions.

    Higher yields on Japanese government debt could affect the relative attractiveness of overseas assets for domestic investors, although the extent of any resulting changes to investment allocations remains uncertain.

    Brent trades above $91 as markets monitor Strait of Hormuz

    Crude prices extended their gains on Tuesday amid continued military exchanges involving the United States and Iran.

    At 01:02 ET, Brent crude futures were 1.1% higher at $91.51 per barrel, while WTI futures rose 1.4% to $86.99. Both benchmarks had advanced nearly 3% in the previous session.

    The latest developments followed U.S. strikes against Iranian military targets on Larak Island and subsequent Iranian missile attacks on U.S. military facilities in Jordan.

    President Donald Trump has also raised the possibility of further military action against Iran.

    Markets are monitoring the developments for their potential effect on energy supplies and shipping through the Strait of Hormuz.

    Tanker incident adds to shipping concerns

    The Strait of Hormuz remains a focus because of the volume of crude oil and petroleum products transported through the waterway.

    According to the United Kingdom Maritime Trade Operations agency, a tanker was struck by three unidentified projectiles while leaving the strait on Monday.

    The duration and scale of any disruption to commercial shipping remain uncertain. Any sustained reduction in energy shipments through the waterway could affect global oil supplies and prices.

    Higher energy prices could also contribute to inflation through transportation, production and consumer energy costs.

    U.S. labour and manufacturing data in focus

    Investors will receive the July JOLTS job openings report and ISM manufacturing index later Tuesday.

    Federal Reserve Governor Michael Barr is also scheduled to speak.

    Markets are assessing the possibility of another interest rate increase after Federal Reserve Chair Kevin Warsh recently adopted a more hawkish tone.

    Tuesday’s releases and Friday’s nonfarm payrolls report will provide additional economic information ahead of the Federal Reserve’s September interest rate decision.

  • European stocks trade flat as bond yields rise and Middle East conflict continues: DAX, CAC, FTSE100

    European stocks trade flat as bond yields rise and Middle East conflict continues: DAX, CAC, FTSE100

    European equities were broadly unchanged on Tuesday as investors assessed higher global bond yields, developments in the Middle East and economic data scheduled for release later in the day.

    The pan-European STOXX 600 traded flat, while Germany’s DAX declined 0.6% and France’s CAC 40 gained 0.1%. London’s FTSE 100 fell 0.4%.

    Energy producers benefited from higher commodity prices, while other sectors traded lower amid rising sovereign borrowing costs and concerns about the potential inflationary effects of higher energy prices.

    Japanese government bond yields reach generational high

    Fixed-income markets remained a focus after the yield on Japan’s benchmark 10-year government bond rose to its highest level in a generation.

    U.S. Treasury and European sovereign bond yields also increased as investors adjusted interest-rate expectations amid inflation concerns and government debt issuance.

    Higher yields affected rate-sensitive sectors including technology, real estate and high-dividend utilities, as investors assessed the impact of higher discount rates on equity valuations.

    Markets assess further U.S.-Iran military exchanges

    Geopolitical developments also remained in focus following further military exchanges involving the United States and Iran.

    Iran launched overnight missile strikes targeting two U.S. military bases in Jordan following U.S. strikes against Iranian targets earlier in the week.

    U.S. President Donald Trump subsequently raised the possibility of additional military action against Iranian infrastructure.

    Energy commodity prices increased as markets assessed the potential impact of continued military activity on supplies and commercial shipping through the Strait of Hormuz.

    Eurozone inflation and U.S. JOLTS data awaited

    Investors were also awaiting August eurozone Consumer Price Index data, with the figures expected to provide further information on underlying inflation ahead of the European Central Bank’s policy meeting next week.

    Market participants were assessing the possibility of another 25-basis-point interest rate increase from the ECB, although the decision remains subject to incoming economic data and the central bank’s assessment.

    In the United States, the July Job Openings and Labor Turnover Survey is also due, providing additional information on labour market conditions ahead of Friday’s nonfarm payrolls report and the Federal Reserve’s September policy decision.

    Across regional markets, industrial, automobile and consumer stocks were among the areas facing pressure. The FTSE 100 recorded a smaller decline than Germany’s DAX, with energy and mining companies accounting for a substantial proportion of the UK benchmark.

  • Blencowe Resources reports Orom-Cross graphite used in Mach 5.5 rocket test

    Blencowe Resources reports Orom-Cross graphite used in Mach 5.5 rocket test

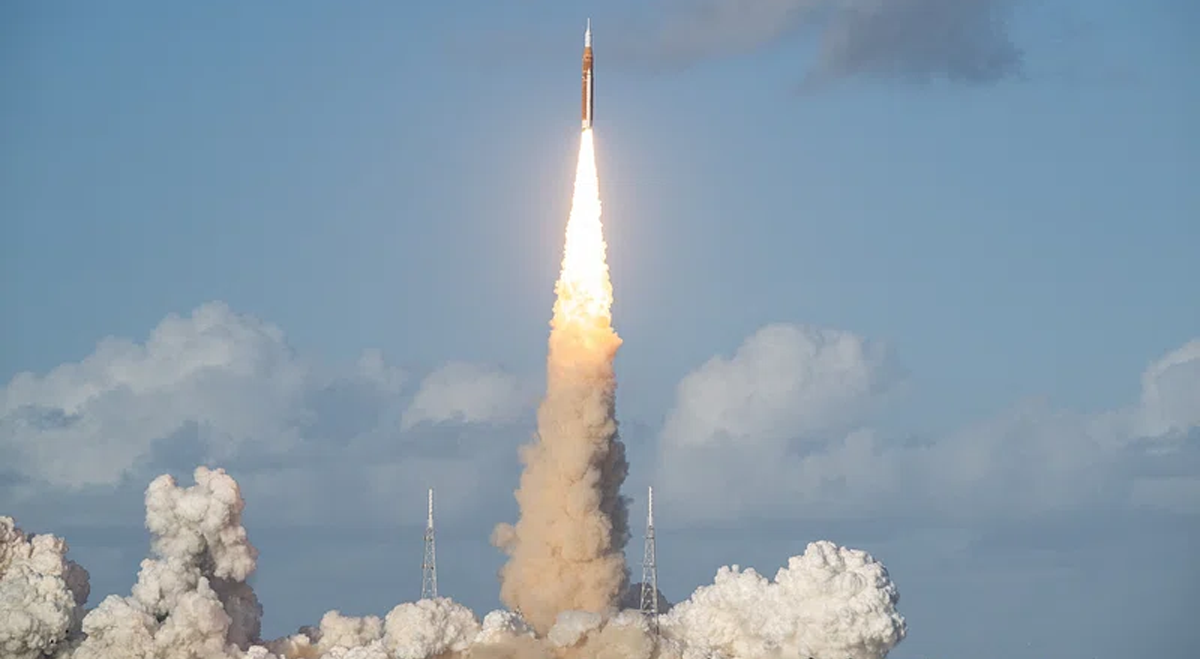
    Blencowe Resources (LSE:BRES) reported that graphite from its Orom-Cross Project in Uganda was used across several components of a hypersonic rocket that reached Mach 5.5 during a U.S. test programme.

    The flight took place on August 18 in Las Cruces, New Mexico, and was conducted by Pluto Aerospace alongside American Energy Technologies Co (AETC), Purdue University and U.S. Government Agencies. Blencowe Chief Operating Officer Iain Wearing attended the test.

    The solid-fuel rocket reached acceleration approaching 150G, an increase from the performance recorded during an earlier test programme in April.

    Orom-Cross graphite tested across multiple rocket components

    Graphite supplied from Orom-Cross was incorporated into an ablative rocket nozzle insert, anti-friction and ice-phobic coatings applied to the rocket’s fins, and the lithium-ion battery used to power the vehicle’s altimeter.

    AETC manufactured graphite mouldings for rocket and missile exhaust nozzles using Orom-Cross concentrates supplied by Blencowe. The material replaced a proportion of the synthetic graphite typically used in these applications.

    The lithium-ion battery incorporated natural graphite supplied by Blencowe alongside recycled graphite produced through AETC’s direct recycling process. According to the company, the battery contained no synthetic graphite.

    The August flight used a substantially larger motor than the rocket tested in April. Further orbital testing is planned for the fourth quarter of 2026.

    Blencowe continues testing Orom-Cross graphite applications

    Blencowe said the testing programme is examining the potential use of Orom-Cross graphite in specialist aerospace and defence applications as the company advances the project towards production.

    The company said successful qualification in these applications could create opportunities for additional offtake relationships and strategic funding, although no new agreements were announced in the supplied information.

    Blencowe Executive Chairman Cameron Pearce said: “These results continue to highlight the emergence of Orom-Cross graphite as an important source of high-quality graphite products for use in military and aerospace applications. There are relatively few graphite projects worldwide capable of supplying the quality of products required for these specialist applications, which may open new offtake relationships and strategic opportunities and places Orom-Cross in a strong position moving forward as we advance towards first production.”

    “As we complete funding for P1 Production and move to building the first stage of operations, we are continuously testing new products and adding new offtakers, each of which builds further value within the Project. Our strategy is to differentiate Orom-Cross from other graphite projects by targeting the most lucrative markets available to us, through both our products and strategic relationships.”

  • Market Open: Alien Metals Funding, Futura Medical Partner

    Market Open: Alien Metals Funding, Futura Medical Partner

    FTSE opens flat as bond and Middle East risks weigh, while Alien Metals secures exploration funding and Brent crude moves higher.

    Market Overview

    The FTSE 100 opened broadly unchanged at 10,824.60, as London markets returned from the bank holiday amid pressure from a global bond sell-off and renewed Middle East tensions. The Euronext 100 gained 0.06 per cent to 1,916.51, while Germany’s DAX fell 0.29 per cent to 26,181.16. In the US, the Nasdaq closed lower at 26,370.89 and the S&P 500 declined to 7,686.14. Higher borrowing costs and renewed geopolitical concerns weighed on broader risk appetite.

    Commodity markets reflected renewed concerns over Middle East supply disruption, with Brent crude moving higher alongside copper, gold and natural gas. Bitcoin was unchanged against sterling. The US dollar, Swiss franc, euro and Japanese yen weakened marginally versus the pound, while the Australian dollar strengthened slightly. Oil markets remained focused on renewed US-Iran fighting and risks to shipping through the Strait of Hormuz.


    Market Numbers

    FTSE 100: Up (0.001%), 10,824.60
    Euronext 100: Up (0.06%), 1,916.51
    DAX: Down (-0.29%), 26,181.16
    NASDAQ: Down, 26,370.89
    S&P 500: Down, 7,686.14


    In the Headlines

    Exploration funding – Alien Metals (LSE:UFO)
    Alien Metals’ joint venture partner West Coast Silver has secured commitments to raise A$6 million for further exploration at the Elizabeth Hill Silver Project. The funding supports additional drilling and technical work while Alien retains its 30% free-carried project interest and equity exposure to West Coast Silver.

    New U.S. partner – Futura Medical (LSE:FUM)
    Futura Medical reported first-half revenue of £1.62 million and appointed Market Performance Group as its new U.S. commercial partner for Eroxon. The consumer healthcare company is reshaping its U.S. commercial strategy while seeking further funding and partnerships to support its operations and product pipeline.


    Currencies (vs GBP)

    USD: Down (-0.01%), $1.3549
    CHF: Down (0.00%), Fr.1.0952
    EUR: Down (0.00%), €1.1662
    JPY: Down (0.00%), ¥216.443
    AUD: Up (0.00%), $1.8894
    Bitcoin (BTC/GBP): Unchanged, £58,067.58


    Commodities

    Copper: Up
    Gold: Up
    Brent Crude: Up
    Natural Gas: Up