Author: Fiona Craig

  • Wall Street looks to retail earnings as softer data reshapes Fed rate outlook: Dow Jones, S&P, Nasdaq, Futures

    Wall Street looks to retail earnings as softer data reshapes Fed rate outlook: Dow Jones, S&P, Nasdaq, Futures

    Investors entered the new week with expectations for an imminent Federal Reserve rate increase fading, leaving U.S. stock futures mixed as attention shifts towards major retail earnings and another round of economic indicators.

    Walmart (NYSE:WMT), Home Depot (NYSE:HD) and Lowe’s (NYSE:LOW) are among the prominent retailers due to report in the coming days, potentially providing fresh evidence about the health of U.S. consumer spending.

    Away from Wall Street earnings, investors are assessing reports that Anthropic (NASDAQ:ANTP) could generate as much as $200 billion in annual revenue by 2028 as the artificial intelligence company considers a potential IPO. Geopolitical risk also remains prominent after commercial shipping through the Strait of Hormuz slowed dramatically over the weekend.

    Fed tightening expectations retreat

    U.S. futures showed no clear direction early Monday. At 03:08 ET (07:08 GMT), Dow futures had fallen 26 points, or 0.1%, while S&P 500 futures were 15 points, or 0.2%, higher. Nasdaq 100 futures gained 160 points, equivalent to 0.5%.

    The moves followed declines for the major Wall Street averages in the previous session, when unexpectedly weak U.S. retail sales added to evidence of cooling economic conditions.

    Applied Materials (NASDAQ:AMAT) contributed to the pressure after an optimistic outlook still fell short of demanding investor expectations. Its shares dropped more than 5%, with the disappointment spilling over into other stocks associated with the artificial intelligence investment cycle.

    Deutsche Bank analysts identified signs that markets could be entering a summer lull, noting that the VIX volatility index fell to a 2026 low on Friday. They nevertheless highlighted “challenging August crosswinds playing out in bond markets.”

    “Expectations for an imminent Fed rate hike have been pulled back, but this has been accompanied by a significant U.S. curve steepening, with the backdrop of higher oil prices, elevated fiscal deficits, and demand for capital from the AI investment boom putting upward pressure on yields,” the analysts wrote.

    Bond investors will receive further signals this week from the minutes of the Federal Reserve’s July policy meeting and preliminary August business activity data.

    Corporate results could prove equally important for equities. Alongside Home Depot, investors are preparing for earnings from Target, Lowe’s and Walmart as they assess whether U.S. households are becoming more cautious with their spending.

    Anthropic’s potential IPO faces ambitious growth assumptions

    Anthropic (NASDAQ:ANTP) expects annual revenue to reach approximately $190 billion to $200 billion by 2028, Reuters reported, citing people familiar with the AI developer’s finances.

    Those projections are attracting attention as bankers and investors attempt to determine an appropriate valuation ahead of a possible initial public offering.

    The forecast is more than four times Anthropic’s $47 billion revenue run rate disclosed in May, meaning any valuation based on the projection would incorporate substantial expectations for continued expansion.

    According to Reuters, bankers and investors are using enterprise value-to-revenue multiples based on financial forecasts extending two years into the future.

    Revenue multiples are frequently applied to rapidly growing software companies before their profitability reaches maturity. Looking two years ahead is less conventional, however, reflecting both Anthropic’s rapid expansion and the difficulty of valuing an AI developer facing enormous spending requirements for computing capacity, model development and talent.

    Strait of Hormuz traffic virtually stops

    Geopolitical tensions remain another important variable for global markets after commercial shipping activity through the Strait of Hormuz fell sharply during the weekend.

    Kpler data cited by Reuters showed only five commodity vessels transited the waterway on Saturday, followed by none on Sunday. The previous weekend had recorded 31 crossings.

    The slowdown followed attacks on three vessels operated by Abu Dhabi National Oil Company last week, which were reported by the United Arab Emirates.

    Prospects for an immediate diplomatic solution have also deteriorated after the U.S. suggested its naval blockade of Iranian ports could continue indefinitely.

    The scale of the disruption is particularly significant given the strait’s importance to global energy supplies. Before the U.S. and Israel launched their assault against Iran in late February, more than 130 vessels were crossing the route every day.

    Brent crude futures were last 0.1% lower at $88.45 a barrel.

    Chinese factories feel pressure from weaker domestic demand

    China delivered another softer economic signal on Monday as industrial production growth slowed to 4.5% year-on-year in July.

    The figure missed expectations for a 5% increase and represented a slowdown from June’s 5.3% growth rate, according to the National Bureau of Statistics.

    Domestic conditions remain challenging for manufacturers. China’s official manufacturing PMI slipped into contraction territory in July, while consumer demand continued to show limited momentum.

    Export demand remains a source of resilience, particularly for higher-technology Chinese goods, helping to cushion the broader slowdown in factory output.

    Producers are nevertheless facing additional pressure from higher costs caused by disruption across international energy and shipping markets.

    Nvidia could deepen AI infrastructure role with SB Energy investment

    Nvidia (NASDAQ:NVDA) is considering an investment of up to $3 billion in SB Energy, according to The Information, which cited people familiar with the discussions.

    The SoftBank Group-backed company is developing a planned data centre campus in Ohio for OpenAI, and Nvidia’s potential investment would further expand the chipmaker’s involvement in the infrastructure supporting the AI industry.

    Separate negotiations between Nvidia, OpenAI and SB Energy reportedly involve the possibility of around $100 billion in credit support from Nvidia for the Ohio project.

    Such an arrangement would illustrate how Nvidia’s role in the AI boom is expanding beyond supplying advanced processors and into financing the enormous computing infrastructure required to develop and operate artificial intelligence systems.

    No final agreement has been reached, and the terms under discussion could still change. Nvidia is scheduled to report its latest quarterly earnings next week.

  • Market Open: Defence Tech Fund, Gattaca Profit Growth

    Market Open: Defence Tech Fund, Gattaca Profit Growth

    FTSE 100 opens flat as Fed rate expectations support sentiment, while Defence Holdings invests £2m and Gattaca reports profit growth.

    Market Overview

    The FTSE 100 opened broadly unchanged at 10,749.95, down less than 0.01 per cent from its previous close, while the Euronext 100 gained 0.04 per cent to 1,970.69 and Germany’s DAX was 0.02 per cent higher at 26,446.72. European sentiment was supported by falling bond yields and expectations that the Federal Reserve may remain on hold after softer US retail sales data. Overnight on Wall Street, the Nasdaq closed lower at 26,729.16 and the S&P 500 declined to 7,785.76.

    Commodity trading was mixed, with copper and gold higher while Brent crude and natural gas moved lower. Oil markets remained sensitive to continuing tensions involving Iran following a strong week for prices. Against sterling, the US dollar and Japanese yen strengthened marginally, the Swiss franc weakened slightly, while the euro and Australian dollar were unchanged. Bitcoin rose against sterling.


    Market Numbers

    FTSE 100: Down (-0.001%), 10,749.95
    Euronext 100: Up (+0.04%), 1,970.69
    DAX: Up (+0.02%), 26,446.72
    NASDAQ: Down, 26,729.16
    S&P 500: Down, 7,785.76


    In the Headlines

    Defence investment – Defence Holdings (LSE:ALRT)
    Defence Holdings has committed £2 million to a new UK defence technology fund. The investment increases the company’s exposure to emerging defence technologies as the sector attracts greater strategic attention.

    Contract hiring – Gattaca (LSE:GATC)
    Gattaca reported growth in profit and net fee income for FY26, supported by contract hiring. The performance highlights the importance of its contract recruitment operations in driving earnings growth.


    Currencies (vs GBP)

    USD: Up (+0.00%), $1.3546
    CHF: Down (-0.00%), Fr.1.1009
    EUR: Unchanged (0.00%), €1.1704
    JPY: Up (+0.01%), ¥215.684
    AUD: Unchanged (0.00%), $1.9119
    Bitcoin (BTC/GBP): Up, £46,806.15


    Commodities

    Copper: Up
    Gold: Up
    Brent Crude: Down
    Natural Gas: Down

  • European gas extends rally as Hormuz disruption deepens supply concerns

    European gas extends rally as Hormuz disruption deepens supply concerns

    European natural gas prices climbed for a fourth consecutive session on Monday, reaching their highest levels in several weeks as escalating tensions around the Strait of Hormuz combined with unusually low storage inventories to intensify concerns over supplies heading into autumn.

    Benchmark Dutch front-month futures rose 1.83% to €62.55 per megawatt-hour, touching their strongest level since July 24. British wholesale contracts recorded an even larger advance, rising more than 2% to 154.01 pence per therm and also reaching their highest intraday level since July 24.

    The gains marked a fourth straight positive session for both benchmarks, their longest consecutive daily advance since late July.

    Hormuz tensions add geopolitical premium

    The latest move follows an escalation in U.S. diplomatic and military rhetoric towards Tehran ahead of the weekend.

    Energy traders have increased the geopolitical risk premium embedded in European gas prices after Washington warned that it could impose a complete naval blockade on Iranian ports if restrictions on commercial shipping through the Strait of Hormuz continue.

    The prospect of stronger naval enforcement has further reduced expectations that an agreement restoring normal maritime traffic can be reached quickly.

    Disruption through the waterway has left LNG tankers originating from Qatar stranded and delayed spot cargoes that would otherwise be heading towards European import terminals.

    European utilities are simultaneously competing with Asian buyers for available LNG supplies. Asian importers have been bidding aggressively for uncommitted cargoes, increasing the challenge for European companies seeking replacement volumes on the global spot market.

    Low storage levels increase Europe’s exposure

    Supply concerns are being amplified by a significant deficit in European gas inventories.

    Figures from Gas Infrastructure Europe show that underground storage facilities across the European Union are only 59% full, an unusually low level for the middle of August.

    Intense summer heatwaves have contributed to the shortfall by increasing the amount of gas burned by utilities to meet cooling-related electricity demand. Delays to LNG imports have further restricted the pace at which inventories can be replenished ahead of the winter heating season.

    Market pricing is also making storage injections less attractive. Immediate gas supplies are commanding a substantial premium, leaving the forward curve deeply backwardated.

    That structure reduces the economic incentive for traders to purchase expensive spot gas today and store it for delivery later, potentially making it more difficult to rebuild inventories before colder weather arrives.

    Energy markets remain focused on supply risks

    With relatively few European economic releases scheduled at the beginning of the week, gas traders are looking primarily to geopolitical developments and movements in wider energy and commodity markets for direction.

    Broader financial markets received some relief from softer U.S. inflation indicators last week, which strengthened expectations for a more dovish Federal Reserve stance.

    European gas markets face a different set of pressures, however. Energy analysts continue to see limited scope for a sustained decline in prices while shipping through the Strait of Hormuz remains disrupted and European storage inventories remain significantly below normal seasonal levels.

  • European stocks rise as lower yields and Fed pause expectations support sentiment: DAX, CAC, FTSE100

    European stocks rise as lower yields and Fed pause expectations support sentiment: DAX, CAC, FTSE100

    European equities moved modestly higher at the start of the week as declining government bond yields and a weaker U.S. dollar improved risk appetite, with investors increasingly expecting the Federal Reserve to keep interest rates unchanged at its September meeting.

    The pan-European Stoxx Europe 600 Index gained 0.2%, recovering some ground after ending a four-week winning streak on Friday. Among the major regional markets, Germany’s DAX advanced 0.2%, France’s CAC 40 was broadly unchanged and London’s FTSE 100 climbed 0.4%.

    European sovereign bond yields retreated from the multi-week highs reached recently, providing some relief to equity markets. The move was particularly supportive for growth-oriented sectors, which tend to be more sensitive to changes in borrowing costs and discount rates.

    At the same time, the U.S. dollar weakened against major currencies as investors reduced expectations for further near-term Federal Reserve tightening.

    Weak U.S. data pushes Fed pause probability towards 70%

    Money markets are now pricing in approximately a 70% chance that the Federal Reserve will leave its benchmark interest rate unchanged at its September policy meeting.

    Expectations have shifted following a series of softer U.S. economic releases that have weakened the argument for additional monetary tightening in the near term.

    Investors have recently digested several important data points, including a weaker-than-expected July employment report showing a contraction in payrolls, Consumer Price Index figures that met expectations, a flat Producer Price Index reading and an unexpected 0.6% month-on-month decline in July retail sales.

    Taken together, the figures have reduced concerns that inflationary pressures will require an immediate policy response. That has encouraged expectations that the Federal Reserve can maintain its current policy stance for longer while assessing the direction of the U.S. economy.

    For equity markets, the possibility of an extended pause has provided support by reducing fears of another increase in borrowing costs.

    Sparse European calendar keeps global risks in focus

    Europe’s economic calendar is unusually quiet this week, leaving regional equity markets more dependent on developments in the global economy, bond markets, currencies and commodities for direction.

    Several risks that influenced trading throughout August nevertheless remain unresolved.

    One of the most significant is the continuing disruption to shipping through the Strait of Hormuz. Diplomatic negotiations between Washington and Tehran over commercial transit remain deadlocked, keeping crude oil prices elevated and maintaining pressure on input costs for energy-intensive European companies.

    European equities have already enjoyed a strong summer rally that brought several benchmarks close to record highs. As a result, strategists remain divided over whether equity risk premiums have become too compressed relative to persistently high real borrowing costs.

    The second-quarter earnings season is also largely complete. The succession of better-than-expected corporate results that supported European stocks through late July has therefore faded, leaving macroeconomic developments as a more important driver of market direction.

    Markets turn to U.S. PMIs and Jackson Hole

    Attention is now shifting towards upcoming U.S. economic indicators that could provide the next significant catalyst for global markets.

    S&P Global’s preliminary August Purchasing Managers’ Index readings for U.S. manufacturing and services are due later this week. They will be followed by the Federal Reserve’s annual Jackson Hole Symposium the following week.

    Investors will examine the data for evidence that economic activity is cooling at a controlled pace. A gradual slowdown would strengthen expectations for a soft landing while supporting the case for the Federal Reserve to keep rates unchanged.

    Markets will also be watching closely for any signs that inflationary pressures are rebuilding, which could challenge the increasingly widespread expectation of an extended policy pause.

  • FTSE 100 rises as weak U.S. retail sales ease Fed tightening concerns

    FTSE 100 rises as weak U.S. retail sales ease Fed tightening concerns

    UK equities moved higher on Monday as weaker-than-expected U.S. retail sales reduced expectations for further near-term monetary tightening by the Federal Reserve, allowing London’s blue-chip index to recover some ground after falling 1.4% last week.

    The FTSE 100 gained 0.26% as of 03:25 ET (07:25 GMT). Elsewhere in Europe, Germany’s DAX slipped 0.03%, while France’s CAC 40 edged 0.05% lower. Sterling strengthened 0.22% against the dollar to $1.3562.

    Sentiment received support from U.S. retail sales data showing a 0.6% month-on-month decline in July. Economists had expected an increase of 0.1%, while the contraction was the steepest monthly fall since May 2025.

    The disappointing figures pushed U.S. Treasury yields and the dollar lower on Friday as investors scaled back expectations for tighter Federal Reserve policy, providing a more supportive backdrop for equities at the beginning of the new week.

    U.S.-Iran tensions keep Hormuz risks in focus

    Geopolitical uncertainty remained a significant consideration for markets. Speaking at Market Regulation Headquarters on Sunday evening, Iran’s vice president said Tehran would be successful in its “economic warfare” as Washington prepared to announce another round of sanctions this week.

    Shipping activity through the Strait of Hormuz remained severely restricted. Ship-tracking company Kpler recorded no commodity vessel crossings on Sunday and only five on Saturday, compared with 31 during the previous weekend.

    The 60-day memorandum of understanding between the U.S. and Iran, agreed in June to halt hostilities, expired on Monday without discussions taking place over an extension. Tehran has maintained that Washington must first meet its obligations under the original agreement.

    Regional security arrangements have also moved into focus. Saudi Arabia, Turkiye and Pakistan signed the Mecca Joint Defence Agreement on Aug. 7, establishing collective-defence provisions. Washington welcomed the agreement, while Turkish President Erdogan said the pact had “sent an important message to the world” and described Egyptian participation as “possible.”

    Jefferies analysts said on Monday that they saw no simple route towards resolving the confrontation, characterising the current situation as “no war and no peace” while the Strait of Hormuz remains closed.

    “The only possibility remains a fudge or look the other way arrangement by which some traffic can start to flow through the Strait while the US and Iran try to negotiate a deal,” strategist Mohit Kumar wrote in a morning note.

    Jefferies said the fragile truce could potentially survive until the U.S. mid-term elections before the threat of renewed escalation increases. From a market perspective, the broker said a crucial question is how far oil prices could rise before Washington becomes willing to make concessions.

    The firm also noted that Europe and Asia are more vulnerable than the United States to an extended disruption in the Strait because of their greater dependence on imported energy supplies.

    UK housing market remains under pressure

    Domestic housing figures added to the cautious UK economic backdrop. Asking prices fell 2% month-on-month in August to an average of £364,999, according to a media report citing Rightmove data.

    The decline was the largest recorded for August since 2018. Prices were also 1% lower year-on-year, representing the steepest annual decline since December 2023, while the number of homes available for sale reached a 12-year seasonal high.

    Rightmove lowered its forecast for house prices across the whole of 2026 to a range of 0% to minus 2%, compared with its previous expectation for growth of 2%.

    “The mini Burnham bounce and some renewed general optimism have brought a degree of improvement,” Rightmove’s Colleen Babcock was quoted as saying, “but whether that develops into a more sustained recovery will likely depend on confidence, mortgage rates and the new chancellor’s first budget this Autumn.”

    Oil slips while gold moves higher

    Energy prices edged lower as investors continued to assess the geopolitical outlook. Brent crude fell 0.30% to $88.26 a barrel, while WTI declined 0.70% to $80.90.

    Precious metals moved in the opposite direction. Gold futures advanced 0.36% to $4,453.35 an ounce, while spot gold gained 0.46% to $4,397.18.

    UK round up

    AstraZeneca (LSE:AZN) discontinued its Phase III eVOLVE-Lung02 study after an independent review concluded that the combination of volrustomig and chemotherapy was unlikely to achieve its progression-free survival or overall survival endpoints when compared with pembrolizumab plus chemotherapy.

    The trial enrolled 895 patients and identified no new safety signals. AstraZeneca said its other Phase III studies evaluating volrustomig will continue as planned.

  • MTI Wireless Edge posts double-digit first-half growth as defence and water technology demand rises

    MTI Wireless Edge posts double-digit first-half growth as defence and water technology demand rises

    MTI Wireless Edge (LSE:MWE) delivered double-digit growth across revenue and profits during the first half of 2026, supported by increasing demand for defence products, smart water management technology and wireless communications solutions.

    For the six months ended 30 June 2026, revenue increased 11% to $26.7 million, while operating profit climbed 21% to $3.0 million. Net profit advanced 28% to $2.5 million, with the group’s gross margin improving to 33.8%.

    MTI also maintained a strong balance sheet, ending the period with net cash of $7.7 million after paying a $3.0 million dividend.

    All three of the group’s operating divisions contributed to the first-half improvement. Mottech recorded the strongest expansion in both revenue and profit, while MTI Summit benefited from operating scalability and additional defence contracts secured through PSK. The antenna business also built momentum after winning approximately $6 million of new orders, predominantly related to defence, which are expected to support a stronger second-half performance.

    Mottech, which provides water control and management technology, increased revenue by 31% and operating profit by 51%. Growth was driven by international demand for smart irrigation and water management systems.

    The group has also taken full ownership of Australian subsidiary Mottech Parkland, positioning the business to capture further opportunities in what MTI considers a rapidly expanding market.

    MTI’s antenna division continued to strengthen its exposure to defence customers after securing AS9100D certification. The business also reported healthy demand for its ABS® 5G backhaul products and secured a significant new customer during the period.

    Meanwhile, MTI Summit expanded its pipeline of defence-related contracts, adding to the group’s visibility for future activity. With a healthy order backlog and continued tender opportunities, management sees positive demand trends across all three divisions for the remainder of the year.

    The company’s broader financial profile is supported by rapid trailing 12-month revenue growth, stable margins and exceptionally low leverage. A notable decline in trailing 12-month free cash flow provides some counterbalance to these strengths.

    Technical indicators remain mixed, reflecting some near-term share-price weakness despite a longer-term upward trend. Valuation is comparatively supportive, with the shares trading on a reasonable price-to-earnings ratio alongside a solid dividend yield.

    More about MTI Wireless Edge

    MTI Wireless Edge is a technology group specialising in communications and radio-frequency solutions across three principal areas: antenna systems, water control and management, and wireless communications integration.

    Its antenna division supplies commercial and military customers, including products used in 5G backhaul networks. Mottech provides smart irrigation and water distribution technology to customers worldwide, while MTI Summit delivers communication systems, integration capabilities and design services with significant exposure to defence markets.

  • Gattaca grows profit and net fee income as contract hiring drives FY26 performance

    Gattaca grows profit and net fee income as contract hiring drives FY26 performance

    Gattaca (LSE:GATC) delivered stronger results for the year ended 31 July 2026, with group net fee income increasing 11% to £43.2 million as rising demand for contract recruitment supported growth across its core specialist markets.

    Contract net fee income advanced 16% during FY26, driven by activity across infrastructure, defence, energy, mobility and digital technology. This growth helped offset subdued statement of work activity and a modest decline in like-for-like permanent recruitment fees.

    Improved sales productivity and continued cost discipline also contributed to a significant increase in profitability. Gattaca expects to report underlying profit before tax of approximately £6.1 million, almost double the level achieved in the previous financial year and slightly ahead of its guidance.

    The group finished FY26 with net cash of £15 million, leaving it with a strong balance sheet as it considers opportunities to invest in further growth. The financial position also provides support for continued shareholder distributions in accordance with Gattaca’s stated dividend policy.

    Management intends to make targeted investments in additional sales consultants as it seeks to capture greater market share across its specialist sectors. The company is also continuing to evaluate selective acquisition opportunities that could strengthen its capabilities or increase exposure to attractive niche markets.

    Despite continued uncertainty in the wider economy and cautious hiring decisions among some customers, the board expects further progress during the new financial year. Gattaca is forecasting another improvement in profit before tax in FY27.

    The company’s wider financial picture remains mixed. Its low-leverage balance sheet and improving operating margins provide support, although negative operating and free cash flow and relatively thin net profitability remain areas of concern.

    Technical indicators also suggest some caution, with momentum signals remaining weak despite the shares trading above major moving averages. Valuation is more supportive, with Gattaca trading on a relatively low price-to-earnings ratio while also providing a moderate dividend yield.

    More about Gattaca

    Gattaca plc is a specialist workforce solutions provider supplying contract and permanent professionals alongside statement of work services.

    The group focuses on industries requiring highly skilled technical talent, including infrastructure, defence, energy, mobility and digital technology. Gattaca has also expanded its capabilities through acquisitions such as InfoSec People, strengthening its presence in specialist and niche recruitment markets.

  • Seeing Machines launches Physical AI platform to expand into collaborative robotics

    Seeing Machines launches Physical AI platform to expand into collaborative robotics

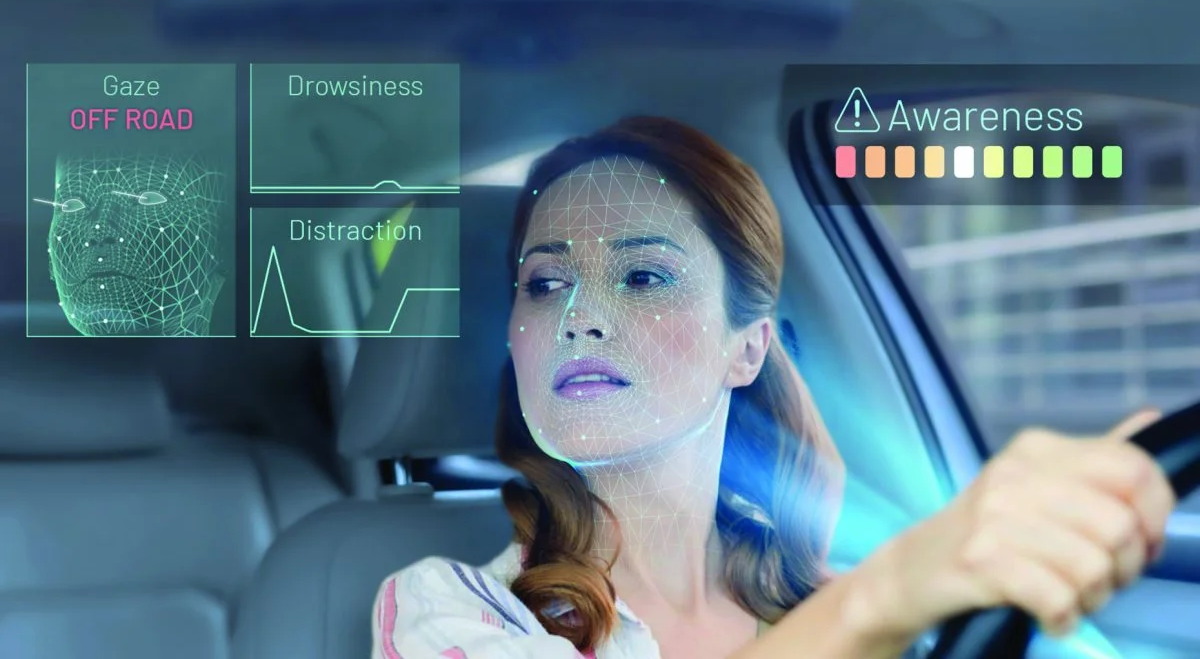
    Seeing Machines (LSE:SEE) has launched a new Physical AI Platform designed to extend its Human-Centred AI technology beyond transport safety and into the rapidly developing markets for humanoid robots, collaborative robotics and industrial automation.

    The platform gives machines a dynamic three-dimensional understanding of people, objects and their surrounding environment. By interpreting spatial relationships and human behaviour, the technology is intended to help robots interact with people more naturally while maintaining safety in shared environments.

    Rather than analysing people and objects as separate elements, Seeing Machines’ Physical AI technology processes them as components of a unified scene. This approach is designed to provide machines with greater contextual awareness and a better understanding of how people are likely to behave within changing surroundings.

    Such capabilities could be particularly important in complex and unpredictable environments including factories, warehouses, hospitals and public spaces, where robots increasingly need to work alongside people rather than within isolated or highly controlled areas.

    The launch represents a strategic expansion for Seeing Machines, which has built its technology around more than two decades of research into human behaviour and machine perception. The company is now applying that expertise to the emerging collaborative robotics market as advances in artificial intelligence and automation increase demand for machines capable of safely interpreting human activity.

    Physical AI could also broaden the company’s addressable market beyond its established transport safety operations. Potential applications span manufacturing, logistics, healthcare, aged care, mining and other areas of industrial automation, creating opportunities to diversify the group’s longer-term revenue base.

    Seeing Machines’ financial profile nevertheless remains mixed. Revenue growth has been particularly strong, but the company continues to report losses, a negative net margin and negative operating cash flow.

    Technical indicators provide a more supportive picture, with the shares trading above major moving averages and momentum ranging from neutral to positive. Traditional valuation measures remain difficult to apply while Seeing Machines is loss-making, resulting in a negative price-to-earnings ratio, while no dividend yield is available.

    More about Seeing Machines

    Seeing Machines is an Australian-headquartered technology company specialising in Human-Centred AI systems designed to help machines understand people and their surroundings, particularly in safety-critical environments.

    Drawing on more than 25 years of human factors research, the company develops vision-based monitoring technologies and Driver Monitoring Systems combining artificial intelligence algorithms, embedded processing and optics. These systems assess factors including human behaviour, attention and cognitive state across automotive, commercial transport, aviation, robotics and industrial automation applications.

    Its Safety AI portfolio includes Cabin AI, Cockpit AI and the new Physical AI platform, with the company’s technologies designed to improve real-time risk anticipation and support safer machine decision-making.

    Seeing Machines’ driver and occupant monitoring technology has been installed in more than eight million vehicles worldwide. The company works with major industry partners internationally and maintains operations across Australia, the U.S., Europe and Asia.

  • Telecom Plus starts five-year growth plan strongly and maintains FY27 guidance

    Telecom Plus starts five-year growth plan strongly and maintains FY27 guidance

    Telecom Plus (LSE:TEP) has reported an encouraging start to its new five-year growth strategy, with customer additions accelerating during the opening four months of FY27 and the company maintaining its full-year profit guidance.

    Annualised growth in multiservice customers is running slightly ahead of the group’s 10% target and at more than 2.5 times the pace recorded during the comparable period last year.

    Activity across the company’s Partner distribution network has also reached record levels. The number of active Partners has increased to approximately 4,900 per month, while the overall Partner network now exceeds 85,000 people. Telecom Plus is also expecting record attendance at its forthcoming sales conference, providing further evidence of increased engagement across its distribution channel.

    Cross-selling existing customers additional services represents another important element of the growth strategy. Around 17,000 additional core services have already been sold against the company’s full-year target of 50,000.

    Telecom Plus is simultaneously progressing the re-platforming of its insurance operations, which is expected to provide the infrastructure required for the planned introduction of motor insurance during the second half of the financial year.

    Investment in digitalisation is continuing alongside new marketing initiatives designed to increase brand awareness and customer acquisition. These include new advertising campaigns and partnerships such as Post Office Plus, which could provide additional routes for reaching potential customers.

    Following the strong start to the year, Telecom Plus reaffirmed its FY27 guidance for adjusted profit before tax of between £80 million and £90 million.

    The company is also maintaining its dividend while progressing a £40 million share buyback programme. These shareholder returns reflect management’s confidence in the group’s ability to generate sustainable earnings growth as its five-year strategy develops.

    From an investment perspective, Telecom Plus continues to demonstrate improving margins and strong return on equity, although rising leverage and fluctuations in cash flow provide some counterbalance. Valuation remains comparatively supportive, with a low price-to-earnings ratio and a high dividend yield.

    Technical indicators are considerably weaker, however, with the shares trading below all major moving averages and momentum indicators remaining negative.

    More about Telecom Plus

    Telecom Plus, which operates under the Utility Warehouse brand, is a UK-listed provider of essential household services offered primarily through subscription-style relationships.

    Its services include energy, broadband, mobile and insurance, which are delivered through an integrated platform and marketed through a nationwide network of local Partners. Utility Warehouse aims to provide customers with competitive pricing and the convenience of combining multiple household services into a single monthly bill.

    The business model is centred on recurring revenues, cross-selling additional services to existing households and maintaining high levels of long-term customer retention.

  • ECR Minerals secures up to A$3m funding for Creswick through Bold Gold joint venture

    ECR Minerals secures up to A$3m funding for Creswick through Bold Gold joint venture

    ECR Minerals (LSE:ECR) has entered into binding conditional farm-in and joint venture agreements with Australian explorer Bold Gold Resources that could provide up to A$3 million of exploration funding for the Creswick Gold Project in Victoria.

    Under the agreement, Bold Gold has a pathway to earn as much as an 80% interest in Creswick by financing exploration through a series of staged commitments. The arrangement brings additional capital, technical expertise and operating capacity to an asset ECR considers highly prospective but comparatively underexplored.

    Bold Gold is required to spend at least A$250,000 during the first year. It can subsequently earn a 51% interest in the project by investing A$1.25 million over three years.

    The Australian explorer can then increase its ownership to 80% by taking total expenditure to as much as A$3 million, subject to the renewal of certain licences. ECR will retain an interest in the project under the joint venture structure as well as potential exposure through royalties.

    The board views the transaction as strategically significant because it provides a route to accelerate exploration at Creswick without placing additional funding pressure on ECR’s own balance sheet.

    Bringing in a partner to finance and operate exploration at Creswick should also allow ECR to direct more of its capital and management resources towards its Queensland portfolio. The company is seeking to advance those assets towards production while continuing exploration across its broader portfolio of Australian gold projects.

    The company’s overall financial profile remains challenging, however. ECR currently generates no revenue and continues to report losses and cash outflows, indicating that future funding requirements remain an important consideration.

    Technical indicators are also weak, with the shares trading below all major moving averages. Some financial support comes from ECR’s debt-free balance sheet and improvements in losses and cash outflows compared with earlier periods, although these factors do not fully offset the company’s weaker underlying fundamentals.

    More about ECR Minerals

    ECR Minerals is a UK-listed gold exploration and development company with a portfolio of Australian assets spanning Victoria, Queensland, South Australia and Western Australia.

    Its projects include the Creswick Gold Project in Victoria’s established goldfields as well as the Maddens and Blue Mountain assets in northern Queensland. The company’s wider strategy combines exploration and project development with efforts to establish near-term production opportunities across its portfolio.