Author: Fiona Craig

  • Xtract Resources moves Amghas antimony project closer to plant commissioning

    Xtract Resources moves Amghas antimony project closer to plant commissioning

    Xtract Resources (LSE:XTR) has made further progress at its Amghas antimony project in north-west Morocco, appointing local mining and civil engineering contractors to undertake site preparation, improve mine access and develop supporting infrastructure. The appointments mark a transition from planning and test work towards physical development activities as the company prepares the project for initial production.

    Development is centred on a proposed gravity processing plant with capacity of approximately 70,000 tonnes per year. Current workstreams cover mine preparation and production readiness, construction of the gravity plant and metallurgical flotation testing aimed at refining the project’s processing strategy and potential recoveries.

    On-site activity has already included improvements to haul roads, while underground working areas have been cleaned, inspected and made safe ahead of future mining operations. These measures are intended to establish the infrastructure and operating conditions required to begin extracting and processing material once the development programme reaches the commissioning stage.

    Amghas already holds a mining licence, while the environmental permitting process required for plant operations remains under way. Xtract is continuing construction activities in parallel so that the processing facility can move rapidly towards commissioning once the necessary environmental approval has been secured.

    The project provides Xtract with exposure to antimony, a strategically important mineral used across a range of industrial and technology applications. Progressing Amghas towards production could allow the company to establish a position within developing critical mineral supply chains while generating value from its Moroccan asset portfolio.

    Xtract’s broader outlook remains constrained by weak operating performance and deteriorating cash flow, although its relatively low level of debt provides some balance sheet support. Technical indicators are more constructive, with the shares trading above key moving averages and MACD remaining positive. Conventional valuation measures are less supportive while the company remains loss-making, resulting in a negative price-to-earnings ratio, with no dividend yield available.

    More about Xtract Resources

    Xtract Resources is a mining and exploration company focused on advancing mineral assets through exploration, development and towards production. Its portfolio includes projects in Morocco and other jurisdictions, with increasing exposure to strategically important commodities such as antimony. The company aims to develop commercially viable resources while positioning its assets within growing global critical mineral supply chains.
  • Nichols expands health drinks portfolio with €75 million VITHIT acquisition

    Nichols expands health drinks portfolio with €75 million VITHIT acquisition

    Nichols plc (LSE:NICL) has acquired Dublin-based functional drinks company VITHIT for €75 million in cash, strengthening its exposure to the growing health and wellness drinks market. The transaction gives Nichols full ownership of the business on a debt-free, cash-free basis and adds an established low-calorie, low-sugar functional beverage brand to its existing portfolio.

    VITHIT has developed strong positions in the UK and Ireland with its range of vitamin-fortified drinks. The business generated revenue of €26.5 million in 2025 and recorded an operating margin of 15.8%. Its Dublin office will remain in place following the acquisition, while the existing management team will continue to support the business during a transition period as founder Gary Lavin steps down.

    Nichols expects the acquisition to be immediately earnings enhancing and is targeting annual synergies of more than €1 million. The group intends to use its established distribution network, customer relationships and international infrastructure to broaden VITHIT’s reach and accelerate the brand’s expansion into additional markets.

    The €75 million purchase price is being funded entirely from Nichols’ existing cash resources. Despite the investment, the group expects to retain a net cash position and has also established a new revolving credit facility to provide additional financial flexibility. Management expects the transaction to generate returns comfortably above the company’s cost of capital.

    The acquisition is projected to contribute positively to earnings per share and dividends from 2027, supporting Nichols’ wider capital allocation strategy and its focus on building a portfolio of differentiated soft drink brands. The company enters the transaction with strong financial foundations, including improved margins during 2025 and an essentially debt-free balance sheet, although weaker free cash flow conversion remains a consideration. Positive share price momentum and a reasonable valuation, alongside its dividend yield, provide further support to the broader outlook.

    More about Nichols

    Nichols plc is a UK-based diversified soft drinks group operating an asset-light business model across UK Packaged, International Packaged and Out of Home channels. Its portfolio is led by the Vimto brand and spans squash, flavoured carbonates, fruit drinks, energy beverages and flavoured water. Nichols also works with licensed brands including MyProtein, Levi Roots, ICEE and Sunkist, with its products sold across more than 60 countries and significant exposure to markets in the Middle East and Africa.

  • Thruvision secures £3 million airport security contract in South-East Asia

    Thruvision secures £3 million airport security contract in South-East Asia

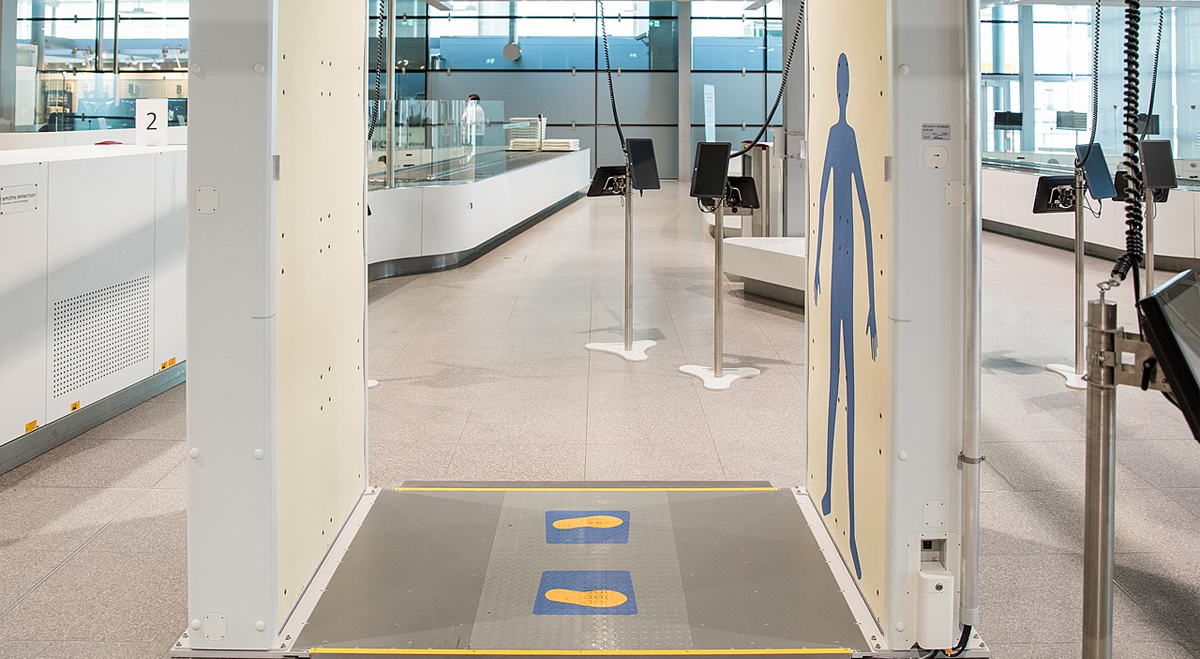
    Thruvision Group (LSE:THRU) has secured a contract valued at more than £3 million through its principal Asian partner for the deployment of high-throughput people-screening technology at several major airports in South-East Asia. The agreement represents the company’s largest deployment in the Asian market to date.

    The systems will primarily be used to screen aviation workers and strengthen measures designed to address insider threats while maintaining efficient movement through airport security operations. Thruvision’s technology is designed to identify concealed items without creating the bottlenecks associated with more conventional screening processes, making it suitable for locations handling large numbers of people.

    The latest award is Thruvision’s third Asian contract worth more than £1 million within the past 14 months, highlighting increasing commercial activity in the region. Delivery is scheduled for the second half of the company’s financial year ending 31 March 2027.

    Management views the contract as further evidence of increasing demand for technology capable of addressing insider-security risks within aviation and other sensitive environments. The award also supports Thruvision’s partner-led commercial strategy in Asia, where local relationships are being used to expand the company’s presence and compete for larger security programmes.

    The company nevertheless continues to face financial challenges, including persistent losses, significant pressure on gross margins and consistently negative operating and free cash flow. Low leverage provides some balance sheet support, but technical indicators remain weak, with the shares below key moving averages, MACD in negative territory and RSI at depressed levels. Traditional valuation measures offer limited support while earnings remain negative and no dividend yield is available.

    More about Thruvision Group plc

    Thruvision Group plc is a UK-based developer and manufacturer of walk-through security screening technology used by government and commercial customers in more than 30 countries. Its patented systems combine advanced imaging technology with AI-based detection algorithms to identify concealed metallic and non-metallic objects in real time. The technology is designed for high-throughput environments including airports, logistics facilities, events and other critical infrastructure locations.

  • Kendrick Resources identifies broad high-grade rare earth zones at Teufelskuppe

    Kendrick Resources identifies broad high-grade rare earth zones at Teufelskuppe

    Kendrick Resources (LSE:KEN) has reported further portable X-ray fluorescence drill results from its Teufelskuppe rare earths project in Namibia, identifying high-grade light rare earth oxide mineralisation across substantial widths in several diamond drill holes. The latest findings provide additional evidence of the scale and grade potential of the Teufelskuppe carbonatite complex.

    According to the company, the grades recorded to date position Teufelskuppe within the upper quartile of comparable carbonatite-hosted rare earth projects globally. Kendrick believes this strengthens the project’s potential to become a future source of neodymium and praseodymium for free-market economies, at a time when demand for critical rare earth elements continues to increase.

    The latest drilling encountered continuous mineralised packages measuring up to 36.75 metres, with light rare earth oxide grades reaching as high as 4.77 wt%. Multiple intersections returned grades above 2 wt%, while several drill holes finished within mineralisation, indicating that the identified zones remain open and could extend beyond the areas tested so far.

    Management believes the consistency and extent of the mineralisation support its assessment that the existing 14 million tonne surface resource represents only a portion of Teufelskuppe’s overall potential. Further drilling is intended to test the wider carbonatite system and establish whether a substantially larger rare earth resource can be defined.

    Kendrick is also progressing work towards JORC 2012 certification as part of its broader exploration programme. Expanding and formalising the resource could position Teufelskuppe to benefit from growing demand for rare earth materials used across electronics, renewable energy technologies, electric vehicles and defence applications.

    The company nevertheless remains at an early stage financially, with no revenue, continuing losses and negative cash flow, alongside a weakened balance sheet and negative equity. Technical indicators provide limited support due to mixed moving-average signals, while conventional valuation measures remain difficult to apply given negative earnings and the absence of dividend data.

    More about Kendrick Resources PLC

    Kendrick Resources PLC is a mineral exploration and development company focused on acquiring and advancing resource projects through exploration, technical studies and resource definition. Its strategy typically involves progressing projects towards production through joint ventures or asset transactions. The company’s portfolio includes rare earth and critical mineral interests in southern Africa, including projects in Namibia and Zambia.

  • Likewise Group acquires Corby distribution hub to expand UK flooring network

    Likewise Group acquires Corby distribution hub to expand UK flooring network

    Likewise Group plc (LSE:LIKE) has agreed to acquire the freehold of a new 60,000-square-foot high-bay distribution facility in Corby for £9.57 million, strengthening the infrastructure supporting its expanding UK flooring business. Completion of the acquisition is expected on 21 August 2026, with the new hub scheduled to become operational in January 2027.

    The Corby facility will provide additional storage, cutting and trunking capacity across the Likewise Floors Logistics Network. The investment forms part of the group’s wider strategy to increase operational scale, improve distribution capabilities and provide the capacity required to serve a growing customer base across the UK.

    The acquisition comes alongside continued positive trading momentum. Likewise reported that sales revenue increased 23.9% year-on-year during July, while like-for-like sales for the year to date were 18.3% ahead of the comparable period. Management also indicated that order intake and invoicing remained strong during the opening days of August.

    Likewise said continued backing from shareholders and its principal banking partners is providing the financial flexibility needed to pursue its expansion strategy. Increasing the scale of its logistics infrastructure is expected to strengthen the company’s position within the UK flooring distribution market while supporting its relationships with manufacturing partners, independent retailers and flooring contractors.

    The broader outlook is supported by improving cash generation and positive share price momentum, with the stock trading above key moving averages and MACD remaining positive. However, valuation represents a significant constraint due to a particularly high price-to-earnings multiple, while thin operating and net margins and slowing revenue growth remain factors that could limit financial performance.

    More about Likewise Group plc

    Likewise Group plc is a UK flooring distributor supplying floor coverings and related products through its Likewise Floors Logistics Network. The company primarily serves independent flooring retailers and contractors and works with manufacturing partners to provide nationwide distribution, product availability and customer service. Its growth strategy is focused on expanding logistics capacity, increasing market penetration and developing a larger presence within the UK flooring sector.

  • H-Power appoints Canaccord Genuity as joint broker to strengthen market engagement

    H-Power appoints Canaccord Genuity as joint broker to strengthen market engagement

    H-Power plc (LSE:HPOW) has appointed Canaccord Genuity as a joint corporate broker as the company strengthens its capital markets advisory network. Canaccord Genuity will work alongside existing brokers Peel Hunt and Zeus, providing H-Power with additional support as it develops its engagement with investors on the London Stock Exchange’s AIM Market.

    The expanded broking team comes as H-Power works towards the commercial rollout of its ammonia-based hydrogen production and fuel cell generator technologies. Strengthening its advisory relationships could support broader investor communication and access to capital as the company seeks to convert its technology portfolio and commercial pipeline into sustained revenue growth.

    H-Power is targeting industries where reducing carbon emissions remains particularly challenging, including industrial operations, transportation and off-grid power generation. Its technology combines decentralised ammonia cracking with hydrogen fuel cell generators, providing a potential alternative to conventional hydrogen supply infrastructure and diesel-powered generation.

    The company’s financial position nevertheless remains challenging. Weak revenue performance, persistently negative margins and continued cash consumption indicate an ongoing requirement for external funding as commercialisation progresses. Technical indicators also remain under pressure, with the shares trading below key moving averages and MACD in negative territory. H-Power’s relatively low level of debt provides some balance sheet support, although traditional valuation measures remain difficult to apply while earnings are negative and no dividend yield is available.

    More about H-Power plc

    H-Power plc, formerly AFC Energy, is a UK-based developer of ammonia-powered low-carbon hydrogen production and hydrogen-to-power technologies. Its decentralised ammonia cracker and fuel cell generator systems are designed to provide scalable hydrogen and clean off-grid power for industrial, transport and power generation applications.

    The company’s modular ammonia cracker technology can produce approximately 0.5 to 4 tonnes of hydrogen per day at the point of use, while its 30 kW and 200 kW fuel cell generators are designed as alternatives to diesel generation in temporary and off-grid power applications. Headquartered in Dunsfold, Surrey and listed on AIM, H-Power is focused on commercialising its core technologies and converting its opportunity pipeline into contracted orders and recurring revenue.

  • ImmuPharma selects Kymos to support Kapiglucagon diabetes development programme

    ImmuPharma selects Kymos to support Kapiglucagon diabetes development programme

    ImmuPharma (LSE:IMM) has appointed Kymos Group as its bioanalytical contract research partner for the Kapiglucagon development programme following a competitive tender process. The appointment represents another step in advancing the drug candidate through its non-clinical and early clinical development stages.

    The collaboration adds to ImmuPharma’s existing development partnerships, which include Thermo Fisher for chemistry, manufacturing and controls activities and Bachem for active pharmaceutical ingredient manufacturing. Together, these relationships form part of a streamlined development strategy for Kapiglucagon, with the company also assessing the potential use of the 505(b)(2) regulatory pathway in the US to shorten the route towards commercialisation.

    Kapiglucagon has been developed to address one of the limitations of native glucagon: its instability in aqueous formulations. ImmuPharma’s candidate is a water-soluble glucagon prodrug designed to be compatible with pumps and suitable for continuous delivery as part of dual-hormone artificial pancreas systems.

    The technology could potentially support improved glucose management for people with Type 1 diabetes by allowing insulin and glucagon to be administered through advanced automated delivery systems. If successfully developed, this approach could help improve glucose control while reducing the day-to-day burden of managing the condition.

    Backed by recent funding and an expanding package of preclinical and CMC data, ImmuPharma intends to pursue regulatory interactions and targeted clinical studies to progress Kapiglucagon. The programme represents a potentially important addition to the company’s pipeline as it seeks exposure to the emerging market for next-generation diabetes management technologies.

    However, ImmuPharma’s financial position remains a key consideration, with the company generating no revenue and continuing to report losses and cash consumption, alongside a relatively fragile equity position. Low debt provides some balance sheet support, while technical indicators remain moderately negative due to a weaker longer-term share price trend and bearish MACD. Traditional valuation measures remain of limited relevance while the company remains loss-making.

    More about ImmuPharma

    ImmuPharma is a UK-listed specialty biopharmaceutical company focused on the discovery and development of peptide-based therapeutics. Its pipeline covers potential treatments for autoimmune diseases and anti-infective indications and includes its lead P140 programme alongside Kapiglucagon, a proprietary glucagon prodrug being developed for Type 1 diabetes and advanced artificial pancreas systems.

  • Cadence Minerals moves Azteca plant refurbishment closer to completion at Amapá

    Cadence Minerals moves Azteca plant refurbishment closer to completion at Amapá

    Cadence Minerals (LSE:KDNC) has reported further progress with the refurbishment of the Azteca processing plant at the Amapá Iron Ore Project in Brazil, with weighted physical completion increasing from 77% to 87%. Work remains on schedule to meet the targeted completion date of 31 August 2026.

    Several major components of the plant have now been completed, including the hopper and feed system, transfer conveyor, screen and process tank. Electrical installation has reached 69%, while the outstanding refurbishment programme is primarily focused on the magnetic separation circuit, piping and completion of the remaining electrical connections. Once these activities are finished, the plant will move towards integrated commissioning.

    Commercial production and shipments from Azteca will be dependent on the successful completion of commissioning and receipt of the required operating licence. The licensing process is progressing alongside the refurbishment programme, with continued engagement taking place with the relevant state environmental authority.

    Azteca is planned as the first production facility within the wider Amapá redevelopment strategy. The plant is expected to process existing tailings and produce approximately 380,000 tonnes per year of iron ore concentrate grading around 65% Fe. This initial operation is intended to establish an early source of cash flow that could contribute towards the development of the broader project.

    The wider Amapá project is supported by a substantial JORC-compliant mineral resource and a pre-feasibility study outlining the potential economics of restoring the integrated mining operation. However, Cadence continues to face financial constraints, including the absence of revenue during 2025, ongoing losses and persistent cash consumption, which leave the company dependent on external funding despite relatively low debt. Technical indicators also remain subdued, with bearish momentum and the shares trading below important short-term moving averages.

    More about Cadence Minerals

    Cadence Minerals is a London-listed mining investment company focused on advancing mineral resource projects, with particular exposure to iron ore development in Brazil. Its principal asset is a 36.2% interest in the Amapá Iron Ore Project, an integrated mining operation with existing mine, railway, port and beneficiation infrastructure. The longer-term development strategy is focused on producing high-grade iron ore concentrate suitable for the direct reduction market.

  • Angus Energy steps up debt repayments following financial restructuring

    Angus Energy steps up debt repayments following financial restructuring

    Angus Energy (LSE:ANGS) has accelerated the reduction of its borrowings following its recent financial restructuring, completing its first cash sweep and directing substantial funds towards outstanding liabilities. The company has fully repaid a £1.95 million overriding royalty interest (ORRI) obligation while also making a £1.996 million prepayment against its senior debt facility with Trafigura.

    Since late June, Angus has repaid a total of £5.241 million of debt, reducing the outstanding balance of the Trafigura facility to approximately £22.7 million. The rapid reduction in borrowings represents a significant step in the company’s efforts to strengthen its balance sheet and reduce its financing burden.

    Following the elimination of the ORRI liability, all proceeds generated through future cash sweeps will be allocated exclusively to further repayments of the Trafigura senior debt facility. This simplifies the company’s deleveraging strategy and could allow Angus to reduce its outstanding borrowings more quickly if operational cash generation remains strong.

    Management said the pace of repayments demonstrates the cash-generating capability of the business while allowing the company to continue investing in operational growth. Reducing debt alongside investment in its producing assets is intended to lower financing costs over time and improve the potential for longer-term shareholder value creation.

    Despite the progress on deleveraging, the company’s outlook continues to face challenges from negative free cash flow and inconsistent cash conversion. The technical picture also remains subdued, with the share price below longer-term moving averages. Improved reported profitability during 2025 and a more stable balance sheet provide some support, although declining revenue and continued earnings volatility remain factors to watch.

    More about Angus Energy

    Angus Energy is an AIM-quoted independent oil and gas company focused on onshore production in the UK. The company owns a 100% interest in the Saltfleetby Gas Field and majority interests in the Brockham and Lidsey oil fields, alongside a 25% interest in the Balcombe licence. Angus operates all of the assets in which it holds an interest and is a leading producer of onshore gas in the UK.

  • Fulcrum Metals increases Terra North equity exposure under revised uranium agreement

    Fulcrum Metals increases Terra North equity exposure under revised uranium agreement

    Fulcrum Metals (LSE:FMET) has revised its option agreement relating to Terra North Resources’ Saskatchewan uranium portfolio, securing an additional C$560,000 of equity through the issue of 5.6 million Terra North shares. The shares replace part of the consideration originally due on the second anniversary of the agreement and increase Fulcrum’s exposure to the future performance of the uranium assets.

    The amended structure follows previous cash and equity payments made under the agreement and shifts a portion of the outstanding consideration into deferred cash payments and future share issues. As a result, Fulcrum retains the potential to participate in the value created from the Saskatchewan portfolio while altering the timing and composition of the remaining payments.

    Under the revised terms, Fulcrum remains entitled to potential consideration comprising C$225,000 in cash and C$1.9 million in Terra North shares. Terra North must also complete a minimum exploration expenditure commitment of C$3.25 million in order to exercise its option over the claims.

    Should the option ultimately be exercised, Fulcrum will retain a 1% net smelter return royalty over the relevant properties, providing continued economic exposure to any future development or production from the assets. The company could also benefit from Terra North’s proposed public listing, which has the potential to improve both the liquidity and market valuation of Fulcrum’s equity interest.

    The arrangement adds to Fulcrum’s existing equity exposure to Terra and Terra North while allowing third-party capital to fund exploration of the Saskatchewan uranium portfolio. This structure enables the company to maintain potential upside from the assets while concentrating its own resources on its core technology-led mine tailings strategy in Canada.

    More about Fulcrum Metals Plc

    Fulcrum Metals plc is an AIM-listed, technology-led natural resources company focused on recovering precious metals from mine tailings in Canada. Its strategy incorporates cyanide-free leaching technology developed by Extrakt Process Solutions, with key projects including the Teck-Hughes and Sylvanite tailings assets in Ontario. Fulcrum also retains interests in mineral exploration properties across Ontario and Saskatchewan and holds exclusivity over Extrakt’s technology within several major historic Canadian gold districts.