Author: Fiona Craig

  • Entain Reviews Strategic Options for Central and Eastern Europe Joint Venture (ENT)

    Entain Reviews Strategic Options for Central and Eastern Europe Joint Venture (ENT)

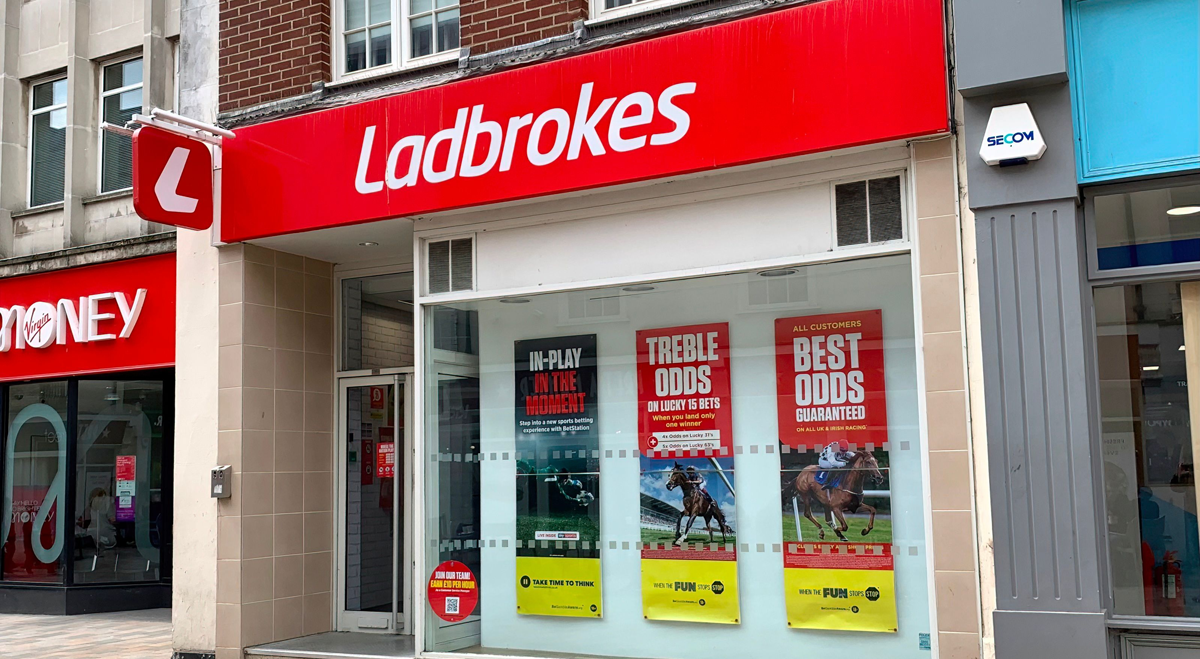
    Entain (LSE:ENT), the owner of Ladbrokes and Coral, is reportedly evaluating strategic alternatives for its Central and Eastern Europe joint venture, including the possibility of a sale, according to people familiar with the matter. One option under consideration would involve the company selling its stake to its existing partner, Czech investment group EMMA Capital, although discussions are understood to be at an early stage and no agreement has been reached.

    The review comes as Entain seeks to manage the impact of significant increases in UK online gambling taxes. The company has been exploring ways to improve efficiency, strengthen its balance sheet and offset higher operating costs arising from changes to the UK regulatory environment. Sources indicated that any proceeds from a potential transaction could be used to reduce debt.

    Entain CEE was established in 2022 following the acquisition of Croatian sportsbook operator SuperSport and subsequently expanded in 2023 through the purchase of Polish betting company STS for approximately £750 million. The venture remains majority owned by Entain and includes contractual options that could ultimately allow either partner to alter the ownership structure after the third anniversary of the original transaction.

    The business has delivered solid financial performance, generating earnings before interest, tax, depreciation and amortisation of £183.7 million in 2025, compared with £170 million in the previous year. At group level, Entain reported better-than-expected annual profit of £1.16 billion, while adjusted net debt stood at £3.64 billion at the end of 2025.

    Management has warned that recent UK gambling tax increases are expected to add around £200 million in annual costs. The company aims to offset approximately 25% of that impact during the current year and more than 50% by 2027 through cost-saving initiatives and operational efficiencies. Following the government’s tax announcement, Entain also recorded a non-cash impairment charge of £488 million against its UK operations, contributing to a loss after tax of £680.5 million for the year ended December.

    The company’s outlook remains supported by the strength of its international operations and established market positions, although elevated debt levels, regulatory pressures and rising taxation continue to present challenges. Any transaction involving the Central and Eastern Europe business could form part of a broader effort to optimise the group’s portfolio and improve financial flexibility.

    More About Entain plc

    Entain plc is a global sports betting and gaming operator with a portfolio of well-known brands including Ladbrokes, Coral, bwin, Sportingbet and part ownership of BetMGM in the United States. The company operates across regulated markets worldwide, offering sports wagering, online gaming and retail betting services.

    Through a combination of organic growth, acquisitions and strategic partnerships, Entain has built a diversified international presence. Its strategy focuses on expanding in regulated markets, investing in technology and enhancing shareholder value through disciplined capital allocation and operational efficiency.
  • Atome Continues Discussions With Paraguayan Authorities on Villeta Project Development (ATOM)

    Atome Continues Discussions With Paraguayan Authorities on Villeta Project Development (ATOM)

    Atome PLC (LSE:ATOM) has confirmed that negotiations relating to its Villeta project in Paraguay remain ongoing, following recent volatility in the company’s share price. The group said it continues to engage with both the Government of Paraguay and ANDE, the country’s state-owned electricity provider, as discussions progress.

    Management stated that talks with key stakeholders are continuing and that the market will be updated once a definitive outcome has been reached. The announcement indicates that no final agreements have yet been concluded on matters central to the development of the Villeta project.

    Investors remain focused on the progress of these negotiations, as the outcome is expected to play an important role in shaping the project’s future development. Any agreement with Paraguayan authorities and ANDE could have a significant impact on Atome’s growth plans, funding strategy and long-term commercial prospects in the region.

    The company’s outlook continues to be constrained by its pre-revenue status, ongoing losses and negative free cash flow, all of which contribute to continuing funding requirements. These challenges are partially offset by relatively strong technical indicators, with the share price remaining above key moving averages and momentum measures showing positive trends. Valuation support remains limited due to negative earnings and the absence of a stated dividend yield.

    More About Atome PLC

    Atome PLC is a London-listed energy company focused on developing large-scale green energy projects in Latin America. Its flagship development is the Villeta project in Paraguay, which is being advanced in collaboration with local stakeholders and government-linked organisations.

    The company’s business model is centred on securing long-term access to renewable electricity supplies, making its relationship with Paraguay’s state-owned electricity provider, ANDE, a key component of its strategy. Through projects such as Villeta, Atome aims to establish a platform for the production of green energy products while supporting the transition toward lower-carbon industrial and energy systems.

  • Union Jack Oil to Abandon Oklahoma Crossroads Well After Non-Commercial Test Results (UJO)

    Union Jack Oil to Abandon Oklahoma Crossroads Well After Non-Commercial Test Results (UJO)

    Union Jack Oil (LSE:UJO) has reported that the Crossroads well in Garvin County, Oklahoma, where it holds a 43% working interest, has been deemed non-commercial following testing operations. The update follows the completion of evaluation work on the well, which had encountered hydrocarbon shows across multiple geological formations.

    During drilling and testing activities, hydrocarbons were identified in several intervals ranging from the Hoxbar formation to the Basal McLish section. Four zones considered to have production potential were perforated and subjected to testing in an effort to assess their commercial viability.

    Despite these encouraging indications, subsequent analysis and testing concluded that the well does not support commercial development. As a result, Union Jack and its partners intend to plug and abandon the well in due course. The outcome represents a disappointment for the company’s US onshore exploration programme and removes the prospect of near-term production, revenue or cash flow from the Crossroads asset.

    The company’s outlook remains weighed down by weak financial performance, including a significant loss reported in 2025, negative operating cash flow and continued free cash flow deficits. Technical indicators also remain under pressure, with the shares trading below key short-term moving averages and momentum measures signalling weakness. A debt-free balance sheet provides some support, although valuation metrics remain challenged by negative earnings and the absence of dividend guidance.

    More About Union Jack Oil plc

    Union Jack Oil plc is a UK-based onshore oil and gas company with interests in production, development and exploration assets across both the United Kingdom and the United States. Listed on AIM under the ticker UJO, the company focuses primarily on conventional hydrocarbon opportunities and seeks to build value through a combination of exploration success, production growth and strategic investments.

    Its portfolio includes interests in a range of oil and gas projects, with exposure to both established producing assets and higher-risk exploration prospects. The company continues to evaluate opportunities that can deliver long-term growth while maintaining a disciplined approach to capital allocation and operational development.

  • Mobico Revises German Rail Agreements to Reduce Risk and Improve Earnings Visibility (MCG)

    Mobico Revises German Rail Agreements to Reduce Risk and Improve Earnings Visibility (MCG)

    Mobico Group (LSE:MCG) has agreed updated terms with five public transport authorities across North Rhine-Westphalia and neighbouring regions, marking a significant restructuring of its German rail portfolio. The changes are designed to improve the sustainability of the company’s rail operations and reduce exposure to contract structures that have weighed on profitability.

    Under the revised arrangements, the Rhein-Münsterland Express contract, which includes the RE 7 and RB 48 routes, will transition to a gross contract model from the beginning of 2026. This change removes revenue risk from the operator and extends the contract by an additional two years through to 2032, providing greater earnings certainty and longer-term operational visibility.

    Mobico has also agreed amendments to its Rhein-Ruhr-Express contracts, which currently cover several important regional rail services but have been operating at a loss. These agreements will now conclude in 2030, three years earlier than originally planned, enabling a coordinated retendering process that aligns with the regional transport strategy of North Rhine-Westphalia.

    Management believes the revised framework will help stabilise financial performance within its German rail business by aligning contract terms more closely with industry standards and reducing exposure to underperforming routes. The changes form part of a broader effort to reposition the company’s operations in Germany and improve long-term profitability.

    The company’s outlook continues to be affected by weak financial fundamentals, including losses, negative equity and inconsistent free cash flow generation. However, improving technical indicators and a cautiously positive earnings outlook, supported by cost-saving initiatives and a focus on cash generation and deleveraging, provide some offsetting support. Valuation metrics remain constrained by the company’s loss-making position.

    More About Mobico Group plc

    Mobico Group plc is an international public transport operator with a significant presence in the German regional rail market. The company provides passenger transport services under long-term contracts with public transport authorities and operates a number of key rail routes across North Rhine-Westphalia and surrounding regions.

    Its business model is centred on delivering reliable public transport services through franchise and contract-based arrangements. Mobico remains focused on improving operational performance, strengthening profitability and adapting its portfolio to evolving market and regulatory conditions across Europe’s transportation sector.

  • Record Grows Assets Under Management While Expanding Private Markets Strategy (REC)

    Record Grows Assets Under Management While Expanding Private Markets Strategy (REC)

    Record plc (LSE:REC) reported a 14% increase in assets under management to $114.6 billion for the year ended 31 March 2026, supported by new client mandates and favourable market conditions. Despite the growth in managed assets, revenue declined 4% to £40.1 million, while profit after tax fell 23% to £7.0 million as lower performance fee income and a return to a more normalised tax rate weighed on earnings.

    The company reduced its final dividend to 1.45 pence per share, although it continues to maintain a relatively high payout ratio. During the year, Record also strengthened its leadership team and reported encouraging growth within its Solutions for Asset Managers division, alongside continued development of its private markets capabilities.

    Management identified private markets, particularly infrastructure equity strategies, as a major area of future growth. The company believes these businesses have the potential to deliver higher margins and more diversified revenue streams compared with its traditional currency hedging operations. As part of this strategy, Record is investing in the expansion of Record Asset Management GmbH and the development of a broader private markets platform.

    The board said capital is being directed toward initiatives that can create scalable, long-term revenue opportunities, even if earnings become less predictable in the near term. Management also highlighted a strong pipeline of prospective business and mandates nearing completion, which it expects to support current market expectations for FY27. The company continues to focus on risk management, absolute return strategies and private markets expansion as it seeks to evolve into a more diversified alternative asset manager.

    The company’s outlook is supported by a strong valuation profile, solid financial stability and an attractive dividend yield. Strategic investments and corporate developments provide additional support for long-term growth prospects, although technical indicators continue to suggest a weaker near-term market trend.

    More About Record plc

    Record plc is a specialist asset management company that originally built its business around currency risk management and customised hedging solutions for institutional investors. Over more than four decades, the company has expanded its capabilities beyond foreign exchange management into areas including FX alpha strategies and absolute return investment products.

    More recently, Record has focused on broadening its offering into private markets, with investments spanning infrastructure equity and sustainable finance opportunities in emerging markets. The group’s strategy is centred on creating higher-margin, scalable revenue streams while maintaining its expertise in risk management and institutional investment solutions.

  • Phoenix Copper Restates Prior Accounts Following Investigation as Empire Mine Development Progresses (PXC)

    Phoenix Copper Restates Prior Accounts Following Investigation as Empire Mine Development Progresses (PXC)

    Phoenix Copper (LSE:PXC) has reported its audited results for 2025, highlighting continued investment in its flagship Empire Mine project in Idaho while outlining measures taken to strengthen corporate governance following an internal investigation into unauthorised payments.

    For the year, the company reported a reduced loss of $4.40 million and increased its investment in the Empire Mine to $45.32 million. Net assets stood at $38.27 million, while additional funding was secured through an equity raise and a $2 million unsecured convertible loan facility. Phoenix also restated its prior-year financial statements to reverse $1.75 million of unauthorised payments identified during the investigation.

    Following the discovery, the company implemented enhanced financial controls and governance procedures after the departure of its former executive chairman and chief financial officer. Management said efforts are ongoing to recover the misappropriated funds and emphasised its commitment to maintaining stronger oversight and accountability across the business.

    Operationally, Phoenix confirmed that the mineral resources and reserves associated with the Empire Mine remain unaffected. The company continues to advance engineering studies, environmental baseline programmes and reclamation work as it moves toward the permitting and development stages of the project. Management also noted that current copper, gold and silver prices remain significantly above the assumptions used in the 2024 pre-feasibility study, potentially improving the project’s economic outlook and future cash generation potential should market conditions remain favourable.

    The company’s outlook continues to be weighed down by weak financial performance, including the absence of revenue, ongoing losses and increasing cash outflows, all of which contribute to funding and dilution risks. Technical indicators present a mixed picture but remain broadly subdued, with the share price trading below key moving averages. Valuation metrics offer limited support due to negative earnings and the absence of a dividend.

    More About Phoenix Copper Limited

    Phoenix Copper Limited is an AIM-listed mining and exploration company focused on the development of base and precious metals assets in the United States. Its principal asset is the Empire Mine in Idaho, where the company is working to advance a copper, gold and silver project toward construction and eventual production.

    The group’s strategy centres on progressing projects through engineering, permitting and development milestones while seeking to benefit from long-term demand for industrial and precious metals. Phoenix Copper’s portfolio provides exposure to copper, gold and silver markets, with the company positioning itself to capitalise on favourable commodity price conditions as its projects advance.

  • Synthomer Agrees Sale of Acrylate Monomers Business to Advance Speciality Chemicals Strategy (SYNT)

    Synthomer Agrees Sale of Acrylate Monomers Business to Advance Speciality Chemicals Strategy (SYNT)

    Synthomer (LSE:SYNT) has reached an agreement to sell Synthomer a.s., its Acrylate Monomers operation in the Czech Republic, to German investment firm Mutares SE & Co. KGaA. The transaction marks the group’s exit from its final upstream base chemicals business and represents another step in its strategy of focusing on higher-value speciality chemicals markets.

    The business being sold is a significant European producer of acrylic acid and acrylate monomers and employs approximately 300 people at its Sokolov facility. Following completion of the transaction, the operation will continue supplying acrylic raw materials and dispersions to Synthomer under the new ownership structure, helping to maintain continuity across the company’s downstream manufacturing activities.

    The divested business has operated in cyclical and capital-intensive markets, requiring average annual capital expenditure of around €5 million. In 2025, it generated €68 million in external revenue while reporting an adjusted EBITDA loss of €10 million, before returning to break-even performance during the early part of 2026. The transaction does not include an upfront cash payment. Instead, consideration will be linked to future performance, with Synthomer eligible to receive up to €12 million through a shared cash generation mechanism over a three-year period.

    Management expects the disposal to complete by the end of the third quarter of 2026 and believes the move will strengthen profitability, improve cash generation and further align the group with higher-margin speciality chemical markets.

    The company’s outlook continues to be weighed down by a history of losses and inconsistent revenue performance, despite improvements in leverage and a recovery in cash flow during 2025. Technical indicators remain one of the stronger aspects of the investment case, with the shares trading above major moving averages and momentum signals remaining positive. However, overbought conditions suggest some risk of a short-term pullback. Valuation metrics remain under pressure due to the company’s negative price-to-earnings ratio.

    More About Synthomer plc

    Synthomer plc is a London-headquartered speciality chemicals manufacturer supplying high-performance polymers and ingredients to customers across a range of industrial and consumer markets. The company serves sectors including coatings, construction, adhesives, healthcare and protection products.

    Employing approximately 3,800 people, Synthomer operates five innovation centres and 29 manufacturing facilities worldwide, supplying more than 6,000 customers globally. The group generated £1.7 billion of continuing revenue in 2025 and organises its operations across three divisions: Coatings & Construction Solutions, Adhesive Solutions, and Health & Protection and Performance Materials.

    Its products are used in applications ranging from architectural coatings and waterproofing systems to packaging, medical gloves and industrial foams. Synthomer’s strategy focuses on expanding its presence in higher-growth and sustainability-linked markets, supported by innovation, proprietary technologies and climate objectives aligned with the Paris Agreement.

  • Cordiant Digital Infrastructure Announces Second Interim Dividend for 2026 (CORD)

    Cordiant Digital Infrastructure Announces Second Interim Dividend for 2026 (CORD)

    Cordiant Digital Infrastructure Limited (LSE:CORD) has declared a second interim dividend of 2.275 pence per ordinary share for the six months ended 31 March 2026, reinforcing its commitment to delivering regular shareholder returns from its portfolio of digital infrastructure assets.

    The dividend will go ex-dividend on 2 July 2026, with shareholders on the register as of 3 July 2026 eligible to receive the payment. The distribution is scheduled to be paid on 30 July 2026. The announcement reflects the company’s strategy of generating sustainable income from essential digital infrastructure assets across Europe and North America.

    As one of the largest specialist digital infrastructure investors and operators listed in London, Cordiant focuses on assets including data centres, fibre networks and telecommunications towers. Its portfolio has been built to generate resilient, long-term cash flows, with many revenues benefiting from inflation-linked characteristics that support income visibility and growth potential.

    The company’s outlook remains broadly positive, supported by favourable technical indicators and attractive valuation metrics. Strategic corporate developments and continued confidence in the business model further strengthen the investment case. These positives are partially offset by cash flow challenges, which continue to place some pressure on the overall financial assessment.

    More About Cordiant Digital Infrastructure Limited

    Cordiant Digital Infrastructure Limited is a London-listed investor, owner and operator of digital infrastructure assets. The company focuses on acquiring and developing critical communications infrastructure, including data centres, fibre-optic networks, telecommunications towers and broadcast assets across Europe and North America.

    The group has raised £795 million in equity capital alongside a €375 million debt facility to support its growth strategy. Through its Buy, Build & Grow approach, Cordiant has assembled a portfolio of six infrastructure businesses designed to provide stable, often index-linked income streams while benefiting from the long-term growth in global demand for digital connectivity and data services.

  • Marks Electrical Preserves Margins and Cash Position While Prioritising Direct Sales Channels (MKS)

    Marks Electrical Preserves Margins and Cash Position While Prioritising Direct Sales Channels (MKS)

    Marks Electrical Group (LSE:MKS), the UK online retailer specialising in domestic appliances and consumer electronics, reported lower revenue for the year ended 31 March 2026 after deliberately reducing its exposure to marketplace sales channels in favour of driving business through its own website and telesales operations. Underlying revenue declined 7.5% to £108.4 million as the company focused on strengthening the quality and profitability of its sales mix.

    The shift in strategy weighed on earnings, with adjusted EBITDA falling to £2.5 million and the group reporting a small statutory loss per share. As a result, the board decided not to recommend a final dividend while management concentrates on restoring profitability and supporting future growth initiatives.

    Despite the decline in revenue, Marks Electrical maintained broadly stable gross margins and retained a 2.6% share of the UK major domestic appliances market. The business ended the financial year with net cash of £4.4 million, reflecting continued balance sheet strength. Management highlighted a stronger performance during the second half of the year, supported by peak seasonal trading, cost-saving measures and operational efficiencies, alongside the implementation of a new Microsoft Dynamics 365 enterprise resource planning system.

    Following the year-end, the company concluded an investigation by the Competition and Markets Authority, agreeing to pay a reduced financial penalty of £0.7 million together with approximately £0.6 million of consumer redress. These costs will be funded from existing cash resources and treated as exceptional items. Looking ahead to FY27, management said trading remains in line with expectations, with encouraging signs emerging in the major appliances and television categories. However, the company remains cautious regarding sales growth and margin expansion due to subdued consumer confidence and ongoing macroeconomic uncertainty in the UK.

    The company’s outlook is supported by strong cash generation, a net cash position and low leverage, although these strengths are partly offset by weaker technical indicators and valuation concerns following recent losses. Management’s confidence in operational improvements and longer-term growth opportunities provides some support, but market momentum and valuation metrics continue to weigh on the overall assessment.

    More About Marks Electrical Group plc

    Marks Electrical Group plc is a technology-driven online retailer of major domestic appliances and consumer electronics in the UK. Founded in Leicester in 1987, the company offers more than 4,500 products from over 50 leading brands through its e-commerce platform.

    The group operates a vertically integrated business model that includes its own nationwide delivery, installation and recycling network, enabling it to serve more than 90% of the UK population. Marks Electrical focuses on providing next-day delivery, competitive pricing and high levels of customer service, supported by strong brand partnerships and a growing base of repeat customers.

  • Trellus Health Obtains $260,000 Loan From Mount Sinai as Restructuring Efforts Continue (TRLS)

    Trellus Health Obtains $260,000 Loan From Mount Sinai as Restructuring Efforts Continue (TRLS)

    Trellus Health (LSE:TRLS) has secured an unsecured loan of $260,000 from Mount Sinai Health System to provide additional liquidity while the company continues to address financial challenges and evaluate strategic alternatives. The financing is expected to extend the group’s available cash resources until 31 July 2026.

    Under the terms of the agreement, the loan will accrue interest at an annual rate of 8% beginning in December 2026. Repayment is due by June 2027, although the balance would become payable within 90 days should the company complete a sale of its U.S. subsidiary, Trellus Health Inc.

    The transaction has been classified as a related party arrangement and was reviewed by the company’s independent directors, who concluded that the terms are fair and reasonable following consultation with Trellus Health’s nominated adviser. The additional funding arrives as the board continues to explore restructuring initiatives and strategic options aimed at strengthening the company’s financial position.

    Trading in Trellus Health shares remains suspended on AIM while the company seeks greater clarity regarding its financial outlook. Management is assessing a range of potential outcomes, including restructuring measures and possible corporate transactions, such as the sale of its U.S. operations, in an effort to preserve value for stakeholders.

    The company’s outlook continues to be weighed down by weak financial performance, including substantial ongoing losses, negative free cash flow and declining equity. The absence of debt provides some balance-sheet support, while technical indicators remain one of the few positive factors, with the shares previously demonstrating strong momentum above major moving averages. Valuation metrics remain constrained by the company’s loss-making position and lack of a dividend.

    More About Trellus Health plc

    Trellus Health plc is a healthcare technology company focused on delivering value-based digital care solutions for individuals living with complex chronic conditions. The company’s approach combines behavioural science, technology and personalised support to help patients improve health outcomes and reduce the long-term costs associated with chronic disease management.

    Its flagship platform, Trellus Elevate, incorporates a proprietary resilience-based methodology, data analytics tools and expert coaching to support patients with gastrointestinal conditions such as inflammatory bowel disease. The company also offers Trellus TrialSet, a solution designed to support pharmaceutical companies across clinical development programmes and commercialisation initiatives.