Author: Fiona Craig

  • FTSE 100 Falls Ahead of Bank of England Decision as Oil Prices Retreat

    FTSE 100 Falls Ahead of Bank of England Decision as Oil Prices Retreat

    UK equities moved lower on Thursday as investors awaited the latest interest rate decision from the Bank of England, while a sharp decline in crude oil prices weighed heavily on energy stocks.

    The FTSE 100 was down 0.54% in early trading, lagging broader European markets. By contrast, Germany’s DAX gained 0.46% and France’s CAC 40 rose 0.25% as investors reacted positively to signs of improving stability in the Middle East.

    Labour Market Remains Resilient

    Fresh economic data painted a mixed picture of the UK labour market ahead of the central bank’s policy announcement.

    Average weekly earnings excluding bonuses remained at an annual growth rate of 3.4% in the three months to April, exceeding economists’ expectations of 3.2%. Meanwhile, the unemployment rate unexpectedly fell to 4.9% from 5.0%.

    Total earnings including bonuses increased 4.4% year-on-year, suggesting wage pressures remain relatively firm despite broader signs of economic moderation.

    However, other indicators pointed to some cooling in employment conditions. Job vacancies fell by 19,000 to 707,000 during the three months to May, marking the lowest level since early 2021, while the claimant count increased during May.

    The figures are likely to leave policymakers balancing concerns about persistent wage growth against evidence of softening labour demand.

    Middle East Agreement Pressures Oil Prices

    Market sentiment was also influenced by developments in the Middle East after the United States and Iran agreed a 14-point framework aimed at restoring Iranian oil exports and reopening the Strait of Hormuz.

    The agreement outlines a pathway toward a broader deal within 60 days, with implementation discussions expected to begin in Switzerland on Friday.

    Investors broadly welcomed the development, viewing it as a potential step toward improving energy security and reducing risks to global trade and shipping routes.

    The prospect of additional oil supplies returning to international markets pushed energy prices lower.

    Brent crude fell 1.5% to $78.35 a barrel, while U.S. benchmark WTI crude declined 2.0% to $75.28 a barrel. Gold moved in the opposite direction, with spot prices rising 1.1% to $4,305.84 per ounce.

    Informa Reaffirms Growth Outlook

    Among individual stocks, Informa (LSE:INF) traded higher after reiterating its full-year guidance and expressing confidence in stronger growth prospects for 2027.

    The events and academic publishing group reported underlying revenue growth of 6.4% during the first five months of 2026, supported by continued strength in its live events business and a recovery from disruption linked to the Iran conflict.

    Management maintained its expectation for double-digit growth in adjusted earnings per share this year.

    Tesco Maintains Guidance Despite Softer Sales Growth

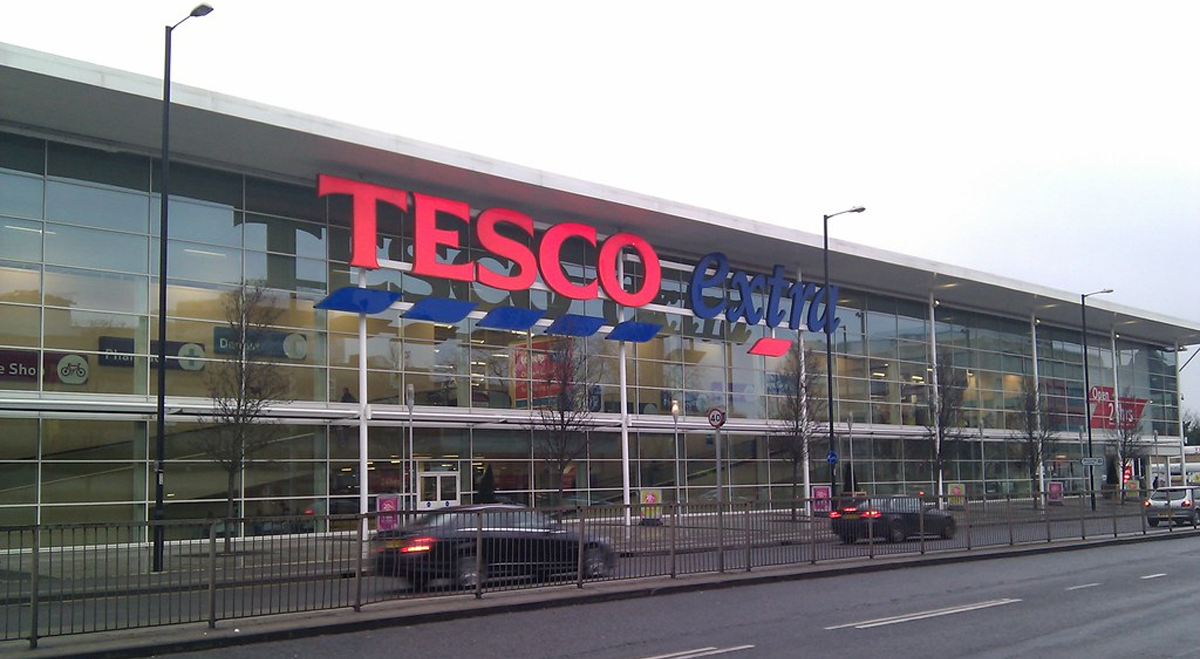
    Tesco (LSE:TSCO) remained in focus after reporting first-quarter UK like-for-like sales growth of 1.8%.

    The figure came in below analyst expectations, with the retailer citing ongoing consumer caution and uncertainty linked to geopolitical developments.

    Despite the softer sales performance, Tesco maintained its full-year profit outlook and highlighted continued progress across its value-focused strategy, online operations and customer loyalty initiatives.

    Investors Await Bank of England Verdict

    Attention now turns to the Bank of England’s policy decision, where investors will be looking for clues on the future path of interest rates and the central bank’s assessment of inflation and economic conditions.

    With wage growth remaining relatively firm but labour demand showing signs of moderation, markets are likely to scrutinise any changes in tone regarding the outlook for monetary policy over the remainder of the year.
  • Informa Shares Gain as Trading Update Shows Strong Revenue Momentum (INF)

    Informa Shares Gain as Trading Update Shows Strong Revenue Momentum (INF)

    Shares in Informa (LSE:INF) moved higher after the events and academic publishing group reported solid trading across its core businesses during the opening months of 2026 and reiterated its expectations for double-digit growth in adjusted earnings per share for the full year.

    The company reported underlying revenue growth of 6.4% for the first five months of the year, supported by continued strength in both its Academic Markets and B2B Live Events divisions.

    Academic Publishing Continues to Deliver

    Taylor & Francis, Informa’s academic publishing business, recorded underlying revenue growth of 5.5% during the period.

    The performance was driven by ongoing demand for subscription-based content, open research products and advanced learning solutions.

    Management said the division remains on course to achieve approximately 4% revenue growth for the full year, reflecting the resilience of its recurring revenue model and strong position within global academic publishing markets.

    Live Events Business Maintains Strong Growth

    Informa’s B2B Live Events division delivered underlying revenue growth of 7.6%, benefiting from robust activity across multiple geographic regions and industry sectors.

    The company highlighted strong performances in the Americas, Greater China, ASEAN, Europe and IMEA markets, with healthcare, food, beauty and financial services events among the leading contributors to growth.

    Management said event activity across these regions has remained resilient despite ongoing geopolitical uncertainty in certain markets.

    Recovery Emerging in Previously Disrupted Markets

    The group also reported improving conditions in regions that have been affected by recent conflicts and disruptions.

    These markets account for roughly 10% of Informa’s B2B Live Events portfolio.

    More than 15 event brands impacted by regional instability have now been rescheduled within the 2026 calendar year, while several planned launches have been postponed until 2027.

    The company said these adjustments have helped preserve long-term growth opportunities while limiting disruption to customers and exhibitors.

    Revenue Visibility Remains Strong

    Informa highlighted the strength of its forward revenue profile, reporting that more than $4 billion of expected 2026 revenue has already been traded, contracted, booked or is otherwise visible through subscriptions and recurring arrangements.

    The company also disclosed that more than $600 million of revenue relating to the first half of 2027 has already been secured or confirmed.

    Management said this high level of visibility provides confidence in the group’s near-term outlook and supports ongoing investment in growth initiatives.

    Outlook Reaffirmed

    Looking ahead, Informa maintained its guidance for double-digit underlying growth in adjusted earnings per share during 2026.

    The company also expressed confidence that growth will accelerate further in 2027 as its multi-year strategy to expand and scale its B2B growth platform continues to progress.

    Management believes the combination of strong recurring revenues, global event brands and growing academic publishing operations positions the group well for continued expansion.

    More about Informa

    Informa plc is an international events, digital services and academic publishing company serving specialist markets around the world. Its portfolio includes the Taylor & Francis academic publishing business and a large network of B2B events across industries including healthcare, finance, technology, beauty and food. The group operates globally, generating revenues through subscriptions, exhibitions, conferences, digital services and research products.

  • LSEG Shares Slide After Redburn Downgrade Highlights AI-Related Risks (LSEG)

    LSEG Shares Slide After Redburn Downgrade Highlights AI-Related Risks (LSEG)

    Shares in London Stock Exchange Group Plc (LSE:LSEG) fell more than 4% after Rothschild & Co Redburn downgraded the stock to “neutral” from a more positive stance and reduced its price target to £104 from £120.

    The broker cited concerns that advances in artificial intelligence could increase pressure on parts of LSEG’s Data & Analytics business, particularly areas exposed to changing customer behaviour and evolving methods of data consumption.

    Redburn Flags Diverging Business Dynamics

    In its research note, Redburn described LSEG’s earnings profile as becoming “increasingly bar-belled,” arguing that some of the group’s businesses remain highly resilient while others face growing structural challenges.

    According to the broker, operations such as real-time market data, index services and post-trade infrastructure continue to benefit from strong competitive positions and high barriers to entry.

    However, it warned that products linked to workflow tools, terminals and segments of non-real-time data services may be more vulnerable to technological disruption.

    “These concerns are not without merit,” Redburn said, adding that a shift toward “modular, API- and AI-driven data consumption may prove structurally deflationary for parts of the model.”

    AI Seen as Potential Source of Pressure

    The broker estimated that approximately 30% of LSEG’s earnings before interest, taxes, depreciation and amortisation could face downside risk under what it described as a realistic base-case scenario.

    Redburn identified three principal concerns: AI-driven disintermediation within Data & Analytics, cyclical pressures affecting the Markets division and the potential application of a conglomerate discount to the group’s valuation.

    The note suggested that as clients increasingly access information through AI-enabled tools and application programming interfaces, some traditional data aggregation and workflow products could experience pricing and demand pressures over time.

    Valuation Remains Attractive but Uncertainty Persists

    Despite the downgrade, Redburn acknowledged that LSEG remains capable of delivering low double-digit earnings-per-share growth, supported by mid- to high-single-digit organic revenue expansion and operating leverage.

    The broker noted that the shares currently trade at around 18 times forward earnings, below the approximately 24 times average seen since the Refinitiv acquisition.

    However, Redburn argued that uncertainty surrounding the long-term outlook for parts of the Data & Analytics division may limit the potential for valuation expansion.

    The new £104 price target still implies approximately 15% upside from current levels, but the broker said the balance between opportunities and risks has become more evenly matched.

    Focus Turns to Data & Analytics Strategy

    The downgrade highlights increasing investor focus on how financial information providers adapt to rapid technological change and the growing influence of artificial intelligence across capital markets.

    While LSEG retains significant strengths across its infrastructure, market data and index businesses, analysts are increasingly evaluating how AI could reshape demand for traditional financial information products and workflow solutions.

    Management’s ability to navigate these changes is likely to remain a key area of attention for investors in the coming years.

    More about London Stock Exchange Group

    London Stock Exchange Group Plc is a global financial markets infrastructure and data provider operating across capital markets, post-trade services, indices and financial information. The company owns businesses including the London Stock Exchange, FTSE Russell and LSEG Data & Analytics, which was significantly expanded through the acquisition of Refinitiv. LSEG serves financial institutions, corporations and governments worldwide through a combination of trading, clearing, data and technology services.

  • Duke Capital Increases Cash Revenue and Free Cash Flow While Maintaining Dividend (DUKE)

    Duke Capital Increases Cash Revenue and Free Cash Flow While Maintaining Dividend (DUKE)

    Duke Capital (LSE:DUKE) delivered growth in revenue, free cash flow and earnings during the 2026 financial year, demonstrating the resilience of its hybrid capital investment model despite a challenging economic backdrop.

    The company reported total cash revenue of £28.6 million for the year, representing a 7% increase, while recurring cash revenue rose 5% to £27.1 million. Free cash flow increased 13% to £14.2 million, supporting the board’s decision to maintain its annual dividend at 2.80 pence per share.

    Profit Growth Driven by Improved Portfolio Valuations

    Profit after tax increased to £11.0 million during the year, benefiting in part from lower non-cash fair value losses compared with the prior period.

    The result reflects the continued performance of Duke’s portfolio and the cash-generative nature of its investment model, which focuses on providing long-term capital solutions to small and medium-sized businesses.

    Management said the business continued to perform well despite an operating environment characterised by inflationary pressures, higher costs and restricted access to financing for many companies.

    Capital Redeployed Across Existing Partners

    During the year, Duke deployed more than £21 million into existing capital partners, reinforcing its commitment to supporting portfolio company growth while deepening established relationships.

    The company said its disciplined approach to capital allocation remains central to its strategy, allowing it to expand exposure to businesses it knows well while maintaining a focus on risk management and recurring income generation.

    Management believes this strategy provides greater visibility over future cash flows while supporting long-term value creation.

    Hybrid Capital Model Demonstrates Resilience

    Duke highlighted the defensive qualities of its hybrid capital structure, which combines elements of debt and equity financing and aligns returns with the performance of partner businesses.

    The model is designed to provide entrepreneurs with long-term growth capital without the refinancing risks associated with conventional lending structures.

    Management said the approach has continued to prove resilient despite economic uncertainty and remains well suited to the current environment, where access to traditional funding remains constrained for many SMEs.

    Monitoring Economic and Geopolitical Risks

    The board noted that it remains attentive to broader macroeconomic developments, including inflationary pressures, weakness in the UK economy and geopolitical tensions in the Middle East.

    Despite these uncertainties, Duke said it remains focused on maintaining financial discipline, preserving income visibility and supporting the growth of its portfolio companies.

    Looking ahead, the company expects recurring cash revenue of approximately £7.0 million during the first quarter of the 2027 financial year.

    Focused on Long-Term Income Generation

    Management continues to prioritise predictable cash generation and sustainable shareholder returns through a combination of recurring revenue streams and disciplined capital deployment.

    The maintained dividend reflects confidence in the underlying strength of the portfolio and the company’s ability to continue generating stable cash flows despite a more challenging economic backdrop.

    More about Duke Capital

    Duke Capital Limited is a Guernsey-based provider of hybrid capital solutions to small and medium-sized businesses across Europe and North America. Listed on AIM, the company offers long-term financing structures that combine characteristics of both debt and equity, enabling business owners to access growth capital while avoiding traditional refinancing risks. Duke’s model is designed to generate recurring income, preserve capital and align investor returns with the growth of its portfolio companies.

  • Ascent Resources Awaits Final Decision in Slovenia Arbitration Dispute (AST)

    Ascent Resources Awaits Final Decision in Slovenia Arbitration Dispute (AST)

    Ascent Resources (LSE:AST) said a key milestone has been reached in its long-running arbitration proceedings against the Republic of Slovenia, with the tribunal formally closing the case and moving toward a final ruling.

    The claim, which was brought under the Energy Charter Treaty and is being administered through the International Centre for Settlement of Investment Disputes (ICSID), has now entered its final stage following the closure of proceedings.

    Tribunal Moves Toward Final Award

    Under ICSID procedures, the closure of proceedings signals that the tribunal has completed its review of submissions and evidence presented by the parties.

    A final award is now expected before the end of June, potentially bringing an end to a dispute that has been closely followed by investors and stakeholders.

    The outcome could have significant implications for Ascent, depending on the tribunal’s findings and any financial remedies that may be awarded.

    Long-Running Case Nears Resolution

    The arbitration relates to Ascent’s historic interests in Slovenia and forms part of the company’s efforts to seek redress under international investment protection mechanisms.

    Management said it will provide further updates as appropriate once the tribunal has delivered its decision.

    With the process now approaching its conclusion, investors are expected to gain greater clarity regarding the potential impact of the case on the company’s future strategy and financial position.

    Strategic Focus Remains on U.S. Operations

    While the arbitration has remained an important legacy matter, Ascent’s operational focus has increasingly shifted toward its onshore oil and gas activities in the United States.

    The company continues to position itself around opportunities in the North American energy sector while working to resolve outstanding international issues stemming from its previous operations.

    A final ruling in the Slovenia case could influence future capital allocation decisions and help shape the balance between operational growth initiatives and the management of legacy assets and disputes.

    Awaiting Greater Certainty

    The forthcoming award is likely to represent an important event for the company, providing a clearer picture of any potential financial recovery or obligations arising from the proceedings.

    Management has indicated that additional information will be released once the tribunal’s decision becomes available.

    More about Ascent Resources

    Ascent Resources plc is a London-listed oil and gas company focused primarily on onshore energy opportunities in the United States. Alongside its current operational activities, the company continues to manage legacy matters associated with its former international assets, including arbitration proceedings linked to historic operations in Slovenia. Ascent’s strategy centres on developing and expanding its North American energy portfolio while seeking to maximise value from existing interests and legal claims.

  • Tesco Reports Higher First-Quarter Sales and Strengthens Value Offering (TSCO)

    Tesco Reports Higher First-Quarter Sales and Strengthens Value Offering (TSCO)

    Tesco (LSE:TSCO) delivered first-quarter sales growth as investments in value, product innovation and customer experience helped attract shoppers across its core markets despite ongoing economic uncertainty.

    The retailer reported a 1.0% increase in group like-for-like sales for the first quarter of the 2026/27 financial year, with growth driven by strong performances in its food, online and Irish businesses. This was partly offset by a weaker contribution from Booker following the exit of a lower-margin contract.

    Customer Satisfaction Continues to Improve

    Tesco said customer satisfaction strengthened significantly during the quarter, with its UK net promoter score rising by six points.

    Management attributed the improvement to continued investment in value and quality, including the expansion of its Aldi Price Match programme, the launch of new products under its Finest range and the introduction of additional high-protein offerings.

    The company has also enhanced personalisation across its digital platforms, providing customers with more tailored shopping experiences and targeted promotions.

    Online and Convenience Channels Gain Momentum

    Online sales remained a key growth driver, supported by further investment in digital capabilities and delivery services.

    Tesco continued expanding its Whoosh rapid-delivery platform, which offers customers access to a growing range of products through fast fulfilment options.

    The retailer also increased the use of personalised Clubcard offers, helping strengthen customer engagement and encourage repeat spending across its store and online channels.

    Media and Loyalty Businesses Deliver Additional Growth

    Beyond its core grocery operations, Tesco highlighted continued progress within Tesco Media, its retail media business.

    The division benefited from increased advertising activity linked to major events, including the FIFA World Cup, as brands sought to engage with Tesco’s large customer base through targeted marketing campaigns.

    Management sees retail media as an increasingly important complementary revenue stream that leverages the scale of its loyalty programme and customer data capabilities.

    Guidance Reaffirmed and Buyback Progresses

    Tesco maintained its full-year guidance, continuing to expect adjusted operating profit of between £3.0 billion and £3.3 billion and free cash flow in the range of £1.5 billion to £2.0 billion.

    The company also reported strong progress on its ongoing £750 million share buyback programme, with almost half of the authorised amount already completed.

    Management said the continued pace of shareholder returns reflects confidence in the group’s cash generation capabilities and resilience despite broader macroeconomic and geopolitical uncertainties.

    Focused on Value and Market Leadership

    Tesco said its strategy remains centred on offering customers a combination of value, quality and convenience while continuing to invest in growth areas such as online grocery, loyalty programmes and rapid delivery.

    The retailer believes its scale, strong brand position and broad customer offering leave it well placed to navigate competitive pressures and maintain its leadership position in the UK grocery market.

    More about Tesco

    Tesco plc is one of Europe’s largest food retailers, operating supermarkets, convenience stores and online grocery platforms across the UK, Ireland and Central Europe. The group also owns wholesale business Booker and offers a range of complementary services, including mobile, insurance and retail media. Tesco focuses on delivering value through a mix of own-brand and branded products while expanding its digital, loyalty and convenience offerings to meet changing consumer needs.

  • Whitbread Delivers Q1 Sales Growth as Premier Inn Gains Market Share in UK and Germany (WTB)

    Whitbread Delivers Q1 Sales Growth as Premier Inn Gains Market Share in UK and Germany (WTB)

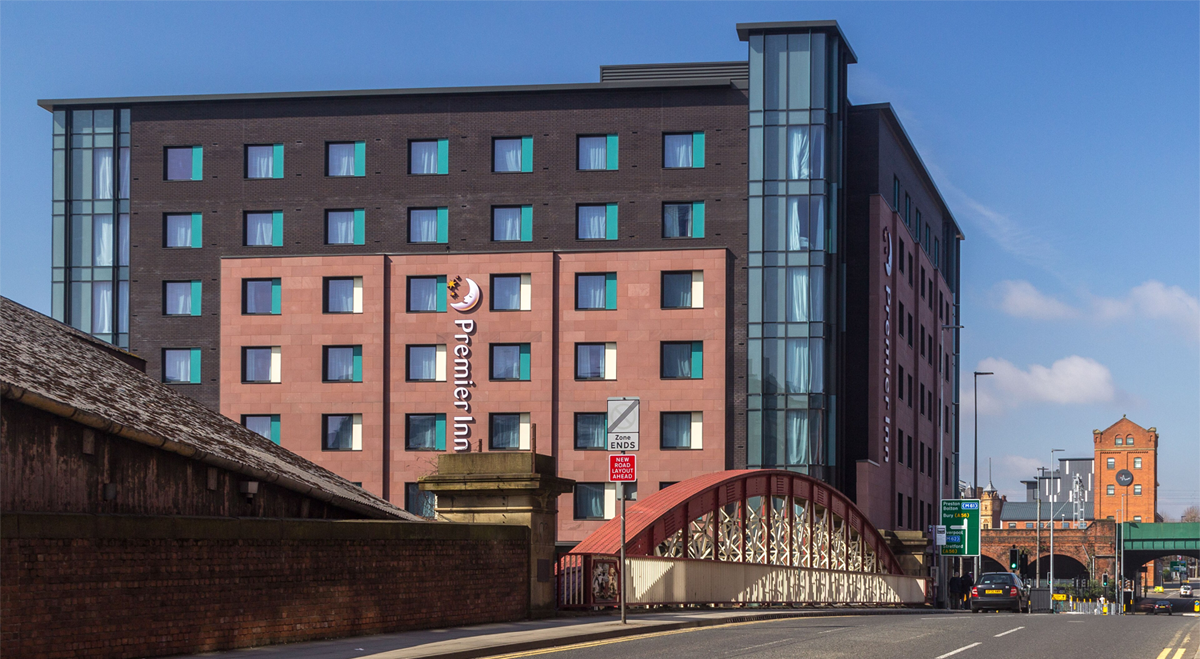
    Whitbread (LSE:WTB) reported a positive start to the 2026-27 financial year, with growth across its Premier Inn hotel operations in both the UK and Germany helping lift group sales despite an anticipated decline in food and beverage revenues.

    Total group sales increased 2% to £727 million during the first quarter, supported by strong accommodation demand and continued expansion of the company’s hotel portfolio.

    UK Hotels Continue to Outperform Market

    Premier Inn’s UK business delivered a 3% increase in accommodation sales, benefiting from robust leisure travel demand and continued market share gains.

    The hotel chain maintained its revenue per available room (RevPAR) premium over the wider midscale and economy hotel sector, reinforcing its position as one of the strongest-performing brands in its market segment.

    Whitbread also reported encouraging booking trends, with forward reservations running ahead of the prior year. London hotels continued to outperform regional locations, supported by sustained demand across both leisure and business travel segments.

    German Expansion Drives Double-Digit Growth

    In Germany, Premier Inn generated 16% accommodation sales growth on a sterling basis as the business continued to scale its presence in the market.

    During the quarter, Whitbread opened six new leasehold hotels, expanding its footprint and supporting further revenue growth.

    The company said its German operations continued to outperform the local midscale and economy hotel market on a RevPAR basis, reflecting increasing brand recognition, operational maturity and effective commercial initiatives.

    Management believes Germany remains a significant long-term growth opportunity as the business builds scale in one of Europe’s largest hotel markets.

    Confidence Maintained in Full-Year Outlook

    Whitbread reiterated confidence in its outlook for the current financial year, citing favourable supply conditions across both its UK and German markets.

    Management said demand trends remain supportive and believes the company is well positioned to benefit from continued growth in domestic and international travel.

    The group continues to focus on operational execution while advancing strategic initiatives designed to improve profitability and enhance shareholder returns.

    Five-Year Strategy Targets Cash Generation and Efficiency

    Whitbread is progressing its recently announced five-year plan, which aims to transform the business into a more focused hotel operator.

    Key objectives include completing the exit from branded restaurant operations, improving margins, reducing capital intensity and enhancing returns on invested capital.

    The company has outlined ambitions to lower capital requirements by approximately £1 billion and generate around £2 billion of free cash flow by the 2031 financial year.

    Management believes these initiatives will strengthen the group’s financial profile while supporting long-term value creation for shareholders.

    More about Whitbread

    Whitbread is a UK hospitality company best known for operating the Premier Inn hotel brand. The group is one of the largest providers of midscale and economy accommodation in the UK and is expanding rapidly in Germany. Whitbread is pursuing a strategy focused on hotel operations, including the gradual exit from branded restaurant businesses, with the aim of improving profitability, increasing cash generation and delivering stronger shareholder returns over the long term.

  • Seeing Machines Secures US$31 Million Automotive Programme Expansion with European Carmaker (SEE)

    Seeing Machines Secures US$31 Million Automotive Programme Expansion with European Carmaker (SEE)

    Seeing Machines (LSE:SEE) has won a US$31 million expansion to an existing automotive production programme, extending the deployment of its in-cabin monitoring technology across additional vehicle models for a major European manufacturer.

    The expanded agreement will see the company’s driver and occupant monitoring systems introduced into a broader range of vehicles from the second half of 2026, further increasing its presence within global automotive platforms.

    Deployment Extended Across Multiple Regions

    The programme expansion is being delivered in collaboration with a key Tier 1 automotive supplier and will support vehicle production across several major markets, including Europe, the United States and China.

    By extending the use of its technology across additional models, Seeing Machines is increasing the scale of its relationship with the automaker while broadening the geographic reach of its in-cabin safety systems.

    Management said the award reflects continued customer confidence in the company’s ability to deliver production-ready monitoring technology at volume.

    Growing Adoption of In-Cabin Safety Systems

    The latest contract builds on an existing relationship with the European original equipment manufacturer and represents a further stage in the rollout of its driver and occupant monitoring capabilities.

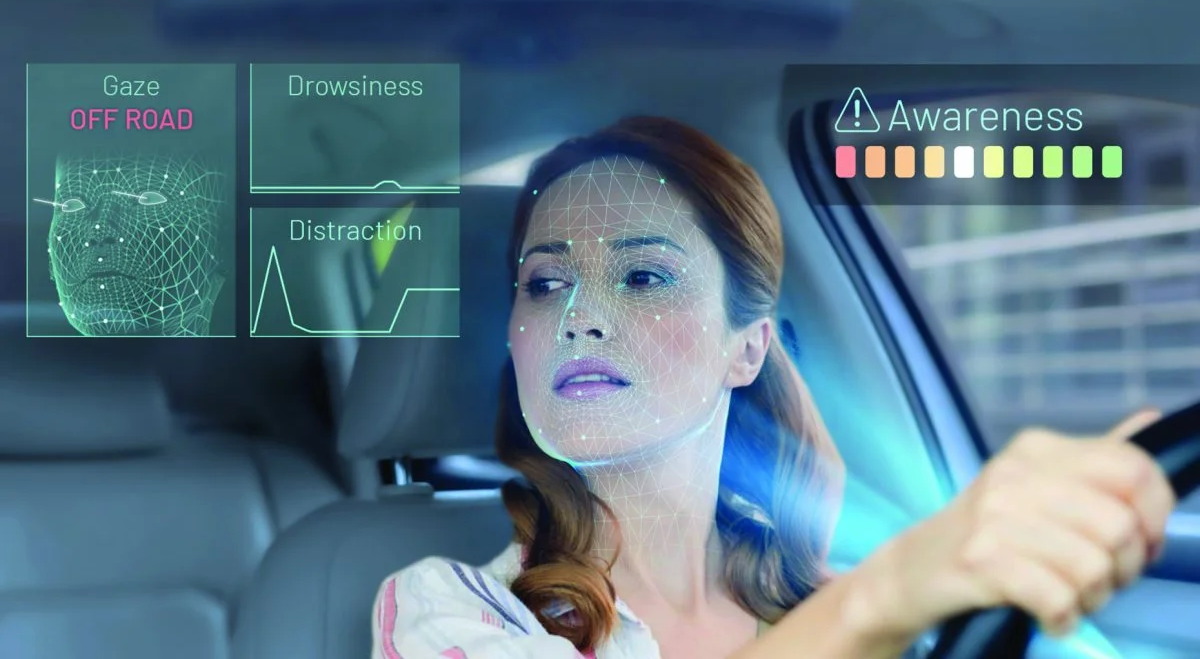
    Seeing Machines develops vision-based systems that analyse driver attention, alertness and behaviour in real time, helping improve vehicle safety and support advanced driver assistance features.

    The company believes growing regulatory requirements and increasing consumer awareness of vehicle safety are accelerating the adoption of in-cabin monitoring technologies across the automotive industry.

    Strengthening Position in Automotive Technology

    The programme expansion reinforces Seeing Machines’ position within the rapidly growing market for driver and occupant monitoring systems.

    As automotive manufacturers incorporate more advanced safety technologies into new vehicle platforms, the company expects demand for its solutions to continue increasing.

    Management believes the additional contract value not only enhances future revenue visibility but also strengthens the company’s standing as a trusted supplier to global automotive manufacturers.

    Expanding Global Automotive Footprint

    With deployments now spanning major automotive markets across Asia, North America and Europe, Seeing Machines continues to build a larger installed base of production vehicles using its technology.

    The company sees further opportunities to expand existing customer relationships while pursuing new programme wins as in-cabin sensing becomes an increasingly standard feature in modern vehicles.

    More about Seeing Machines

    Seeing Machines Limited is an Australia-headquartered technology company listed on AIM that specialises in vision-based monitoring systems designed to improve transport safety. Its artificial intelligence-powered driver and occupant monitoring technologies are used across automotive, commercial fleet, off-road and aviation markets. The company’s systems analyse driver attention and cognitive state in real time, helping manufacturers and operators improve safety outcomes and comply with evolving regulatory requirements.

  • Anpario Reports Positive Trading Momentum and Expands Share Buyback Programme (ANP)

    Anpario Reports Positive Trading Momentum and Expands Share Buyback Programme (ANP)

    Anpario (LSE:ANP) said trading during the opening months of 2026 has remained strong, with both revenue and profit exceeding the prior-year period and tracking in line with market expectations despite ongoing geopolitical and economic uncertainty.

    The animal nutrition specialist highlighted robust performances across several key international markets, helping to sustain growth momentum at the start of the year.

    International Markets Drive Growth

    The Middle East was among the strongest-performing regions during the period, supported in part by the first commercial sales of the company’s recently launched AmpLIPhy product.

    Anpario also reported continued growth across its operations in the United States and Australasia, reflecting ongoing demand for its animal health and nutrition solutions.

    Management said the broad-based nature of the growth demonstrates the resilience of the company’s global business model despite challenging market conditions.

    Margins Maintained Through Pricing Discipline

    The company noted that increases in logistics and raw material costs have largely been passed through to customers, helping to protect profitability.

    As a result, gross margins have remained broadly consistent with levels achieved during the latter part of 2025.

    Management said a disciplined pricing strategy continues to support earnings resilience while enabling the business to manage inflationary pressures affecting its supply chain.

    Shareholder Returns Enhanced

    Anpario has also accelerated capital returns to shareholders through an ongoing £3 million share buyback programme.

    The company said approximately £2 million of the authorised amount has already been deployed, complementing its established dividend policy and reflecting confidence in both the business and its financial position.

    The buyback programme is supported by a strong cash balance and the group’s historically conservative approach to capital management.

    Recognition for Sustainability Efforts

    During the period, Anpario also received recognition as ESG Company of the Year, highlighting its focus on sustainable animal nutrition and responsible business practices.

    Management believes sustainability remains an increasingly important consideration for customers and industry participants, supporting long-term demand for the company’s natural feed additive portfolio.

    Positioned for Continued Progress

    With growth across several core markets, stable margins and a strong balance sheet, Anpario believes it is well positioned to navigate ongoing macroeconomic challenges while continuing to invest in product development and international expansion.

    The company remains focused on supporting livestock performance through natural, sustainable nutrition solutions while delivering value to shareholders through both growth and capital returns.

    More about Anpario

    Anpario plc is an independent manufacturer of natural animal feed additives designed to improve animal health, nutrition and biosecurity. The company supplies products to livestock producers worldwide, with operations spanning key agricultural markets including the Middle East, North America and Australasia. Its portfolio includes acid-based eubiotics and other specialist feed solutions, including the recently launched AmpLIPhy product, aimed at enhancing animal performance through sustainable nutrition.

  • Nanoco Postpones Delisting Vote Following Shareholder Opposition (NANO)

    Nanoco Postpones Delisting Vote Following Shareholder Opposition (NANO)

    Nanoco Group plc (LSE:NANO) has delayed plans to seek shareholder approval for a proposed delisting from the London Stock Exchange’s Main Market after feedback from investors indicated the resolution was unlikely to secure the support required to pass.

    The company said its board now intends to adjourn the previously scheduled general meeting and continue discussions with shareholders while assessing alternative options for the business.

    Board Responds to Investor Concerns

    The proposed delisting had been presented as part of a broader effort to reduce costs and enable management to focus resources on strategic priorities.

    However, following extensive engagement with investors, directors concluded that concerns surrounding share liquidity after a delisting remained a significant issue for many shareholders.

    As a result, the board believes the special resolutions required to approve the proposal would be unlikely to achieve the necessary 75% level of shareholder support.

    Alternative Options Under Review

    With the vote now expected to be postponed, Nanoco said it will continue discussions with investors and evaluate other approaches that could address the company’s objectives while taking shareholder concerns into account.

    Management said future deliberations will focus on balancing the need for cost efficiencies and targeted investment with the interests of shareholders and the preservation of value.

    The company has not yet outlined what alternative options may be considered but indicated that further engagement with stakeholders will form part of the decision-making process.

    Focus Remains on Advanced Nanomaterials

    Nanoco continues to develop and commercialise its portfolio of cadmium-free quantum dot technologies and related nanomaterials.

    The company’s products, including its CFQD and HEATWAVE ranges, are designed for use in displays, sensors and advanced electronics applications, offering tunable optical and electronic characteristics while avoiding the use of toxic heavy metals.

    Management believes these technologies position the business within growing markets focused on high-performance electronic components and environmentally sustainable materials.

    Continuing Dialogue with Shareholders

    The decision to postpone the vote reflects the importance of shareholder support in determining the company’s future market listing status.

    Nanoco said it remains committed to maintaining open communication with investors as it evaluates the next steps and considers how best to support long-term growth and shareholder value creation.

    Further updates are expected once the board has completed its review and consultation process.

    More about Nanoco Group

    Nanoco Group plc is a UK-based nanomaterials company specialising in the development, manufacture and licensing of patented cadmium-free quantum dots and related technologies. Headquartered in Runcorn, the company supplies advanced materials for use in sensor, electronics and display applications. Its intellectual property portfolio and production capabilities are focused on enabling high-performance electronic devices while supporting the transition toward more environmentally sustainable technologies.