Author: Fiona Craig

  • Market Open: Greggs Profit Growth, Aston Martin Margins

    Market Open: Greggs Profit Growth, Aston Martin Margins

    FTSE 100 opens steady as earnings support sentiment. Greggs and Aston Martin lead UK headlines while Brent crude rebounds and Nasdaq slips.

    Market Overview

    The FTSE 100 opened marginally higher at 10,871.16, up 0.001 per cent from the previous close. Across Europe, the Euronext 100 gained 0.04 per cent and Germany’s DAX rose 0.25 per cent. Overnight in the US, the Nasdaq closed lower at 24,876.91, while the S&P 500 finished higher at 7,428.78. Market sentiment was supported by a strong corporate earnings backdrop despite ongoing concerns over Middle East tensions, higher oil prices and expectations that interest rates could remain elevated for longer.

    Commodity markets reflected a more cautious tone, with Brent crude rebounding after supply concerns linked to geopolitical developments and OPEC+ expectations, while gold eased and copper edged higher. Natural gas was little changed. Against sterling, the US dollar and Japanese yen strengthened slightly, while the euro and Swiss franc were broadly steady and the Australian dollar weakened marginally. Bitcoin rose against the pound.


    Market Numbers

    FTSE 100: Up (0.001%), 10,871.16
    Euronext 100: Up (0.04%), 1,905.37
    DAX: Up (0.25%), 25,528.18
    NASDAQ: Down, 24,876.91
    S&P 500: Up, 7,428.78


    In the Headlines

    Interim results – Greggs (LSE:GRG)
    Greggs reported higher first-half profit and continued market share gains as its value-focused strategy attracted customers despite softer food-to-go demand. Continued investment in new stores, digital channels and supply chain capacity supports its long-term growth strategy.

    Trading update – Aston Martin Lagonda (LSE:AML)
    Aston Martin improved margins, strengthened liquidity and delivered better first-half performance as preparations for Valhalla customer deliveries gathered pace. The update signals continued progress on profitability and cash generation despite a challenging luxury automotive market.


    Currencies (vs GBP)

    USD: Down (-0.02%), $1.3287
    CHF: Down (-0.02%), Fr.1.0888
    EUR: Up (+0.02%), €1.1669
    JPY: Down (-0.04%), ¥217.725
    AUD: Up (+0.00%), $1.9051
    Bitcoin (BTC/GBP): Up, £48,420.42


    Commodities

    Copper: Up
    Gold: Down
    Brent Crude: Down
    Natural Gas: Up
  • FTSE 100 Rises as Strong Corporate Results Offset Geopolitical Tensions

    FTSE 100 Rises as Strong Corporate Results Offset Geopolitical Tensions

    UK equities moved higher on Wednesday, supported by a series of stronger-than-expected corporate earnings from several FTSE 100 constituents, while energy stocks gained as oil prices climbed following joint U.S. and Saudi military operations in Iraq.

    By 03:51 ET (07:51 GMT), the FTSE 100 had advanced 0.50%. Elsewhere in Europe, Germany’s DAX edged up 0.05% and France’s CAC 40 added 0.11%. Sterling also strengthened slightly, rising 0.08% against the U.S. dollar to 1.3304.

    Oil prices extended their gains after the U.S. Central Command (CENTCOM) and Saudi Arabian armed forces carried out coordinated strikes on militia logistics and weapons facilities in eastern Iraq on Tuesday. According to CENTCOM, the operation was launched in response to more than 30 drone attacks attributed to Iran’s Islamic Revolutionary Guard Corps (IRGC) over a 72-hour period.

    “U.S. Central Command and the Saudi Arabian Armed Forces conducted precision strikes in Iraq, July 28, against Iran-aligned terrorists,” CENTCOM said, adding that the IRGC and its affiliated groups must “halt the aggression immediately to prevent further US military action.”

    Saudi Arabia’s Ministry of Defence separately confirmed the strikes, stating they were conducted under Article 51 of the United Nations Charter.

    Earlier, Iran fired multiple ballistic missiles toward U.S. military forces stationed in the Middle East in what CENTCOM described as “an attempted surprise attack,” adding on social media platform X that “all Iranian missiles were successfully intercepted.”

    According to Axios, the intended target was a U.S. military installation in Jordan, marking Iran’s first direct strike against a U.S. base since Washington paused military action against Tehran last week to allow diplomatic negotiations.

    Regional governments reacted swiftly. Kuwait and Qatar both condemned the missile launches, with Kuwait’s Foreign Ministry describing the incident as “a flagrant violation of the sovereignty of Jordan and a threat to its security and stability.”

    The escalation followed talks between U.S. and Israeli leaders at the White House, which the U.S. press secretary described as “positive and productive.”

    In a video published on Instagram, the Israeli prime minister said the meeting was “a conversation with full partnership” focused on preventing Iran from developing nuclear weapons.

    Earlier on Tuesday, the U.S. president told Fox News that military action could resume if negotiations with Tehran failed.

    “If they don’t make a deal, then I go back, and I finish the job,” he said, adding that he could destroy most of Iran’s bridges “in less than an hour.”

    Commodity markets reflected the heightened geopolitical uncertainty. Brent crude rose 3.3% to $84.78 per barrel, while U.S. West Texas Intermediate crude gained 3.7% to $82.19. Gold futures edged up 0.11% to $4,043.20 an ounce, with spot gold adding 0.4% to $4,044.06.

    UK Market Highlights

    Rio Tinto (LSE:RIO) reported first-half earnings ahead of expectations, increased its interim dividend and highlighted growing long-term demand for metals linked to artificial intelligence infrastructure.

    Glencore (LSE:GLEN) announced a 15% increase in first-half copper production, maintained its full-year production guidance and said marketing earnings are expected to be near the upper end of its annual target range.

    Reckitt (LSE:RKT) delivered stronger-than-expected first-half profit, unveiled a £500 million share buyback programme and raised its interim dividend while reaffirming its full-year outlook.

    Standard Chartered (LSE:STAN) exceeded second-quarter earnings forecasts, upgraded its income guidance for 2026 and announced a new $1 billion share buyback programme.

  • Reckitt Reports Better-Than-Expected First-Half Profit and Unveils £500 Million Share Buyback

    Reckitt Reports Better-Than-Expected First-Half Profit and Unveils £500 Million Share Buyback

    Reckitt Benckiser (LSE:RKT) delivered stronger-than-expected first-half 2026 earnings, reporting adjusted operating profit ahead of market forecasts while announcing a new £500 million share buyback programme aimed at enhancing shareholder returns.

    Adjusted operating profit declined 15% year over year to £1.46 billion, comfortably exceeding the S&P Global Visible Alpha consensus estimate of £1.40 billion. Adjusted diluted earnings per share reached 152.1 pence, also beating analyst expectations of 140.7 pence.

    Revenue for the period decreased 8.1% to £6.41 billion, primarily reflecting the disposal of the Essential Home business. Adjusted operating margin narrowed by 100 basis points to 23.6%, although management noted that profitability was stronger than the company’s own internal expectations.

    Alongside the results, Reckitt announced a share repurchase programme of up to £500 million, which is scheduled to be completed over the next 12 months. The company also increased its interim dividend by 5% to 88.6 pence per share.

    Underlying trading remained resilient despite the headline revenue decline. Like-for-like net revenue increased 2.6% during the first half, with momentum improving in the second quarter as growth accelerated to 4.2%. The company reported stronger performance across all product categories and geographic regions.

    Emerging Markets continued to lead growth, with like-for-like sales rising 8.5% in the first half. China delivered another quarter of double-digit growth, while India recorded high-single-digit gains. Trading also improved across developed markets, with Europe showing sequential progress and North America returning to positive growth during the second quarter.

    Looking ahead, Reckitt reaffirmed its guidance for 2026, continuing to expect Core Reckitt like-for-like revenue growth of between 4% and 5%, alongside an adjusted operating margin in the range of 24.9% to 25.6%.

    The company said lower oil prices, continued productivity initiatives and a stronger product mix in the second half are expected to support profitability, helping offset ongoing macroeconomic uncertainty and elevated raw material costs.

  • Standard Chartered Reports Strong First-Half Earnings as Wealth Business Drives Performance

    Standard Chartered Reports Strong First-Half Earnings as Wealth Business Drives Performance

    Standard Chartered PLC (LSE:STAN) delivered better-than-expected second-quarter results, with adjusted earnings per share exceeding analyst forecasts by 17%, supported by strong growth in its Wealth Solutions division and disciplined cost management.

    For the first half of 2026, the bank reported adjusted earnings per share of 151.6 cents, representing a 17% increase from the same period last year. Second-quarter operating income rose 3% year over year to $5.7 billion, or 8% excluding the $238 million gain generated by the Solv India transaction in the prior-year period. Overall revenue also exceeded market expectations, coming in approximately 3% ahead of consensus estimates.

    Wealth Solutions continued to be a major growth engine, with second-quarter revenue climbing 43% year over year. Revenue from investment products increased an impressive 56%, while Global Banking posted an 18% rise in revenue, benefiting from strong origination activity and healthy capital markets performance. Operating expenses remained tightly controlled, broadly unchanged from a year earlier and around 2% below analyst forecasts at approximately $3.15 billion for the quarter.

    “We delivered a record first-half performance in 2026, with double-digit growth in Wealth Solutions and Global Banking,” said Bill Winters, Group Chief Executive. “We delivered a 17% increase in our earnings per share, and our upgraded income guidance and new share buyback of $1 billion reflect our confidence in the business.”

    Net interest income increased 7% year over year to $2.9 billion during the second quarter, while non-interest income rose 9%, excluding the impact of the Solv India transaction, to $2.8 billion. Net interest margin improved to 203 basis points, up five basis points from the previous year. Credit impairment charges totaled $150 million, below analyst expectations, and included $44 million of management overlays related to the conflict in the Middle East.

    Following the strong first-half performance, Standard Chartered raised its guidance for 2026 operating income growth, now expecting results to be around the midpoint of its previous 5% to 7% constant currency growth range, excluding notable items. The bank also expects net interest income to deliver low single-digit percentage growth for the full year while maintaining its expense guidance of approximately $13.3 billion at constant currency, excluding notable items.

    The group’s Common Equity Tier 1 (CET1) ratio strengthened to 14.2%, an increase of 77 basis points from the previous quarter and around 50 basis points above consensus forecasts. The improvement reflected lower risk-weighted assets totaling $261.5 billion. Standard Chartered also announced a new $1 billion share buyback programme, which is expected to reduce the CET1 ratio by approximately 38 basis points, and increased its interim ordinary dividend by 66% to 20.4 cents per share.

  • Weir Reports Strong First-Half Orders as Revenue and Earnings Beat Expectations

    Weir Reports Strong First-Half Orders as Revenue and Earnings Beat Expectations

    Weir Group PLC (LSE:WEIR) delivered stronger-than-expected first-half 2026 results, with revenue and adjusted earnings per share exceeding analyst forecasts, supported by robust order growth and particularly strong demand during the second quarter.

    The engineering group generated first-half revenue of £1.269 billion, representing constant currency growth of 5% and coming in slightly ahead of the company-compiled consensus forecast of £1.262 billion. Adjusted EBITA totaled £239 million, broadly matching market expectations, while the adjusted EBITA margin was 18.8%, a decline of 100 basis points compared with the same period last year. On a reported basis, revenue increased 6% year over year.

    Adjusted earnings per share reached 54.6p, surpassing the consensus estimate of 53.6p by around 2%. The performance reflected resilient demand across the company’s core markets despite a more challenging margin environment.

    Order intake was a standout feature of the results, rising to £1.426 billion during the first half, 3% above analyst expectations of £1.379 billion and 8% higher than a year earlier on a constant currency basis. Weir recorded a book-to-bill ratio of 1.12x, improving from 1.01x for the full 2025 financial year. Original equipment orders increased 10% year over year, while aftermarket orders rose 8%. The Minerals division continued to perform particularly well, with orders climbing 7% and achieving a book-to-bill ratio of 1.15x.

    Momentum accelerated during the second quarter, with original equipment orders in the Minerals business jumping 19%, the strongest quarterly growth recorded in two years. Aftermarket demand also reached a record level, increasing 8% over the same period. Meanwhile, the company’s Micromine software business remains on course to deliver annual recurring revenue growth of more than 25% during fiscal 2026.

    Net debt increased to £1.449 billion from £1.274 billion at the end of 2025, primarily reflecting the acquisition of ESEL and the timing of cash flows. Despite the increase, the company’s net debt-to-EBITDA ratio remained at a manageable 2.2 times.

    Looking ahead, Weir reaffirmed its guidance for the 2026 financial year, continuing to expect growth in constant currency revenue, adjusted EBITA and EBITA margins. The company also maintained its forecast for free operating cash conversion of between 90% and 100%, while confirming that its Performance Excellence programme remains on track to generate cumulative savings of £90 million.

  • Lancashire Holdings Shares Fall After First-Half Earnings Miss Expectations

    Lancashire Holdings Shares Fall After First-Half Earnings Miss Expectations

    Shares in Lancashire Holdings (LSE:LRE) fell 5.6% during today’s trading session to 623p after the specialist insurer reported first-half 2026 results that came in below market expectations. Earnings per share were $0.56, around 15% below analyst forecasts, while overall profit missed consensus estimates by approximately 14%. The weaker performance was largely attributed to additional reserve provisions linked to the 2024 collapse of the Francis Scott Key Bridge in Baltimore, which increased claims costs and weighed on profitability.

    The impact was also reflected in the group’s underwriting performance. Lancashire reported an undiscounted combined ratio of 90.8%, around 500 basis points weaker than analysts had expected, while the discounted combined ratio reached 80.7%, missing consensus by approximately 310 basis points. Gross written premiums also declined 6.1% compared with the same period last year, highlighting slower premium growth at a time when investors had been looking for continued expansion.

    Market expectations had been elevated ahead of the earnings announcement after Lancashire shares moved above their 200-day moving average during the previous trading session, a level often viewed as a positive technical signal. The disappointing financial results prompted investors to reassess the company’s near-term outlook, accelerating selling pressure following the release.

    Before the announcement, the consensus analyst recommendation on the stock was “Hold,” with an average price target of around 675p. At least one major brokerage maintained a “buy” recommendation with a target price of 698p, although those valuations are likely to come under renewed scrutiny following the weaker-than-expected results. Broader market conditions offered little support, with major U.S. equity indices trading largely unchanged and the FTSE 250, where Lancashire is a constituent, providing limited assistance to sentiment.

    The combination of an earnings miss, weaker underwriting performance driven by higher catastrophe reserve charges and elevated investor expectations heading into the results contributed to the sharp share price decline. Following the sell-off, the stock moved closer to the lower end of its 52-week trading range of 549p to 700p.

  • St. James’s Place Delivers Strong First-Half Performance with Profit Ahead of Expectations

    St. James’s Place Delivers Strong First-Half Performance with Profit Ahead of Expectations

    St. James’s Place (LSE:STJ) reported first-half 2026 results that came in ahead of market expectations, with adjusted profit after tax reaching £224 million, approximately 14% above analyst forecasts.

    During the first six months of the year, the wealth manager generated net inflows of £2.7 billion, broadly in line with consensus estimates. Funds under management increased to £240.8 billion, exceeding analyst expectations by around 2%, while the client retention rate improved by 10 basis points year over year to 95.4%.

    The company also announced a £128 million share buyback programme, consisting of a £45 million ordinary repurchase alongside an additional £83 million buyback funded through the release of a provision. St. James’s Place maintained its interim dividend at the level anticipated by the market.

    At 30 June, the business employed 4,951 advisers, an increase of 17 compared with the end of 2025 but one fewer than a year earlier. Management reaffirmed its expectation that adviser numbers will remain broadly stable over the full year.

    Adjusted profit also benefited from a lower effective tax rate of 19%, compared with 23% during the same period last year. Operating expenses remained well managed, although the company noted that a greater proportion of planned investment spending will fall in the second half of 2026.

    During the period, St. James’s Place introduced changes to the timing of partner remuneration, moving from annual to monthly payments. The company said the adjustment would not affect the parent company’s profit and loss account, stating, “this change will not affect the parent company’s profit and loss statement, as market risk is hedged and there is no net interest income benefit from retaining cash for a year.”

    Elsewhere, pension inflows were below historical levels, while unit trust and ISA products continued to attract healthy investor demand throughout the first half.

  • Greggs Reports Higher Profit and Market Share as Value Strategy Continues to Deliver

    Greggs Reports Higher Profit and Market Share as Value Strategy Continues to Deliver

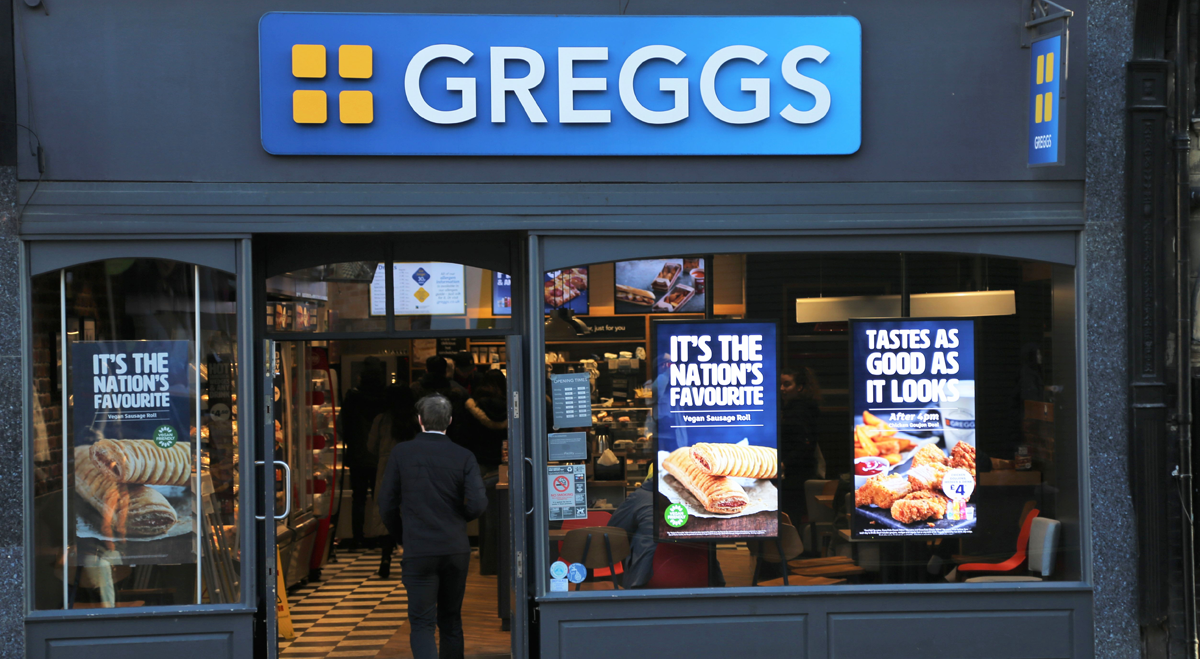
    Greggs (LSE:GRG) reported strong interim results for the 26 weeks ended 27 June 2026, with total sales increasing 7.2% year over year to £1.10 billion and operating profit rising almost 23% to £86.5 million. The food-to-go retailer also increased its share of customer visits to 8.7%, despite an overall decline in the wider food-to-go market, demonstrating the continued appeal of its value-focused offering during a challenging period for consumer spending.

    The company’s growth was supported by higher like-for-like sales across both company-operated and franchised stores, continued estate expansion and increasing sales through grocery retail partners including Tesco and Iceland. During the first half, Greggs opened a net 34 new shops, introduced its smaller “bitesize Greggs” store format, expanded trials of “Greggs Express” self-service locations and launched its first international travel hub outlet in Tenerife. The company’s digital loyalty programme also continued to strengthen customer engagement and repeat visits.

    Greggs is continuing to invest in its long-term growth strategy through major supply chain and logistics projects, including new national distribution centres in Derby and Kettering that are designed to support an estate of up to 3,500 UK stores. At the same time, management is pursuing operational efficiencies, reducing planned capital expenditure for 2026 to approximately £180 million while maintaining a target return on capital employed of around 20%, creating the potential for additional shareholder returns over time.

    Product innovation also remains a key growth driver. During the period, Greggs expanded its menu with new offerings including the Chicken Roll, additional hot food and pizza options, refreshed salad selections and a wider drinks range featuring iced beverages and Matcha. These initiatives are intended to strengthen the brand’s position as a leading destination for convenient food-to-go while supporting like-for-like sales growth and reinforcing its reputation for affordable, high-quality products.

    Greggs’ outlook continues to be supported by a resilient operating model and an attractive valuation, although management noted softer earnings quality during 2025, including pressure on margins, earnings per share and free cash flow, alongside gradually increasing leverage. Technical indicators remain generally positive despite mixed momentum, while the company expects sales growth to continue even as supply chain investment and inflationary pressures are likely to limit profit expansion in the near term.

    About Greggs plc

    Greggs plc is one of the UK’s largest food-to-go retailers, offering a wide range of freshly prepared bakery products, hot meals, snacks and beverages through a nationwide network of company-owned and franchised stores. In addition to its traditional retail estate, the company has expanded its presence through supermarket partnerships and new store formats designed to improve convenience and accessibility.

    The business focuses on providing affordable, ready-to-eat food throughout the day, serving millions of customers with products ranging from baked goods and sandwiches to pizzas, salads and hot drinks. Continued investment in digital services, menu innovation and supply chain infrastructure supports Greggs’ strategy of expanding its market share while delivering long-term sustainable growth.

  • Aberdeen Group Reports Higher Profit and Capital Generation as Interactive Investor Delivers Strong Growth

    Aberdeen Group Reports Higher Profit and Capital Generation as Interactive Investor Delivers Strong Growth

    Aberdeen Group (LSE:ABDN) reported a 21% increase in adjusted operating profit to £151 million for the first half of 2026, supported by modest revenue growth and continued cost discipline. Net capital generation rose 47% to £163 million, while the group’s capital position strengthened, with total capital coverage improving to 229%. Management reaffirmed its full-year guidance, targeting at least £300 million in adjusted operating profit and approximately £300 million in net capital generation for 2026.

    Interactive investor was the strongest-performing division during the period, with adjusted operating profit rising 18% to £84 million and net operating revenue increasing 22%. The platform attracted record net inflows of £6.8 billion, while customer numbers grew 14% to 525,000 and cash balances increased significantly. Although the business continued investing in technology and brand development, it also improved operating efficiency relative to assets under administration, reinforcing Aberdeen’s strategy of expanding its presence in the UK direct-to-consumer investment market.

    The Adviser division generated adjusted operating profit of £41 million, broadly unchanged from the previous year, on slightly higher revenue. However, it continued to experience difficult net flow conditions, recording £1.3 billion of net outflows despite stronger gross inflows. To address this, the company appointed a new chief executive for the business, aiming to convert recent improvements in customer service and product offerings into stronger commercial performance. Client satisfaction also improved during the period, as reflected by higher net promoter scores.

    Within the Investments division, adjusted operating profit increased 9% to £38 million as cost savings and transformation initiatives more than offset a modest decline in net operating revenue. Investment performance also improved, with 86% of assets outperforming their benchmarks over three years, comfortably exceeding the company’s 70% target. The business experienced net outflows of £5.6 billion, excluding liquidity products, largely due to withdrawals from lower-margin equity strategies. These were partly offset by inflows into fixed income and real assets, while recent acquisitions are expected to contribute more meaningfully to earnings during the second half of the year.

    Looking ahead, Aberdeen expects interactive investor to continue growing in line with customer acquisition while maintaining improving cost efficiency. The Adviser business is forecast to deliver broadly stable profitability in the second half as efforts continue to restore positive net flows, while the Investments division is expected to benefit from acquisitions and improved market conditions. Management continues to target medium-term annual growth in net capital generation of between 5% and 10%, supported by the group’s recent return to the FTSE 100 and strengthening operational momentum.

    Aberdeen’s outlook is underpinned by improving profitability, stronger cash generation, low leverage and a healthier balance sheet. Positive technical indicators also support the investment case, while the company’s valuation remains attractive thanks to a modest price-to-earnings ratio and an appealing dividend yield. Continued pressure on adviser flows, potential margin compression and near-term investment outflows remain the principal risks.

    About Aberdeen Group

    Aberdeen Group PLC is a UK-based asset and wealth management company operating across retail investing, financial advice and institutional investment management. Its core businesses include interactive investor, a digital investment platform serving individual investors, an Adviser division supporting financial advisers, and an Investments business managing multi-asset, fixed income, real assets and specialist investment strategies for clients around the world.

    The company focuses on growing assets under management and administration, improving investment performance and increasing capital generation, with particular emphasis on expanding its direct-to-consumer business and specialist investment capabilities. Its recent return to the FTSE 100 reflects its scale within the UK financial services sector.

    Aberdeen generates recurring income through platform subscriptions, investment management fees and treasury activities while maintaining a disciplined approach to cost management and capital allocation. The group’s strategy combines operational efficiency, balance sheet strength and targeted investment to support sustainable long-term growth and consistent shareholder returns.

  • Glencore Increases Copper Production and Maintains 2026 Guidance as Trading Business Performs Strongly

    Glencore Increases Copper Production and Maintains 2026 Guidance as Trading Business Performs Strongly

    Glencore (LSE:GLEN) delivered a solid operational performance during the first half of 2026, with own-sourced copper production increasing 15% year over year to 397,000 tonnes. The improvement was driven by stronger mining rates and higher ore grades at its African Copper operations, together with improved grades at the Antamina mine in Peru. Production of cobalt, zinc, gold and steelmaking coal declined during the period, largely reflecting regulatory restrictions, mine closures and production curtailments, while nickel and silver output remained broadly stable. Chrome and energy coal production also recorded modest decreases.

    The company left its full-year 2026 production guidance unchanged for copper, zinc and nickel, effectively upgrading its like-for-like outlook for copper and zinc following the sale of the Kidd mine in Canada in June. Guidance for energy coal production was increased slightly, while expectations for steelmaking coal were revised modestly lower. Glencore also reported a significant reduction in copper net unit cash costs despite higher input expenses linked to supply chain disruption arising from tensions in the Middle East. Its Marketing division is expected to deliver approximately $3.3 billion in adjusted EBIT for the first half, highlighting the continued strength of its global commodity trading business despite changing pricing conditions across coal and metals markets.

    Glencore’s outlook reflects improving revenue and earnings, although profitability continues to be affected by relatively thin margins, increasing leverage and weaker free cash flow conversion. Technical indicators remain supportive, with the shares continuing to trade above key moving averages and maintaining positive momentum. While the company’s valuation remains relatively demanding and dividend yield is modest, management’s reaffirmed production guidance, continued growth in copper output and resilient Marketing performance provide a positive backdrop despite ongoing operational and cash flow risks.

    About Glencore

    Glencore is one of the world’s largest diversified natural resources companies, with operations spanning the production, processing and marketing of metals, minerals and energy products. The group produces commodities including copper, zinc, nickel and coal, while also operating one of the world’s largest commodity marketing businesses, with significant exposure to African and South American copper operations and global energy markets.

    Its portfolio combines wholly owned mining assets with joint venture operations, supplying essential raw materials for industries such as steel production, power generation and manufacturing. Through its Marketing division, Glencore captures value by trading commodities across different regions and markets, allowing the company to benefit from price, quality and logistical differences while balancing earnings between production and trading activities.