Author: Fiona Craig

  • Premier African Minerals Raises £500,000 to Support Development of Zulu Lithium Project

    Premier African Minerals Raises £500,000 to Support Development of Zulu Lithium Project

    Premier African Minerals Limited (LSE:PREM) has secured approximately £500,000 through a share subscription and has also settled £100,000 of supplier invoices through the issuance of new equity at 0.0185 pence per share. In total, the company issued 3,243,243,244 new ordinary shares as part of the funding and debt settlement.

    The capital raise and debt-for-equity arrangement are intended to support operational costs and manage outstanding creditor obligations at the company’s Zulu Lithium and Tantalum Project, while also providing additional working capital.

    Most of the newly raised funds will be directed toward the installation and commissioning of a 15–20 tonne-per-hour flotation plant supplied by Xinhai at the Zulu project. The facility is designed to enable the production of lithium products at commercially viable grades and recovery levels, marking a key step toward stable processing operations.

    Following admission of the newly issued shares to trading on AIM—expected around 17 March 2026—the company’s total issued share capital will increase to 17,501,485,100 ordinary shares with voting rights. The enlarged share count highlights the ongoing dilution faced by shareholders as the company prioritises stabilising operations and achieving consistent production at Zulu.

    Despite operational progress, the company’s outlook remains challenged by financial pressures. Premier continues to report persistent losses, negative gross profit and ongoing cash burn. Technical indicators also suggest bearish market momentum, with the share price trading below key moving averages and showing a negative MACD signal. Valuation metrics provide limited support due to a negative price-to-earnings ratio and the absence of dividend yield.

    More about Premier African Minerals

    Premier African Minerals Limited is a mining and natural resources development company focused on projects in Southern Africa. Its key assets include the RHA Tungsten Project and the Zulu Lithium and Tantalum Project in Zimbabwe. The company also holds a broader portfolio of exploration and development interests spanning tungsten, lithium, tantalum and rare earth elements in Zimbabwe, along with lithium and gold projects in Mozambique, ranging from early-stage exploration to near-term production opportunities.
  • Supermarket Income REIT Targets 2% Annual Dividend Growth After Redeploying JV Capital

    Supermarket Income REIT Targets 2% Annual Dividend Growth After Redeploying JV Capital

    Supermarket Income REIT plc (LSE:SUPR) reported interim results for the six months to 31 December 2025 broadly in line with expectations, with annualised passing rent increasing 11% and the portfolio value rising 27% to £2.06bn. EPRA earnings per share declined 10% during the period, while dividend cover fell to 88%.

    The company said the reduction in earnings mainly reflected temporary factors, including cash drag from its expanded joint venture and one-off refinancing costs. Management expects these pressures to ease following the full redeployment of joint venture capital into £398m of acquisitions aimed at boosting future earnings.

    With the joint venture proceeds now fully invested, the board has updated its dividend outlook and is targeting a sustainable minimum dividend increase of 2% per year from the 2027 financial year onward. The dividend strategy will continue to be supported by long-term, inflation-linked rental income from grocery tenants. The group also highlighted a significant improvement in efficiency, with its EPRA cost ratio falling to 9.2%, among the lowest levels in the sector after bringing management fully in-house.

    Portfolio performance remained stable, with like-for-like valuations rising 1.3% and the portfolio delivering a net initial yield of 6.0%. Loan-to-value increased to 45% as the company used leverage, including a debut bond issuance, to expand its grocery property holdings.

    Management said the long-term outlook for grocery real estate remains favourable, supported by rising supermarket sales and the essential role of omnichannel stores that serve both in-store shoppers and online fulfilment operations. The company aims to significantly expand its portfolio over time.

    Recent transactions have broadened the trust’s tenant base and geographic exposure. The group acquired 20 supermarkets leased to Carrefour directly and, through its joint venture, added 10 stores leased to Asda. Management described the properties as well-established locations with strong trading histories.

    The company is also exploring further diversification opportunities, including grocery-anchored retail parks, European supermarket assets and potentially grocery distribution facilities. It said its acquisition pipeline currently exceeds £500m.

    On the sustainability front, Supermarket Income REIT received its first EPRA Sustainability Best Practices Gold Award and achieved a seventh consecutive EPRA Gold Award for financial reporting. The group has also joined the United Nations Global Compact, reinforcing its commitment to responsible business standards.

    Overall, the company’s outlook remains supported by stable financial performance, a relatively attractive dividend yield and positive market momentum. Strategic acquisitions and continued confidence from management further strengthen its position as a leading specialist investor in grocery real estate.

    More about Supermarket Income REIT

    Supermarket Income REIT plc is a FTSE 250-listed property investment company focused on high-quality omnichannel supermarkets and grocery-related real estate. As of 31 December 2025, its portfolio was valued at approximately £2.1bn and leased to leading UK and European grocery operators under long-term, inflation-linked agreements. The company aims to deliver progressive dividends alongside long-term capital growth by investing in assets that support both physical and online grocery retail.

  • ITM Power Wins 20 MW Green Hydrogen Project in Milford Haven with Long-Term Service Agreement

    ITM Power Wins 20 MW Green Hydrogen Project in Milford Haven with Long-Term Service Agreement

    ITM Power plc (LSE:ITM) confirmed that a previously announced 20 MW Notice to Proceed relates to MorGen Energy’s West Wales Hydrogen project in Milford Haven, which has now reached final investment decision under the UK government’s Hydrogen Allocation Round 1 (HAR1) funding framework.

    The project will see ITM supply its 20 MW POSEIDON electrolysis module for installation at a facility located on the site of the former Milford Haven Refinery in Wales. Once operational, the plant is expected to produce approximately 2,000 tonnes of green hydrogen each year, supplying industrial users across Milford Haven, Port Talbot and the wider Welsh industrial region. Commissioning of the facility is planned for 2028.

    Alongside the equipment contract, ITM has also signed a ten-year long-term service agreement with MorGen Energy to support the facility’s ongoing operation. The agreement covers maintenance and operational services for the electrolysis system and is expected to provide recurring revenue for ITM over the life of the contract.

    The project represents an important step in the development of large-scale green hydrogen infrastructure in the UK and reinforces the bankability of ITM’s electrolysis technology. Management believes the contract strengthens the company’s position in industrial decarbonisation initiatives as demand for low-carbon hydrogen solutions continues to grow.

    Despite these strategic wins, the company’s near-term outlook remains constrained by financial factors. ITM continues to report operating losses and negative operating and free cash flow, while technical indicators point to a bearish share price trend with the stock trading below major moving averages. However, operational progress has been evident, including record first-half revenue, improving order backlog quality and reaffirmed growth guidance. The company also maintains a relatively low-leverage balance sheet, although profitability and cash flow timing remain key risks.

    More about ITM Power

    ITM Power plc, founded in 2000 and listed on London’s AIM since 2004, is headquartered in Sheffield and specialises in proton exchange membrane (PEM) electrolysers used to produce green hydrogen from renewable electricity and water. The company focuses on supplying advanced electrolysis technology to support industrial decarbonisation and the development of the emerging green hydrogen economy across the UK and Europe.

  • 4imprint Maintains Strong Margins and Dividend Despite Slight Revenue Dip in 2025

    4imprint Maintains Strong Margins and Dividend Despite Slight Revenue Dip in 2025

    4imprint Group plc (LSE:FOUR) reported a modest decline in its 2025 financial results, with revenue slipping 2% to $1.35bn while profit before tax also eased 2% to $150.8m. Despite the softer top-line performance, the company maintained a solid operating margin of 10.8% and continued to deliver a strong gross margin.

    Cash and bank deposits declined to $132.8m during the year but remained at a comfortable level. The board maintained the total regular dividend at 240.0 cents per share, reflecting the group’s continued confidence in its financial position while still investing in staff, marketing initiatives, technology and infrastructure improvements.

    Operational activity showed mixed trends. Total orders decreased 3% to 2.06 million as new customer orders fell by 12%. However, orders from existing customers remained stable and the average order value increased by 1%, highlighting strong customer retention and the company’s ability to maintain pricing strength.

    The group is also progressing a project valued at approximately $10m to relocate its Oshkosh office to a larger distribution centre. Management said the business is managing cost pressures linked to tariffs and navigating a softer start to 2026 trading. At the same time, the board reiterated confidence in the company’s long-term strategy as leadership transitions continue, including the planned appointment of Paul Forman as chair.

    Overall, the company’s outlook is supported by strong financial health, disciplined capital management and a low-risk balance sheet. Attractive valuation metrics and positive technical signals add to the constructive view, while strategic leadership changes may help support future growth.

    More about 4imprint

    4imprint Group plc is a direct marketer of promotional merchandise operating in a large and fragmented global market for branded products. The company focuses primarily on organic expansion, aiming to increase market share through its highly cash-generative direct marketing model. Its strategy is built around strong brand recognition, long-standing supplier relationships and high levels of customer retention.

  • BATM Advanced Communications Increases Profits as It Refocuses on Networking and Cybersecurity

    BATM Advanced Communications Increases Profits as It Refocuses on Networking and Cybersecurity

    BATM Advanced Communications Ltd (LSE:BVC) reported revenue from continuing operations of $123.2m in 2025, compared with $117.3m the previous year on a comparable basis. Profitability improved significantly during the period, with gross profit rising to $40.1m and adjusted operating profit increasing to $14.7m from $3.8m a year earlier.

    Adjusted EBITDA more than doubled as the group benefited from improved operational performance and capital gains generated through business disposals. Gross margin strengthened to 32.5%, although cash and short-term investments declined to $23.4m by year-end.

    During 2025, the company executed a major strategic shift by selling four non-core businesses, followed by a fifth disposal after the year-end, generating a combined $24.4m. The divestments are part of a broader plan to simplify the organisation and redirect resources toward higher-growth areas such as networking and cybersecurity.

    The group’s networking division returned to strong growth, with revenue increasing 36% and a healthy project pipeline emerging for 2026. Meanwhile, the cybersecurity unit reported lower sales after an exceptionally strong 2024 driven by large orders, but it secured new development projects that are expected to support future growth.

    BATM has also reclassified its diagnostics activities as non-core. The proprietary diagnostics business moved from an adjusted operating loss of $1.8m in 2024 to a small profit in 2025 after shifting strategy toward reagent sales and completing the sale of its diagnostic distribution arm. That disposal generated a capital gain of $14.1m.

    Management also highlighted increasing collaboration between the networking and cybersecurity units, including joint sales efforts and integration of their technology platforms. This combined secure connectivity offering could help the group win larger contracts and deliver stronger results in the coming year.

    The company’s outlook remains mixed. While recent restructuring and strategic disposals are positive developments and technical indicators show improving momentum, profitability challenges and negative earnings still weigh on valuation metrics. Nonetheless, management believes the streamlined business is better positioned to compete in higher-margin secure networking and cyber markets.

    More about BATM Advanced Communications

    BATM Advanced Communications is a global technology provider specialising in advanced network infrastructure, cybersecurity and diagnostic solutions. Listed in both London and Tel Aviv, the company is increasingly concentrating on secure managed networking and cybersecurity through its BATM Networks and BATM Cyber divisions, while gradually reducing exposure to non-core diagnostics operations.

  • Nichols Boosts Profitability as Vimto Delivers Record UK Sales

    Nichols Boosts Profitability as Vimto Delivers Record UK Sales

    Nichols plc (LSE:NICL) reported a modest increase in group revenue for 2025, rising 1.3% to £175.1m, while profitability improved more sharply. Adjusted operating profit climbed 9.9% during the year as operating margins strengthened, supported by disciplined cost management and strategic changes across several business units.

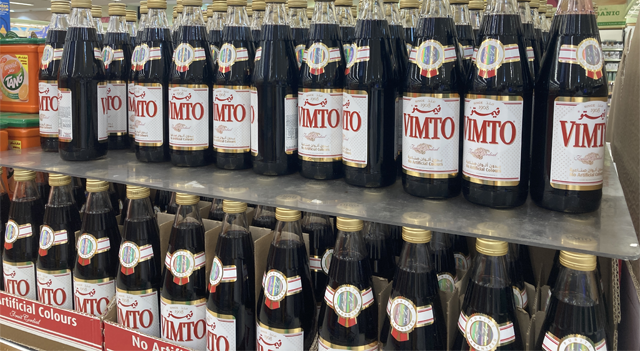
    The group benefited from record retail sales of its flagship Vimto in the UK Packaged division. International Packaged operations also performed strongly, helped by a transition to a higher-margin concentrate sales model in West Africa. Meanwhile, the company simplified its Out of Home segment and exited the lower-margin Starslush business as part of its efforts to streamline operations.

    Operational improvements were further supported by the introduction of a new enterprise resource planning (ERP) system, which has begun delivering efficiency gains across the organisation. Strong financial performance enabled Nichols to increase its ordinary dividend, reflecting management’s confidence in the strength of the balance sheet and the group’s medium-term growth prospects.

    The company’s outlook remains shaped by a combination of positive and challenging factors. Solid profitability and the appointment of a new chief financial officer represent supportive developments, while technical indicators currently show bearish momentum in the share price. Although the company maintains a stable financial position, it still faces pressure to accelerate revenue growth and strengthen cash flow generation.

    More about Nichols

    Nichols plc is a UK-based soft drinks group that operates an asset-light business model across three main channels: UK Packaged, International Packaged and Out of Home. The company’s portfolio is centred on the Vimto brand and also includes licensed beverages such as Levi Roots, ICEE, SLUSH PUPPiE and Sunkist. Its product range spans squash, flavoured carbonated drinks, fruit beverages, energy drinks and flavoured water, with a strong presence in markets across the Middle East and Africa.

  • Ascent Resources Bolsters Legal Position in Ongoing Slovenian Disputes

    Ascent Resources Bolsters Legal Position in Ongoing Slovenian Disputes

    Ascent Resources plc (LSE:AST) said its legal standing in a series of long-running disputes in Slovenia has been strengthened after a Slovenian court rejected a jurisdictional challenge brought by Geoenergo against a domestic arbitration tribunal. The ruling supports a claim by its subsidiary, Ascent Slovenia Limited, seeking roughly €7.8m in unpaid proceeds from hydrocarbon production along with accrued interest.

    The court decision reinforces the validity of the arbitration process and keeps the company’s claim moving forward. Additional rulings related to the recognition of the arbitration award, as well as a separate annulment case, are expected within the coming weeks or months.

    Despite the positive development, any potential recovery remains uncertain as it depends on the outcome of Geoenergo’s insolvency administration. The company is also continuing to defend claims filed by Petrol Geo while working toward a potential negotiated resolution among the parties.

    Separately, Ascent confirmed there have been no delays in its case under the Energy Charter Treaty being heard at the International Centre for Settlement of Investment Disputes (ICSID). The company still expects a tribunal decision on the merits this month, a development that could have a significant impact on its legacy Slovenian assets and any potential financial recovery.

    The company’s outlook remains constrained by financial pressures. It reported no revenue in 2024 and continues to face persistent losses, negative equity, rising debt and ongoing cash burn. Market indicators also show weak technical momentum, with the share price trading below key moving averages and a negative MACD signal. Valuation metrics remain neutral due to the absence of both price-to-earnings and dividend yield data.

    More about Ascent Resources

    Ascent Resources plc is a London-listed oil and gas company with a strategic focus on onshore U.S. energy assets while maintaining legacy interests in Slovenia. Through its wholly owned subsidiary Ascent Slovenia Limited, the company has previously participated in hydrocarbon production projects and joint ventures in the region. It is also pursuing legal claims linked to unpaid production proceeds and contractual disputes related to those operations.

  • Ariana Reports High-Grade Gold Intercepts at Dokwe, Highlighting Resource Expansion Potential

    Ariana Reports High-Grade Gold Intercepts at Dokwe, Highlighting Resource Expansion Potential

    Ariana Resources plc (LSE:AAU) has reported encouraging assay results from its 2025–2026 reverse circulation drilling programme at the 1.1-million-ounce Dokwe Gold Project in Zimbabwe. New high-grade intercepts at Dokwe North confirm that gold mineralisation extends beyond the boundaries of the existing resource model.

    The current drilling campaign has been expanded to 5,659 metres across 31 holes and suggests strong potential for additional near-surface oxide resources. Exploration results indicate that mineralisation continues up to 150 metres northeast of the present resource envelope, pointing to possible future resource growth.

    Among the most notable results were intercepts of 4 metres grading 16.90 grams per tonne gold and 10 metres at 7.67 grams per tonne. These grades reinforce the strength of the shear-hosted gold system at Dokwe and support expectations that the project could ultimately deliver a larger and higher-quality resource base.

    The company plans to move into a second phase of drilling at Dokwe North later in March, focusing on diamond drilling to refine geological interpretations. The programme will test potential extensions along strike and at depth while improving structural understanding of the deposit. The results are expected to support a possible update to the project’s resource estimate under the JORC reporting standard.

    While exploration progress remains encouraging, the company’s outlook is still influenced by underlying financial challenges, including ongoing operating losses and structurally negative operating and free cash flow. On the positive side, the balance sheet carries relatively low leverage. Technical indicators currently suggest supportive market momentum, with the share price trading above key moving averages and showing a positive MACD signal. Valuation appears moderate based on the available price-to-earnings metrics, although the absence of dividend yield limits income appeal.

    More about Ariana Resources

    Ariana Resources plc is a mineral exploration, development and production company focused primarily on gold projects across Africa and Europe. The business is listed on both AIM and the ASX and holds a 100% interest in the Dokwe Gold Project in Zimbabwe. The company is working to expand the project’s 1.1-million-ounce gold resource through ongoing drilling programmes and further exploration aimed at unlocking additional resource potential.

  • Breedon Reports Higher Revenue and Strong Cash Flow as It Advances Decarbonisation Plans

    Breedon Reports Higher Revenue and Strong Cash Flow as It Advances Decarbonisation Plans

    Breedon Group plc (LSE:BREE) reported revenue of £1.71bn for 2025, a 9% increase year on year, supported by the acquisition of Lionmark and a full-year contribution from BMC. The group delivered modest growth in underlying EBITDA despite weaker like-for-like volumes in the UK and project delays in Ireland.

    Profit before tax and earnings per share declined during the year, but the company generated record post-pandemic free cash flow of £133.2m. Improved free cash flow conversion and strong operating performance enabled Breedon to raise its dividend by 3%, highlighting the resilience of its cash generation and balance sheet flexibility.

    Management pointed to several operational improvements aimed at strengthening efficiency and profitability. These included adopting a simplified country-based organisational structure, implementing cost-saving measures in Great Britain and expanding strategically in Ireland. The company also continued to build its presence in the United States, particularly in Missouri, where it is involved in major infrastructure projects.

    Breedon is continuing to execute its EXPAND and IMPROVE strategy through targeted acquisitions, reserve extensions and operational efficiencies. At the same time, the group is advancing decarbonisation initiatives, including its participation in the Peak Cluster carbon capture project, while engaging with policymakers to encourage supportive regulatory frameworks for low-carbon cement production.

    While demand conditions remain mixed, particularly in the UK construction market, management said it remains cautiously optimistic. The company is maintaining a disciplined approach to capital allocation while pursuing growth opportunities across its geographic markets.

    Overall, Breedon’s outlook is supported by solid financial performance and strategic corporate actions. Although technical indicators suggest a degree of caution, the company’s valuation appears relatively attractive. Its proactive market strategy and continued stakeholder support provide additional confidence in its long-term prospects.

    More about Breedon

    Breedon Group is a vertically integrated construction materials company operating across Great Britain, Ireland and the United States. The group produces cement, aggregates, asphalt and ready-mixed concrete, supplying infrastructure, residential and commercial construction markets. Breedon is the largest cement producer in Great Britain and operates a network of quarries and downstream facilities, while also expanding its footprint in the United States.

  • NextEnergy Solar Fund Announces Strategic Reset to Target Higher Total Returns

    NextEnergy Solar Fund Announces Strategic Reset to Target Higher Total Returns

    NextEnergy Solar Fund Limited (LSE:NESF) has completed a strategic review and introduced a “strategic reset” designed to shift its focus from primarily delivering income to generating a balanced total-return profile. Under the revised approach, the fund is targeting long-term annual returns of 9%–11%.

    A key change involves moving away from a progressive dividend policy. Instead, the fund will distribute 75% of operating free cash flow, a structure expected to release roughly £40m over the next five years. Management plans to use this capital to reduce debt, repower existing solar assets and invest in higher-return opportunities. The dividend for the 2026/27 financial year is projected at between 4.0p and 4.6p per share, representing an estimated yield of around 7%–8% at current share prices.

    Alongside the revised payout model, the company intends to lower leverage to a target range of 40%–45% of gross asset value. It also plans to expand its asset recycling programme by selling up to 120MW of capacity and capturing additional realisations equivalent to 116MW starting from 2027. These measures are aimed at supporting renewed growth in net asset value.

    Operational improvements will include upgrading existing solar facilities and integrating co-located battery storage. Management expects energy storage exposure to rise to as much as 30% of gross assets over time. The board believes the strategic reset will help narrow the persistent discount to net asset value seen across listed renewable energy funds, strengthen the balance sheet and position the portfolio to benefit from rising demand for clean power aligned with the UK’s long-term energy transition goals.

    Despite these initiatives, the company’s outlook remains affected by recent financial pressures. Revenue has declined sharply and the business has recorded net losses in each of the past two years, while technical indicators suggest weak share price momentum. These challenges are partly balanced by strong operating cash flow, a debt-free position reported in 2025 and a relatively high dividend yield.

    More about NextEnergy Solar Fund

    NextEnergy Solar Fund Limited is a specialist infrastructure investor focused on utility-scale solar power generation and energy storage. Its portfolio includes 99 operational solar sites, primarily located in the UK, as well as a $50m commitment to private solar infrastructure. The fund seeks to deliver stable, inflation-linked cash flows through a mix of subsidised and merchant electricity sales while expanding into co-located and standalone battery storage as part of the UK’s accelerating transition to clean energy.