Author: Fiona Craig

  • Tullow Oil plc Agrees Landmark Refinancing With Noteholders and Glencore

    Tullow Oil plc Agrees Landmark Refinancing With Noteholders and Glencore

    Tullow Oil (LSE:TLW) has reached agreement on a wide-ranging refinancing with approximately two-thirds of its senior secured noteholders and Glencore, reshaping its debt profile and extending maturities. The transaction replaces the company’s 2026 senior secured notes with new “Extended Notes” due in November 2028, alongside new junior notes issued to Glencore maturing in 2030.

    The restructuring reduces near-term refinancing pressure, lowers overall cash interest costs and avoids equity dilution. It also introduces enhanced creditor oversight, including the appointment of at least three new independent non-executive directors and the creation of a dedicated value maximisation committee at board level.

    As part of the package, $1.285 billion of existing senior secured notes and Glencore’s $400 million facility will be written down and exchanged. The agreement also includes a mandatory repayment of at least $100 million on the new notes and establishes a new $100 million super senior cargo prepayment facility secured against Ghanaian oil cargoes.

    By extending its debt maturities and stabilising its capital structure, Tullow aims to create financial flexibility to deliver its 2026–2027 investment plans in Ghana. Priorities include securing licence extensions, addressing outstanding tax and receivable matters with the government, and advancing drilling programmes, gas monetisation projects and potential FPSO ownership initiatives. Management believes these steps could support long-term production stability and value creation for both creditors and shareholders.

    From an investment perspective, the company continues to face material balance sheet risks, including negative equity and elevated leverage, despite solid operating cash generation. Technical indicators show improving short-term momentum, though the broader long-term trend remains fragile. Valuation metrics offer limited comfort, with a negative price-to-earnings ratio and no dividend yield currently in place.

    More about Tullow Oil

    Tullow Oil plc is an independent upstream oil and gas company with its core producing assets in Ghana’s Jubilee and TEN fields. Listed in London and Ghana, the group focuses on exploration and production across West Africa, monetising crude oil and gas through established offtake and infrastructure arrangements while pursuing cost efficiencies and production optimisation to enhance reserves and cash flow generation.
  • Chemring Group plc Maintains FY26 Guidance as Record Order Book Underpins Growth

    Chemring Group plc Maintains FY26 Guidance as Record Order Book Underpins Growth

    Chemring (LSE:CHG) said trading for fiscal 2026 remains consistent with board expectations, despite a marginally slower start to the year. The group reported a record order book of £1.364 billion and noted that around 85% of expected revenues are already covered by first-quarter performance and contracted work. Demand continues to be supported by rising defence budgets among NATO members and allied nations, although first-quarter order intake was lower year on year following an unusually strong prior period that included several large, multi-year contract wins.

    Operationally, the company is centralising production at its automated Kilgore Flares facility in the United States. While this restructuring is expected to result in a non-cash impairment charge, management anticipates improved operational efficiency over time. Chemring is also progressing with substantial, debt-funded capital investment to expand capacity within its Energetics division, positioning the business to meet sustained demand for munitions and related products.

    The group acknowledged continued disruption in the UK defence market, driven by delays in strategic planning and procurement decisions. However, it pointed to improving order trends, new multi-year countermeasures agreements and ongoing progress at its Roke technology business. The company also confirmed a board change, with its senior independent director stepping down and an interim successor appointed.

    From a market perspective, Chemring’s fundamentals are supported by strong operational performance and positive commentary, particularly within Energetics. Nonetheless, technical indicators currently appear cautious, and a relatively elevated price-to-earnings ratio suggests valuation sensitivity. While the record order book and long-term defence spending trends underpin the growth case, cash flow pressures and valuation considerations temper the overall outlook.

    More about Chemring

    Chemring Group is a UK-based defence and security technology supplier serving military, security and space markets. The company operates through two primary divisions: Countermeasures & Energetics, and Sensors & Information. It provides advanced materials, munitions, countermeasure systems and specialist sensing technologies, with a core customer base spanning NATO countries and allied defence organisations.

  • SkinBioTherapeutics plc Appoints FRP Advisory for Independent Forensic Review

    SkinBioTherapeutics plc Appoints FRP Advisory for Independent Forensic Review

    SkinBioTherapeutics (LSE:SBTX), the AIM-listed skin health specialist based in Newcastle, has engaged FRP Advisory to carry out an independent forensic review into previously disclosed matters. The move is intended to bring clarity to outstanding issues and support the timely publication of interim results.

    The board has appointed new Non-Executive Director and Audit Committee Chair Alyson Levett to oversee the investigation process. Her role will include supervising the review on behalf of the board and ensuring appropriate governance standards are maintained throughout. Management said the objective is to conclude the process as swiftly as possible so that financial reporting can proceed with confidence and focus can return to operational priorities and growth initiatives.

    SkinBioTherapeutics continues to pursue expansion both organically and through acquisitions in complementary skincare and cosmetic segments, aiming to widen distribution channels, extend geographic reach and enhance manufacturing capabilities. The group seeks to apply its platform technologies across multiple skin health categories while leveraging consolidation opportunities to strengthen routes to market for its proprietary brands.

    From an investment standpoint, the company’s profile remains challenged by weak technical momentum and a pronounced downtrend in the share price, alongside ongoing losses and negative cash flow. These factors are partly balanced by strong revenue growth and what management describes as a relatively prudent balance sheet.

    More about SkinBioTherapeutics

    SkinBioTherapeutics is a UK life sciences company focused on dermatological health, built around its proprietary SkinBiotix technology originating from research at the University of Manchester. Its activities span cosmetic skincare and gut-skin axis supplements, marketed under brands including SkinBiotix and AxisBiotix, as well as Zenakine through a partnership with Croda. Products are distributed directly to consumers online, via Amazon and through selected Superdrug stores.

  • Anglo American plc Reports 2025 Loss While Advancing Teck Deal and Portfolio Overhaul

    Anglo American plc Reports 2025 Loss While Advancing Teck Deal and Portfolio Overhaul

    Anglo American (LSE:AAL) delivered a modest increase in underlying EBITDA from continuing operations to $6.4 billion in 2025, supported by solid production performance, disciplined cost management and strong margins in copper and premium iron ore. The group achieved $1.8 billion in annualised cost savings and reduced net debt to $8.6 billion, reflecting improved cash generation and tighter capital allocation.

    Despite these operational improvements, the company reported a $3.7 billion loss attributable to shareholders. The headline deficit was driven primarily by a $2.3 billion impairment at De Beers. At the same time, Anglo American is progressing with the disposal of its steelmaking coal, nickel and platinum businesses, while pursuing regulatory clearances for its proposed merger with Teck. The combination is expected to materially increase its copper exposure and reposition the group more firmly within the global critical minerals landscape.

    In addition to financial updates, the miner reported further advances in safety performance, lower greenhouse gas emissions and reduced freshwater usage, with most environmental and diversity objectives described as on track. The board upheld its 40% payout framework, declaring $0.2 billion in dividends, albeit at a lower per-share level than previous periods. Management characterised 2025 as a pivotal year focused on reshaping the portfolio, strengthening the balance sheet and laying foundations for long-term value creation through a more concentrated, growth-oriented asset mix.

    From a market perspective, sentiment is supported by positive technical momentum and the strategic implications of the Teck transaction. However, the negative earnings profile and relatively modest dividend yield weigh on valuation metrics, tempering the overall outlook despite progress on strategic objectives.

    More about Anglo American

    Anglo American is a diversified global mining company with core operations spanning copper, premium iron ore, manganese and crop nutrients. De Beers remains part of continuing operations under current accounting treatment. The group is actively repositioning toward critical minerals, with its proposed merger with Canada’s Teck intended to create a copper-focused mining leader positioned to benefit from long-term electrification and decarbonisation trends.

  • Aston Martin Lagonda Global Holdings plc to Monetise F1 Naming Rights as 2025 Performance Softens

    Aston Martin Lagonda Global Holdings plc to Monetise F1 Naming Rights as 2025 Performance Softens

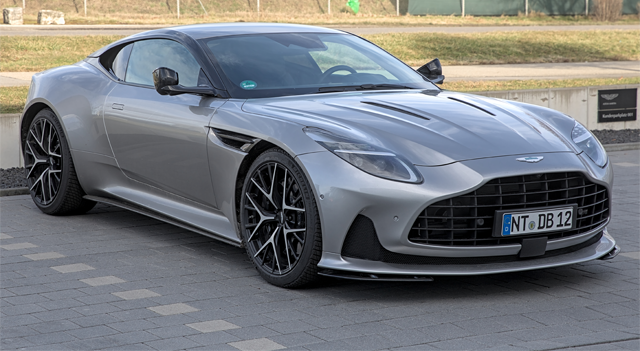
    Aston Martin Lagonda (LSE:AML) has reached an agreement in principle to sell the perpetual rights to use the Aston Martin name and chassis designation for the Aston Martin Formula 1 Team to AMR GP Holdings for £50 million. The transaction also covers certain F1-related branding rights.

    Because Executive Chairman Lawrence Stroll is connected to AMR GP, the deal qualifies as a substantial property transaction and related-party arrangement under UK Listing Rules. Shareholder approval is required, although backing is effectively assured, with investors representing 54.27% of the issued share capital already committed to vote in favour.

    Alongside the announcement, the company provided a trading update for 2025. Wholesale volumes totalled 5,448 vehicles, down from 6,030 the previous year, reflecting fewer high-margin special models and the impact of U.S. tariffs. Adjusted EBIT is expected to land slightly below the lower end of analyst forecasts.

    Cost-reduction initiatives have helped lower operating expenses and capital expenditure, while liquidity remained broadly stable at £250 million. Management anticipates that proceeds from the naming-rights sale, combined with a stronger product mix — including around 500 deliveries of the Valhalla — will support a meaningful financial recovery in 2026.

    The company’s independent directors, advised by Goldman Sachs International, have concluded that the terms of the transaction are fair and reasonable for shareholders. Strategically, the move unlocks value from Aston Martin’s Formula 1 association while maintaining its longer-term sponsorship presence, potentially reinforcing the balance sheet as the group continues its transformation programme and expands its model portfolio in a challenging luxury automotive market.

    From an investment standpoint, the outlook remains constrained by elevated leverage and ongoing losses. While short-term technical indicators show signs of recovery, the longer-term trend is still fragile. Valuation metrics are pressured by negative earnings, and macroeconomic headwinds continue to pose risks despite management’s efforts to stabilise operations and reposition the brand.

    More about Aston Martin Lagonda Global Holdings plc

    Aston Martin Lagonda is a British ultra-luxury performance car manufacturer headquartered in Gaydon, England. The company produces high-end sports cars and SUVs — including the Vantage, DB12, Vanquish, DBX and Valhalla — blending advanced engineering with traditional craftsmanship. Its vehicles are sold in more than 50 countries worldwide, with SUV production based in St Athan, Wales.

  • Pulsar Helium Inc. Raises £7.4m to Fast-Track U.S. Development Projects

    Pulsar Helium Inc. Raises £7.4m to Fast-Track U.S. Development Projects

    Pulsar Helium (LSE:PLSR) has secured approximately £7.4 million through an accelerated bookbuild placing in the UK, issuing 9,191,175 new shares at £0.80 per share. The transaction was led by OAK Securities as sole bookrunner and attracted participation from both new institutional and other investors. Admission of the new shares to trading on AIM is anticipated on or around 27 February 2026, subject to approval from the TSX Venture Exchange. Following admission, the company’s total voting share capital is expected to increase to 180,142,697 shares.

    The majority of the net proceeds will be directed toward advancing the Topaz helium project in Minnesota. Planned activities include extended well testing, further reservoir analysis, additional seismic surveys and completion of a pre-feasibility study covering integrated helium and carbon dioxide production. The company also intends to place deposits on long-lead processing equipment to support project timelines.

    A portion of the funds will be allocated to early-stage geophysical and geochemical exploration at the Falcon project in Michigan, alongside general working capital. Management believes the capital injection will accelerate development across its portfolio and reinforce its positioning in the emerging primary helium sector.

    More about Pulsar Helium, Inc.

    Pulsar Helium Inc. is a publicly listed primary helium exploration and development company, quoted on AIM, the TSX Venture Exchange and the OTCQB. Its asset base includes the flagship Topaz project in Minnesota, the Falcon project in Michigan and the Tunu project in Greenland. The company focuses on identifying and developing primary helium resources not associated with hydrocarbons, targeting first-mover opportunities in stable jurisdictions.

    Pulsar’s strategy centres on building an integrated helium production and processing platform across North America and Greenland, positioning the group to benefit from tightening global helium supply and increasing demand from technology, healthcare and industrial markets.

  • SEGRO Delivers Record Leasing and Expands Data Centre Ambitions

    SEGRO Delivers Record Leasing and Expands Data Centre Ambitions

    SEGRO (LSE:SGRO) reported a robust performance for 2025, achieving record new contracted rent of £99 million and like-for-like net rental income growth of 6.0 per cent. Adjusted earnings per share and dividends per share both increased by 6.1 per cent, supported by strong leasing activity and a high occupancy rate of 94.9 per cent. Development completions, the majority of which were pre-let, generated an attractive yield of 8.2 per cent.

    Management emphasised the scale of embedded growth within the existing portfolio, citing opportunities from rent reversion and leasing vacant space, alongside a sizeable pipeline of industrial, logistics and powered shell data centre projects. The group expects these drivers, combined with disciplined capital allocation and moderate leverage, to sustain rental growth and compound earnings and dividends over time.

    SEGRO estimates a further £152 million of potential rental uplift from its standing portfolio, in addition to up to £355 million of prospective new rent from developments across industrial, logistics and data centre assets. Targeted development yields are in the 7–8 per cent range. With one of Europe’s largest powered land banks dedicated to data centres, the company plans to increase development capital expenditure in 2026, leveraging its strengthened balance sheet to reinforce its presence in key European markets where demand for logistics and digital infrastructure continues to intensify.

    Overall, SEGRO’s outlook reflects solid financial foundations, supportive technical momentum and a valuation viewed as reasonable relative to growth prospects. While macroeconomic headwinds remain a consideration, the company’s strategic positioning in supply-constrained urban and logistics hubs, together with expanding data centre exposure, underpins confidence in its longer-term growth trajectory.

    More about SEGRO plc (REIT)

    SEGRO plc is a UK-listed real estate investment trust specialising in modern, sustainable industrial, logistics and data centre properties across Europe. Its portfolio is concentrated in prime urban areas and major transport corridors, serving customers seeking energy-efficient space to support e-commerce expansion, resilient supply chains and growing digital infrastructure requirements.

  • AstraZeneca Wins U.S. Approval for First Fixed-Duration, All-Oral CLL Regimen

    AstraZeneca Wins U.S. Approval for First Fixed-Duration, All-Oral CLL Regimen

    AstraZeneca (LSE:AZN) has received approval from the U.S. Food and Drug Administration for Calquence (acalabrutinib) in combination with venetoclax as the first fully oral, fixed-duration treatment for adults with previously untreated chronic lymphocytic leukaemia (CLL) or small lymphocytic lymphoma (SLL). The 14-month regimen offers a defined course of therapy, providing an alternative to indefinite treatment and enabling clinicians to tailor care to individual patient preferences and clinical needs.

    The decision is supported by data from the Phase III AMPLIFY trial, in which the Calquence–venetoclax combination demonstrated a statistically significant improvement in progression-free survival compared with standard chemoimmunotherapy. At the three-year mark, 77% of patients receiving the combination remained progression-free, versus 67% in the chemotherapy arm. The safety profile was consistent with prior experience of Calquence. The regimen has already been authorised in Europe, Canada, the U.K. and other markets, reinforcing AstraZeneca’s position in the first-line CLL setting.

    Beyond CLL, the company continues to evaluate Calquence both as monotherapy and in combination regimens across a range of B-cell malignancies, including mantle cell lymphoma and diffuse large B-cell lymphoma. The expanded U.S. label, alongside ongoing global regulatory activity, supports AstraZeneca’s ambition to strengthen its haematology franchise and broaden adoption of its BTK inhibitor-based therapies in a sizable and growing patient population.

    From an investment perspective, the company’s outlook remains underpinned by solid operational performance, earnings growth guidance and continued pipeline advancement. However, valuation metrics — including a price-to-earnings ratio around 30 — and variability in recent free cash flow temper the picture. Technical indicators suggest the shares remain in an overall uptrend, though momentum appears somewhat stretched.

    More about AstraZeneca

    AstraZeneca is a global, science-driven biopharmaceutical group headquartered in Cambridge, U.K. The company focuses on developing and commercialising prescription medicines across oncology, rare diseases and biopharmaceuticals, spanning cardiovascular, renal and metabolism, as well as respiratory and immunology. Its oncology and haematology portfolio has been strengthened through acquisitions including Alexion and Gracell Biotechnologies, with medicines marketed in more than 125 countries worldwide.

  • Digital 9 Infrastructure Proposes Compulsory Share Redemptions as Wind-Down Progresses

    Digital 9 Infrastructure Proposes Compulsory Share Redemptions as Wind-Down Progresses

    Digital 9 Infrastructure plc (LSE:DGI9) has issued a shareholder circular and convened a general meeting to approve amendments to its articles of association, introducing a compulsory redemption framework as part of its managed wind-down strategy. The proposed mechanism would enable the company to distribute cash to investors through pro rata redemptions of ordinary shares, which would be converted into redeemable shares for this purpose.

    The structure is designed to facilitate capital returns while ensuring the company retains adequate working capital and remains solvent in accordance with Jersey law. The first compulsory redemption is anticipated in late April 2026. The redemption price is expected to be set at a modest premium to the prevailing market price, subject to a cap at net asset value per share.

    Digital 9 said it intends to keep its London Stock Exchange listing in place for as long as feasible during the realisation process. The circular outlines technical details including ISIN adjustments, CREST settlement procedures and UK tax considerations. Shareholders are encouraged to review the documentation carefully and submit proxy votes ahead of the general meeting.

    Financially, the company’s profile remains under pressure, reflecting significant recent losses, negative revenue, declining equity and volatile cash flows. Technical indicators also suggest weakness, with the share price trading below key moving averages and momentum measures pointing lower. Valuation metrics offer limited guidance due to the absence of meaningful earnings and dividend data.

    More about Digital 9 Infrastructure Plc

    Digital 9 Infrastructure plc is a London-listed investment trust and constituent of the FTSE All-Share, focused on digital infrastructure assets such as data centres, subsea cables and telecommunications networks. The company is currently undertaking a managed wind-down of its portfolio, overseen by InfraRed Capital Partners as its AIFM and investment manager, with the objective of returning capital to shareholders in an orderly manner.

  • Metals Exploration Secures £643,000 from Option Conversions and Revises Voting Rights

    Metals Exploration Secures £643,000 from Option Conversions and Revises Voting Rights

    Metals Exploration PLC (LSE:MTL) has raised approximately £643,347 after receiving exercise notices for options covering 14,473,500 new ordinary shares at an average price of £0.0445. The shares are expected to be admitted to trading on AIM on or around 24 February 2026, providing a modest boost to the company’s equity base and reflecting the continued use of share-based incentives.

    Following admission, the company’s issued share capital will total 3,273,720,868 ordinary shares. Of these, 299,385,458 will be held in treasury, leaving 2,974,335,410 shares with voting rights. The revised figure becomes the benchmark for shareholders assessing their disclosure obligations under UK transparency rules. While the issuance results in slight dilution for existing investors, it clarifies the group’s updated capital structure.

    Operationally, the company’s outlook is underpinned by improving financial metrics, including revenue growth, stronger margins and healthy cash generation. Technical indicators reinforce the positive trend, though momentum measures suggest the shares may be approaching overbought territory in the near term. Valuation remains less supportive due to a negative price-to-earnings ratio and the absence of dividend yield data.

    More about Metals Exploration

    Metals Exploration PLC is a gold production, development and exploration company with principal assets in the Philippines and Nicaragua. Listed on AIM in London, the group focuses on advancing and expanding its gold operations in these jurisdictions to deliver production growth and long-term shareholder value.