Author: Fiona Craig

  • LSEG rises on report of Elliott position and engagement over strategic improvements

    LSEG rises on report of Elliott position and engagement over strategic improvements

    London Stock Exchange Group plc (LSE:LSEG) shares advanced more than 2% on Wednesday following reports that Elliott Investment Management L.P. had taken a stake in the business. The move buoyed a stock that, according to analysts at Barclays plc, has been the weakest performer among Europe’s exchange operators amid rising debate about artificial intelligence and its potential effect on data and analytics revenues.

    Barclays’ sector research indicates LSEG has lagged major European peers since mid-2025, with the bank describing the recent de-rating as “overdone” in its latest review.

    The report suggests investors have concentrated heavily on headline disclosures around LSEG’s data and analytics exposure. However, Barclays points to the company’s own segmental breakdown, which implies that only around 5% of total group revenue may be susceptible to AI-driven disruption.

    That calculation stems from LSEG’s assessment that roughly 10% of revenue within each of its two largest Data & Analytics units — Workflows and Data & Feeds — could be at risk.

    Even so, Barclays notes that the shares have experienced “the most aggressive” valuation compression across the peer group, despite the relatively modest revenue exposure implied by these disclosures.

    Pressure intensified after Anthropic PBC introduced its Cowork plug-ins and rolled out Claude Opus 4.6, developments that, in Barclays’ view, revived concerns about “terminal growth and even terminal value” for LSEG’s data-centric operations.

    The decline drove LSEG to three-year lows, with its valuation — excluding its stake in Tradeweb Markets Inc. — moving closer to levels more commonly associated with traditional asset managers, a segment Barclays characterises as “previously unloved.”

    By comparison, Barclays estimates potential AI-related revenue exposure at mid- to high-single-digit percentages for Deutsche Börse AG, primarily within ESG and index services, and in the low-single-digit range for Euronext N.V., where a larger proportion of data revenues is proprietary.

    Barclays argues that LSEG’s comparatively high reliance on data and analytics — accounting for 55% of group revenue, versus 16% at Euronext and 12% at Deutsche Börse — has placed it at the centre of investor anxiety.

    The bank adds that exchange operators more broadly have absorbed much of the sector’s AI-related de-rating, even though consensus earnings expectations for LSEG through FY27 have shifted by less than 5%.

    In Barclays’ view, the recent selloff appears sentiment-driven rather than reflective of weakening fundamentals. The broker reiterates its stance that concerns are “overdone,” highlighting LSEG’s existing data-licensing partnerships with Microsoft Corporation, Rogo AI Ltd, Databricks Inc., Anthropic and OpenAI, Inc.. Under these agreements, access to LSEG’s information by AI-tool users is restricted to licensed data feeds.
  • KEFI completes Tulu Kapi funding package as construction phase begins

    KEFI completes Tulu Kapi funding package as construction phase begins

    KEFI Gold and Copper plc (LSE:KEFI) has secured a US$20 million equity-ranking royalty investment from Chancery Royalty for its Tulu Kapi gold project in Ethiopia, effectively completing the funding coverage for its US$340 million development package.

    The remaining US$30 million of equity-risk capital is being finalised through a combination of KEFI share-settled development costs and additional royalty arrangements. The company also retains the option to raise Ethiopian birr-denominated preference shares to cover potential cost overruns, exploration activity and community-focused initiatives.

    With bank debt facilities, equity participation from the Ethiopian government and KEFI’s previous placings already in place, the group has begun mobilising contractors, progressed resettlement compensation and scheduled a formal groundbreaking ceremony this month. Major contracts covering infrastructure, housing, plant construction and mining services are close to completion, supporting a planned two-year build period. First gold production is targeted for 2028, with projected all-in sustaining costs of around US$1,000–1,150 per ounce and an estimated post-capital-servicing break-even price near US$1,400 per ounce.

    KEFI estimates that its 83% beneficial interest in Tulu Kapi could generate a post-capital-servicing net present value (5% discount rate) of between US$700 million and US$1.5 billion at the start of construction, increasing further at production depending on gold prices in a US$3,000 to US$5,000 per ounce range. Factoring in an initial valuation of its 13% stake in Saudi-based GMCO, the company calculates a fully diluted per-share value of 7 to 17 pence, positioning itself as a leveraged exposure to higher gold prices with limited additional default risk under its royalty and preference share structures.

    Despite the funding milestone, KEFI remains pre-revenue and continues to report losses and cash outflows, weighing on its financial profile. Technical indicators are comparatively supportive, with the share price trading above key moving averages and momentum signals turning positive, though valuation remains constrained by negative earnings and the absence of dividend support.

    More about KEFI Gold and Copper

    KEFI Gold and Copper is a mineral exploration and development company focused primarily on gold and copper assets in Ethiopia and Saudi Arabia. Its flagship project is the high-grade Tulu Kapi gold development in Ethiopia, complemented by a minority interest in GMCO in Saudi Arabia, where several gold and base metal deposits are being advanced toward potential production.

  • PZ Cussons unveils refreshed strategy targeting double-digit shareholder returns

    PZ Cussons unveils refreshed strategy targeting double-digit shareholder returns

    PZ Cussons plc (LSE:PZC) has set out a renewed group strategy at a capital markets event in London, outlining a more focused approach centred on strengthening portfolios of locally trusted brands across four core markets in both developed and emerging economies.

    Management said the business is now more streamlined and resilient following a recent strategic review, which included measures to reinforce the balance sheet and refine geographic and category priorities. The updated framework is designed to sharpen execution and concentrate resources on higher-return segments.

    The company is aiming to deliver double-digit total shareholder returns over the cycle. This ambition is supported by targets of mid-single-digit like-for-like revenue growth, high single-digit operating profit growth and high single-digit earnings-per-share expansion under its revised financial model.

    PZ Cussons also detailed a disciplined capital allocation policy. Net debt will be maintained within a defined range, the dividend is set to progress steadily, and excess cash will be directed toward bolt-on acquisitions in priority markets. The approach signals management’s intent to balance organic growth with selective expansion while sustaining returns to investors.

    While recent performance has reflected pressures on profitability and cash flow, improved earnings guidance and strategic clarity suggest potential for operational recovery. Market indicators and valuation metrics, however, imply a degree of investor caution as the company works to deliver on its updated objectives.

    More about PZ Cussons

    PZ Cussons is a Manchester-headquartered consumer goods business operating in personal care, home care and baby categories across the UK, Australia and New Zealand, Nigeria and Indonesia.

    Its portfolio includes well-known brands such as Carex, Childs Farm, Cussons Baby, Imperial Leather, Morning Fresh, Original Source, Premier, Sanctuary Spa, Stella and St.Tropez. The group combines brand development with a long-standing focus on sustainability and community impact.

  • Seeing Machines benefits from regulatory push as automotive and fleet volumes climb

    Seeing Machines benefits from regulatory push as automotive and fleet volumes climb

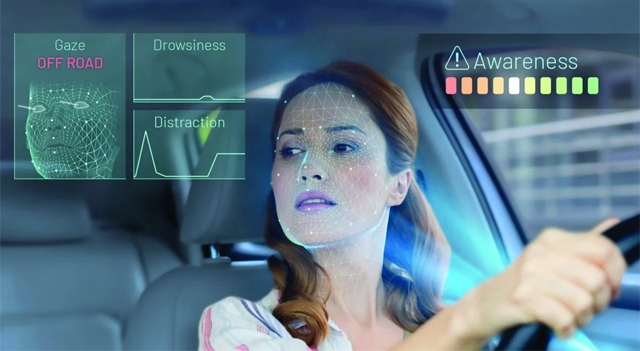
    Seeing Machines Limited (LSE:SEE) delivered strong expansion in its automotive driver and occupant monitoring segment, with the number of vehicles on the road equipped with its technology rising 67% year on year to around 4.8 million. Quarterly production volumes increased 13% compared with the prior quarter and were up 117% from a year earlier.

    Management expects royalty income to gather pace as European manufacturers step up installation of driver monitoring systems ahead of the EU’s 2026 General Safety Regulation requirements. The regulatory backdrop is reinforcing Seeing Machines’ role within next-generation vehicle safety systems.

    The company also reported a sharp recovery in sales of its Guardian aftermarket solution for commercial fleets. Hardware units sold rose to 3,764 in the quarter, up from 368 previously, helping lift annual recurring revenue modestly to $14.0 million.

    Chief executive Paul McGlone said the rebound in automotive production and Guardian volumes supports the company’s expectation of reaching positive adjusted EBITDA in the third quarter and across the second half of FY2026. This comes despite some delays in new requests for quotation (RFQs) and cumulative production volumes remaining below guaranteed thresholds.

    While regulatory-driven growth and cost measures aimed at achieving cash-flow breakeven provide encouragement, the investment outlook remains constrained by ongoing losses and negative operating cash flow. Near-term technical indicators also point to weaker momentum, partially offset by improved sentiment following recent operational updates.

    More about Seeing Machines

    Seeing Machines is headquartered in Australia and listed on AIM. The company specialises in AI-powered computer vision systems that monitor driver and occupant behaviour to enhance transport safety.

    Its technology is deployed by automotive manufacturers and commercial fleet operators, and is also applied in off-road and aviation settings, supporting safety and regulatory compliance across multiple transport sectors.

  • Barratt Redrow reports steady H1 performance as Redrow merger synergies build

    Barratt Redrow reports steady H1 performance as Redrow merger synergies build

    Barratt Redrow plc (LSE:BTRW) delivered a stable first-half performance despite subdued UK housing conditions. Total completions increased 4.7% to 7,444 homes, while adjusted operating profit remained broadly unchanged at £210.2 million. Adjusted profit before tax declined 13.6%, reflecting continued pressure on margins.

    On a statutory basis, profit before tax rose to £156.2 million, supported by lower transaction and integration costs related to the Redrow acquisition. The group ended the period with net cash of £173.9 million, even after accounting for dividends and share buybacks, underlining the strength of its balance sheet.

    Integration of the Redrow business is progressing in line with expectations. Cost synergies remain on track toward the £100 million target, driven by office consolidation, central function efficiencies and improved procurement terms. Revenue synergies are also advancing, particularly through planning initiatives across the enlarged land portfolio.

    Barratt Redrow continues to highlight its leadership in build quality and sustainability standards. The forward order book stands at 11,168 homes, valued at £3.41 billion. For FY26, the company expects completions between 17,200 and 17,800 units and anticipates full-year adjusted profit before tax to align with current market consensus, dependent on the strength of the crucial spring selling season.

    From an investment perspective, disciplined financial management and a robust balance sheet underpin the outlook, while the ongoing share repurchase programme enhances shareholder returns. However, profitability pressures, technical signals and valuation metrics suggest a degree of caution, with the shares appearing relatively expensive and lacking strong momentum.

    More about Barratt Redrow

    Barratt Redrow was formed through the combination of Barratt Developments and Redrow and is one of the UK’s leading housebuilders. The group operates across private and affordable housing markets, leveraging a substantial land bank and nationwide divisional structure to drive scale, efficiency and volume growth.

    Its strategy emphasises build quality, customer satisfaction and sustainability, positioning the enlarged business to compete across a broad range of residential segments.

  • Jangada Mines secures £1.2m to progress Molly and Paranaíta gold assets in Brazil

    Jangada Mines secures £1.2m to progress Molly and Paranaíta gold assets in Brazil

    Jangada Mines plc (LSE:JAN) has raised £1.2 million via an oversubscribed placing and director subscription priced at 1.4 pence per share. The fundraising resulted in the issue of 85,714,281 new shares, each accompanied by a two-year warrant exercisable at 2.25 pence.

    The proceeds will be directed toward drilling, geophysical surveys and geological analysis at the high-grade Molly Gold Project, alongside continued exploration at the Paranaíta Gold Project in Brazil. A portion of the funds will also support general working capital requirements.

    At Molly, Jangada plans to undertake a 2,000-metre drilling campaign aimed at confirming and expanding the existing 130,000-ounce JORC-compliant resource. The programme will also test western extensions of the deposit, with the objective of delineating a potential multi-pit development scenario.

    At Paranaíta, where the current exploration target stands at 210,000 ounces, management is seeking to grow the resource base toward approximately 350,000 ounces. Pending assay results are expected to inform additional drilling and resource modelling, supporting the development of a shallow open-pit opportunity. Together, the two projects form part of Jangada’s strategy to build scale within its Brazilian gold portfolio and enhance its future production potential.

    From an investment standpoint, the company remains pre-revenue and continues to report recurring losses and cash outflows, despite operating without debt. Technical indicators are relatively supportive, with the share price trading above key moving averages and showing moderate positive momentum. However, valuation metrics remain constrained by negative earnings and the absence of dividend support.

    More about Jangada Mines plc

    Jangada Mines is an AIM-quoted natural resources developer focused on gold assets in Brazil. The group targets shallow, high-grade and data-rich projects in established gold districts, pursuing low upfront acquisition costs and a staged funding model linked to exploration milestones. Its broader aim is to assemble a scalable, multi-asset gold portfolio.

  • Renalytix targets higher FY2026 revenue as kidney test rollout accelerates in the U.S.

    Renalytix targets higher FY2026 revenue as kidney test rollout accelerates in the U.S.

    Renalytix plc (LSE:RENX) reported unaudited revenue of $1.6 million for the first half of fiscal 2026 and is guiding to full-year revenue of approximately $4 million, representing year-on-year growth of around 33%. The uplift is being driven by faster integration of its kidneyintelX.dkd test into electronic medical record (EMR) systems across U.S. healthcare networks.

    The company is preparing a large-scale EMR integration with a major regional health system, which could extend access to more than 40,000 chronic kidney disease patients. Alongside commercial expansion, Renalytix is relocating its laboratory operations to lower its cost base, advancing a real-world evidence programme and progressing its collaboration with Tempus AI, Inc..

    Management is also preparing additional clinical data intended to support broader physician adoption and improved reimbursement coverage from payers. These initiatives form part of a strategy to deepen penetration within U.S. healthcare systems and strengthen the long-term commercial case for its technology.

    Despite the operational momentum, the company’s outlook remains constrained by continued losses, negative equity and ongoing cash burn. Technical indicators also suggest a weak trend, with the share price trading below key moving averages and momentum signals remaining negative. While recent corporate updates and oversold conditions offer some counterbalance, financial and trend risks continue to weigh on the investment profile.

    More about Renalytix

    Renalytix is a London- and New York-based developer of artificial intelligence-driven in vitro diagnostics aimed at improving kidney disease management. Its flagship product, kidneyintelX.dkd, is the only FDA-approved and Medicare-reimbursed prognostic test for early-stage risk assessment in chronic diabetic kidney disease, and is being deployed across major healthcare systems in the United States.

  • Gattaca tops H1 forecasts as contract momentum and cyber expansion fuel progress

    Gattaca tops H1 forecasts as contract momentum and cyber expansion fuel progress

    Gattaca plc (LSE:GATC) delivered a stronger-than-expected first half in FY2026, with total net fee income (NFI) projected to rise to £21.2 million from £18.9 million a year earlier. On a like-for-like basis, NFI increased 7%, reflecting solid demand for contract talent across its core markets.

    Contract NFI advanced 13% year on year on a comparable basis, while permanent placement income held steady. Statement-of-work revenue declined, primarily due to delays in client programmes. During the period, the group reduced its sales headcount by 6% as part of efficiency measures, while continuing to focus investment on priority growth areas.

    Gattaca is forecasting adjusted profit before tax of £4.5 million for the full year and plans to expand its sales workforce by around 10% over the remainder of FY2026, signalling confidence in sustainable growth. Net cash stood at £13.0 million, down from prior levels following working capital outflows, the acquisition of InfoSec People Limited and dividend distributions.

    Management highlighted the successful integration of InfoSec, which has strengthened the group’s cyber recruitment offering and supported contract-driven growth. The company intends to reinstate interim dividends, underlining its positive outlook and commitment to shareholder returns.

    From an investment perspective, supportive technical signals and favourable corporate developments underpin the near-term view. Although financial performance remains mixed in certain areas, a reasonable valuation and an attractive dividend yield add to the stock’s appeal.

    More about Gattaca

    Gattaca is a UK-based provider of specialist staffing solutions, offering contract, permanent and statement-of-work recruitment services. The group focuses on high-growth sectors, particularly technology and cyber security, and has reinforced its position in cyber recruitment through the acquisition and integration of InfoSec People Limited.

  • Renishaw delivers record first-half sales and upgrades confidence for FY2026

    Renishaw delivers record first-half sales and upgrades confidence for FY2026

    Renishaw plc (LSE:RSW) reported record revenue of £365.6 million for the first half of FY2026, representing a 7.1% increase year on year. Growth was broad-based across Industrial Metrology, Position Measurement and Specialised Technologies, with particularly strong demand in the Americas and Asia-Pacific regions.

    Adjusted operating margin improved to 15.7%, while adjusted profit before tax rose 11.5%. Statutory profit, however, was reduced by £18 million of restructuring-related redundancy and impairment costs, reflecting investment in productivity improvements and additional capacity to support an expanding order book.

    The company highlighted robust momentum in defence and semiconductor markets, as well as in newer product categories including additive manufacturing systems, coordinate measuring and gauging solutions, and enclosed optical encoders. Although general industrial markets remain mixed and currency and tariff pressures persist, management reiterated confidence in delivering strong full-year growth.

    For FY2026, Renishaw is guiding to revenue in the range of £740 million to £780 million and adjusted profit before tax of £132 million to £157 million. The interim dividend has been maintained, with the group emphasising its solid balance sheet and improved return on invested capital.

    From an investment perspective, Renishaw benefits from strong financial resilience and supportive technical signals. However, its valuation remains elevated and sector-specific headwinds, including cost pressures, require continued operational discipline to sustain margins.

    More about Renishaw

    Renishaw is a worldwide provider of high-precision measurement and manufacturing systems. Its sensor-driven and software-enabled technologies deliver accurate, traceable data for industrial clients across sectors such as semiconductors, defence and electrification.

    The group conducts significant research and development in the UK, with manufacturing operations spanning the UK, Ireland and India.

  • IG Design upgrades outlook as cash position strengthens and distribution plans take shape

    IG Design upgrades outlook as cash position strengthens and distribution plans take shape

    IG Design Group plc (LSE:IGR) has refocused its business following the disposal of DG Americas, with operations now centred on its continuing European and international activities. Reflecting the streamlined structure, the group will switch its reporting currency to sterling, aligning financial presentation with its primary operating base.

    For the year ending 31 March 2026, IG Design expects revenue in the region of $280 million to $285 million and an adjusted operating margin of roughly 4%. Both metrics sit at the upper end of prior guidance and ahead of market forecasts. Robust cash generation — supported by disciplined working capital management and the planned sale of a UK warehouse — is projected to lift net cash to between $55 million and $60 million, significantly exceeding earlier expectations.

    Looking further ahead, the group is maintaining guidance for modest annual revenue growth of 0–5%, adjusted operating margins of 4–5%, and sustainable cash generation of $6 million to $8 million per year. Management continues to focus on long-term growth initiatives designed to enhance returns beyond core trading performance, reinforcing its post-disposal strategic repositioning.

    Shareholders have approved a capital reduction to establish distributable reserves, paving the way for potential shareholder returns once a formal capital allocation policy is outlined in June. Meanwhile, the search for a permanent chief executive remains ongoing, with Interim Executive Chair Stewart Gilliland providing leadership continuity during the transition.

    Despite the improved cash outlook, the company’s investment profile remains weighed down by recent loss-making margins and pressured free cash flow. Technical indicators are currently negative, with the share price trading below key moving averages, while valuation metrics reflect the absence of earnings and dividend support.

    More about IG Design

    IG Design Group designs and manufactures products across celebration and creative categories, supplying retailers and consumer markets with items such as gift wrap and related goods. Following the sale of its DG Americas division in 2025, the group now concentrates on its remaining operations, primarily in the UK and other international markets, and will report its results in GBP going forward.