Author: Fiona Craig

  • Market Open: Bellway Completions, Seeing Machines Royalties

    Market Open: Bellway Completions, Seeing Machines Royalties

    UK markets open flat as Bellway lifts completions, Seeing Machines reports record royalties and Brent crude remains sensitive to Iran tensions.

    Market Overview

    The FTSE 100 opened broadly unchanged, up 0.001 per cent at 10,862.85, while the Euronext 100 was also effectively flat at 1,972.91 and Germany’s DAX edged 0.01 per cent higher to 26,327.10. European markets remained cautious as renewed US-Iran tensions and uncertainty over the Strait of Hormuz kept energy risks in focus, while softer UK retail sales added pressure domestically. Overnight in the US, the Nasdaq closed lower at 26,605.36 and the S&P 500 also declined to 7,753.11, with investors looking ahead to US inflation data and assessing elevated technology valuations.

    Commodity markets were softer at the open, with copper, gold, Brent crude and natural gas all declining from their previous closes. Oil nevertheless remained supported by fading hopes of a US-Iran agreement and continuing concerns over flows through the Strait of Hormuz. Bitcoin rose against sterling. Currency moves were limited, with the US dollar, Swiss franc, euro and Japanese yen strengthening marginally against sterling, while the Australian dollar weakened slightly.


    Market Numbers

    FTSE 100: Up (0.001%), 10,862.85
    Euronext 100: Up (0.001%), 1,972.91
    DAX: Up (0.01%), 26,327.10
    NASDAQ: Down, 26,605.36
    S&P 500: Down, 7,753.11


    In the Headlines

    Higher completions and cash – Bellway (LSE:BWY)
    The housebuilder reported a 10.8% increase in housing completions to 9,695 homes, while housing revenue rose to £3.14 billion and net cash strengthened to £157.7 million. Stronger cash generation is supporting continued share buybacks, although Bellway remains cautious over subdued demand and housing market conditions.

    Record automotive royalties – Seeing Machines (LSE:SEE)
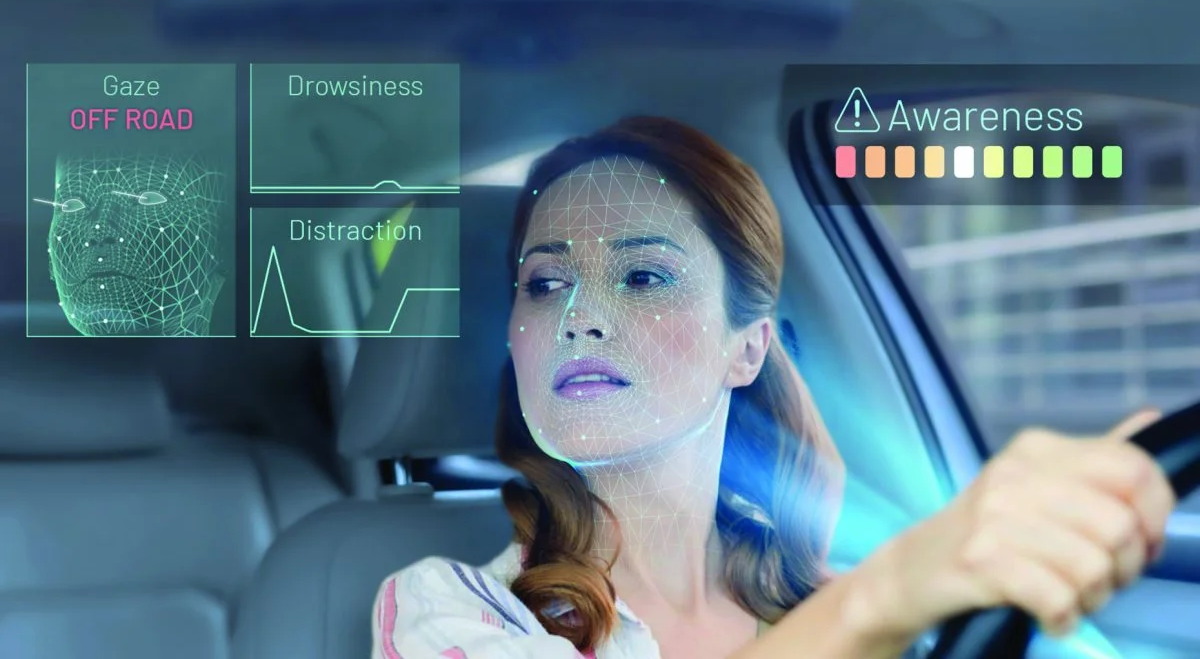
    The driver and occupant monitoring technology group reported adjusted revenue growth of 45%, with automotive production volumes rising sharply and royalty revenue more than doubling. The improved revenue mix helped Seeing Machines achieve a profitable second half and move closer to full-year breakeven, supported by growing automotive adoption and European driver-monitoring requirements.


    Currencies (vs GBP)

    USD: Up (0.001%), $1.3511
    CHF: Up (0.001%), Fr.1.0942
    EUR: Up (0.01%), €1.1702
    JPY: Up (0.001%), ¥215.0305
    AUD: Down (-0.01%), $1.9151
    Bitcoin (BTC/GBP): Up, £47,442.65


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Down
    Natural Gas: Down

  • Oil Prices Surge Over 2% as Iran Deal Setback Keeps Hormuz Supply Risks Elevated

    Oil Prices Surge Over 2% as Iran Deal Setback Keeps Hormuz Supply Risks Elevated

    Oil prices extended their rally on Tuesday, reaching their highest levels in more than a week as diminishing prospects for a U.S.-Iran peace agreement increased uncertainty over when the Strait of Hormuz could fully reopen.

    Brent crude futures climbed $1.92, or 2.19%, to $89.64 a barrel by 0805 GMT. U.S. West Texas Intermediate futures advanced $1.91, or 2.33%, to $84.04 a barrel, putting both benchmarks at their highest levels since July 31.

    The gains followed a surge of more than 5% for both contracts on Monday. The rally accelerated after President Donald Trump responded to Iran’s conditions for a peace agreement by demanding that Tehran provide compensation for people killed in wars, attacks and protests.

    Those demands have added another complication to negotiations aimed at ending the conflict and restoring normal shipping through the Strait of Hormuz.

    Trump later said the United States controlled the strait and had cleared Iranian mines from the strategically important energy route.

    Hormuz shipping data points to continued supply disruption

    Restrictions on shipping remain a central factor supporting crude prices.

    “There’s no clear path to a solution and to a full reopening of the strait at this point in time and that’s adding renewed upside pressure on prices,” Saxo Bank head of commodity strategy Ole Hansen said, adding that meaningful supply disruption remains in place.

    Only six vessels travelled through the Strait of Hormuz on Monday, according to shipping data, well below the 10-day average of approximately 11 vessels.

    Barclays analysts said net exports of crude and refined petroleum products through the waterway averaged 3 million barrels per day during the week ending August 7. That compares with 4.4 million bpd in the preceding week.

    The scale of the disruption is particularly significant because around one-fifth of daily global oil and liquefied natural gas supplies passed through the Strait of Hormuz before the Iran conflict began in late February.

    Saudi refinery delay adds another regional supply concern

    Oil markets are also monitoring developments elsewhere in the region after Saudi Aramco postponed the restart of its 400,000-barrel-per-day Jazan refinery until August 30.

    The delay followed two attacks on the facility on Sunday that were claimed by the Houthis.

    “The chokehold risk around both the Strait of Hormuz and the Bab el-Mandeb remains highly significant. Even intermittent restrictions or the threat of further incidents keep insurance costs elevated and force longer shipping routes … hence energy flows look likely to stay constrained near term,” said Tim Waterer, chief market analyst at KCM Trade.

    The combination of shipping restrictions and threats to regional energy infrastructure is keeping transportation costs and supply risks elevated.

    ADNOC continues spot crude tenders

    Abu Dhabi National Oil Company, or ADNOC, is meanwhile offering another cargo of spot crude through a tender as the UAE state producer works to move supplies from inside the Strait of Hormuz.

    The latest sale represents ADNOC’s eighth such tender since the beginning of June.

    With diplomatic negotiations yet to provide a clear route towards reopening the strait and other regional shipping corridors facing disruption risks, crude markets remain highly sensitive to developments affecting Middle Eastern energy flows.

  • Gold Rally Extends to Two-Month High as U.S. Inflation and Hormuz Risks Drive Demand

    Gold Rally Extends to Two-Month High as U.S. Inflation and Hormuz Risks Drive Demand

    Gold remained close to its highest level in more than two months on Tuesday as buying momentum continued despite a firmer dollar, rising Treasury yields and stronger energy prices.

    At 00:56 ET (04:56 GMT), XAU/USD rose 0.4% to $4,407.79 an ounce, while gold futures climbed 1.1% to $4,467.59. XAG/USD declined 0.5% to $65.41 an ounce, while XPT/USD increased 0.2% to $1,761.10.

    U.S. inflation becomes the next test for gold

    Bullion’s advance gained momentum on Friday, when it jumped 2.4% following an unexpected contraction in U.S. nonfarm payrolls for July. Gold extended that strength on Monday, closing around $4,390 after gaining 1.11%, its highest daily finish in almost 10 weeks.

    The move has come despite several market forces that would normally work against the precious metal. The U.S. dollar, Treasury yields and energy prices have all strengthened, yet gold has continued to attract buyers.

    Tony Sycamore, senior market analyst at IG, pointed to several possible drivers, including buying from investors who missed the earlier decline towards $4,000, speculative short-covering and renewed demand for safe-haven assets.

    The next major test comes from U.S. inflation figures, with the consumer price index scheduled for Wednesday followed by producer prices on Thursday.

    Markets currently assign a 52% probability to a September interest-rate increase and an 81% chance of a December hike, according to CME FedWatch.

    That outlook matters for bullion because higher interest rates typically make non-yielding assets such as gold relatively less attractive.

    Hormuz dispute keeps geopolitical risk elevated

    Uncertainty surrounding the Strait of Hormuz is providing another source of support for safe-haven demand.

    Iran said it was nearing a final agreement with Oman over new shipping lanes through the strategically important waterway, although Tehran maintained that Washington must meet further conditions before traffic can resume.

    Prospects for a breakthrough have been complicated by stalled U.S.-Iran negotiations and President Donald Trump’s demand for compensation from Iran.

    The resulting uncertainty has helped push oil prices higher again, increasing concerns that elevated energy costs could feed through to inflation. Persistent energy-driven price pressures could make it more difficult for the Federal Reserve to consider easing monetary policy.

    China’s gold purchases strengthen underlying demand

    Chinese demand is also contributing to the supportive backdrop for bullion.

    The People’s Bank of China increased its gold holdings in July by the largest amount since October 2023, pointing to continued demand from the official sector.

    The U.S. Dollar Index, meanwhile, was little changed near 99.8 after strengthening alongside crude prices.

    Sycamore said gold’s rebound from its June low of $3,942 has brought an important technical resistance area back into view.

    Downtrend resistance sits around $4,460, while the 200-day moving average provides another potential barrier near $4,495.

    The $4,460 to $4,500 range could initially restrict the rally, according to Sycamore. A sustained move through that zone, however, could provide scope for a broader recovery towards $5,000.

  • Wall Street Futures Steady as Iran Tensions Lift Oil and Intel Completes $20 Billion Share Sale: Dow Jones, S&P, Nasdaq

    Wall Street Futures Steady as Iran Tensions Lift Oil and Intel Completes $20 Billion Share Sale: Dow Jones, S&P, Nasdaq

    U.S. equity futures showed little movement on Tuesday as markets balanced another increase in oil prices against major developments in artificial intelligence and semiconductors, with upcoming inflation figures also keeping investors cautious.

    At 03:05 ET (07:05 GMT), Dow futures slipped 51 points, or 0.1%, while futures tracking the S&P 500 and Nasdaq 100 were broadly unchanged.

    Stocks had finished lower in the previous session after prospects for reopening the Strait of Hormuz deteriorated, sending crude prices higher. The renewed energy rally raised concerns that more expensive fuel could add to inflationary pressures and make the monetary policy outlook more difficult for central banks.

    Treasury yields also moved higher, creating another headwind for equities.

    Nvidia financing plan puts AI spending back under the spotlight

    Nvidia (NASDAQ:NVDA) confirmed an extensive AI infrastructure arrangement involving financial groups including Apollo, BlackRock, Goldman Sachs and KKR.

    The initiative is designed to mobilise more than $500 billion in third-party capital for infrastructure needed to support the continued expansion of artificial intelligence.

    Nvidia shares declined more than 2% after the Financial Times first reported the development.

    Vital Knowledge analysts described the move as another case of Nvidia “extending its balance sheet to drive AI infrastructure demand.”

    The reaction highlights growing sensitivity towards the scale of spending required to support the AI boom. Questions around the sustainability of these investments have weighed on technology sentiment in recent weeks, despite broadly resilient quarterly results from S&P 500 companies.

    Iran reparations dispute reduces hopes for rapid agreement

    Geopolitical risk remains another major consideration for markets after U.S. President Donald Trump rejected fresh demands from Iran, reducing expectations for an imminent breakthrough in peace negotiations.

    Tehran’s proposals included a demand for the United States to pay reparations for damage caused during the conflict, which has continued for more than five months.

    Trump said Iranian negotiators had not previously raised the issue and argued that Iran should instead compensate Washington “for all of the people that they have killed and gravely wounded with their roadside bombs and many conflicts.”

    The continued diplomatic deadlock has kept the Strait of Hormuz effectively closed, restricting an important route for global energy supplies. Before fighting began in late February, roughly one-fifth of global oil and liquefied natural gas moved through the waterway.

    Brent crude futures rose another 1.8% to $89.34 a barrel as traders responded to the reduced likelihood of a near-term agreement.

    Riot Platforms rallies after Anthropic identified as data centre customer

    Riot Platforms (NASDAQ:RIOT) surged more than 20% in after-hours trading after Anthropic was reportedly identified as the customer behind Riot’s previously announced data centre contract.

    Bloomberg reported that the AI company agreed to pay $9.1 billion under a long-term arrangement securing computing capacity as it expands infrastructure for its Claude products.

    The contract covers 191 megawatts at Riot’s Rockdale campus in Texas and is scheduled to run until June 2048.

    Riot expects $9.1 billion of revenue from the initial contract period. Two five-year extension options could potentially increase total sales to as much as $16.1 billion.

    Intel expands equity raise to $20 billion

    Intel Corporation (NASDAQ:INTC) completed an upsized $20 billion stock offering as the semiconductor manufacturer seeks additional financial capacity for its manufacturing plans.

    The company priced 210.5 million common shares at $95 each, representing a 2.6% discount to its previous closing price. Underwriters also received a 30-day option covering up to another 31.6 million shares.

    Intel had initially targeted proceeds of $15 billion before increasing the offering. The company said the funds would be available for general corporate purposes.

    Intel shares declined more than 4% on Monday. The stock has nevertheless risen sharply this year as investors assess the company’s plans for substantial spending on manufacturing facilities and advanced chip packaging as it competes with foundry rivals including TSMC.

    RBA pauses after 75 basis points of rate increases

    The Reserve Bank of Australia kept its benchmark interest rate at 4.35%, matching market expectations after recent inflation figures showed signs of moderation.

    The decision was unanimous and follows a cumulative 75 basis points of rate increases this year.

    A softer-than-expected second-quarter consumer inflation reading had strengthened expectations for the RBA to hold rates, while policymakers also lowered their inflation projections for the end of 2026.

    The central bank nevertheless warned that headline and underlying inflation remain high and could stay elevated in the near term.

    Fuel costs associated with the Iran conflict were highlighted as an important source of inflationary pressure, meaning policymakers have not ruled out further interest-rate increases.

  • European Stocks Stall Near Records as Hormuz Tensions and Oil Rally Test AI Momentum: DAX, CAC, FTSE100

    European Stocks Stall Near Records as Hormuz Tensions and Oil Rally Test AI Momentum: DAX, CAC, FTSE100

    European equities hovered around the flatline near record highs as renewed Middle East tensions and another jump in crude oil prices tempered market momentum, while a volatile earnings season increased scrutiny of elevated technology and artificial intelligence valuations.

    The pan-European Stoxx Europe 600 Index was little changed, remaining just below its all-time highs. Energy stocks outperformed as crude prices climbed to their highest levels since July 31, while capital-goods companies, media stocks and technology suppliers lagged.

    Hormuz negotiations keep markets on edge

    The subdued performance across European markets reflects growing sensitivity to developments surrounding the Strait of Hormuz.

    Stocks have repeatedly responded positively to preliminary reports of progress in Gulf diplomatic negotiations, only for geopolitical risk to return when discussions encounter political obstacles.

    The latest setback followed U.S. President Donald Trump’s response to an Iranian draft proposal with Oman concerning new transit coordinates through the Strait of Hormuz.

    Trump pushed for more stringent terms, including demands that Tehran provide direct financial compensation for lives lost in regional conflicts, attacks and protests. The tougher position represents an escalation in rhetoric that could complicate mediation efforts being pursued by Muscat and Qatar.

    Brent crude subsequently moved towards multi-week highs above $84 a barrel, adding another source of uncertainty for European investors.

    Higher oil prices add pressure during earnings season

    The increase in energy costs comes as markets are already dealing with substantial individual stock volatility during the second-quarter earnings season.

    European corporate results have produced solid headline beats overall, with healthcare, power infrastructure and defence among the areas providing support.

    Technology companies and industrial suppliers, however, are facing greater scrutiny. Mixed results from major global hardware companies have triggered pronounced moves throughout semiconductor supply chains.

    Investor attitudes towards artificial intelligence spending are also becoming more selective. Markets are showing greater reluctance to reward large capital expenditure commitments to AI infrastructure when there is limited visibility over how quickly those investments will translate into revenue.

    That shift is adding pressure to a technology sector that has been a major contributor to this year’s equity rally.

    Investors await U.S. inflation data

    Rapid sector rotations are making the environment more difficult for fund managers, who are balancing inflation risks from higher energy prices against signs of slowing global economic growth.

    Attention is now turning to Wednesday’s U.S. Consumer Price Index report.

    Following last week’s unexpected contraction in U.S. payrolls, investors are looking for clearer evidence that underlying inflation is slowing sufficiently to allow central banks in the United States and Europe to keep monetary policy unchanged through the autumn.

    Until there is greater clarity on inflation and shipping through the Strait of Hormuz, European equity markets could remain particularly sensitive to geopolitical headlines, energy prices and company earnings.

  • FTSE 100 Slips as U.S.-Iran Tensions and Weak UK Retail Sales Weigh

    FTSE 100 Slips as U.S.-Iran Tensions and Weak UK Retail Sales Weigh

    UK equities moved modestly lower on Tuesday as renewed tensions between the United States and Iran combined with disappointing British retail sales data to dampen investor sentiment.

    As of 03:23 ET (07:23 GMT), the FTSE 100 was down 0.08%. Germany’s DAX declined 0.06%, while France’s CAC 40 fell 0.07%. Sterling was unchanged against the dollar at $1.3501.

    Geopolitical risk remained firmly in focus after the Washington Post reported that U.S. President Donald Trump used a decoy operation when leaving Turkiye following the NATO summit on July 8 because of a potential Iranian threat.

    According to the report, Trump was covertly transferred by catering truck to a smaller C-32A aircraft, while the traditional Air Force One continued its journey carrying journalists and some White House personnel.

    A U.S. official described the situation as involving a “credible threat” from Iran.

    A White House spokesperson defended the security measures, saying “there are many enemies of America who have their sights on him, and we use every tool at our disposal to address those threats.”

    Tensions surrounding the Strait of Hormuz also remained elevated. Trump told reporters on Monday that the U.S. Navy has “100 per cent control” of the strategically important waterway, describing the blockade as “infallible” and a “steel wall.”

    Iran’s Revolutionary Guard Corps, meanwhile, maintained that the Strait would remain a “theatre of war” until Washington meets Tehran’s conditions, including financial restitution.

    Trump also reiterated his demand for reparations in a Truth Social post, saying Iran should provide compensation for the “last five month Military Conflict.”

    In a separate post, he said Iran “should be responsible for the damages and death caused to the people of Lebanon, Syria, Yemen, and Gaza.”

    Weak retail data adds pressure on UK stocks

    Domestic economic data provided another headwind after UK retail sales growth slowed considerably in July.

    Total sales increased 1.3% year on year, according to BRC-KPMG data, compared with growth of 2.5% a year earlier and below the 12-month average of 1.8%.

    Food sales increased 3.8%, helped by the closing stages of the World Cup, but non-food sales declined 0.7%.

    “Consumer demand has struggled in the heat, leaving retailers facing a challenging start to the second half of the year,” said Helen Dickinson, chief executive of the British Retail Consortium.

    Dickinson added that “household budgets remain stretched” and called on the government to reduce business rates and regulatory costs.

    IGD chief executive Sarah Bradbury also warned that “pressures are building across the food supply chain” because of the Middle East conflict and hot weather, creating a risk of “higher food costs” heading into autumn.

    Oil prices climb as Middle East risks remain in focus

    Energy markets reflected the continued geopolitical uncertainty, with Brent crude rising 2.15% to $89.62 a barrel and U.S. WTI gaining 2.24% to $83.95.

    Gold prices were softer. Gold futures slipped 0.02% to $4,418.82, while spot gold declined 0.65% to $4,360.46.

    UK stocks in focus

    Bellway (LSE:BWY) highlighted uncertainty around near-term housing demand as higher construction costs and moderating consumer demand weighed on the outlook. The housebuilder indicated that operating profit was likely to come in at the lower end of its guidance range.

    IHG (LSE:IHG) reported higher second-quarter RevPAR, supported by demand from affluent travellers and activity associated with the 2026 Soccer World Cup.

    With geopolitical uncertainty pushing oil prices higher and domestic retail data pointing to softer consumer demand, investors are balancing external risks against company-specific developments as the FTSE 100 trades close to flat.

  • International Workplace Group Shares Fall as Investors Weigh Cost Cuts and Cash Flow Pressure

    International Workplace Group Shares Fall as Investors Weigh Cost Cuts and Cash Flow Pressure

    International Workplace Group (LSE:IWG) shares fell sharply on Tuesday despite the flexible-workspace operator reaffirming its full-year and medium-term outlook, as investors focused on weak first-half cash generation and the potential impact of recently introduced cost reductions.

    IWG shares were down 5.17% at 175.90 pence after the company reported cash flow before corporate activities of negative $55 million for the first half.

    The group expects overhead costs to fall significantly during the second half, with cost-cutting measures introduced in response to a more uncertain macroeconomic environment expected to make a greater contribution to performance through the remainder of 2026 and into subsequent periods.

    Management also maintained its medium-term targets, indicating that it continues to see its broader strategy progressing despite geopolitical tensions and wider economic uncertainty.

    IWG had previously outlined steps to control costs as it navigates the more challenging backdrop while continuing to expand its flexible-workspace operations.

    At its first-quarter trading update, the company reported accelerating centre signings and openings, increased enquiries from enterprise customers, higher sales and positive pricing trends.

    The group continues to expect adjusted EBITDA of between $585 million and $625 million for 2026. It is also targeting growth of at least 4% in company-owned revenue and recurring management-fee income of $80 million.

    Over the medium term, IWG is aiming to generate at least $1 billion of adjusted EBITDA while retaining its investment-grade credit rating.

    Cost reductions become a key focus for IWG

    The share-price decline suggests investors are placing particular emphasis on cash generation despite management maintaining its earnings targets.

    The expected reduction in overheads could become increasingly important during the second half if IWG is to improve cash performance while continuing to invest in expanding its network.

    The company has been shifting towards a more capital-light growth model, with recurring management fees forming a larger part of its strategy alongside expansion of its flexible-workspace footprint.

    Cost discipline, improving profitability and stronger cash conversion are therefore likely to remain important measures of progress as IWG works towards its medium-term financial objectives.

    More about International Workplace Group

    International Workplace Group is a global provider of flexible offices, coworking spaces and workplace solutions.

    The company operates brands including Regus and Spaces and is expanding its network while pursuing a more capital-light business model.

    Its strategy combines new centre growth, recurring management-fee income and tighter cost management as the group seeks to improve profitability and progress towards its medium-term earnings targets.

    International Workplace Group shares trade on the London Stock Exchange under the symbol IWG.

  • Seeing Machines Moves Towards Profitability as Automotive Royalties Reach Record Levels

    Seeing Machines Moves Towards Profitability as Automotive Royalties Reach Record Levels

    Seeing Machines (LSE:SEE) reported a sharp improvement in FY2026 trading, with strong growth in automotive production volumes and royalty revenue helping the company achieve a profitable second half and move close to breakeven for the full year.

    Adjusted revenue increased 45% to $76.3 million, supported by a significant expansion in the company’s automotive business. Production volumes incorporating Seeing Machines technology climbed 195% to 4.49 million units during the year.

    Adjusted automotive royalty revenue more than doubled as the growing number of vehicles using the company’s driver and occupant monitoring technology translated into higher recurring income.

    The changing revenue mix also strengthened margins. Higher-volume, higher-margin automotive royalties became a larger contributor relative to hardware sales, helping Seeing Machines reach profitability during the second half.

    Cash flow also turned positive in H2, representing another important step as the company works towards establishing sustainable profitability and cash generation.

    More than 8.2 million vehicles now incorporate Seeing Machines technology. The installed base provides the company with growing exposure to automotive production volumes as existing programmes scale and additional vehicles equipped with its monitoring systems enter production.

    Regulatory developments provide another potential growth driver. Newly effective European Union requirements for driver monitoring systems are increasing the importance of technologies capable of assessing driver attention and behaviour.

    Seeing Machines is also expanding its automotive programmes with manufacturers in Europe and Japan, while continuing to pursue opportunities through its Guardian commercial fleet technology and emerging autonomous mobility applications.

    The combination of accelerating royalty revenue, improved margins and positive second-half cash flow suggests the company’s financial model is beginning to benefit from greater scale. Continued growth in vehicle production volumes could further increase the contribution from automotive royalties.

    However, the broader financial position still carries risk. Seeing Machines remains loss-making on a full-year basis, with a negative net margin and negative operating cash flow continuing to weigh on overall financial quality.

    Technical indicators provide a more supportive signal, with the shares trading above major moving averages and momentum ranging from neutral to positive.

    Valuation remains more difficult to support through traditional earnings measures while the company remains unprofitable, resulting in a negative P/E ratio, while no dividend yield is available.

    More about Seeing Machines

    Seeing Machines is an Australia-headquartered technology company specialising in computer vision and artificial intelligence systems designed to improve transport safety.

    Its technology uses AI algorithms, embedded processing and optical systems to monitor drivers and vehicle occupants, including assessing driver attention and cognitive state.

    The company serves automotive manufacturers, commercial fleet operators and emerging autonomous mobility markets through its driver and occupant monitoring technologies.

    Seeing Machines shares trade on AIM under the symbol SEE.

  • Helium One Reports Regular Helium Shipments as Colorado Production Advances

    Helium One Reports Regular Helium Shipments as Colorado Production Advances

    Helium One Global (LSE:HE1) has reported further operational progress at the Galactica-Pegasus helium development in Colorado, where regular product shipments are beginning to establish a more consistent production cycle.

    Operator Blue Star Helium has delivered a third helium trailer from the Pinon Canyon Plant at the Galactica Project to its offtaker. A fourth trailer is already on site and being filled, indicating that shipments are moving towards a scheduled and recurring pattern.

    Helium One holds a 50% working interest in Galactica-Pegasus, giving the company exposure to the developing Colorado operation alongside its core helium assets in Tanzania.

    As production progresses towards design capacity, Helium One indicated that it may no longer announce every individual trailer exchange. Instead, future updates are expected to concentrate on more significant operational milestones.

    The shift towards regular shipments represents further progress in establishing consistent commercial output from Colorado. Continued production ramp-up will be important in demonstrating the operating performance of the Pinon Canyon facility and the contribution Galactica-Pegasus can make to Helium One’s wider portfolio.

    In Tanzania, the company is advancing its southern Rukwa Project following its successful drilling campaign. The Itumbula West-1 discovery delivered sustained helium flows and subsequently supported the award of a major mining licence in 2025.

    Helium One is now progressing Rukwa through appraisal and development activities as it seeks to build a helium business spanning projects in both Tanzania and the United States.

    Despite the operational advances, the company’s financial profile remains a key consideration. Helium One is still pre-revenue at group level, with continuing losses and significant cash consumption creating an ongoing requirement for external funding.

    The absence of debt provides some balance-sheet support, but future exploration and development expenditure will still need to be funded as the company advances its projects.

    Technical indicators also remain weak, with the shares trading below major moving averages, a negative MACD and subdued momentum readings. Traditional valuation measures offer limited insight while earnings remain negative and no dividend yield is available.

    More about Helium One Global Limited

    Helium One Global is a helium exploration and development company with assets in Tanzania and the United States.

    Its Tanzanian portfolio includes the Rukwa Project, where the company is progressing the Itumbula West-1 discovery following successful helium flow testing and the award of a mining licence.

    In the United States, Helium One holds a 50% working interest in the Galactica-Pegasus development in Colorado, providing exposure to progressing helium production and commercial shipments.

    The company’s strategy is focused on developing helium resources across both regions as it seeks to establish itself as a supplier to the global helium market.

    Helium One Global shares trade on the London Stock Exchange under the symbol HE1.

  • Atalaya Mining Delivers Record H1 2026 EBITDA and Raises Interim Dividend

    Atalaya Mining Delivers Record H1 2026 EBITDA and Raises Interim Dividend

    Atalaya Mining (LSE:ATYM) reported record EBITDA for both the second quarter and first half of 2026, supported by higher copper prices, solid production and improved recoveries while maintaining its full-year production and cost guidance.

    The strong earnings performance came despite lower ore grades and increased mining and processing costs. Higher realised copper prices and operational improvements helped offset these pressures and supported healthy margins during the period.

    Atalaya continued to maintain competitive all-in sustaining costs while generating strong free cash flow. This strengthened the balance sheet, with the company’s net cash position increasing to €318.3 million.

    The improved financial position has also supported higher shareholder distributions. Atalaya declared an interim dividend of €0.055 per share, increasing its return to investors while retaining substantial liquidity to fund its growth programme.

    Management reaffirmed its full-year copper production and cost guidance, indicating that the company’s operational expectations remain unchanged following the first-half performance.

    Alongside its existing production operations, Atalaya continues to advance several projects intended to expand its longer-term position in Spain.

    These include Proyecto Touro, development of a polymetallic processing circuit and progress at Masa Valverde. Advancement of these projects could broaden the company’s production and resource base while providing additional growth opportunities beyond its current operations.

    The combination of record EBITDA, strong free cash flow and a €318.3 million net cash position gives Atalaya financial flexibility to invest in its development pipeline while maintaining shareholder returns.

    The broader outlook remains supported by healthy margins, operating cash generation and low leverage. However, earnings remain exposed to fluctuations in copper prices and the timing of operational activity, which can produce variability between reporting periods.

    Technical indicators are broadly neutral to moderately positive rather than showing a particularly strong trend. Valuation is similarly balanced, with the company’s P/E ratio and modest dividend yield providing neither a significant positive nor negative contribution to the overall picture.

    More about Atalaya Mining

    Atalaya Mining Copper, S.A. is a Spain-focused copper producer with shares traded on the London Stock Exchange under the symbol ATYM.

    The company operates open-pit mining and processing facilities producing copper concentrates alongside silver by-products.

    Atalaya’s growth strategy centres on expanding its operations across the Iberian Peninsula while advancing development opportunities including Proyecto Touro. The company combines investment in future production with a focus on cost discipline, cash generation and capital allocation.