Author: Fiona Craig

  • Potentially AI Expands Free Access as Consumer App Waitlist Reaches 25,000

    Potentially AI Expands Free Access as Consumer App Waitlist Reaches 25,000

    Potentially AI PLC (LSE:AGI) has announced that registrations for early access to its upcoming consumer application have climbed to 25,000, with more than two-thirds of those sign-ups recorded during the past 72 hours. In response to the strong demand, the company has increased the availability of its free Protect plan, allowing every current registrant to receive a one-year licence at no cost. Management said the rapid growth supports its strategy of bringing together multiple leading AI models and tools within a single platform and confirmed that users will be onboarded in stages over the coming weeks.

    Growing User Base Supports Commercial Strategy

    The expanding waitlist provides Potentially AI with an established community of early adopters before the product’s full launch, helping to strengthen its position in the increasingly competitive artificial intelligence software market. By extending free access to all 25,000 registered users, the company is investing in user acquisition while creating opportunities to gather product feedback, refine the platform and encourage long-term engagement. Management believes this early user base will support the wider rollout of its consumer, professional and marketplace AI products throughout 2026.

    Outlook Reflects Strong Momentum but Ongoing Financial Challenges

    Potentially AI continues to face financial headwinds, including recurring losses, inconsistent revenue and negative operating and free cash flow, with cash burn increasing during 2025. However, technical indicators remain supportive, with the shares trading above key moving averages, although momentum measures suggest the stock may be overbought and vulnerable to short-term volatility. Valuation also remains difficult to assess given the company’s negative earnings and the absence of a dividend.

    About Potentially AI PLC

    Potentially AI PLC is a London-based technology company developing a collective artificial intelligence platform that provides access to more than 1,000 open-source AI models alongside systems from leading frontier AI developers. The company aims to serve both consumer and professional users by offering greater control over data, AI model selection and token usage, while enabling customers to build, customise and commercialise AI-powered applications through its planned ecosystem of consumer products, workplace tools and marketplace services.

  • Wynnstay to Double Scottish Fertiliser Production Capacity with Montrose Investment

    Wynnstay to Double Scottish Fertiliser Production Capacity with Montrose Investment

    Wynnstay Group PLC (LSE:WYN) has announced plans to significantly expand its Glasson Fertilisers operations in Montrose, Scotland, by securing a long-term lease on a larger facility on Barrack Road. The investment will create one of Europe’s largest fertiliser blending plants, enabling the company to double its production capacity in Scotland while improving operational efficiency to meet growing customer demand. Part of the project will be financed through the sale of the existing Cobden Street site.

    Expansion Supports Long-Term Growth Strategy

    The new facility is expected to generate a return on net assets of at least 10%, in line with Wynnstay’s capital allocation objectives and its wider Strategy Genesis growth programme. Blending operations will continue at the current Montrose site throughout the construction and transition period, ensuring uninterrupted customer supply. Full commissioning of the new plant is targeted for the first half of the 2027 financial year, strengthening the group’s manufacturing network following the recent expansion of its Avonmouth facility and enhancing its presence in the Scottish agricultural market.

    Outlook Reflects Stable Finances Despite Earnings Pressure

    Wynnstay continues to benefit from a solid financial position, supported by low leverage and a stable balance sheet. However, this is balanced by weaker earnings and a decline in cash flow during 2025. Technical indicators remain moderately positive rather than strongly bullish, while the valuation presents a mixed picture, with an attractive dividend yield offset by a relatively high price-to-earnings ratio following softer profitability. Recent insider share purchases provide an additional, albeit secondary, signal of management confidence.

    About Wynnstay

    Wynnstay Group PLC is a leading UK supplier of agricultural products and services, providing farmers with a broad range of inputs, manufacturing capabilities and technical support. The company supplies products and expertise designed to improve farm productivity, sustainability and profitability, supporting the UK’s food production sector through its integrated manufacturing, distribution and on-farm service network.

  • Gelion Signs £2 Million Development Agreement to Advance Sulfur Battery Technology

    Gelion Signs £2 Million Development Agreement to Advance Sulfur Battery Technology

    Gelion PLC (LSE:GELN) has entered into a funded joint development agreement with Japan’s Mitsui Kinzoku to accelerate the commercial development of its Nano-Encapsulated Sulfur (NES™) cathode active material. Valued at £2 million in milestone-based payments, the collaboration will evaluate the technology in both liquid and solid-state sulfur battery cells for applications spanning electric vehicles, stationary energy storage, consumer electronics, aerospace and defence. The project aims to replace conventional critical-mineral cathodes with sulfur, a lower-cost and more abundant material that can be produced using existing lithium battery manufacturing infrastructure.

    Partnership Creates Route to Commercial Manufacturing

    Under the agreement, Mitsui Kinzoku has secured an option to negotiate manufacturing and distribution rights for Gelion’s NES™ cathode material across selected Asian markets. The arrangement provides a potential pathway towards large-scale commercial production if development milestones are successfully achieved. The partnership also expands Gelion’s network of industrial collaborators, complementing existing relationships with companies including TDK, Nissan and QinetiQ, and further strengthens the company’s strategy of bringing its battery technology to market through established industry partners.

    Commercialisation Strategy Gains Momentum

    Gelion views the agreement as an important milestone in scaling production of its sulfur cathode technology ahead of broader commercial deployment. The project also supports the company’s ongoing pilot-scale development work with the US National Laboratory of the Rockies. The latest collaboration highlights increasing industry interest in sulfur-based battery materials as a potential lower-cost, higher-energy alternative to traditional cathode technologies and provides further evidence of a developing commercial pathway across multiple end markets.

    Outlook Reflects Technology Progress Despite Financial Challenges

    The company’s outlook continues to be influenced by ongoing operating losses, negative earnings and continued cash investment in technology development. These financial pressures are partly balanced by improving technical indicators, with the share price trading above key moving averages and supported by positive momentum. Recent corporate updates have also demonstrated meaningful technical and commercial progress, alongside a reduced EBITDA loss, although execution and commercial timing remain key risks as the technology moves towards market adoption.

    About Gelion PLC

    Gelion PLC is a UK-listed battery technology company specialising in advanced cathode materials for lithium-ion and lithium-sulfur batteries. Its proprietary Nano-Encapsulated Sulfur (NES™) technology is designed to replace conventional critical-mineral cathodes with sulfur, delivering the potential for higher energy density while remaining compatible with existing battery manufacturing processes. The technology is aimed at sectors including automotive, defence, consumer electronics and stationary energy storage.

    The company follows a partnership-driven commercialisation model, collaborating with leading industrial and research organisations including Mitsui Kinzoku, TDK, Nissan, QinetiQ, the US National Laboratory of the Rockies and Germany’s Max Planck Institute of Colloids and Interfaces to accelerate the adoption of its next-generation battery technologies.

  • Young & Co.’s Brewery Issues Shares Under Employee Bonus Scheme

    Young & Co.’s Brewery Issues Shares Under Employee Bonus Scheme

    Young & Co.’s Brewery PLC (LSE:YNGA) has admitted 21,918 new A ordinary shares, each with a nominal value of 12.5 pence, to trading on the London Stock Exchange’s Main Market. Following the admission, the company now has 38,048,005 A ordinary shares in issue, with a proportion of those shares held in treasury. The new shares were issued under a block admission established on 28 May 2026 to satisfy awards granted through the company’s deferred annual bonus scheme.

    Share Issuance Supports Employee Incentives

    The newly issued shares rank equally with the existing A ordinary shares and are fully interchangeable with stock already in circulation. While the issuance results in a slight increase in the number of shares available to investors, it primarily reflects the company’s ongoing use of equity-based incentives to reward employees and align their interests with those of shareholders.

    Outlook Supported by Improving Financial Performance

    Young & Co.’s Brewery continues to benefit from improving profitability and stronger free cash flow generation, although earnings, operating margins and cash conversion have remained somewhat uneven. Technical indicators present a more cautious picture, with the shares trading below key longer-term moving averages and a negative MACD suggesting weaker momentum. From a valuation perspective, the stock remains reasonably priced and is supported by a dividend yield of around 3.1%.

    About Young & Co.’s Brewery

    Young & Co.’s Brewery PLC is a UK hospitality company operating a portfolio of pubs alongside its brewing activities. Listed on the London Stock Exchange’s Main Market, the business provides investors with exposure to a well-established pub estate and beer-focused operations serving customers across its core UK markets.

  • Chesnara Issues New Shares Under Employee Incentive Schemes

    Chesnara Issues New Shares Under Employee Incentive Schemes

    Chesnara plc (LSE:CSN) has issued new ordinary shares with a nominal value of 5 pence each under its 2023 short-term and long-term incentive plans, together with its 2022 savings-related share option scheme. The newly issued shares have been admitted to trading on the London Stock Exchange and rank equally with the company’s existing ordinary shares. Following the latest allotments, Chesnara’s total issued share capital has increased to 231,709,059 shares, resulting in modest dilution for existing shareholders while supporting employee participation in the group’s incentive programmes.

    Equity Awards Support Long-Term Incentive Strategy

    The share issuances were completed through a series of admissions between late April and early August 2026, reflecting Chesnara’s continued use of equity-based remuneration to reward and retain employees. By issuing the shares through an established admission process that did not require a prospectus, the company continues to align management incentives with shareholder interests while supporting its long-term growth and acquisition strategy in the European life and pensions sector.

    Outlook Reflects Strong Balance Sheet but Mixed Earnings Performance

    Chesnara’s outlook remains supported by a strengthened balance sheet, although profitability has been volatile and cash flow has been inconsistent, including a significant cash outflow during 2025. Technical indicators remain constructive, with the shares trading above key moving averages and supported by positive momentum. The investment case also benefits from an attractive dividend yield, although the company’s recent losses have resulted in a negative price-to-earnings ratio, tempering the overall valuation.

    About Chesnara

    Chesnara plc is a FTSE 250 life insurance, pensions and investment group specialising in the acquisition and management of life and pension businesses across Europe. The company administers approximately 1.4 million policies through operations in the UK, the Netherlands and Sweden, combining efficient policy administration with selective new business opportunities and value-enhancing acquisitions.

    Chesnara has built a long track record of returning capital to shareholders, having increased its dividend for 21 consecutive years, while continuing to pursue growth through insurance consolidation across its core European markets.

  • Sanderson Design Group Delivers Revenue Growth Driven by U.S. Expansion and Digital Sales

    Sanderson Design Group Delivers Revenue Growth Driven by U.S. Expansion and Digital Sales

    Sanderson Design Group PLC (LSE:SDG) reported a 6% increase in first-half revenue to £51.4 million, supported by strong performances across its North American operations, manufacturing business and licensing activities. Brand sales in North America rose 19%, manufacturing revenue increased by 19% and licensing income advanced 13%. The group’s direct-to-consumer business also continued to gain momentum, with online sales through its brand websites surging 137% to £1.6 million. Net cash improved to £10.2 million despite ongoing share buybacks, and the board said it expects full-year results to meet current market expectations.

    North America and Manufacturing Continue to Drive Performance

    The company highlighted the United States as its strongest-performing and highest-margin market, benefiting from continued demand for its heritage British brands, high-profile collaborations including Morris & Co. x The Huntington and Highgrove by Sanderson, and stronger relationships with leading interior designers. Manufacturing also delivered a robust performance, helped by restructuring initiatives, the rollout of its Future Factory programme and sustained third-party demand. Continued investment in digital platforms for both retail and trade customers remains a key part of the group’s strategy to support long-term international growth.

    Diversified Business Offsets Softer UK Trading

    Although UK brand revenue declined by 8% during the period, growth in North America and manufacturing more than compensated for the weakness, demonstrating the benefits of the group’s increasingly diversified geographic and operational footprint. Supported by premium design brands, strategic partnerships and continued digital expansion, Sanderson Design Group remains focused on strengthening its international presence while delivering profitable growth.

    Outlook Supported by Balance Sheet Strength

    The company’s outlook reflects a mixed financial profile. A strong balance sheet and improved cash generation during 2026 provide solid support, although earnings have remained volatile and operating margins are relatively thin. Technical indicators remain positive, with the shares continuing to trade in an established uptrend supported by improving momentum. Valuation is somewhat constrained by a relatively high price-to-earnings ratio and a modest dividend yield.

    About Sanderson Design Group PLC

    Sanderson Design Group PLC is a UK-based designer, manufacturer and marketer of luxury wallpapers, fabrics, paints and interior furnishings. The company also licenses its designs for a broad range of home products, including bedding, rugs, blinds and tableware. Its manufacturing operations are based in Loughborough and Lancaster, while its showrooms are located in London, New York and Chicago.

    The group’s portfolio includes well-known brands such as Sanderson, Morris & Co., Zoffany, Harlequin, Clarke & Clarke and Scion. Employing around 500 people worldwide, Sanderson Design Group is listed on AIM under the ticker SDG and continues to expand its presence in the global premium home furnishings market.

  • Goodwin Begins Strategic Review of Mechanical Engineering Business

    Goodwin Begins Strategic Review of Mechanical Engineering Business

    Goodwin PLC (LSE:GDWN) has announced the launch of a strategic review of its Mechanical Engineering division following recent market speculation regarding a possible disposal of assets. The review is intended to assess a range of strategic options that could enhance shareholder value while ensuring the continued stability of the group’s operations and supporting the long-term development of its businesses.

    Potential Asset Sale Among Options Under Review

    As part of the review, Goodwin is considering the possible sale of a significant portion of its Mechanical Engineering division, including several of its principal subsidiaries. The company has appointed Rothschild & Co as its financial adviser to oversee the process and confirmed that discussions are ongoing. Shareholders will be updated as the review progresses, with the outcome expected to influence the group’s future portfolio structure and strategic direction.

    Outlook Supported by Strong Fundamentals

    Goodwin’s investment outlook continues to be underpinned by solid financial performance, including revenue growth, healthy profit margins, low leverage and improving free cash flow. The valuation also remains attractive, supported by a reasonable price-to-earnings ratio and a relatively high dividend yield. However, technical indicators remain weak, with the share price trading below key moving averages and momentum continuing to lag.

    About Goodwin

    Goodwin PLC is a diversified engineering group operating across the mechanical engineering sector through businesses including GSC, GI, Noreva, Easat and Pumps. The company designs and manufactures specialist engineered products while providing industrial services to customers across a variety of end markets. Its broad portfolio supports a diversified business model focused on delivering long-term value for customers and shareholders.

  • Arrow Exploration Increases Colombian Production Following Strong Icaco Well Performance

    Arrow Exploration Increases Colombian Production Following Strong Icaco Well Performance

    Arrow Exploration Corp. (LSE:AXL) continues to expand production from its Colombian oil portfolio, targeting underdeveloped assets across the Llanos, Middle Magdalena Valley and Putumayo basins. The company benefits from high working interests and Brent-linked oil pricing, supporting attractive operating margins. Under a private commercial agreement, Arrow is entitled to 50% of production from the Tapir block, where it is pursuing production growth through a combination of vertical and horizontal drilling programmes led by its experienced management team.

    Icaco Wells Lift Production Above 5,000 boe/d

    The company has reported encouraging drilling and initial production results from the Icaco-3 vertical well and the Icaco-4 and Icaco-5 horizontal wells on the Tapir block in Colombia’s Llanos Basin. The successful campaign has increased gross corporate production to more than 5,000 barrels of oil equivalent per day while confirming the commercial potential of both the Gacheta and Ubaque reservoirs. All three wells were completed on schedule and within budget. Icaco-3 has been brought into production from the Gacheta formation, while Icaco-5 delivered strong early production from the Ubaque interval. Arrow is continuing to optimise completion techniques on Icaco-4 as it prepares for additional drilling at the Icaco field.

    Strong Financial Position Supports Growth Plans

    Arrow remains in a solid financial position, with approximately US$27.5 million in cash and no outstanding debt, providing flexibility to fund further development activity. The company is also awaiting a decision on an extension to the Tapir block while monitoring regulatory developments under Colombia’s new administration, which has indicated support for increased investment in the country’s oil and gas sector.

    About Arrow Exploration Corp.

    Arrow Exploration Corp. is an oil and gas producer focused on developing underexploited hydrocarbon assets across Colombia’s Llanos, Middle Magdalena Valley and Putumayo basins. Through its operating subsidiary, Carrao Energy S.A., the company holds significant working interests in light oil projects benefiting from Brent-linked pricing and relatively low royalty rates. Arrow is entitled to half of the production from the Tapir block, subject to Ecopetrol’s approval.

    Listed on both AIM in London and the TSX Venture Exchange under the ticker AXL, Arrow is focused on increasing production through operated assets in some of Colombia’s most prospective oil regions, with the aim of delivering sustainable production growth and long-term value for shareholders.

  • Talisman Metals Expands High-Grade Copper-Silver Mineralisation at Morocco’s Tirzzit Project

    Talisman Metals Expands High-Grade Copper-Silver Mineralisation at Morocco’s Tirzzit Project

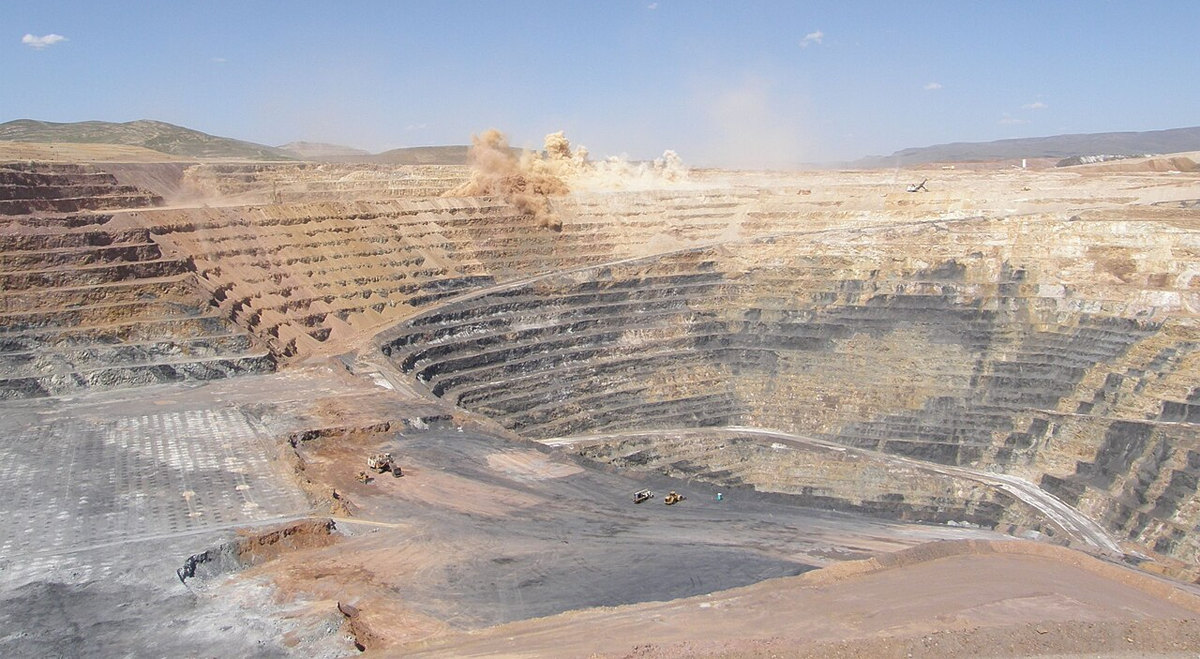
    Talisman Metals PLC (LSE:TLM) has announced encouraging channel sampling results from its Tirzzit copper-silver project in Morocco, confirming the presence of a mineralised horizon within the project’s basal series. Copper grades ranged from 0.60% to 2.62%, while silver values came in between 12 ppm and 44 ppm. The latest sampling has extended the known mineralised zone by a further 70 metres along strike within an interpreted 300-metre north-west trend, contributing to a total identified strike length of at least four kilometres.

    Results Strengthen Exploration Potential Ahead of Drilling

    Sampling returned true thicknesses of between 0.90 metres and 2.78 metres, supporting the company’s view that Tirzzit represents a sediment-hosted stratiform copper-silver system. Assays also identified elevated levels of barium, lead, zinc, cobalt and manganese, providing additional geological indicators associated with the mineralisation. The new findings will help shape Talisman’s planned drilling programme in 2026 and further enhance the project’s exploration potential. The company noted that historical exploration data obtained from Morocco’s BRPM remains under review and has not yet been verified or upgraded to comply with the JORC 2012 reporting standard.

    Quality Controls Support Confidence in Sampling

    The July 2026 sampling programme incorporated a comprehensive quality assurance and quality control process, including the use of blanks, field duplicates and certified reference materials analysed by ISO/IEC 17025-accredited laboratory Labomine. While a small analytical bias was identified in copper values from one certified reference material, Talisman said this was not considered significant enough to alter the overall interpretation of the results. The combination of encouraging surface mineralisation, expanding strike continuity and ongoing assessment of historical exploration data continues to strengthen the investment case for the Tirzzit project.

    Outlook Reflects Exploration Upside Despite Early-Stage Profile

    The company’s outlook remains constrained by its early-stage exploration status, with no revenue generation, continued operating losses, negative free cash flow and declining equity. These financial challenges are partly offset by a debt-free balance sheet. Technical indicators remain positive but suggest the shares may be significantly overbought, while valuation is difficult to assess given the absence of earnings and dividend payments.

    About Talisman Metals PLC

    Talisman Metals PLC is a mineral exploration company focused on developing copper and silver assets, with its flagship Tirzzit Project in Morocco representing a sediment-hosted stratiform copper-silver opportunity. The project covers two mining licences spanning 16.5 square kilometres and was acquired from Aya Silver & Gold Inc. Historical drilling has identified encouraging copper mineralisation, although the results have not yet been upgraded to JORC 2012-compliant mineral resources.

    The company is currently evaluating historical drilling and geophysical datasets provided by Morocco’s BRPM to refine future exploration plans, with further work expected during the third quarter of 2026. Talisman is also progressing the formal transfer of the Tirzzit mining licences from Aya, reinforcing the project’s strategic importance within its exploration portfolio. Located around 225 kilometres east of Agadir, Tirzzit is overseen by Head Geologist Fabien Linares, who is recognised as a Qualified and Competent Person under the JORC 2012 Code.

  • Essentra Retains PwC as External Auditor Following Competitive Review

    Essentra Retains PwC as External Auditor Following Competitive Review

    Essentra plc (LSE:ESNT) has concluded a competitive audit tender and selected PricewaterhouseCoopers (PwC) to continue as the group’s external auditor for the financial year ending 31 December 2027. The decision follows UK corporate governance requirements that listed companies undertake an audit tender at least every ten years. The reappointment remains subject to shareholder approval at the 2027 Annual General Meeting and is intended to provide continuity in the company’s audit and financial reporting process.

    Board Backs Continuity in Audit Oversight

    By retaining PwC after the tender process, Essentra’s board has demonstrated its confidence in the firm’s ability to continue delivering high-quality audit services. The decision supports consistency within the group’s governance framework and helps maintain stability in financial oversight as the company continues to execute its business strategy.

    Outlook Weighed by Profitability Challenges

    Essentra’s outlook continues to be affected by inconsistent profitability and softer recent cash flow performance, although these factors are partly offset by a strong balance sheet. From a technical perspective, the shares remain in a positive trend, trading comfortably above key moving averages. Valuation remains the principal consideration for investors, with a relatively high price-to-earnings ratio and a modest dividend yield limiting the overall investment case.

    About Essentra

    Essentra plc is a global manufacturer and distributor of essential industrial components and solutions, supplying customers across a wide range of end markets. The company offers an extensive portfolio of engineered products designed to support manufacturing and assembly operations, with a focus on reliable supply, operational efficiency and value-added services for industrial businesses worldwide.