Category: Market News

  • FTSE 100 Slips as U.S.-Iran Tensions and Weak UK Retail Sales Weigh

    FTSE 100 Slips as U.S.-Iran Tensions and Weak UK Retail Sales Weigh

    UK equities moved modestly lower on Tuesday as renewed tensions between the United States and Iran combined with disappointing British retail sales data to dampen investor sentiment.

    As of 03:23 ET (07:23 GMT), the FTSE 100 was down 0.08%. Germany’s DAX declined 0.06%, while France’s CAC 40 fell 0.07%. Sterling was unchanged against the dollar at $1.3501.

    Geopolitical risk remained firmly in focus after the Washington Post reported that U.S. President Donald Trump used a decoy operation when leaving Turkiye following the NATO summit on July 8 because of a potential Iranian threat.

    According to the report, Trump was covertly transferred by catering truck to a smaller C-32A aircraft, while the traditional Air Force One continued its journey carrying journalists and some White House personnel.

    A U.S. official described the situation as involving a “credible threat” from Iran.

    A White House spokesperson defended the security measures, saying “there are many enemies of America who have their sights on him, and we use every tool at our disposal to address those threats.”

    Tensions surrounding the Strait of Hormuz also remained elevated. Trump told reporters on Monday that the U.S. Navy has “100 per cent control” of the strategically important waterway, describing the blockade as “infallible” and a “steel wall.”

    Iran’s Revolutionary Guard Corps, meanwhile, maintained that the Strait would remain a “theatre of war” until Washington meets Tehran’s conditions, including financial restitution.

    Trump also reiterated his demand for reparations in a Truth Social post, saying Iran should provide compensation for the “last five month Military Conflict.”

    In a separate post, he said Iran “should be responsible for the damages and death caused to the people of Lebanon, Syria, Yemen, and Gaza.”

    Weak retail data adds pressure on UK stocks

    Domestic economic data provided another headwind after UK retail sales growth slowed considerably in July.

    Total sales increased 1.3% year on year, according to BRC-KPMG data, compared with growth of 2.5% a year earlier and below the 12-month average of 1.8%.

    Food sales increased 3.8%, helped by the closing stages of the World Cup, but non-food sales declined 0.7%.

    “Consumer demand has struggled in the heat, leaving retailers facing a challenging start to the second half of the year,” said Helen Dickinson, chief executive of the British Retail Consortium.

    Dickinson added that “household budgets remain stretched” and called on the government to reduce business rates and regulatory costs.

    IGD chief executive Sarah Bradbury also warned that “pressures are building across the food supply chain” because of the Middle East conflict and hot weather, creating a risk of “higher food costs” heading into autumn.

    Oil prices climb as Middle East risks remain in focus

    Energy markets reflected the continued geopolitical uncertainty, with Brent crude rising 2.15% to $89.62 a barrel and U.S. WTI gaining 2.24% to $83.95.

    Gold prices were softer. Gold futures slipped 0.02% to $4,418.82, while spot gold declined 0.65% to $4,360.46.

    UK stocks in focus

    Bellway (LSE:BWY) highlighted uncertainty around near-term housing demand as higher construction costs and moderating consumer demand weighed on the outlook. The housebuilder indicated that operating profit was likely to come in at the lower end of its guidance range.

    IHG (LSE:IHG) reported higher second-quarter RevPAR, supported by demand from affluent travellers and activity associated with the 2026 Soccer World Cup.

    With geopolitical uncertainty pushing oil prices higher and domestic retail data pointing to softer consumer demand, investors are balancing external risks against company-specific developments as the FTSE 100 trades close to flat.
  • International Workplace Group Shares Fall as Investors Weigh Cost Cuts and Cash Flow Pressure

    International Workplace Group Shares Fall as Investors Weigh Cost Cuts and Cash Flow Pressure

    International Workplace Group (LSE:IWG) shares fell sharply on Tuesday despite the flexible-workspace operator reaffirming its full-year and medium-term outlook, as investors focused on weak first-half cash generation and the potential impact of recently introduced cost reductions.

    IWG shares were down 5.17% at 175.90 pence after the company reported cash flow before corporate activities of negative $55 million for the first half.

    The group expects overhead costs to fall significantly during the second half, with cost-cutting measures introduced in response to a more uncertain macroeconomic environment expected to make a greater contribution to performance through the remainder of 2026 and into subsequent periods.

    Management also maintained its medium-term targets, indicating that it continues to see its broader strategy progressing despite geopolitical tensions and wider economic uncertainty.

    IWG had previously outlined steps to control costs as it navigates the more challenging backdrop while continuing to expand its flexible-workspace operations.

    At its first-quarter trading update, the company reported accelerating centre signings and openings, increased enquiries from enterprise customers, higher sales and positive pricing trends.

    The group continues to expect adjusted EBITDA of between $585 million and $625 million for 2026. It is also targeting growth of at least 4% in company-owned revenue and recurring management-fee income of $80 million.

    Over the medium term, IWG is aiming to generate at least $1 billion of adjusted EBITDA while retaining its investment-grade credit rating.

    Cost reductions become a key focus for IWG

    The share-price decline suggests investors are placing particular emphasis on cash generation despite management maintaining its earnings targets.

    The expected reduction in overheads could become increasingly important during the second half if IWG is to improve cash performance while continuing to invest in expanding its network.

    The company has been shifting towards a more capital-light growth model, with recurring management fees forming a larger part of its strategy alongside expansion of its flexible-workspace footprint.

    Cost discipline, improving profitability and stronger cash conversion are therefore likely to remain important measures of progress as IWG works towards its medium-term financial objectives.

    More about International Workplace Group

    International Workplace Group is a global provider of flexible offices, coworking spaces and workplace solutions.

    The company operates brands including Regus and Spaces and is expanding its network while pursuing a more capital-light business model.

    Its strategy combines new centre growth, recurring management-fee income and tighter cost management as the group seeks to improve profitability and progress towards its medium-term earnings targets.

    International Workplace Group shares trade on the London Stock Exchange under the symbol IWG.

  • Seeing Machines Moves Towards Profitability as Automotive Royalties Reach Record Levels

    Seeing Machines Moves Towards Profitability as Automotive Royalties Reach Record Levels

    Seeing Machines (LSE:SEE) reported a sharp improvement in FY2026 trading, with strong growth in automotive production volumes and royalty revenue helping the company achieve a profitable second half and move close to breakeven for the full year.

    Adjusted revenue increased 45% to $76.3 million, supported by a significant expansion in the company’s automotive business. Production volumes incorporating Seeing Machines technology climbed 195% to 4.49 million units during the year.

    Adjusted automotive royalty revenue more than doubled as the growing number of vehicles using the company’s driver and occupant monitoring technology translated into higher recurring income.

    The changing revenue mix also strengthened margins. Higher-volume, higher-margin automotive royalties became a larger contributor relative to hardware sales, helping Seeing Machines reach profitability during the second half.

    Cash flow also turned positive in H2, representing another important step as the company works towards establishing sustainable profitability and cash generation.

    More than 8.2 million vehicles now incorporate Seeing Machines technology. The installed base provides the company with growing exposure to automotive production volumes as existing programmes scale and additional vehicles equipped with its monitoring systems enter production.

    Regulatory developments provide another potential growth driver. Newly effective European Union requirements for driver monitoring systems are increasing the importance of technologies capable of assessing driver attention and behaviour.

    Seeing Machines is also expanding its automotive programmes with manufacturers in Europe and Japan, while continuing to pursue opportunities through its Guardian commercial fleet technology and emerging autonomous mobility applications.

    The combination of accelerating royalty revenue, improved margins and positive second-half cash flow suggests the company’s financial model is beginning to benefit from greater scale. Continued growth in vehicle production volumes could further increase the contribution from automotive royalties.

    However, the broader financial position still carries risk. Seeing Machines remains loss-making on a full-year basis, with a negative net margin and negative operating cash flow continuing to weigh on overall financial quality.

    Technical indicators provide a more supportive signal, with the shares trading above major moving averages and momentum ranging from neutral to positive.

    Valuation remains more difficult to support through traditional earnings measures while the company remains unprofitable, resulting in a negative P/E ratio, while no dividend yield is available.

    More about Seeing Machines

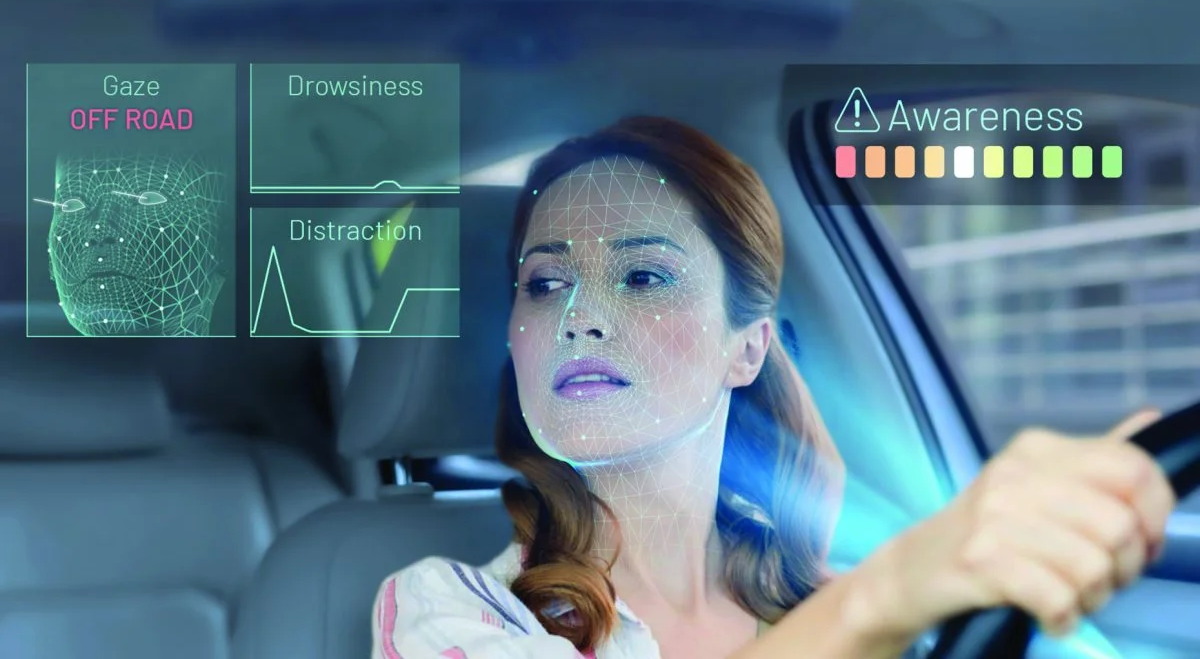
    Seeing Machines is an Australia-headquartered technology company specialising in computer vision and artificial intelligence systems designed to improve transport safety.

    Its technology uses AI algorithms, embedded processing and optical systems to monitor drivers and vehicle occupants, including assessing driver attention and cognitive state.

    The company serves automotive manufacturers, commercial fleet operators and emerging autonomous mobility markets through its driver and occupant monitoring technologies.

    Seeing Machines shares trade on AIM under the symbol SEE.

  • Helium One Reports Regular Helium Shipments as Colorado Production Advances

    Helium One Reports Regular Helium Shipments as Colorado Production Advances

    Helium One Global (LSE:HE1) has reported further operational progress at the Galactica-Pegasus helium development in Colorado, where regular product shipments are beginning to establish a more consistent production cycle.

    Operator Blue Star Helium has delivered a third helium trailer from the Pinon Canyon Plant at the Galactica Project to its offtaker. A fourth trailer is already on site and being filled, indicating that shipments are moving towards a scheduled and recurring pattern.

    Helium One holds a 50% working interest in Galactica-Pegasus, giving the company exposure to the developing Colorado operation alongside its core helium assets in Tanzania.

    As production progresses towards design capacity, Helium One indicated that it may no longer announce every individual trailer exchange. Instead, future updates are expected to concentrate on more significant operational milestones.

    The shift towards regular shipments represents further progress in establishing consistent commercial output from Colorado. Continued production ramp-up will be important in demonstrating the operating performance of the Pinon Canyon facility and the contribution Galactica-Pegasus can make to Helium One’s wider portfolio.

    In Tanzania, the company is advancing its southern Rukwa Project following its successful drilling campaign. The Itumbula West-1 discovery delivered sustained helium flows and subsequently supported the award of a major mining licence in 2025.

    Helium One is now progressing Rukwa through appraisal and development activities as it seeks to build a helium business spanning projects in both Tanzania and the United States.

    Despite the operational advances, the company’s financial profile remains a key consideration. Helium One is still pre-revenue at group level, with continuing losses and significant cash consumption creating an ongoing requirement for external funding.

    The absence of debt provides some balance-sheet support, but future exploration and development expenditure will still need to be funded as the company advances its projects.

    Technical indicators also remain weak, with the shares trading below major moving averages, a negative MACD and subdued momentum readings. Traditional valuation measures offer limited insight while earnings remain negative and no dividend yield is available.

    More about Helium One Global Limited

    Helium One Global is a helium exploration and development company with assets in Tanzania and the United States.

    Its Tanzanian portfolio includes the Rukwa Project, where the company is progressing the Itumbula West-1 discovery following successful helium flow testing and the award of a mining licence.

    In the United States, Helium One holds a 50% working interest in the Galactica-Pegasus development in Colorado, providing exposure to progressing helium production and commercial shipments.

    The company’s strategy is focused on developing helium resources across both regions as it seeks to establish itself as a supplier to the global helium market.

    Helium One Global shares trade on the London Stock Exchange under the symbol HE1.

  • Atalaya Mining Delivers Record H1 2026 EBITDA and Raises Interim Dividend

    Atalaya Mining Delivers Record H1 2026 EBITDA and Raises Interim Dividend

    Atalaya Mining (LSE:ATYM) reported record EBITDA for both the second quarter and first half of 2026, supported by higher copper prices, solid production and improved recoveries while maintaining its full-year production and cost guidance.

    The strong earnings performance came despite lower ore grades and increased mining and processing costs. Higher realised copper prices and operational improvements helped offset these pressures and supported healthy margins during the period.

    Atalaya continued to maintain competitive all-in sustaining costs while generating strong free cash flow. This strengthened the balance sheet, with the company’s net cash position increasing to €318.3 million.

    The improved financial position has also supported higher shareholder distributions. Atalaya declared an interim dividend of €0.055 per share, increasing its return to investors while retaining substantial liquidity to fund its growth programme.

    Management reaffirmed its full-year copper production and cost guidance, indicating that the company’s operational expectations remain unchanged following the first-half performance.

    Alongside its existing production operations, Atalaya continues to advance several projects intended to expand its longer-term position in Spain.

    These include Proyecto Touro, development of a polymetallic processing circuit and progress at Masa Valverde. Advancement of these projects could broaden the company’s production and resource base while providing additional growth opportunities beyond its current operations.

    The combination of record EBITDA, strong free cash flow and a €318.3 million net cash position gives Atalaya financial flexibility to invest in its development pipeline while maintaining shareholder returns.

    The broader outlook remains supported by healthy margins, operating cash generation and low leverage. However, earnings remain exposed to fluctuations in copper prices and the timing of operational activity, which can produce variability between reporting periods.

    Technical indicators are broadly neutral to moderately positive rather than showing a particularly strong trend. Valuation is similarly balanced, with the company’s P/E ratio and modest dividend yield providing neither a significant positive nor negative contribution to the overall picture.

    More about Atalaya Mining

    Atalaya Mining Copper, S.A. is a Spain-focused copper producer with shares traded on the London Stock Exchange under the symbol ATYM.

    The company operates open-pit mining and processing facilities producing copper concentrates alongside silver by-products.

    Atalaya’s growth strategy centres on expanding its operations across the Iberian Peninsula while advancing development opportunities including Proyecto Touro. The company combines investment in future production with a focus on cost discipline, cash generation and capital allocation.

  • Bellway Lifts Housing Completions and Cash as Buybacks Support Shareholder Returns

    Bellway Lifts Housing Completions and Cash as Buybacks Support Shareholder Returns

    Bellway (LSE:BWY) delivered higher housing completions and revenue for the year ended 31 July 2026, while strong cash generation and a growing net cash position provided the housebuilder with flexibility to continue returning capital to shareholders.

    Housing completions increased 10.8% to 9,695 homes, while housing revenue rose by more than 13% to £3.14 billion. Underlying operating profit is expected to be around £320 million, although margins were affected by a greater proportion of lower-margin bulk sales.

    The performance came against a challenging housing market, with Bellway highlighting subdued customer demand following increases in mortgage rates and uncertainty surrounding the Budget.

    Despite these pressures, the group’s financial position strengthened during the year. Net cash increased to £157.7 million, supported by disciplined spending, land investment and working capital management.

    Adjusted operating cash flow exceeded £850 million, while adjusted gearing remained below 5%. The stronger capital position is allowing Bellway to balance selective investment in future development with increased shareholder distributions.

    The company is progressing with a £150 million share buyback and plans a further £50 million programme as the initial tranche of buybacks for FY27. Capital discipline remains central to its strategy, with management prioritising the monetisation of its existing land bank and controlled investment in new sites.

    Bellway remains cautious about the near-term market environment, citing continued industry headwinds and softer customer demand. The company has also called for government measures to improve housing affordability, including lower Stamp Duty and greater support for buyer deposit schemes.

    The financial outlook is supported by recovering revenue, strong cash generation and relatively low balance-sheet leverage. These factors provide Bellway with flexibility to maintain investment while continuing its capital return programme.

    However, margin pressure remains a consideration, alongside weaker cash-flow trends shown elsewhere in the financial statements and uncertainties surrounding building safety costs.

    Technical indicators have improved over the shorter term, although the shares remain below their 200-day trend and some momentum measures appear stretched. This leaves the technical picture more mixed despite recent improvement.

    More about Bellway

    Bellway p.l.c. is a UK housebuilder focused on residential development across regional markets.

    The group builds private, affordable and social housing through a network of developments across the country. Its substantial owned and strategic land portfolio provides sites for future construction and supports its longer-term volume ambitions.

    Bellway’s strategy combines selective growth with disciplined land investment, cash generation and relatively low balance-sheet gearing as it seeks to manage housing market cycles while maintaining shareholder returns.

    Bellway shares trade on the London Stock Exchange under the symbol BWY.

  • CML Microsystems Reports Strong FY27 Start and Expects Earlier Return to Profitability

    CML Microsystems Reports Strong FY27 Start and Expects Earlier Return to Profitability

    CML Microsystems (LSE:CML) has reported a strong start to its FY27 financial year, with improving demand, revenue progressing in line with expectations and order intake running ahead of forecasts.

    The semiconductor specialist entered the new financial year with positive momentum following an improved final quarter, when revenue growth was accompanied by stronger order intake.

    That momentum has continued into the early stages of FY27, with demand strengthening across all of the group’s key market verticals. Revenue performance is currently tracking in line with management expectations, while orders are exceeding the levels previously forecast.

    The improved trading environment has increased the board’s confidence in CML’s growth strategy and its expectations for profitability.

    Management now anticipates a return to operational profitability earlier in the current financial year than previously expected. This represents an important change in the near-term earnings outlook following the recent deterioration in profitability.

    Stronger order intake could also provide improved visibility over future revenue if current demand translates into sales as anticipated. Continued progress across CML’s key communications markets will therefore be important in determining whether the early FY27 momentum can be sustained.

    The company’s financial position provides some support for its growth strategy. CML has a low-debt balance sheet and delivered improved cash flow during 2026, providing greater flexibility as it works towards restoring operational profitability.

    However, recent weakness in earnings remains a consideration, while technical indicators continue to signal softer momentum. The shares are trading below key moving averages and the MACD remains negative.

    Valuation is also mixed. A relatively high P/E ratio limits some of the valuation appeal, although this is partly balanced by the company’s dividend yield.

    More about CML Microsystems

    CML Microsystems Plc develops mixed-signal, radio frequency and microwave semiconductors for communications markets worldwide.

    The group serves specialised market segments characterised by relatively high barriers to entry and structural demand for faster, more secure data transmission. Its products are also exposed to investment in telecommunications infrastructure and the expansion of private commercial wireless networks associated with the industrial internet of things.

    CML combines outsourced manufacturing with its own testing capabilities and operates across the UK, Asia and the US. Its customer base includes established commercial and industrial equipment manufacturers.

    The group operates with no debt, generates cash and pays dividends, providing a financial foundation for its longer-term growth strategy.

    CML Microsystems shares trade on the London Stock Exchange under the symbol CML.

  • Afentra Reports Pacassa SW Oil Discovery and Restarts Impala-1 Production in Angola

    Afentra Reports Pacassa SW Oil Discovery and Restarts Impala-1 Production in Angola

    Afentra (LSE:AET) has reported a series of operational advances in Angola, led by an oil discovery at Pacassa SW and the restart of production from the Impala-1 well, strengthening the company’s near-term production and development pipeline.

    The Pacassa SW well encountered 136 metres of net oil pay within the Albian Pinda carbonate reservoir. The result supports previous estimates that the Pacassa SW area could contain up to 70 million barrels of gross recoverable resources.

    Following the discovery, the well is being completed for production, with first oil targeted for the third quarter of 2026. Bringing Pacassa SW into production would provide Afentra with another source of output as it continues to develop its Angolan portfolio.

    The company has also successfully returned Impala-1 to production after the well had remained shut in since 2017. A low-cost slickline intervention removed an obstruction from the wellbore, allowing production to resume at approximately 3,000 barrels of oil per day.

    In addition to restoring production, the intervention generated reservoir information that has reduced subsurface uncertainty ahead of the planned Impala-2 development well.

    Drilling at Impala-2 is expected to begin after completion of operations at Pacassa SW. The well has a production target of around 4,000 barrels per day and could represent the next stage of redevelopment at the Impala field if drilling delivers the anticipated results.

    Afentra has also completed its first offshore operational campaign as operator of Block 3/24. The company deployed a compact remotely operated vehicle from a local vessel to inspect subsea wellheads and collect integrity and video information.

    The campaign was completed without safety or environmental incidents and cost approximately $60,000. Afentra said this was around 90% below typical market rates for comparable survey work.

    Information gathered during the programme will contribute to technical evaluation of Block 3/24 ahead of a potential future Final Investment Decision on the GPQ development.

    Together, the Pacassa SW discovery, Impala-1 restart and Block 3/24 work provide several avenues for organic growth within Afentra’s Angolan portfolio. Pacassa offers a potential near-term production addition, while Impala-2 and GPQ represent further development opportunities.

    The company’s broader financial position remains more mixed. A decline in revenue during 2025, a return to net losses and significantly negative free cash flow continue to weigh on the outlook, although the balance sheet remains comparatively sound.

    Technical indicators are broadly neutral, with the negative MACD pointing to slightly weaker momentum. Valuation measures offer limited support while earnings remain negative, reflected in a negative P/E ratio, and no dividend yield is available.

    More about Afentra

    Afentra plc is an upstream oil and gas company focused on production, redevelopment and exploration opportunities in Africa, with its portfolio concentrated primarily in Angola.

    The company’s Angolan interests include offshore Blocks 3/05, 3/05A, 3/24 and 23, together with onshore Kwanza Basin blocks KON4, KON15 and KON19.

    Its portfolio combines producing mature fields with redevelopment and exploration opportunities, allowing Afentra to pursue near-term cash generation alongside longer-term resource and production growth.

    The company focuses on disciplined capital allocation, cost-efficient interventions and pragmatic project execution as it seeks to extract additional value from established assets and build a larger Angolan upstream business.

    Afentra shares trade on the London Stock Exchange under the symbol AET.

  • Shoe Zone Improves Full-Year Outlook Following Strong July Trading

    Shoe Zone Improves Full-Year Outlook Following Strong July Trading

    Shoe Zone (LSE:SHOE) has reported continued positive trading through July, prompting the footwear retailer to narrow its expected full-year loss as its cash position performs ahead of the original budget.

    Cash and cash equivalents stood at approximately £7.0 million as of 25 July 2026, exceeding the company’s initial expectations.

    Following the stronger trading performance, the board now expects an adjusted loss before tax of no more than £1.0 million for the financial year ending 3 October 2026.

    The revised expectation indicates an improvement in Shoe Zone’s financial trajectory, although the company is still forecast to remain loss-making for the year.

    Its stronger-than-budgeted cash position provides some additional financial flexibility as the retailer operates against a challenging consumer backdrop. The performance also suggests that Shoe Zone’s value-focused proposition and combination of physical stores and online sales are continuing to support the business.

    For investors, attention will now turn to whether the improved momentum can be sustained through the remainder of the financial year and whether stronger cash generation can ultimately translate into a return to profitability.

    The wider financial picture remains mixed. Weaker profitability continues to weigh on the outlook, although cash generation and improved leverage compared with earlier years provide some offset.

    Technical indicators are more supportive, with the shares trading above major moving averages. However, overbought readings could indicate increased near-term technical risk.

    Valuation remains less supportive while the company is loss-making, reflected in a negative P/E ratio, while no dividend yield is available to provide an income contribution.

    More about Shoe Zone

    Shoe Zone plc is a UK footwear retailer focused on providing affordable shoes for customers across a combination of town-centre stores, retail parks and online channels.

    The company operates 253 stores, ranging from its traditional high-street locations to larger-format outlets carrying additional brands including Skechers, Hush Puppies, Rieker and Lilley & Skinner. Its physical estate is supported by the shoezone.com online platform.

    Shoe Zone sells approximately 13.3 million pairs of shoes annually at an average price of around £13 and employs approximately 2,050 people across the UK.

    Its multichannel model is designed to serve value-conscious consumers with a broad range of footwear for different members of the family. Shoe Zone shares trade on the London Stock Exchange under the symbol SHOE.

  • Amaroq Begins 2026 Nanoq Drilling Programme to Advance Greenland Gold Project

    Amaroq Begins 2026 Nanoq Drilling Programme to Advance Greenland Gold Project

    Amaroq Ltd. (LSE:AMRQ) has started its 2026 resource drilling programme at the Nanoq gold project in South Greenland, targeting greater drill density and continuity following high-grade results from its 2025 exploration campaign.

    Three company-owned drill rigs have been deployed at Nanoq, with the programme focused primarily on the Central Zone. The planned campaign is expected to be broadly comparable with the 4,807 metres of drilling completed during 2025.

    Amaroq will also conduct step-out drilling at the parallel West 1 Zone, providing an opportunity to test the wider extent of mineralisation beyond the principal area of exploration.

    The programme is designed to generate the geological information required to support a potential maiden Mineral Resource Estimate later in 2026. Achieving that milestone would represent an important step in Amaroq’s strategy to establish Nanoq as its next high-grade gold project alongside the producing Nalunaq mine.

    In parallel with drilling, Amaroq is conducting preliminary metallurgical testing at SGS Lakefield in Canada. The work will assess whether material from Nanoq could be processed using the existing gravity and flotation flowsheet at Nalunaq.

    If metallurgical compatibility is demonstrated, the existing processing infrastructure could potentially support bulk sampling and trial processing of Nanoq material, providing another route for evaluating the project as exploration advances.

    Amaroq is also assessing infrastructure requirements around Nanoq, including a potential harbour and access road. These improvements are being considered as part of plans to strengthen site access from 2027 onwards.

    Better infrastructure could reduce logistical costs and make it easier to conduct larger exploration and development programmes as the project progresses.

    The combination of resource drilling, metallurgical testing and early infrastructure planning represents a broader push to move Nanoq beyond exploration towards a more defined development opportunity. Results from the 2026 drilling campaign will be particularly important in determining whether the company can establish sufficient continuity and scale to support a maiden resource estimate.

    More about Amaroq Ltd.

    Amaroq Ltd. is a Greenland-focused mining and exploration company developing gold and strategic metal assets across South and West Greenland.

    Its principal asset is the producing Nalunaq gold mine in South Greenland, while its wider exploration portfolio includes prospective projects targeting gold, copper, nickel, rare earth elements and other base and precious metals.

    The company is pursuing a strategy of developing a full-cycle mining business in Greenland, combining production from established assets with exploration and development of additional mineral projects.

    Amaroq shares trade on the London Stock Exchange under the symbol AMRQ.