Category: Market News

  • Travis Perkins Improves Profitability and Balance Sheet Despite Soft Construction Demand

    Travis Perkins Improves Profitability and Balance Sheet Despite Soft Construction Demand

    Travis Perkins (LSE:TPK) reported revenue of £2.26 billion for the first half of 2026, a decline of 1.8% from the previous year as UK construction activity remained subdued and following the earlier disposal of its Staircraft business. Despite lower sales, adjusted operating profit increased to £67 million, supported by an £11 million improvement in gross margin and higher gains from property transactions.

    Performance varied across the group’s divisions during the period. General Merchant delivered stronger margins through improved pricing discipline and procurement efficiencies, while Toolstation UK achieved growth in both revenue and profitability. Trading conditions in the Benelux remained challenging, although the group’s specialist businesses proved resilient as infrastructure-related demand helped offset weakness in residential new-build markets.

    Travis Perkins also strengthened its financial position, ending the period with net cash of £55 million before lease liabilities. Leverage fell to 1.9 times adjusted EBITDA, returning to the company’s target range of 1.5 to 2.0 times and supporting its investment-grade financial profile. The improvement reflected disciplined capital expenditure, effective working capital management and continued optimisation of the property portfolio.

    Although operational performance continued to improve, the Board reduced the interim dividend to 4.0 pence per share in line with its policy of distributing between 30% and 40% of earnings. Management expects market conditions to remain broadly unchanged during the second half of the year as the construction sector continues to face weak demand and fluctuating building material costs.

    Chief Executive Gavin Slark said the group’s turnaround programme is making encouraging progress, citing greater stability within the senior leadership team and a renewed emphasis on customer service. He added that the stronger balance sheet provides the flexibility to invest selectively while positioning the business to benefit when construction markets recover.

    The company’s investment outlook remains constrained by the weaker profitability recorded during 2024 and 2025, together with negative technical indicators, including trading below key moving averages and a bearish MACD. However, stronger operating cash flow, improved free cash flow and moderate leverage provide some support. Valuation remains mixed, with the absence of positive earnings offset in part by a dividend yield of around 2.3%.

    More about Travis Perkins

    Travis Perkins plc is the UK’s largest distributor of building materials, supplying professional tradespeople and construction businesses through its General Merchant network, Toolstation stores and specialist operations. The company serves a broad range of residential, commercial and infrastructure markets across the UK, with a smaller presence in the Benelux region.

    Its business combines traditional builders’ merchanting with trade-focused retail and specialist distribution, making the group an important indicator of activity across the UK construction sector. Alongside its nationwide branch network, Travis Perkins manages an extensive property portfolio and vehicle fleet, using disciplined capital allocation and operational efficiency to support long-term financial performance.
  • Sabre Insurance Reports Strong Premium Growth as Ambition 2030 Strategy Progresses

    Sabre Insurance Reports Strong Premium Growth as Ambition 2030 Strategy Progresses

    Sabre Insurance Group (LSE:SBRE) delivered a strong performance during the first half of 2026, with gross written premiums increasing by more than 15% compared with the same period last year. Premiums from its core motor vehicle business rose by more than 18%, reflecting continued growth despite challenging conditions across the UK motor insurance market.

    The group’s interim net insurance margin was 15.7%, below its long-term target, while the expense ratio remained elevated due to the impact of higher business volumes written in previous periods. However, management said new business continues to be priced at margins that fully account for claims inflation, providing confidence in future profitability.

    Sabre expects the strong premium growth recorded in the first half to contribute more significantly to earnings during the second half of the year, supporting an improvement in the expense ratio and a return to its target net insurance margin range of 18% to 22%. The company also continued to reward shareholders through a 4.1 pence interim dividend and a £5 million share buyback programme.

    Growth initiatives remain centred on the Ambition 2030 strategy, including the expansion of the Sabre Direct motorcycle insurance offering and the wider use of artificial intelligence across pricing and operational processes. Management believes these investments will help drive profitable growth as market conditions continue to stabilise, despite ongoing claims inflation.

    Sabre’s outlook is supported by a strong financial position, including low leverage, improving earnings momentum and an attractive valuation underpinned by a relatively high dividend yield. However, historical fluctuations in profitability and cash flow, together with technical indicators suggesting the shares may be overbought, could create some short-term risks.

    More about Sabre Insurance Group plc

    Sabre Insurance Group plc is a UK motor insurance specialist focused on providing cover for private motor vehicles and motorcycles. The company operates with a disciplined underwriting approach, aiming to maintain net insurance margins of between 18% and 22% while carefully managing the impact of claims inflation.

    Through its Ambition 2030 strategy, Sabre is investing in product expansion, including its direct motorcycle insurance business, while introducing artificial intelligence to improve pricing accuracy and operational efficiency. The group also maintains a strong capital position to support long-term growth and shareholder returns.

  • Seraphim Space Trust Deploys C Share Capital into Pixxel and Zeno Power

    Seraphim Space Trust Deploys C Share Capital into Pixxel and Zeno Power

    Seraphim Space Investment Trust Plc (LSE:SSIT) has started investing the £137 million raised through its recent C Share issue, committing $25 million to hyperspectral imaging company Pixxel and a further $3.6 million to nuclear power technology developer Zeno Power. Both businesses are existing portfolio holdings, reflecting the trust’s strategy of increasing investment in established SpaceTech companies with strong growth potential rather than adding new investments.

    Pixxel is continuing to expand its high-resolution hyperspectral Earth observation satellite constellation alongside its AI-powered analytics platform. The company also benefits from in-house satellite manufacturing capabilities and a number of significant contracts with the Indian government, strengthening its position across both commercial and sovereign markets.

    Meanwhile, Zeno Power is developing radioisotope power systems designed for applications in lunar exploration, maritime operations and defence. The business is supported by contracts with organisations including NASA, the US Navy and the US Space Force. Seraphim Space Investment Trust said the deployment of proceeds from the C Share fundraising remains on schedule and is focused on long-term investment themes such as Earth observation, advanced energy technologies and the emerging lunar economy.

    The trust’s investment outlook is moderated by consistently negative operating cash flow and earnings that are heavily influenced by changes in portfolio valuations. However, its debt-free balance sheet provides financial stability. Technical indicators point to weak short-term momentum, with the shares trading below key moving averages, while a relatively low price-to-earnings ratio offers only limited support.

    More about Seraphim Space Investment Trust Plc

    Seraphim Space Investment Trust Plc is the world’s first publicly listed investment company dedicated exclusively to the SpaceTech sector. Listed on the London Stock Exchange under the ticker SSIT, the trust invests in innovative businesses developing technologies for commercial and government applications across the global space industry.

    Its portfolio includes companies focused on satellite infrastructure, Earth observation, artificial intelligence, defence technologies and advanced energy systems. By investing in businesses positioned to benefit from long-term trends such as sovereign space capability, national security and lunar exploration, the trust aims to capture growth across the rapidly evolving space economy.

  • CLS Holdings Lowers 2026 Outlook as Leasing Activity Remains Subdued

    CLS Holdings Lowers 2026 Outlook as Leasing Activity Remains Subdued

    CLS Holdings plc (LSE:CLI) has reduced its earnings guidance for 2026 after weaker-than-expected leasing activity during the first half of the year. The company expects vacancy levels to remain around 14.5%, while the departure of the largest tenant at its Spring Gardens property, following the expiry of its lease in late September, is also expected to affect occupancy. CLS now anticipates reporting interim EPRA earnings of 2.7 pence per share and EPRA Net Tangible Assets of 177.7 pence per share at 30 June, following a 4.6% decline in property valuations driven by higher market yields.

    The softer trading environment is expected to continue into the second half, leading the Board to lower its full-year EPRA earnings guidance to between 4.6 pence and 5.5 pence per share, below existing market expectations. Despite this, the company said its balance sheet improvement programme remains on schedule. CLS has completed £62 million of asset disposals and remains on track to achieve £100 million of sales by the end of the year. It has also made significant progress in refinancing more than half of the £190 million of debt due to mature during 2026.

    Management said its long-term strategy remains unchanged despite the near-term challenges. The company believes its locally managed property portfolio, together with ongoing debt reduction and refinancing initiatives, will strengthen financial flexibility and leave the business better positioned to benefit from an eventual recovery in the commercial property market.

    CLS Holdings’ investment outlook continues to be affected by persistent losses, relatively high leverage for an office-focused real estate investment group and weak technical indicators, with the shares trading below key moving averages and a negative MACD signal. However, a relatively attractive dividend yield and generally positive cash flow provide some support, although these factors do not fully offset concerns over profitability and market trends.

    More about CLS Holdings

    CLS Holdings plc is a UK-based real estate investment company that owns and manages office properties across several European markets. Its portfolio is concentrated in well-located commercial assets, while the company continues to execute a strategy of selective disposals and refinancing to improve its balance sheet and enhance financial flexibility.

    The group’s performance is closely linked to rental income, occupancy levels and property valuations, making metrics such as EPRA earnings and EPRA Net Tangible Assets important indicators of operating performance. Through active portfolio management and local market expertise, CLS aims to position the business for improved returns as conditions in the office property sector recover.

  • Keller Group Delivers Strong First-Half Performance as Order Book Reaches New High

    Keller Group Delivers Strong First-Half Performance as Order Book Reaches New High

    Keller Group (LSE:KLR) reported a strong set of results for the six months ended 30 June 2026, with revenue increasing to £1.61 billion and underlying operating profit rising to £117.9 million. Growth was led by record trading volumes and higher profitability in North America, while the group also delivered solid performances across Europe, the Middle East and Australasia. Improved margins and a 22% increase in underlying earnings per share reflected continued operational strength across the business.

    The group’s financial position also strengthened during the period, with covenant net debt reduced to £15.9 million and leverage falling to just 0.1 times. This has enabled Keller to increase shareholder returns through a £100 million share buyback programme and a 57% rise in its interim dividend, while maintaining flexibility to pursue future acquisitions.

    Keller ended the first half with a record order book of £1.9 billion, supported by major infrastructure projects and continued demand from the data centre sector. Management said the strong pipeline provides confidence for the remainder of the financial year and positions the company to benefit from long-term investment in infrastructure and commercial development.

    The company’s outlook is supported by improving financial fundamentals, consistent free cash flow generation and a stronger balance sheet. Recent trading has also been reinforced by positive management commentary highlighting record performance, low leverage and enhanced capital returns. While technical indicators remain positive, they suggest the shares may be trading in overbought territory. Valuation appears reasonable, although not significantly discounted, which moderates the overall investment outlook.

    More about Keller Group plc

    Keller Group plc is the world’s largest specialist geotechnical contractor, providing foundation engineering and ground improvement solutions for construction projects around the globe. The company employs approximately 10,000 people across five continents and completes around 5,500 projects each year, generating annual revenue of roughly £3 billion.

    Its geographically diversified business spans North America, Europe, the Middle East and the Asia-Pacific region, serving infrastructure, commercial and industrial construction markets. Keller’s technical expertise and broad international footprint position the company to benefit from long-term trends including infrastructure modernisation and the growing demand for data centre construction.

  • Great Western Mining Prepares to Begin Defender Tungsten Drilling

    Great Western Mining Prepares to Begin Defender Tungsten Drilling

    Great Western Mining (LSE:GWMO) has completed the site preparation work required to begin drilling at its Defender Tungsten Project in Mineral County, Nevada, with drilling expected to commence during the first half of August. Preparations have included geophysical surveys, geological mapping, trenching, road improvements and the construction of drill pads, providing the groundwork for a programme designed to enhance understanding of the project’s geology.

    The company has also appointed Addison Mining Services as the independent Competent Person to prepare the maiden JORC-compliant mineral resource estimate for the Defender project. Principal Geologist Lewis Harvey will oversee onsite geological logging, data collection and quality assurance throughout the drilling campaign.

    Laboratory assay results from the drilling programme, together with findings from metallurgical bulk sample testing, are expected during September and October. Great Western Mining said it remains fully funded to complete the work and is targeting publication of its initial JORC mineral resource estimate before the end of the fourth quarter of 2026.

    The company’s outlook continues to be influenced by weak financial performance, reflecting the absence of revenue, ongoing losses and negative free cash flow. These factors are partly offset by a debt-free balance sheet, which provides financial stability as exploration activities progress. Technical indicators also remain subdued, with the shares trading below their 20-day and 50-day moving averages alongside a negative MACD reading. Valuation remains difficult to assess while the company is loss-making and does not pay a dividend.

    More about Great Western Mining

    Great Western Mining Corporation PLC is a mineral exploration and development company focused on a portfolio of wholly owned mining claims in Mineral County, Nevada. The company is increasing its exposure to tungsten, a strategically important critical mineral, while also advancing its Huntoon Copper Project, which hosts an existing JORC-compliant mineral resource.

    Alongside its copper and tungsten projects, Great Western Mining continues to explore for gold and silver across its Nevada assets and is pursuing opportunities in tailings reprocessing to unlock additional value from historic mining operations.

  • SIG Advances Vision 2030 Strategy Despite Challenging Construction Conditions

    SIG Advances Vision 2030 Strategy Despite Challenging Construction Conditions

    SIG plc (LSE:SHI) reported first-half revenue of £1.29 billion, slightly below the previous year, as like-for-like sales declined 1.5% against a backdrop of subdued construction activity and poor weather during the opening quarter. Gross margin eased to 23.9%, while underlying operating profit fell to £10.5 million. The company also reported a wider underlying pre-tax loss and net debt of £532 million.

    Despite the difficult trading environment, SIG said every business division returned to profitability during the period. The group also maintained liquidity of £154 million and reported market share gains in several key regions, including the UK roofing market, Poland and the Benelux countries, reflecting continued progress in its operational performance.

    With construction markets expected to remain challenging through 2027, SIG is stepping up its Vision 2030 transformation programme. The company is targeting a £50 million annualised improvement in operating profit by the middle of 2028 and aims to generate at least £100 million in cash by the end of 2027. These initiatives are intended to reduce leverage to below 3.0x and support long-term operating margins of between 3% and 5%.

    The transformation plan focuses on procurement efficiencies, streamlining back-office operations, optimising the distribution network and branch footprint, simplifying the product portfolio and deploying AI-powered tools to improve pricing, inventory management and route planning. The strategy also includes updated sustainability objectives and continued investment in reducing fleet emissions.

    SIG’s investment outlook remains constrained by weak underlying fundamentals, including declining revenue, continued net losses and elevated debt levels, although recent free cash flow has shown improvement. Technical indicators are broadly neutral with only limited signs of momentum, while valuation remains under pressure due to negative earnings and the absence of dividend support.

    More about SIG plc

    SIG plc is a specialist distributor of building products operating across the UK, Ireland and mainland Europe. The group supplies insulation, roofing and interior building materials to trade customers through an extensive distribution network spanning the UK, France, Germany, the Benelux region and Poland.

    The company focuses on serving professional construction customers with a wide range of products, technical expertise and logistics services. Its customer base is primarily made up of smaller contractors and installers, supported by local distribution centres and specialist product knowledge.

  • Metro Bank Delivers Strongest Half-Year Performance on Record

    Metro Bank Delivers Strongest Half-Year Performance on Record

    Metro Bank (LSE:MTRO) has reported the highest half-year profit in its history, with underlying profit before tax rising 34% year-on-year to £61 million for the first six months of 2026. The lender also recorded a 43% increase in core target lending, which reached £6.2 billion, while its net interest margin continued to improve, ending the period at 3.25%.

    The bank retained the lowest cost of deposits among its UK high street banking peers and reported further improvements in asset quality, supported by lower levels of arrears and non-performing loans. Management also reaffirmed its return-on-tangible-equity targets through 2028, highlighting continued confidence in its strategy to expand its presence in the corporate, commercial and specialist mortgage markets. Although customer deposits edged lower during the period and capital and liquidity ratios declined slightly, the bank said it remains well positioned to deliver sustainable growth.

    Metro Bank’s outlook is tempered by relatively weak recent cash flow generation and an elevated level of leverage, despite stronger profitability during 2025. Technical indicators remain broadly supportive, although they suggest the shares may be trading in overbought territory. From a valuation perspective, the stock continues to benefit from a comparatively low price-to-earnings ratio.

    More about Metro Bank

    Metro Bank Holdings PLC is a UK-based retail and commercial bank that provides banking services to individuals, small and medium-sized businesses, and larger corporate customers. Its product offering includes current and savings accounts, business lending and specialist mortgage solutions.

    The bank is focused on expanding its higher-margin corporate, commercial and specialist mortgage businesses while continuing to reduce exposure to its legacy prime residential mortgage portfolio and government-backed lending programmes. This strategy is intended to improve profitability and support long-term growth across its core markets.

  • Phoenix Copper Maintains Idaho Mining Claims and Clears Convertible Debt

    Phoenix Copper Maintains Idaho Mining Claims and Clears Convertible Debt

    Phoenix Copper (LSE:PXC) has renewed its unpatented mining claims in Idaho after completing its recent fundraising, ensuring the company retains those assets for a further year. By paying the required annual assessment fees, Phoenix Copper has preserved its exploration and development rights across its land package in the Alder Creek district, including the Empire Mine and surrounding projects. The renewal supports the company’s ongoing strategy to advance its operations and maintain continuity across its core U.S. assets.

    The company has also settled the outstanding principal under its convertible loan agreement with Indigo Capital LP in full. With the debt now repaid and all associated obligations discharged, Phoenix Copper has simplified its capital structure and removed a potential source of future shareholder dilution. The repayment is expected to improve the company’s financial position as it works towards providing additional operational updates.

    Phoenix Copper’s current investment outlook continues to be weighed down by weak financial fundamentals, including the absence of revenue, continuing losses and ongoing cash outflows, despite some signs of improvement. Technical indicators also remain negative, with the shares trading well below key moving averages, alongside a bearish MACD reading and a very low Relative Strength Index (RSI). While valuation offers limited support, the company’s negative earnings and lack of dividend payments continue to constrain the overall assessment.

    More about Phoenix Copper

    Phoenix Copper Limited is an AIM-listed mining and exploration company focused on developing base and precious metal projects in the United States, with copper, gold and silver forming the core of its production strategy. Its principal asset is the Empire Mine in Idaho’s historic Alder Creek district, where exploration drilling carried out since 2017 has significantly expanded the open-pit resource and established substantial proven and probable reserves.

    In addition to its 80% interest in the Empire project, the company owns several historic producing mines within the district, including Horseshoe, White Knob and Blue Bird. Its portfolio also includes the high-grade Red Star silver-lead deposit, the Navarre Creek gold exploration project and two cobalt properties located along the Idaho Cobalt Belt. Phoenix Copper is listed on both London’s AIM market and the OTCQX market in the United States, providing access to investors across both regions as it advances its development plans.

  • MedPal AI Builds Momentum with Record July as Annualised Recurring Revenue Climbs Above £8.6 Million

    MedPal AI Builds Momentum with Record July as Annualised Recurring Revenue Climbs Above £8.6 Million

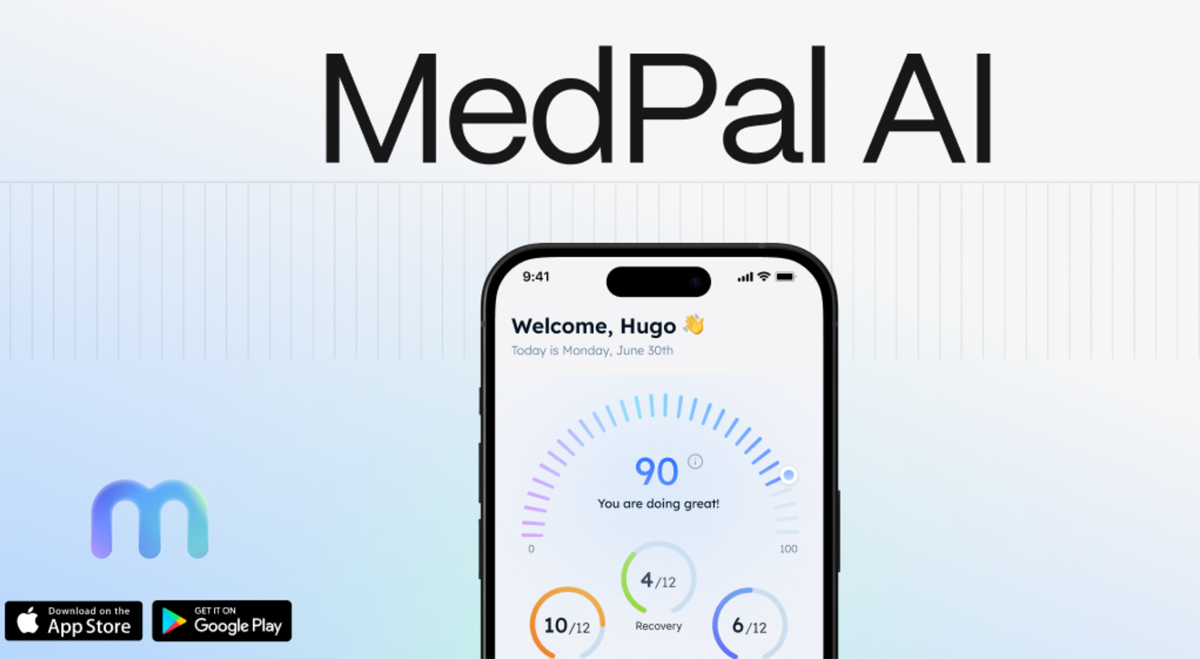
    MedPal AI plc (LSE:MPAL) has delivered another significant milestone in its rapid growth story, reporting a record trading month in July as all three of its recurring revenue streams contributed simultaneously for the first time. Just nine months after launching its dispensing operations, the AI-native digital health and pharmacy group has built an annualised recurring revenue run rate of more than £8.6 million, underlining the speed at which its integrated healthcare model is scaling.

    The latest update demonstrates that MedPal is evolving beyond a traditional pharmacy business into a diversified digital healthcare platform, combining NHS pharmacy services, private healthcare and software-as-a-service (SaaS) into a business built around recurring, predictable income.

    From Standing Start to Multi-Million Pound Revenue

    Perhaps the most striking aspect of the update is the pace of execution.

    Since beginning dispensing operations in October 2025, MedPal has grown from zero revenue to an annualised run rate exceeding £8.6 million. Even more impressive is the acceleration in recent months, with recurring revenue increasing by more than 70% since the beginning of June, when the Group reported an annualised run rate of over £5 million.

    For investors, this highlights management’s ability to execute on its strategy while successfully integrating multiple revenue-generating businesses.

    NHS Pharmacy Continues to Break Records

    The Group’s NHS prescription business remains a key growth engine.

    During July, MedPal dispensed 47,223 NHS prescription items, setting a new company record and representing an 11.8% increase over the previous monthly high achieved in May.

    That operational momentum has lifted the NHS pharmacy business to an annualised turnover run rate exceeding £5.5 million, demonstrating continued patient acquisition and growing prescription volumes.

    The recurring nature of NHS prescriptions also provides a solid foundation for future revenue visibility, as patients typically remain with their nominated pharmacy for ongoing medication needs.

    Private Healthcare Showing Early Success

    While the NHS business continues to expand, MedPal’s private healthcare offering is already making an encouraging contribution.

    The Group’s New Health GLP-1 weight management clinic generated more than £180,000 of revenue during July, despite marketing activity having been live for only three weeks.

    This equates to an annualised revenue run rate exceeding £2.2 million, suggesting strong early demand for the service and providing another recurring revenue stream through monthly treatment plans.

    With obesity treatment and preventative healthcare remaining major themes across the healthcare sector, New Health gives MedPal exposure to one of the fastest-growing areas of digital medicine.

    SaaS Adds High-Margin Revenue

    The acquisition of eMARx (Solid State Technologies) introduces another attractive dimension to MedPal’s business model.

    The software platform contributes approximately £843,000 in annualised recurring subscription revenue, while generating an impressive 82% gross margin.

    Unlike dispensing operations, SaaS revenues typically require relatively low incremental costs as customer numbers grow, potentially supporting improving profitability over time.

    The addition also broadens MedPal’s customer base across care homes and pharmacies while complementing its wider healthcare ecosystem.

    The Power of Multiple Recurring Revenue Streams

    One of the most attractive features of MedPal’s update is that every revenue stream shares one common characteristic: repeat business.

    Rather than relying on one-off transactions, the Group generates ongoing income from:

    • Monthly NHS prescription renewals 

    • Recurring private GLP-1 treatment plans 

    • Monthly SaaS software subscriptions 

    This creates greater revenue visibility while reducing dependence on continual customer acquisition.

    As recurring revenues increase, investors often view businesses as having stronger earnings quality and improved long-term scalability.

    Cross-Selling Creates Further Opportunity

    Management believes the current growth trajectory represents only the beginning.

    The next phase of expansion focuses on increasing the lifetime value of each customer by connecting MedPal’s various healthcare services.

    Private patients using New Health will be encouraged to nominate MedPal for their everyday NHS prescriptions, while the wider customer base will gain access to additional products including:

    • At-home blood testing 

    • The MedPal Health OS platform 

    • Juno, the Group’s AI-powered health companion 

    This strategy of delivering multiple services to each customer could significantly increase recurring revenue without requiring the same pace of new customer acquisition.

    Building an Integrated Digital Healthcare Platform

    Chief Executive Officer Jason Drummond summed up the progress by noting that every pound of July’s revenue is recurring, spanning NHS prescriptions, private treatment plans and software subscriptions.

    Perhaps equally important is his emphasis that the Group is only beginning to unlock the opportunities created by integrating these businesses.

    With three revenue engines now operational, high-margin software added to the mix, and cross-selling initiatives still to come, MedPal appears to be building a healthcare ecosystem rather than a single-service business.

    Outlook

    July’s trading update highlights a company delivering rapid operational execution across multiple fronts.

    Record NHS prescription volumes, strong early traction from New Health, the addition of high-margin SaaS revenue and a recurring revenue base now exceeding £8.6 million annualised all point towards a business gaining momentum.

    If MedPal can continue successfully cross-selling services across its growing customer base while maintaining its pace of customer acquisition, the Group could be well positioned to build further scale in the expanding digital healthcare market.

    For more information visit https://www.medpal.ai/