Category: Market News

  • Predator Oil & Gas Extends Rig Agreement for MOU-6 Drilling Programme

    Predator Oil & Gas Extends Rig Agreement for MOU-6 Drilling Programme

    Predator Oil & Gas Holdings Plc (LSE:PRD) has revised its drilling agreement with Intrepid Drilling, extending the availability of Rig 101 for operations at the MOU-6 well in Morocco from 1 August through 1 October 2026. The rig, which is currently stationed at the MOU-5 location, will support a three-month drilling and potential testing campaign targeting the MOU-6 gas prospect in Morocco before moving to the Snowcap-3 oil well in Trinidad.

    Chief executive Paul Griffiths said the company has dedicated the past 15 months to strengthening its well delivery capabilities across several regions, ensuring drilling plans are more closely aligned with anticipated geological conditions. He added that positive drilling and testing results at MOU-6 and Snowcap-3 could significantly reduce development risk, paving the way for faster production opportunities, subject to regulatory approvals and due diligence. The programme supports Predator’s objective of commercialising its Moroccan gas assets while increasing oil production from its Trinidad portfolio over the near term.

    Despite operational progress, Predator continues to face financial challenges, including significant losses, negative profit margins and ongoing cash outflows. These weaknesses have been partly offset by stronger revenue growth and a relatively low level of debt. Market indicators remain broadly neutral, with limited technical momentum, while valuation metrics are constrained by the absence of positive earnings and dividend yield data.

    About Predator Oil & Gas Holdings Plc

    Predator Oil & Gas Holdings Plc is a Jersey-based oil and gas exploration and production company listed on the London Stock Exchange. Its core operations are focused on onshore projects in Morocco and Trinidad, where it is developing gas and oil assets with an emphasis on efficient production and long-term growth. In Morocco, the company is advancing gas projects that could support compressed natural gas (CNG) or micro-LNG developments, while its Trinidad portfolio is centred on increasing output from mature onshore oil fields through production optimisation, infill drilling and the use of historic tax losses.

    Predator’s business model is designed around maintaining a lean operating structure while drawing on experienced technical, financial and legal expertise with extensive local knowledge of both Morocco and Trinidad. The company plans to accelerate Moroccan gas development by taking advantage of existing export infrastructure, while expanding Trinidad production through cost-effective technologies and a Master Services Agreement that allows field operations to be outsourced while retaining a share of gross production revenues.
  • GSK Beats Second-Quarter Forecasts and Unveils £1.9 Billion Efficiency Programme

    GSK Beats Second-Quarter Forecasts and Unveils £1.9 Billion Efficiency Programme

    GSK Plc (LSE:GSK) reported stronger-than-expected second-quarter results on Tuesday, driven by continued momentum in its Specialty Medicines and Vaccines businesses, while announcing a major three-year cost-saving initiative aimed at supporting future growth.

    Second-quarter turnover reached £8.41 billion, ahead of the analyst consensus estimate of £8.24 billion.

    New Cost-Saving Plan to Support Drug Pipeline

    The pharmaceutical group introduced a new restructuring programme, named “Accelerate Growth”, which is expected to generate annual savings of £1.9 billion by 2029.

    The initiative is projected to cost approximately £2.4 billion in total, including around £2.1 billion in cash expenditure.

    GSK said the savings would be reinvested into its late-stage research pipeline while helping to protect profit margins as its HIV treatment dolutegravir approaches patent expiry between 2028 and 2030.

    The company also increased its expectations for clinical development, saying it now plans to begin more than 20 late-stage clinical trials during 2026, compared with its previous target of 10.

    Management identified seven potential medicines across 18 disease areas, including cancer, respiratory disease, liver disease and vaccines, that it believes could offer improvements over existing treatments.

    Most restructuring costs associated with the programme are expected to be recognised during 2026 and 2027.

    Profit Exceeds Market Expectations

    Core operating profit rose to £2.80 billion, surpassing the consensus estimate of £2.68 billion.

    Core profit before taxation reached £2.68 billion, ahead of the expected £2.52 billion, while core earnings per share came in at 50.5 pence, comfortably above the analyst consensus of 47.1 pence.

    GSK also declared a second-quarter dividend of 17 pence per share, matching market expectations.

    Specialty Medicines and Vaccines Continue to Drive Growth

    Sales from the Specialty Medicines division increased 14% to £3.8 billion.

    Within the segment, Oncology revenue rose 17%, while HIV sales increased 10%.

    Vaccines revenue climbed 8% to £2.3 billion, supported by Shingrix sales of £0.9 billion, up 3%, and Meningitis vaccine sales of £0.2 billion, which more than doubled from a year earlier.

    General Medicines revenue declined 9% to £2.3 billion, with Trelegy sales falling 7% to £0.8 billion.

    Positive Cancer Trial and New UK Research Investment

    GSK also reported positive late-stage trial results in China for its cancer treatment risvutatug rezetecan (Ris-Rez), which slowed disease progression in patients with relapsed osteosarcoma.

    The study was conducted by GSK’s partner Hansoh Pharma. The company said the findings build on previous positive late-stage results for the same treatment in advanced lung cancer, making Ris-Rez the only medicine of its type to demonstrate successful late-stage outcomes across more than one cancer indication.

    Separately, GSK announced plans to establish a new 300,000-square-foot research and development centre at the Cambridge Biomedical Campus in the UK.

    The facility will accommodate more than 1,000 scientists working across Oncology, Respiratory, Hepatology, Vaccines and HIV research.

    The company will invest £400 million over the next three years in the project. As part of the plan, GSK will gradually relocate employees from its Stevenage research site by 2029 while upgrading its laboratories in Ware, Hertfordshire.

    “This investment will accelerate our R&D and help us deliver new, competitive products. It integrates GSK further into one of the world’s leading centres of knowledge and demonstrates the attractiveness of the UK’s life sciences ecosystem,” chief executive Luke Miels said in a statement.

    Full-Year Outlook Maintained

    GSK reaffirmed its outlook for 2026, continuing to expect annual turnover growth of between 3% and 5%, with performance anticipated to be towards the upper end of that range.

  • The 13th flight wasn’t the charm for SpaceX

    The 13th flight wasn’t the charm for SpaceX

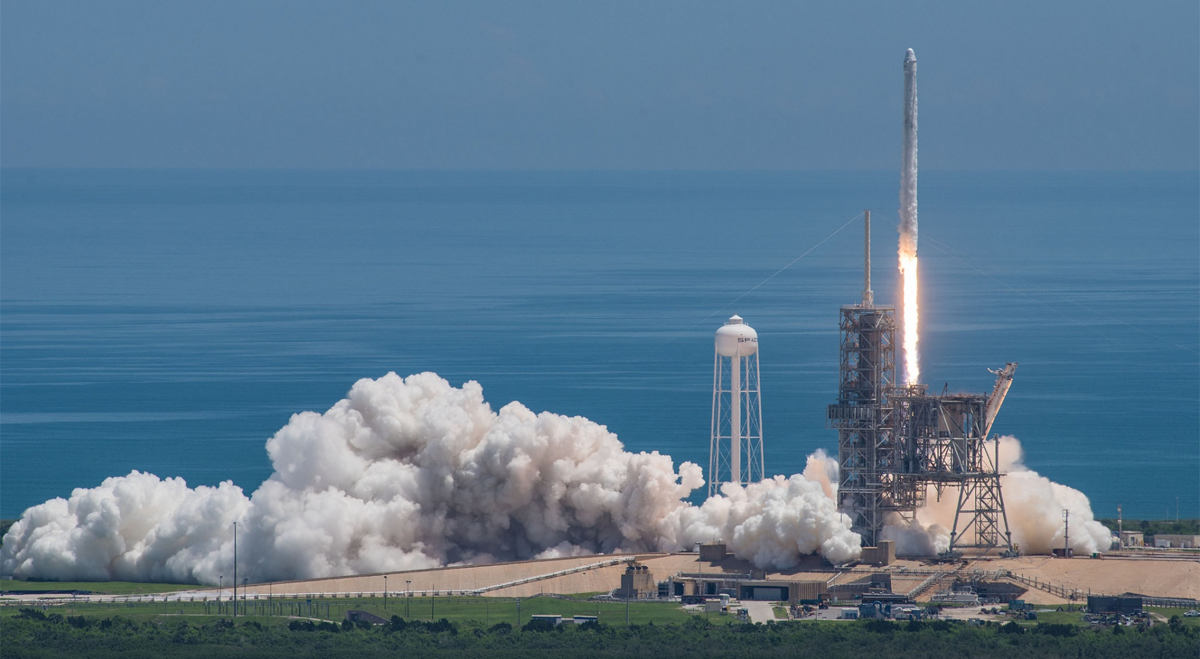
    Last week, SpaceX launched Starship’s 13th test flight, the spacecraft designed for future Moon and Mars missions. While the mission was successful, a partial engine failure during the Super Heavy booster landing burn may have damaged the launch pad and did little to help SpaceX shares, which fell to $113.50 on Monday, almost 20% below their $135 IPO price. 

    And the stock may not have bottomed yet.

    According to Aswath Damodaran, aka the “Dean of Valuation”, SpaceX is worth about $1.3 trillion, or almost $100 per share, assuming the AI market is worth tens of trillions, xAI faces lower margins due to competition and high costs, and SpaceX will need to spend heavily on infrastructure. Now, if the company overestimates the AI market and keeps pouring money into xAI despite weaker economics, the investment case could deteriorate even further.

    Another headwind could come from upcoming lockup expirations. About 20% of insider-held shares will become available for sale two days after SpaceX reports its first earnings as a public company, potentially flooding the market with nearly 1 billion shares. For comparison, only 629 million shares were sold in the June 12 IPO. Another wave hits around August 20, when 455.8 million more shares could enter the market.

    On top of that, tech sentiment has turned increasingly volatile in recent weeks.

    Yet bulls aren’t backing down. Morgan Stanley, for example, said Flight 13 boosted confidence in Starship’s progress, with a successful Flight 14 tower catch seen as the next major catalyst, and kept its Overweight rating with a $300 price target versus Wall Street’s $237 average. 

    As for what could drive the stock higher, positive SpaceX catalysts could trigger a short squeeze, forcing bears to cover and pushing shares higher. 

  • UBS Sees Palladium Prices Falling as Market Heads for Supply Surplus

    UBS Sees Palladium Prices Falling as Market Heads for Supply Surplus

    UBS has become more cautious on the outlook for palladium, lowering its price target after forecasting that the market will move into surplus during the year. The investment bank now expects palladium to trade around $1,100 per ounce.

    The bank noted that China’s palladium imports reached record levels during the first six months of the year. However, UBS believes the increase was mainly linked to the launch of a new trading exchange rather than stronger demand from the automotive industry.

    Higher Recycling Supply Expected to Outweigh Mine Output Decline

    UBS forecasts that the global palladium market will record an oversupply of roughly 200,000 ounces this year.

    While mine production is expected to be lower than in 2025, increased recycled metal entering the market, together with softer investment demand and weaker consumption from the autocatalyst sector, is expected to more than compensate for reduced mining output.

    The bank believes these supply and demand dynamics will continue to place downward pressure on palladium prices throughout the remainder of the year.

    Automotive Sector Continues to Shape Palladium Demand

    UBS maintains a negative outlook for palladium, arguing that supply growth and weaker end-market demand leave little scope for a sustained recovery in prices.

    Palladium is widely used in catalytic converters for gasoline-powered vehicles, making demand closely linked to trends in global vehicle production and environmental emissions standards.

  • Oil Prices Continue Lower as US-Iran Negotiations Reduce Supply Concerns

    Oil Prices Continue Lower as US-Iran Negotiations Reduce Supply Concerns

    Oil prices extended their decline on Tuesday after renewed diplomatic efforts between the United States and Iran strengthened hopes that tensions in the Middle East could continue to ease, reducing fears of major disruptions to global crude supplies.

    By 01:23 GMT, Brent crude futures were down 1.3% at $87.24 per barrel, while West Texas Intermediate (WTI) crude futures fell 1.2% to $81.61 per barrel. The decline followed Monday’s steep sell-off, when both benchmark contracts dropped by more than 9%.

    The latest move lower reflects a broad reassessment of geopolitical risks after last week’s sharp rally, as traders reduced positions built on expectations of prolonged supply disruptions.

    Diplomatic Momentum Pressures the Oil Market

    After briefly climbing above $100 per barrel last week, Brent crude has retreated sharply as investors become increasingly optimistic that diplomatic efforts could prevent a wider regional conflict.

    Market sentiment improved after President Donald Trump confirmed that the United States was holding negotiations with Iran following his decision to suspend additional military strikes and allow diplomacy to continue.

    Iran also paused its retaliatory actions after the United States halted further attacks, while reports suggested China had been encouraging renewed dialogue between Washington and Tehran.

    According to IG senior market analyst Tony Sycamore, the sharp decline in crude prices reflects growing confidence that a diplomatic solution may be emerging, reducing immediate concerns about threats to Middle East energy infrastructure.

    He also warned that the situation remains uncertain, adding that investors still require stronger evidence of a lasting agreement before fully removing geopolitical risk premiums from oil prices.

    Shipping Routes Remain a Key Risk

    Despite the improvement in sentiment, Sycamore said tanker movements through the Strait of Hormuz remain below normal levels, while shipping activity through the Bab el-Mandeb Strait has yet to recover significantly.

    He noted that negotiations aimed at securing navigation through the Strait of Hormuz will remain a major focus for energy markets. Any failure in talks or renewed attacks on Saudi export facilities could quickly drive crude prices higher again.

    Iran and Oman continue discussions designed to restore normal shipping through the strategic waterway, which carries roughly 20% of global oil exports.

    A successful diplomatic outcome could pave the way for broader negotiations between Washington and Tehran, although uncertainty continues to keep traders cautious.

    Markets also welcomed the resumption of loading operations at Kazakhstan’s primary oil export terminal following disruptions caused by Ukrainian drone attacks, easing concerns over short-term crude supplies.

  • Gold Prices Drift Lower Ahead of Fed Decision as Strong US Dollar Pressures Bullion

    Gold Prices Drift Lower Ahead of Fed Decision as Strong US Dollar Pressures Bullion

    Gold prices edged lower on Tuesday as a firmer US dollar continued to weigh on investor demand, with markets awaiting the Federal Reserve’s latest policy announcement and comments from Chair Kevin Warsh for fresh signals on the direction of interest rates.

    Spot gold fell 0.7% to $4,048.40 per ounce by 07:07 GMT, while US Gold Futures also declined 0.7% to $4,049.10. The precious metal had recorded modest gains over the previous two sessions.

    Investors Watch Federal Reserve for Interest Rate Signals

    The US Dollar Index remained close to its highest level in nearly a month, making gold more expensive for buyers holding other currencies and limiting demand for the safe-haven asset.

    Markets widely expect the Federal Reserve to leave interest rates unchanged when its two-day meeting concludes on Wednesday.

    Even so, expectations for further tightening have increased in recent sessions. According to the CME FedWatch tool, traders are assigning roughly a 40% probability to a rate increase this week and an 80% chance of another hike in September.

    Because gold does not generate interest income, rising interest rates generally reduce its appeal compared with interest-bearing assets.

    Investors also remained on the sidelines ahead of several important US economic releases later this week, including second-quarter GDP data and the Federal Reserve’s preferred inflation indicator.

    Analysts said gold is likely to remain rangebound until markets receive greater clarity on the outlook for monetary policy.

    Iran Talks Ease Geopolitical Concerns

    Geopolitical tensions also remained in focus after US President Donald Trump said Washington was holding “good talks” with Iran, while cautioning that military action could resume if negotiations failed.

    The temporary suspension of hostilities between the United States and Iran has helped calm concerns over global energy supplies, reducing inflation expectations in recent days.

    Oil prices continued to decline during Asian trading, adding further support to the view that energy-related inflation pressures may ease.

    Elsewhere, silver dropped 1.8% to $57.387 per ounce, while platinum fell 0.9% to $1,611.60 per ounce.

    Industrial metals were also weaker. London Metal Exchange copper futures slipped 0.6% to $13,677.33 per tonne, while US copper futures declined 0.5% to $6.364 per pound.

  • US Markets Look Ahead to Big Tech Earnings and Fed Decision Amid AI and Geopolitical Concerns: Dow Jones, S&P, Nasdaq, Wall Street Futures

    US Markets Look Ahead to Big Tech Earnings and Fed Decision Amid AI and Geopolitical Concerns: Dow Jones, S&P, Nasdaq, Wall Street Futures

    US stock futures traded mixed on Tuesday as investors prepared for a pivotal week dominated by major technology earnings and the Federal Reserve’s latest policy meeting, while continuing to monitor geopolitical tensions in the Middle East.

    At 07:43 GMT, Dow Jones futures edged 0.1% higher, S&P 500 futures slipped 0.3%, and Nasdaq 100 futures lost 0.9%, reflecting continued weakness in technology stocks.

    Wall Street ended Monday with mixed results after lower oil prices and easing Treasury yields lifted sentiment following a temporary pause in hostilities between the United States and Iran. Even so, markets remained cautious as investors assessed the risk that higher energy costs could reignite inflation and influence future Federal Reserve policy.

    Artificial intelligence remained a major focus. Investors are increasingly questioning whether the enormous levels of spending on AI infrastructure will continue to deliver strong returns, making this week’s earnings reports particularly significant.

    Nvidia (NASDAQ:NVDA) came under pressure after reports suggested the company could provide financial guarantees worth approximately $250 billion for a large OpenAI data centre project. Meanwhile, increased competition from Chinese memory chip producer CXMT and reports that Apple (NASDAQ:AAPL) has requested approval to use Chinese-made chips in selected products added further pressure to semiconductor shares.

    The Philadelphia Semiconductor Index declined 2.2%, with the Wall Street Journal reporting that every constituent closed below its 50-day moving average for the first time since April 2025.

    Investors Await Results From Technology Leaders

    The corporate earnings calendar intensifies this week.

    Before markets open, Coca-Cola Company (NYSE:KO) and Boeing (NYSE:BA) are scheduled to report quarterly earnings. Investors will assess consumer demand trends at Coca-Cola and continue monitoring Boeing’s operational recovery.

    After the market closes, Visa (NYSE:V) will release results that could provide fresh insight into consumer spending patterns, while Seagate Technology (NASDAQ:STX) is expected to offer additional commentary on AI-related demand.

    The biggest releases will come from Microsoft (NASDAQ:MSFT), Meta Platforms (NASDAQ:META), Apple (NASDAQ:AAPL) and Amazon (NASDAQ:AMZN), whose investment in AI infrastructure continues to shape market expectations for the sector.

    Federal Reserve Meeting Takes Centre Stage

    Markets are also focused on the Federal Reserve’s two-day policy meeting, which concludes on Wednesday with its latest interest rate announcement.

    Although recent inflation data has shown signs of easing, volatility in energy markets linked to Middle East tensions continues to cloud the outlook. Meanwhile, the US labour market remains relatively resilient.

    According to CME FedWatch, investors currently see roughly a two-thirds chance that the Federal Reserve will keep interest rates unchanged between 3.5% and 3.75%, while a 25-basis-point increase remains a possibility.

    Trump and Netanyahu Prepare for White House Meeting

    President Donald Trump is expected to host Israeli Prime Minister Benjamin Netanyahu at the White House on Wednesday as diplomatic discussions continue alongside the conflict involving Iran.

    While direct military exchanges have paused in recent days, uncertainty remains over the prospects for a lasting ceasefire.

    Trump described negotiations with Tehran as “good talks,” while warning that military action could resume if diplomacy fails.

    Asian Chip Stocks Extend Global Technology Weakness

    Technology shares in Asia also came under heavy selling pressure.

    South Korea’s KOSPI fell sharply as semiconductor manufacturers were hit by concerns over AI-related valuations and continued capital expenditure across the industry.

    The announcement of new US tariffs on South Korean imports added to investor caution.

    SK Hynix Inc (NASDAQ:SKHY) and Samsung Electronics Co Ltd (USOTC:SSNHZ) both recorded steep declines, contributing to the broader weakness across global semiconductor markets.

  • European Stocks Edge Higher as Strong Corporate Earnings Offset Interest Rate Concerns: DAX, CAC, FTSE100

    European Stocks Edge Higher as Strong Corporate Earnings Offset Interest Rate Concerns: DAX, CAC, FTSE100

    European equity markets traded slightly higher on Tuesday as a series of encouraging corporate earnings reports helped counter investor concerns over persistent inflation and rising bond yields ahead of the US Federal Reserve’s latest policy decision.

    The pan-European STOXX 600 gained 0.2% in early trading. Germany’s DAX also advanced 0.2%, France’s CAC 40 climbed 0.5%, while London’s FTSE 100 traded broadly unchanged.

    Among the strongest performers was Unilever (LSE:ULVR), whose shares jumped around 6% after the consumer goods group reported second-quarter underlying sales growth ahead of market expectations. The performance was supported by resilient sales volumes and continued pricing strength across its personal care and food businesses.

    Unilever’s results were viewed as a positive indicator for the wider European economy, suggesting consumer demand for essential household products remains resilient despite higher borrowing costs and ongoing inflationary pressures.

    Luxury giant LVMH (EU:MC) gained 2.6% after reporting improved second-quarter sales, supported by solid demand for luxury goods in the United States.

    Telecommunications group Orange (EU:ORA) rose nearly 4% after increasing its full-year profit and cash flow guidance.

    In the automotive sector, Mercedes-Benz (TG:MBG) advanced 3.5% after reporting stronger second-quarter profit, despite lowering its vehicle sales forecast for 2026. Fellow German manufacturers BMW (TG:BMW) and Volkswagen (TG:VOW3), the parent company of Audi, also gained around 2%.

    Elsewhere, French aerospace supplier Safran (EU:SAF) moved higher after raising its financial targets for the full year following record first-half operating margins.

    Dutch healthcare technology company Philips (EU:PHIA), however, fell 8.5%, despite reporting second-quarter core earnings that exceeded analyst expectations.

    As the European reporting season gathers pace, company results continue to highlight diverging trends across industries. Luxury goods manufacturers and some industrial businesses remain under pressure from higher interest rates and weaker consumer spending, while defensive sectors such as consumer staples, healthcare and aerospace continue to demonstrate resilient demand, pricing power and operational strength.

    Although oil prices continued to soften, European equity markets remained cautious as government bond yields stayed elevated. Investors continue to expect central banks to maintain relatively high interest rates in the near term, limiting support for equity valuations.

    Additional pressure came from comments by European Central Bank Governing Council member Peter Kazimir, who said another interest rate increase in September could still be appropriate even if the Eurozone economy improves, reinforcing expectations that policymakers remain focused on tackling inflation.

    Attention is now shifting to the United States, where the Federal Reserve begins its two-day policy meeting ahead of Wednesday’s interest rate announcement. While policymakers are widely expected to leave rates unchanged, investors will closely monitor Chair Kevin Warsh’s remarks for signals on the future direction of monetary policy.

  • European Luxury Stocks Advance as LVMH’s Fashion Business Returns to Growth

    European Luxury Stocks Advance as LVMH’s Fashion Business Returns to Growth

    European luxury shares moved higher on Tuesday after LVMH (EU:MC) reported stronger second-quarter sales growth and confirmed that its flagship Fashion & Leather Goods division returned to positive growth, providing fresh optimism for a sector that has faced subdued consumer demand over the past two years.

    By 08:11 GMT, Kering (EU:KER) had gained around 2%, while Hermès (LSE:RMS) and L’Oréal (EU:OR) posted more modest gains of less than 1%.

    Despite the positive sector reaction, LVMH shares reversed earlier gains to trade around 1.5% lower, as investors remained unconvinced that the improvement marked the beginning of a sustained recovery in the group’s most profitable business.

    The luxury group, which owns brands including Louis Vuitton and Dior and is widely regarded as a benchmark for the industry, generated second-quarter revenue of €19.52 billion. Organic sales increased 3% compared with the same period last year, improving on the 1% growth recorded during the first quarter and exceeding analysts’ expectations of €19.45 billion, according to a Visible Alpha survey.

    LVMH’s Fashion & Leather Goods division reported quarterly revenue of €8.9 billion, representing a 1% increase from a year earlier. The result marked a significant improvement from the 2% decline recorded in the previous quarter and ended several consecutive quarters of falling sales. However, the performance remained below analysts’ expectations for growth of 1.7%, with the company citing softer consumer spending across Europe as tourism was affected by the conflict involving Iran.

    Analysts at RBC Capital Markets said the main challenge now is whether the division can deliver full-year expectations despite more demanding comparisons in the third quarter, adding that achieving this would be necessary “for the stock to start working.”

    LVMH, led by Chairman and Chief Executive Bernard Arnault, said geopolitical and economic uncertainty has intensified as a result of the conflict in the Middle East.

    Excluding the effects of the conflict, second-quarter revenue increased by 4%.

  • FTSE 100 Rises as Technology Sell-Off Eases While Middle East Tensions Remain in Focus

    FTSE 100 Rises as Technology Sell-Off Eases While Middle East Tensions Remain in Focus

    The FTSE 100 moved higher on Tuesday, recovering from early losses as selling pressure in technology stocks eased following reports of progress in China’s domestic semiconductor equipment industry. Investors also continued to monitor geopolitical developments in the Middle East and the latest round of UK corporate earnings.

    By 07:40 GMT, the FTSE 100 was up 0.22%, while Germany’s DAX gained 0.29% and France’s CAC 40 advanced 0.42%. Sterling was little changed against the US dollar, with GBP/USD edging 0.05% higher to 1.33051.

    Technology stocks came under pressure earlier in the session after reports suggested China had made significant advances in developing home-grown semiconductor manufacturing equipment. The news weighed on major US chipmakers ahead of the market open, with Nvidia and AMD both trading lower in pre-market activity.

    The weakness spread across Asian markets, with Japan’s Nikkei 225 and South Korea’s Kospi posting notable declines as semiconductor manufacturers Samsung Electronics and SK Hynix fell sharply. Hong Kong’s Hang Seng and China’s Shanghai Composite recorded more modest losses, while Australia’s S&P/ASX 200 ended the session in positive territory.

    Meanwhile, geopolitical tensions remained elevated after Yemen’s Houthi movement claimed responsibility for drone attacks targeting Saudi Arabian crude oil supply and transport infrastructure, including facilities linked to shipments to the Red Sea port of Yanbu.

    Military spokesperson Brigadier General Yahya Saree said the strikes were carried out in response to what the group described as “Saudi enemy drone incursions into Yemeni airspace.”

    The Houthis also claimed to have shot down a Saudi Bayraktar Akinci drone over Al-Jawf Governorate on July 26.

    In the United States, President Donald Trump said he was not concerned by Israeli objections to a proposed sale of F-35 fighter jets to Turkey ahead of talks in Washington with Israeli Prime Minister Benjamin Netanyahu.

    “Nobody tells me what we should be selling,” Trump said, describing Turkey as “a tremendous ally.”

    Trump also dismissed suggestions that Russian support for Iran had materially influenced the conflict, stating, “They have no army, they have no air force, they have no navy.” He added that he intended to discuss Ukrainian allegations regarding Russian satellite intelligence support for Iran during future talks with President Vladimir Putin.

    Separately, a federal judge in Florida granted Trump’s legal team until August 27 to amend its $15 billion defamation lawsuit against The New York Times. The newspaper described the case as “an attempt to stifle independent reporting” with “no merit.”

    Commodity markets were weaker during the session. Brent crude fell 1.5% to $84.59 a barrel, while WTI crude declined 1.4% to $81.40. Gold futures dropped 0.64% to $4,050.70 per ounce, with spot gold also trading lower.

    UK Corporate Highlights

    BT (LSE:BT.A) said its Openreach division is facing a proposed intervention from regulator Ofcom over a discounted broadband pricing initiative that the watchdog believes could make it more difficult for alternative fibre providers to compete.

    Barclays (LSE:BARC) reported a 17% increase in first-half profit, exceeded market expectations, upgraded its 2026 income guidance and announced a £1 billion share buyback, supported by strong performances in equities trading and investment banking.

    Unilever (LSE:ULVR) delivered second-quarter sales growth ahead of forecasts and raised its outlook for underlying sales growth in 2026 as demand remained resilient across its beauty, home care and household product businesses.

    Unite Group (LSE:UTG) reported an 8% decline in adjusted first-half earnings, partly reflecting acquisition-related costs, but maintained its full-year guidance as it continued to optimise its property portfolio.

    Man Group (LSE:MAN) announced record assets under management alongside stronger-than-expected first-half client inflows, benefiting from heightened market volatility that supported demand for its investment products.

    SSP Group (LSE:SSPG) reaffirmed its full-year outlook after posting solid third-quarter sales growth. Strong trading in the UK and Ireland helped offset weaker passenger demand in markets affected by disruption in the Middle East.