Category: Market News

  • Ashtead Technology maintains full-year outlook while monitoring Middle East conflict (AT.)

    Ashtead Technology maintains full-year outlook while monitoring Middle East conflict (AT.)

    Ashtead Technology (LSE:AT.) said it remains confident in meeting full-year market expectations despite disruption to activity in the Middle East during the first half of 2026. The Aberdeen-based subsea technology specialist said its outlook assumes geopolitical tensions between the United States and Iran ease during the second half of the year, allowing customer projects to progress as planned.

    Revenue edges higher despite regional disruption

    The company generated revenue of 100.2 million pounds during the first six months of 2026, representing a 1 percent increase compared with the same period last year.

    EBITDA margin declined to 25.0 percent from 27.3 percent a year earlier, reflecting weaker rental activity in the Middle East and Asia, together with a higher proportion of lower-margin, non-rental revenues linked to project scheduling.

    Ashtead said: “The impact of the geopolitical tension in the Middle East continues to be monitored closely, and the group is working with its customers and partners in the region to manage changing vessel schedules and project priorities.”

    The company added: “Assuming that the disruption associated with the Middle East conflict eases through the second half, and there are no major changes to project scheduling, the board is comfortable with full-year market expectations.”

    Energy security continues to support demand

    Ashtead expects stronger trading during the second half of the year and continues to target a full-year EBITA margin in the high twenties.

    The latest update follows heightened tensions in the Middle East after the United States carried out strikes on multiple targets in Iran on 12 July. Iran subsequently launched retaliatory attacks, including strikes that reportedly hit three Kuwaiti border posts and a Kuwait Oil Company drilling platform.

    The company said growing attention on energy security, combined with a strong customer project backlog, continues to support confidence in its medium-term growth prospects.

    Management remains focused on long-term opportunities

    Ashtead’s latest comments build on remarks made by Chief Executive Allan Pirie during the company’s 2025 annual results in March, when he said the business remained alert to developments in the Middle East.

    At the time, Pirie said the company was, “mindful of the evolving situation” and would be “closely monitoring” the impact of the conflict on its operations.

    Ashtead is scheduled to publish its full first-half 2026 results at the beginning of September.
  • Barratt Redrow increases shareholder returns after resilient year in challenging housing market (BTRW)

    Barratt Redrow increases shareholder returns after resilient year in challenging housing market (BTRW)

    Barratt Redrow (LSE:BTRW) delivered a solid performance during the 2026 financial year despite continued challenges across the UK housing market. The company completed 17,667 homes and reported adjusted profit before tax in line with market expectations. Careful cost management, lower land expenditure and disciplined operations helped protect margins, while the group ended the year with net cash of approximately 772 million pounds.

    Stable demand supports outlook

    Customer demand remained affected by wider economic and geopolitical uncertainty, although reservation rates improved slightly during the year and affordable housing completions increased.

    Looking ahead, Barratt Redrow expects to complete between 17,700 and 18,200 homes during the 2027 financial year. Management anticipates limited house price inflation, while build cost inflation is expected to remain in the range of 3 percent to 4 percent.

    Capital allocation shifts towards share buybacks

    The board has introduced a revised capital allocation strategy that places greater emphasis on share buybacks instead of ordinary dividends. Management believes the company’s share price continues to trade at a significant discount to tangible net asset value, making buybacks a more attractive use of capital.

    During the 2027 financial year, Barratt Redrow intends to return around 400 million pounds to shareholders, with the majority expected to be delivered through share repurchases. The company said it will continue to invest in land acquisitions and work in progress while meeting ongoing commitments related to land creditors and building safety remediation.

    Strong balance sheet supports long-term strategy

    Management said the revised capital allocation approach reflects confidence in the company’s financial strength and its ability to generate cash over the long term.

    The business continues to focus on improving returns through integration synergies following the Redrow combination, increasing the number of active sales outlets and maintaining disciplined land investment. These initiatives are intended to strengthen shareholder returns while preserving balance sheet flexibility.

    Although Barratt Redrow benefits from a solid balance sheet, healthy revenue growth and an attractive valuation, investors continue to monitor weaker cash flow and softer technical share price performance.

    About Barratt Redrow plc

    Barratt Redrow plc is one of the United Kingdom’s largest residential property developers, operating through three complementary housebuilding brands that deliver private and affordable homes across the country.

    The company serves owner occupiers, private rental investors and institutional customers while maintaining a strong focus on build quality and customer satisfaction. Following the integration of Redrow, Barratt Redrow continues to pursue cost synergies, operational efficiencies and disciplined capital allocation to support long-term shareholder value.

  • Audioboom delivers record first half as revenue and profit accelerate (BOOM)

    Audioboom delivers record first half as revenue and profit accelerate (BOOM)

    Audioboom (LSE:BOOM) reported its strongest first-half performance to date, with revenue increasing 30 percent year on year to 45.7 million dollars and gross profit rising 33 percent to 9.9 million dollars. Growth was driven by continued strength in the company’s Showcase advertising marketplace, alongside a significant increase in podcast downloads and video views. Adjusted EBITDA climbed 80 percent to 3.2 million dollars, while higher margins and a stronger cash position reflected improving operational performance.

    Revenue momentum continues to build

    Cash balances more than doubled during the period to 5.4 million dollars, and Audioboom has already secured more than 81 million dollars of revenue for 2026, surpassing total revenue generated during the previous year.

    Management said the results demonstrate the scalability of the business model and continued demand from advertisers and content creators across its podcasting platform.

    Strategic partnerships support future growth

    During the period, Audioboom expanded its strategic relationships with Spotify and Apple to strengthen video monetisation opportunities. The company also continued to grow its creator network by signing several high-profile podcast shows while benefiting from the integration of the Adelicious acquisition, which has strengthened its presence in the UK advertising market.

    Following a strategic review, the board decided not to pursue three takeover proposals after concluding they did not reflect the company’s long-term value. Instead, Audioboom plans to continue pursuing growth through acquisitions, supported by a proposed 10 million dollar revolving credit facility.

    Management said expanding scale, continued investment in technology and sustainable profitable growth remain the company’s key strategic priorities.

    Profitability improves despite valuation concerns

    Audioboom continues to benefit from improving profitability and a relatively low-debt balance sheet, strengthening its financial position.

    However, investors continue to monitor weaker cash flow reported during 2025, while the shares remain in a longer-term technical downtrend despite recent oversold conditions. The company’s relatively high price-to-earnings ratio also continues to present a valuation challenge.

    About Audioboom Group

    Audioboom Group is a global podcasting company that provides advertising technology, content distribution and monetisation services for more than 8,000 podcast creators.

    The company distributes podcasts across major platforms including Apple Podcasts, Spotify, YouTube and Amazon Music and is one of the largest podcast publishers in the United States. Its network reaches approximately 183 million monthly downloads and video views and around 58 million unique listeners worldwide.

  • Bloomsbury expects record annual profit after strong start to the financial year (BMY)

    Bloomsbury expects record annual profit after strong start to the financial year (BMY)

    Bloomsbury Publishing (LSE:BMY) said trading during the first four months of the 2026 to 2027 financial year has been strong, giving the Board confidence that the company is on track to deliver record adjusted profit in line with market expectations. Ahead of its annual general meeting, the publisher highlighted a strong release schedule in its Consumer Division, continued growth in its Academic and Professional business and ongoing contributions from artificial intelligence licensing agreements.

    Publishing pipeline supports outlook

    The Consumer Division is benefiting from a strong publishing programme featuring new releases from several bestselling authors. Bloomsbury also expects additional demand from the upcoming HBO Harry Potter television series, which is anticipated to introduce the books to a new generation of readers.

    The Academic and Professional Division continued to deliver underlying growth across all geographic markets, providing a stable source of recurring revenue alongside the consumer publishing business.

    Management said revenue generated through artificial intelligence licensing agreements also continues to support financial performance.

    Further details on trading are expected when the company publishes its interim results in October 2026.

    Strong financial position underpins confidence

    Bloomsbury continues to benefit from healthy free cash flow generation and a low leverage balance sheet, supporting investment in new publishing opportunities while maintaining financial flexibility.

    The shares also trade on what management considers to be an attractive valuation, supported by a relatively low price-to-earnings ratio and a solid dividend yield.

    Technical indicators remain positive, with the share price trading above key moving averages. However, the company noted that lower revenue and earnings reported during 2026 continue to provide a degree of caution when assessing the longer-term outlook.

    About Bloomsbury Publishing PLC

    Bloomsbury Publishing PLC is an independent publishing company listed on the London Stock Exchange. The business operates through its Consumer and Academic and Professional divisions, publishing bestselling fiction, non-fiction and specialist academic content for readers and institutions worldwide.

    Alongside its traditional publishing activities, Bloomsbury has expanded its revenue streams through licensing agreements that allow artificial intelligence developers to access selected content. The company continues to focus on building long-term value through a combination of bestselling authors, digital publishing and specialist academic resources.

  • Cohort delivers record annual results as defence demand drives order book to new high (CHRT)

    Cohort delivers record annual results as defence demand drives order book to new high (CHRT)

    Cohort plc (LSE:CHRT) reported record financial results for the year ended 30 April 2026, with revenue increasing 13 percent to 306.4 million pounds and adjusted operating profit rising 32 percent to 36.3 million pounds. The group’s adjusted operating margin improved to 11.8 percent, while adjusted earnings per share increased 14 percent. Order intake reached 314.2 million pounds, exceeding annual revenue for another year, and the company increased its dividend by 10 percent, marking its twentieth consecutive year of dividend growth.

    Record order book supports future growth

    Cohort ended the financial year with a record order book of 618.8 million pounds, extending through to 2037. Following contract awards secured after the year end, the order book now covers almost 88 percent of expected market revenue for the 2026 to 2027 financial year.

    Growth was led by the Communications and Intelligence division, which benefited from the first full year contribution from EM Solutions. Performance in the Sensors and Effectors division remained broadly stable during the year.

    Financial flexibility strengthened

    The company renewed and significantly expanded its banking facilities, increasing available funding to 175 million pounds with an additional 50 million pound accordion facility. Management said the enhanced financing provides greater flexibility to support future investment, acquisitions and long-term growth.

    Cohort also noted that trading and earnings exceeded market expectations, supported by strong international demand for defence technologies. Ongoing conflicts in Ukraine and the Middle East, rising geopolitical tensions in the Asia-Pacific region and increased NATO defence spending continue to drive customer demand across its markets.

    Positive outlook backed by strong pipeline

    Management reiterated its target of delivering double-digit earnings growth during the 2026 to 2027 financial year and the following two years. The company is also targeting around 120 million pounds of cash generation before capital expenditure and dividend payments over the same period.

    The combination of a record order book, improving margins and healthy demand provides a strong foundation for continued expansion in global defence technology markets.

    About Cohort plc

    Cohort plc is a UK-based defence technology company listed on AIM that develops communications, intelligence, surveillance, sonar and defence systems for military and government customers.

    The group operates through seven subsidiaries across the United Kingdom, Australia, Germany and Portugal and is organised into two main divisions: Communications and Intelligence, and Sensors and Effectors. Its businesses supply secure communications, electronic warfare systems, sonar technology, surveillance equipment and fire control solutions to customers across NATO countries and international defence markets.

    Cohort employs more than 1,700 people and has increased its dividend every year since its stock market listing in 2006, reflecting its long-term focus on defence technology and disciplined financial management.

  • B&M reports steady first-quarter growth as France delivers strong performance (BME)

    B&M reports steady first-quarter growth as France delivers strong performance (BME)

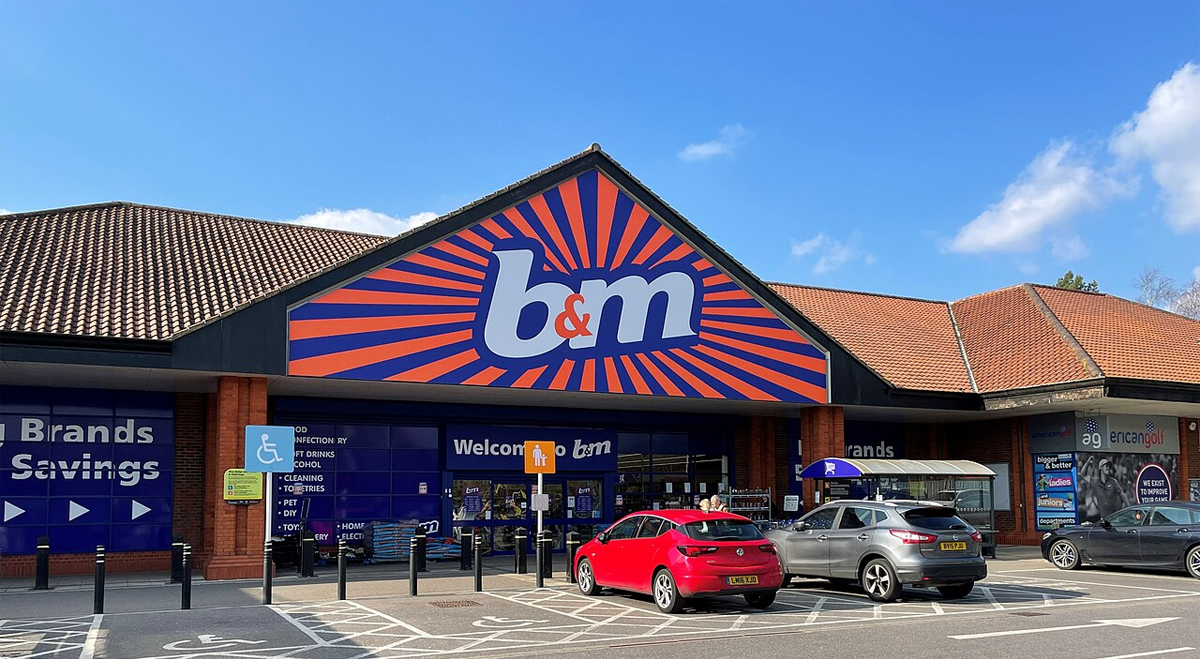
    B&M European Value Retail (LSE:BME) reported 2 percent group revenue growth during the first quarter of the 2027 financial year, supported by strong trading in France and a solid contribution from Heron Foods. In the UK, overall revenue increased modestly, although like-for-like sales declined following a weaker gardening and outdoor season compared with exceptionally strong weather-driven demand in the same period last year.

    UK business focuses on core retail strategy

    Management said trading in general merchandise has continued to improve, while disciplined inventory management has helped return seasonal stock levels to normal following successful clearance activity.

    The company is continuing to implement its Back to B&M Basics strategy, which includes simplifying its fast-moving consumer goods product range, improving margin management and strengthening operational efficiency across the business.

    B&M also announced the appointment of experienced retail executive Atheeq Akbar as chief financial officer, a move expected to support the group’s efforts to improve profitability and reinforce its position within the value retail sector.

    Cash generation remains a key strength

    The company continues to benefit from healthy cash generation and an attractive valuation, supported by a relatively low price-to-earnings ratio and a high dividend yield.

    These strengths are balanced by higher leverage and a significant decline in profitability during 2026. Technical indicators remain supportive, with the shares continuing to trade in an upward trend, although momentum is approaching levels that may indicate the stock is becoming overbought.

    About B&M European Value Retail SA

    B&M European Value Retail is a discount retailer operating across the United Kingdom and France. The group trades primarily through its B&M stores and also owns the Heron Foods and B&M Express convenience formats.

    At the end of the reporting period, the company operated 797 B&M stores in the UK, 340 Heron Foods and B&M Express outlets, and 151 B&M stores in France. Its product range focuses on general merchandise and fast-moving consumer goods, serving value-conscious consumers through a low-cost retail model.

  • NextEnergy Solar Fund begins formal sale process to address persistent valuation discount (NESF)

    NextEnergy Solar Fund begins formal sale process to address persistent valuation discount (NESF)

    NextEnergy Solar Fund Limited (LSE:NESF) has launched a formal sale process as it seeks to address the long-standing discount between its share price and net asset value. The board, supported by investment manager NextEnergy Capital IM, believes exploring a potential sale of the company could unlock greater value for shareholders following an extended period in which the market has undervalued the fund despite the performance of its underlying portfolio.

    Formal process opens to potential bidders

    The company has invited interested parties to submit proposals for the acquisition of its entire issued share capital. Rothschild and Co has been appointed to advise on the process, with prospective bidders required to enter into confidentiality and standstill agreements before receiving further information.

    At this stage, the company confirmed there are no active discussions or formal offers in place. The board also retains the right to modify, suspend or terminate the sale process at any time if it believes doing so is in the best interests of shareholders.

    The announcement also marks the beginning of an official offer period under the UK Takeover Code, triggering additional disclosure obligations for shareholders and other market participants.

    Sale process aims to unlock shareholder value

    Management said the decision reflects continued frustration with the company’s stock market valuation, with the shares trading at a sustained discount to net asset value despite stable operational performance from its solar asset portfolio.

    The board believes that exploring strategic alternatives offers the best opportunity to close the valuation gap and maximise long-term shareholder value.

    Strong balance sheet offsets earnings challenges

    NextEnergy Solar Fund continues to benefit from improving cash generation and a debt-free balance sheet, providing financial stability despite weaker financial performance in recent years.

    The company’s investment profile remains affected by declining revenue and reported losses, while technical indicators continue to point to subdued share price momentum. Although the shares offer a relatively high dividend yield, the absence of earnings profitability continues to weigh on valuation.

    About NextEnergy Solar Fund Limited

    NextEnergy Solar Fund Limited is a London-listed investment company that owns and manages a diversified portfolio of solar energy assets.

    The fund invests in utility-scale and rooftop solar projects designed to generate long-term, predictable income from renewable electricity production. Its strategy is focused on providing investors with infrastructure-style returns while supporting the transition towards cleaner energy generation.

  • Rio Tinto increases first-half production as Simandou project moves closer to completion (RIO)

    Rio Tinto increases first-half production as Simandou project moves closer to completion (RIO)

    Rio Tinto (LSE:RIO) reported a 3 percent increase in copper equivalent production during the first half of 2026, supported by record first-half iron ore production from its Pilbara operations since 2018, higher copper output and continued growth in lithium production. The company maintained its production and sales guidance across its major commodities while lowering its copper C1 net unit cost forecast following stronger gold prices and improved operating efficiency.

    Higher production supports lower copper costs

    Copper production at the Oyu Tolgoi mine increased 31 percent compared with the same period last year, while lithium production rose 53 percent. Aluminium operations also delivered resilient performance, contributing to overall production growth across the group.

    Rio Tinto said stronger by-product gold prices and ongoing productivity improvements enabled it to reduce its guidance for copper C1 net unit costs, supporting margins despite broader cost pressures across the mining sector.

    Simandou development reaches key milestone

    The company reported continued progress at its Simandou iron ore project in Guinea, with construction of the mine and port now more than three quarters complete. Full rail commissioning has also been achieved, marking another important milestone as the project moves towards production.

    Exploration and evaluation spending increased to 480 million dollars during the first half, with much of the investment directed towards expanding the company’s copper portfolio.

    Cash flow affected by one-off factors

    Operating cash flow was impacted by a 443 million dollar tax payment in Mongolia and a working capital outflow of around 1.2 billion dollars during the period.

    Despite ongoing geopolitical tensions and supply chain disruptions linked to conflict in the Middle East, Rio Tinto said its geographically diversified operations and integrated logistics network helped minimise operational disruption.

    Balanced outlook supported by diversified operations

    Rio Tinto continues to benefit from solid operating performance, positive technical momentum and an attractive dividend, supported by its diversified portfolio of mining assets.

    Investors continue to monitor higher debt levels, weaker free cash flow conversion and softer iron ore market conditions, although these factors are partly balanced by productivity improvements, growing copper production and continued progress on major development projects.

    About Rio Tinto

    Rio Tinto is one of the world’s largest mining and metals companies, producing iron ore, copper, aluminium, bauxite and lithium through operations across multiple continents.

    The company focuses on supplying essential industrial commodities to global markets while investing in productivity improvements and major development projects, including Simandou in Guinea and Oyu Tolgoi in Mongolia, to support long-term growth.

  • Supermarket Income REIT launches £100 million fundraise to support grocery property expansion (SUPR)

    Supermarket Income REIT launches £100 million fundraise to support grocery property expansion (SUPR)

    Supermarket Income REIT (LSE:SUPR) plans to raise approximately 100 million pounds through a share issue comprising an institutional placing, a South African placing for qualifying investors and a UK retail offer. The proceeds will help fund a 216 million pound pipeline of grocery property acquisitions, alongside existing debt facilities, as the company continues to expand its portfolio while targeting a loan-to-value ratio below 45 percent.

    Acquisition pipeline expected to boost earnings

    The proposed capital raise will support the acquisition of three UK supermarkets and six additional grocery properties secured by strong tenant covenants and inflation-linked leases.

    Management said the acquisition pipeline is expected to increase earnings per share from the first full year of ownership while causing only minimal dilution to net tangible assets. The properties also offer opportunities to extend lease terms, improving long-term income visibility and enhancing total returns for shareholders.

    Growth strategy backed by refinancing

    The latest fundraising follows a series of recent acquisitions and lease renewals that have increased the weighted average unexpired lease term across the portfolio.

    The company also completed a 445 million pound debt refinancing, reducing financing costs while extending the average maturity of its borrowings. Management believes these measures strengthen Supermarket Income REIT’s position as a scalable and low-cost owner of grocery real estate.

    The company continues to pursue its long-term objective of doubling the size of its property portfolio through disciplined acquisitions and prudent financial management.

    Attractive valuation supports investment case

    Supermarket Income REIT continues to benefit from a relatively attractive valuation, supported by a low price-to-earnings ratio and a high dividend yield. The business also maintains solid operating margins and a strong balance sheet.

    These strengths are partly offset by recent declines in revenue and free cash flow, together with a broadly neutral technical share price outlook. Updated dividend guidance and continued cost discipline provide additional support, although leverage and near-term earnings per share pressures remain factors for investors to monitor.

    About Supermarket Income REIT plc

    Supermarket Income REIT plc is a UK-listed real estate investment trust specialising in grocery-led property assets, including supermarkets, retail parks and distribution facilities.

    Its portfolio is primarily leased to major investment-grade supermarket operators under long-term, inflation-linked triple-net lease agreements, providing stable and predictable rental income. Alongside its UK portfolio, the company also has a selective presence in France and aims to generate long-term shareholder returns through disciplined property investment and active asset management.

  • Hunting maintains full-year guidance as subsea growth supports first-half performance (HTG)

    Hunting maintains full-year guidance as subsea growth supports first-half performance (HTG)

    Hunting PLC (LSE:HTG) reported a solid performance for the first half of 2026, with EBITDA of approximately 62 million dollars in line with guidance and an EBITDA margin of around 12 percent. Strong demand for its subsea and perforating systems businesses helped offset weaker trading across its OCTG and manufacturing operations. The company also reported a sales order book of approximately 387 million dollars, while its tender pipeline remained close to 1 billion dollars.

    Strong subsea demand supports order growth

    During the first half, Hunting secured 63.5 million dollars of orders for subsea titanium stress joints in Guyana, while its perforating systems business continued to benefit from robust demand across both international and North American markets.

    The company also continued to advance its Organic Oil Recovery technology, which now has more than 30 active customers as it moves towards broader commercial deployment.

    Second-half recovery expected

    Management maintained its full-year EBITDA guidance of between 145 million dollars and 155 million dollars and continues to expect stronger activity during the second half of the year.

    The company is also progressing restructuring initiatives within its Europe, Middle East and Africa operations, while continuing to explore bolt-on acquisitions in the subsea and intelligent completions markets. Hunting has also begun the process of appointing a new chief executive officer and confirmed plans to transition its external auditor to KPMG in 2027.

    Cash position reflects investment and shareholder returns

    Higher working capital requirements and capital returned to shareholders resulted in a modest net debt position at the halfway stage of the year. However, Hunting continues to benefit from a resilient balance sheet, supported by positive earnings guidance, a substantial tender pipeline and ongoing plans for share buybacks and dividend growth.

    Investors will continue to monitor cash flow generation and order book conversion, particularly given the cyclical nature of the energy services sector and the decline in free cash flow reported during 2025.

    About Hunting PLC

    Hunting PLC is a global precision engineering company that supplies specialised products and services to the energy industry and selected industrial markets. The company is listed on the London Stock Exchange and operates from offices and manufacturing facilities across the United Kingdom, the United States, Asia and the Middle East.

    Its business spans a range of technologies including oil country tubular goods, perforating systems, subsea equipment, advanced manufacturing and engineered products, serving customers involved in energy production and infrastructure worldwide.