Category: Market News

  • CelLBxHealth Reaffirms Growth Outlook as Search for New CEO Gets Underway (CLBX)

    CelLBxHealth Reaffirms Growth Outlook as Search for New CEO Gets Underway (CLBX)

    CelLBxHealth (LSE:CLBX) has reaffirmed its commercial outlook at its annual general meeting, highlighting continued demand for its live circulating tumour cell (CTC) capture technology and announcing the start of a search for a new chief executive.

    The company said its Parsortix platform continues to address an important clinical need in areas where circulating tumour DNA (ctDNA) testing is less effective. Management noted that the technology is attracting growing interest from pharmaceutical companies and clinicians, with its ability to integrate into existing laboratory workflows providing deeper oncology insights and supporting multiple revenue opportunities.

    The board reiterated its expectation of generating at least £2.1 million in revenue during the 2026 financial year, representing projected growth of approximately 50% compared with FY2025. Management said the core business strategy and commercial outlook remain unchanged despite the planned leadership transition.

    Executive Chairman Jan Groen will continue in his role while the company conducts its search for a new chief executive. The board said it has sufficient senior leadership in place to ensure business operations and commercial activities continue without disruption throughout the recruitment process.

    Although CelLBxHealth remains focused on expanding the commercial adoption of its technology, its outlook continues to reflect the challenges facing an early-stage healthcare company. Financial performance and valuation remain under pressure, while technical indicators suggest continued weakness in the share price. However, management believes recent operational progress and commercial milestones provide a solid foundation for future growth.

    About CelLBxHealth plc

    CelLBxHealth plc is an oncology diagnostics company specialising in circulating tumour cell (CTC) technologies for research, drug development and clinical applications. Its patented Parsortix platform captures live circulating tumour cells from blood samples and integrates with existing laboratory systems to support advanced imaging, proteomic profiling and genomic analysis.

    The company’s business model combines sales of the Parsortix platform and consumables with laboratory services for clinical trials, assay development through its GCLP-compliant UK facility, and the development of laboratory-developed tests through strategic partnerships and internal research programmes.
  • Headlam Accelerates Strategic Review as Falling Revenue Drives Wider Losses (HEAD)

    Headlam Accelerates Strategic Review as Falling Revenue Drives Wider Losses (HEAD)

    Headlam Group (LSE:HEAD) has reported a significant decline in first-half trading, with revenue from continuing operations falling 22.8% year-on-year to £188.8 million. The downturn reflected the company’s planned withdrawal from lower-margin business, challenging market conditions, inventory shortages and the impact of adverse weather, resulting in operating losses that exceeded those recorded during the same period last year.

    Trading conditions remained subdued into early July, with management indicating that activity has continued broadly in line with the weaker performance seen during June.

    Net debt increased to £36.2 million at 30 June 2026, up from £31.4 million at the end of 2025. The rise was driven by ongoing trading losses and one-off transformation costs, which more than offset proceeds generated from property disposals.

    To strengthen its financial position, the board has accelerated its strategic review and refinancing process. The company is exploring a range of options, including discussions with lenders, a potential sale-and-leaseback of its Coleshill headquarters, additional property disposals and other corporate actions aimed at improving liquidity and supporting its long-term turnaround strategy.

    Headlam’s outlook remains challenged by declining revenue, continued losses and negative cash flow, alongside a weakening balance sheet. Technical indicators also point to ongoing downside risk, with the shares remaining in a sustained downtrend despite appearing oversold. Valuation provides limited support given the company’s negative earnings and the absence of a disclosed dividend yield.

    About Headlam Group

    Headlam Group is the UK’s largest distributor of floor coverings, supplying independent retailers and flooring contractors with a wide range of flooring products. The company operates a nationwide distribution network supported by a portfolio of properties, including its headquarters in Coleshill, and serves customers across the residential and commercial flooring markets.

  • Poolbeg Pharma Secures £3.5m to Advance Cancer and Obesity Programmes (POLB)

    Poolbeg Pharma Secures £3.5m to Advance Cancer and Obesity Programmes (POLB)

    Poolbeg Pharma (LSE:POLB) has raised £3.5 million through a placing of 58.3 million new ordinary shares at 6 pence each, representing a 16% discount to the previous closing price. Executive Chair Cathal Friel participated in the fundraising with a £250,000 investment.

    Subject to the admission of the new shares to AIM, which is expected on 21 July 2026, the financing is projected to extend the company’s cash runway into the second quarter of 2028 while also supporting ongoing partnership discussions.

    The proceeds will primarily be used to complete the POLB 001 TOPICAL clinical trial in multiple myeloma patients and to progress a proof-of-concept study of the company’s oral GLP-1 obesity treatment. These programmes strengthen Poolbeg’s presence in the rapidly growing oncology and metabolic disease markets.

    The TOPICAL study is supported by the supply of teclistamab from Johnson & Johnson at no cost and forms part of the wider RISE CRS research programme. The collaboration highlights increasing industry interest in POLB 001, which is being developed to reduce cytokine release syndrome associated with cancer immunotherapy and help improve access to these treatments.

    Despite the successful fundraising, Poolbeg’s outlook continues to reflect the challenges typical of a clinical-stage biotechnology company. The business remains pre-revenue, with ongoing losses, cash burn and shareholder dilution weighing on financial performance. However, progress towards key clinical milestones, regulatory readiness and the prospect of interim trial data provide potential catalysts for investors. Although the shares have shown strong upward momentum, technical indicators suggest the stock is currently overbought, which could increase short-term volatility.

    About Poolbeg Pharma Ltd.

    Poolbeg Pharma is a clinical-stage biopharmaceutical company focused on developing innovative treatments for cancer immunotherapy complications and metabolic diseases. Its lead candidate, POLB 001, is an oral p38 MAP kinase inhibitor designed to treat cytokine release syndrome associated with cancer immunotherapy, while the company is also advancing an oral GLP-1 receptor agonist for obesity and related metabolic disorders.

  • Orosur Expands High-Grade Gold Mineralisation at APTA Prospect in Colombia (OMI)

    Orosur Expands High-Grade Gold Mineralisation at APTA Prospect in Colombia (OMI)

    Orosur Mining (LSE:OMI) has announced another set of encouraging drilling results from the APTA prospect at its Anzá Project in Colombia, with the latest hole providing further evidence that the high-grade gold system extends at depth.

    Drill hole MAP107 intersected 135.5 metres grading 1.91 grams per tonne (g/t) gold, including a higher-grade interval of 49 metres at 4.06 g/t gold. The hole ended in mineralisation, indicating that the gold system remains open and could extend beyond the current drilling limits.

    The latest results support an updated geological interpretation that suggests the deeper high-grade mineralised zones at APTA are more extensive than previously understood. As a result, Orosur has repositioned its drilling rig further east to test shallower mineralisation, with the aim of supporting a future mineral resource estimate and further expanding the project’s exploration potential.

    APTA has now been tested by more than 39,000 metres of drilling and complements the recently established Mineral Resource Estimate (MRE) at Pepas, as well as ongoing exploration at the nearby El Cedro prospect. Together, these targets highlight the significant development pipeline within the Anzá Project and the opportunity to further increase the company’s resource inventory.

    Management said Orosur remains fully funded to continue its expanded exploration programme, providing financial flexibility as it advances its understanding of the Aragon fault-hosted epithermal gold system and works towards defining a formal mineral resource at APTA.

    About Orosur Mining

    Orosur Mining Inc. is a gold exploration and development company listed on both the TSX Venture Exchange and AIM. Its flagship Anzá Project is located in Colombia’s Mid-Cauca gold belt and spans approximately 330 square kilometres through its wholly owned subsidiaries, Minera Anzá and Minera Monte Aguila. The company is advancing exploration across its three principal prospects—Pepas, APTA and El Cedro—with a focus on expanding resources and progressing future development opportunities.

  • British Land Reports Strong Leasing Activity and Reaffirms FY27 Earnings Guidance (BLND)

    British Land Reports Strong Leasing Activity and Reaffirms FY27 Earnings Guidance (BLND)

    British Land (LSE:BLND) has made a strong start to its new financial year, with solid leasing activity across its London campuses, retail parks and urban logistics portfolio reinforcing confidence in its outlook for FY27. During the period, the company completed leases covering 567,000 square feet at rental levels above both previous rents and estimated rental values, while a further 1.1 million square feet remains under offer.

    The property group said demand continues to outstrip supply across its core markets, supporting rental growth and occupancy levels. It also highlighted progress at major development projects, including Broadgate Tower and Canada Water, alongside the successful integration of its recently acquired life sciences portfolio. Retail parks continue to perform strongly, with occupancy remaining close to full capacity.

    British Land has also continued to reshape its portfolio through active capital recycling. During the period, the company completed £83 million of property disposals while acquiring the Telford Bridge retail park as part of its ongoing investment strategy.

    The company reiterated its guidance for underlying earnings per share of at least 30.5p for FY27. Management expects performance to be supported by like-for-like rental growth at the upper end of previous guidance and estimated rental value (ERV) growth of between 3% and 5%, reflecting continued strength across its prime UK real estate assets.

    British Land’s outlook is supported by an attractive valuation, including a relatively low price-to-earnings ratio and a strong dividend yield, together with an improving cash flow profile and positive share price momentum. However, earnings remain subject to the valuation movements typical of real estate investment trusts (REITs), while higher financing costs and the execution of development projects continue to present potential challenges.

    About British Land Company plc

    British Land Company plc is one of the UK’s largest commercial property owners and developers, with a portfolio focused on London campuses and retail parks. The company owns or manages property valued at £15.8 billion, with British Land’s share amounting to £10.1 billion. Its strategy centres on development, repositioning and active asset management to create high-quality, sustainable destinations for occupiers and investors.

  • Catenai Negotiates Extension to Klarian Loan Repayment Deadline (CTAI)

    Catenai Negotiates Extension to Klarian Loan Repayment Deadline (CTAI)

    Catenai PLC (LSE:CTAI) has provided an update on its £450,000 unsecured convertible loan note facility with Klarian Ltd, confirming that discussions are underway to extend the repayment deadline as uncertainty remains over when the outstanding balance will be settled.

    Under the existing agreement, Klarian had committed to repay £699,160, including principal and associated fees, by 1 July 2026. The facility also carries a monthly fee of 3% on the outstanding balance. Catenai said it is now in negotiations with Klarian to agree a further extension while repayment arrangements are finalised.

    Despite the delay, the board said it remains encouraged by Klarian’s commercial prospects. Management highlighted the company’s business plan, ongoing fundraising efforts and a sales pipeline exceeding £5 million, which could strengthen Klarian’s ability to meet its financial obligations and improve the likelihood of Catenai recovering the outstanding funds.

    The latest update highlights Catenai’s continued credit exposure to Klarian. While successful execution of Klarian’s growth strategy could improve the value of the financing arrangement, there remains a risk that the loan may not be repaid in full. Investors are therefore likely to focus on the outcome of the extension negotiations and Klarian’s fundraising progress when assessing the potential impact on Catenai’s financial position.

    Catenai’s broader outlook remains constrained by persistent losses, limited and volatile revenue, and weak technical indicators, with the shares trading below key moving averages and negative momentum signals remaining in place. However, relatively modest balance-sheet leverage and a return to positive operating cash flow during 2025 provide some support, although the company’s valuation continues to be affected by negative earnings and the absence of a dividend.

    About Catenai PLC

    Catenai PLC is an AIM-listed technology company providing digital media and IT services to customers across the corporate, public sector and education markets. The business specialises in delivering technology infrastructure and integration projects through a team of experienced project managers and technical specialists.

  • Rockfire Advances Molaoi Project With High-Grade Zinc Drilling and Feasibility Progress (ROCK)

    Rockfire Advances Molaoi Project With High-Grade Zinc Drilling and Feasibility Progress (ROCK)

    Rockfire Resources (LSE:ROCK) has announced further encouraging drilling results from its wholly owned Molaoi zinc project in Greece, with the latest programme continuing to support the upgrade of the deposit’s existing JORC Inferred Resource to Indicated status. Drill hole HMO-018 successfully infilled another 50-metre panel within the planned resource model, returning high-grade intersections of zinc, silver and germanium.

    The company also reported that portable XRF analysis from hole HMO-020 identified exceptionally high zinc, silver and lead values, reinforcing confidence in the quality and continuity of the mineralisation as the resource definition programme advances.

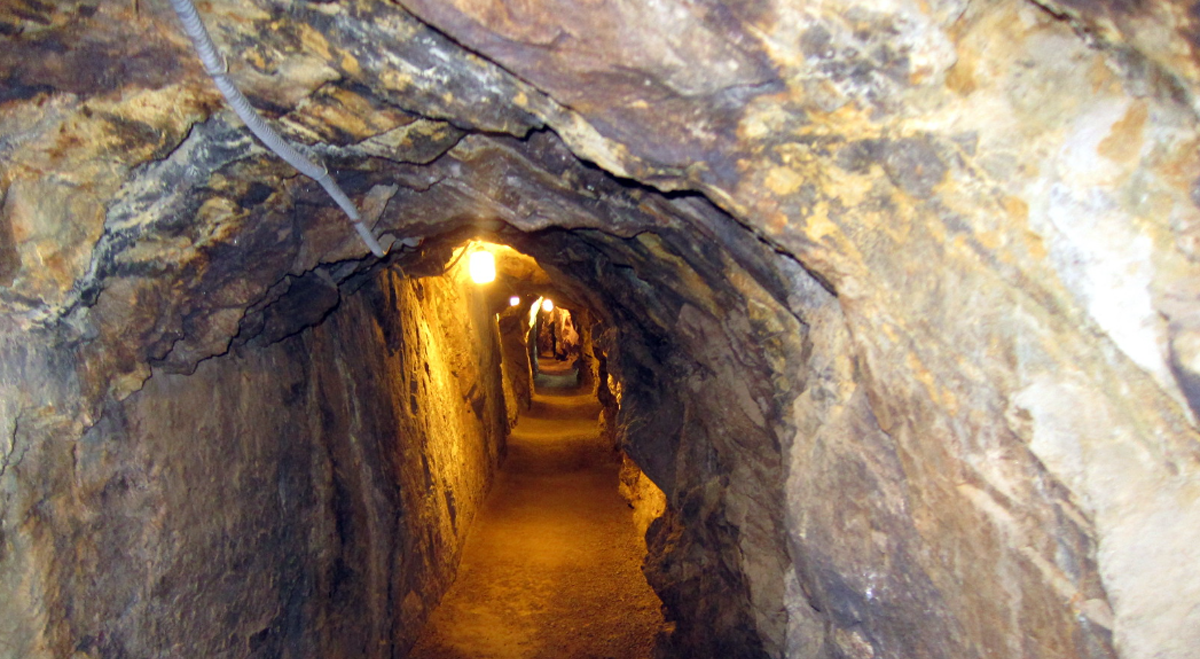
    Alongside the drilling campaign, Rockfire is accelerating several aspects of the Molaoi feasibility study. Current work includes geotechnical drilling to support the reopening of historic underground mine workings, while ecological and hydrological baseline studies are progressing to prepare for potential future mining operations.

    Drilling activity will pause during August as part of a contractor-wide shutdown. However, Rockfire expects its newly acquired drilling rig to arrive in Athens during late September or early October, allowing exploration to resume with minimal disruption and keeping the project broadly on track for its next development milestones.

    Although operational progress remains positive, the company’s financial outlook continues to be constrained by the absence of revenue, ongoing losses and negative free cash flow. A debt-free balance sheet provides some financial flexibility, while recent share price performance has shown modest short-term improvement despite remaining weaker over longer periods. Valuation also remains under pressure due to the lack of earnings and the absence of a dividend.

    About Rockfire Resources PLC

    Rockfire Resources is an AIM-listed exploration company focused on gold, base metals and critical minerals. Its flagship asset is the high-grade Molaoi zinc, lead, silver and germanium project in Greece, where a JORC Inferred Resource has already been established. The company also holds a portfolio of gold, copper and silver exploration projects in Queensland, Australia, including the Plateau and Marengo assets, which are being advanced through farm-in agreements with ASX-listed partners.

  • Ashmore Reports Higher Assets Under Management as Emerging Markets Gain Momentum (ASHM)

    Ashmore Reports Higher Assets Under Management as Emerging Markets Gain Momentum (ASHM)

    Ashmore Group plc (LSE:ASHM) increased its assets under management by 7% during the fourth quarter, reaching an estimated $54.0 billion as of 30 June 2026. The growth was supported by $2.0 billion in positive investment performance and $1.3 billion of net inflows, reflecting improving sentiment across emerging markets.

    The increase in assets was spread across several investment strategies, including local currency, equities, blended debt and corporate debt portfolios. External debt was the only area to record modest net outflows, primarily due to a limited number of institutional client redemptions.

    Ashmore noted that emerging market performance remained strong during the period, with fixed income indices delivering gains of between 2% and 5%, while large-cap equity markets advanced 24%. The company also said its actively managed strategies continued to outperform their respective benchmarks across both fixed income and equity products.

    Management believes the investment backdrop for emerging markets is becoming increasingly favourable as the risk of a renewed global inflation shock eases and macroeconomic conditions move towards a more balanced “Goldilocks” environment. The firm added that increasing geopolitical complexity and shifting global investment trends are expected to strengthen demand for specialist active managers focused on emerging markets.

    Ashmore’s outlook is supported by solid profitability, a highly conservative balance sheet with minimal leverage, positive share price momentum and an attractive valuation, including a dividend yield of 6.81% and a price-to-earnings ratio of 14.343. However, the company continues to face challenges from declining revenue, softer operating cash conversion and ongoing pressure on management fees, while the timing of performance fees remains a potential source of earnings volatility.

    About Ashmore Group plc

    Ashmore Group plc is a specialist investment manager focused exclusively on emerging markets. The company provides institutional and other investors with a range of actively managed strategies spanning fixed income, equities and alternative investments, including external debt, local currency, corporate debt and blended debt portfolios.

  • Rank Group Raises Profit Guidance as Digital Growth and Gaming Machines Boost Performance (RNK)

    Rank Group Raises Profit Guidance as Digital Growth and Gaming Machines Boost Performance (RNK)

    Rank Group (LSE:RNK) reported a 6% increase in like-for-like net gaming revenue to approximately £834.1 million for the year ended 30 June 2026 and has upgraded its profit outlook, with underlying operating profit now expected to reach at least £76 million, ahead of market consensus.

    The improved performance was driven by a strong fourth quarter at Grosvenor casinos, where gaming machine revenue climbed 12%. Digital operations also delivered robust growth, with net gaming revenue rising 12%, supported by efficiency savings that enabled the company to maintain performance marketing investment despite the higher Remote Gaming Duty.

    Performance at Mecca and Enracha venues was in line with expectations, while the group continued to exercise tight control over operating costs. Rank also announced a £5 million provision relating to a proposed regulatory settlement with the Gambling Commission over historic compliance issues at Grosvenor Casinos. The company said the required remedial measures have now been substantially completed and reiterated its medium-term objective of achieving operating profit of at least £100 million.

    Rank is scheduled to publish its preliminary results for the 2025/26 financial year on 13 August 2026, when it will provide further detail on how digital expansion and gaming machine optimisation contributed to profitability. The latest trading update highlights management’s strategy of using operational efficiencies and a stronger revenue mix to offset higher taxation and regulatory costs while supporting long-term shareholder returns.

    While the company’s outlook is supported by improved financial performance and an attractive valuation, investor sentiment remains constrained by weak technical indicators, including a sustained downtrend and negative price momentum. Near-term risks also include the financial impact of the higher Remote Gaming Duty, together with cash flow and lease-related pressures.

    About Rank Group plc

    Rank Group plc is a UK-listed gaming and betting operator whose portfolio includes Grosvenor casinos, Mecca bingo clubs, Enracha venues in Spain and a range of online gaming platforms. The company operates across both land-based and digital gaming markets, with a strategic focus on expanding its digital business and enhancing the performance of its gaming machine estate.

  • Getech Reports Revenue Growth and Returns to Profit as Exploration Activity Strengthens (GTC)

    Getech Reports Revenue Growth and Returns to Profit as Exploration Activity Strengthens (GTC)

    Getech (LSE:GTC) delivered a stronger first half for fiscal 2026 as its renewed emphasis on core subsurface markets continued to gain traction. The company reported a 15% increase in revenue to £2.4 million and returned to an adjusted EBITDA profit of £0.2 million following earlier cost-saving measures. Its order book expanded to £4 million, cash balances improved to £0.6 million, and annual recurring revenue remained stable at £2.8 million, supported by high customer subscription retention and a significantly larger sales pipeline.

    Management said business momentum continues to build, driven by growing global concerns over energy security and increased exploration activity across the oil and gas, mining and natural hydrogen industries. With £1.6 million of contracted work scheduled to be recognised as revenue during the second half of the year, alongside continued emphasis on recurring revenue growth and disciplined cost management, the company remains confident of meeting full-year market expectations.

    Despite the improved trading performance, the outlook is still tempered by ongoing losses and negative operating and free cash flow, although both have shown meaningful improvement compared with 2025. Investor sentiment is also affected by weak technical indicators, with the shares continuing to trade below key moving averages. In addition, the company’s valuation remains under pressure due to its negative price-to-earnings ratio, reflecting the absence of consistent long-term profitability.

    About Getech Group plc

    Getech Group plc is an AIM-listed geoscience and technology company focused on identifying subsurface resources that support global energy security and the energy transition. By combining geoscience expertise with AI-powered analytics and geospatial data, the business helps governments, regulators and corporate clients locate energy and mineral resources while improving exploration efficiency across the oil and gas, mining and emerging natural hydrogen sectors.