Category: Market News

  • Market Open: Jet2 Share Buyback, Vistry Strategic Reset

    Market Open: Jet2 Share Buyback, Vistry Strategic Reset

    FTSE 100 edges higher while European markets fall. Jet2 reports record passenger growth, Vistry resets strategy and Brent crude rises.

    Market Overview

    The FTSE 100 opened marginally higher, while broader European markets weakened as the Euronext 100 slipped and Germany’s DAX fell more than one per cent. Overnight, US markets also closed lower, with the Nasdaq and S&P 500 both retreating as investors reacted to escalating tensions in the Gulf, monitored Federal Reserve policy expectations and assessed the impact of heightened geopolitical uncertainty on global risk sentiment.

    Commodity markets reflected the increase in geopolitical risk, with Brent crude rising sharply while copper, gold and natural gas also moved higher. Bitcoin edged lower against sterling. Sterling strengthened slightly against the US dollar but weakened modestly against the Swiss franc, euro, Japanese yen and Australian dollar as investors sought traditional safe-haven assets amid concerns over energy supplies and shipping through the Strait of Hormuz.


    Market Numbers

    FTSE 100: Up (0.001%), 10,666.09

    Euronext 100: Down (-0.03%), 1,912.02

    DAX: Down (-1.14%), 25,174.68

    NASDAQ: Down, 25,818.69

    S&P 500: Down, 7,503.85


    In the Headlines

    Passenger growth – Jet2 (LSE:JET2)

    Jet2 reported record passenger growth, launched a £250 million share buyback programme and expanded its presence at London Gatwick. The update highlights continued demand for leisure travel while reinforcing confidence in shareholder returns and long-term expansion plans.

    Strategic reset – Vistry (LSE:VTY)

    Vistry said first-half earnings will be affected as it prioritises cash generation through discounted sales, lower-risk developments and tighter capital allocation. The measures are intended to strengthen the balance sheet and support longer-term profitability despite near-term earnings pressure.


    Currencies (vs GBP)

    USD: Up (0.02%), $1.3347

    CHF: Down (-0.01%), Fr.1.0798

    EUR: Down (-0.01%), €1.1706

    JPY: Down (-0.02%), ¥216.7045

    AUD: Down (-0.01%), $1.9281

    Bitcoin (BTC/GBP): Down, £47,017.91


    Commodities

    Copper: Up

    Gold: Up

    Brent Crude: Up

    Natural Gas: Up
  • Tungsten West Set to Begin Phased Commissioning at Hemerdon Mine This Month (TUN)

    Tungsten West Set to Begin Phased Commissioning at Hemerdon Mine This Month (TUN)

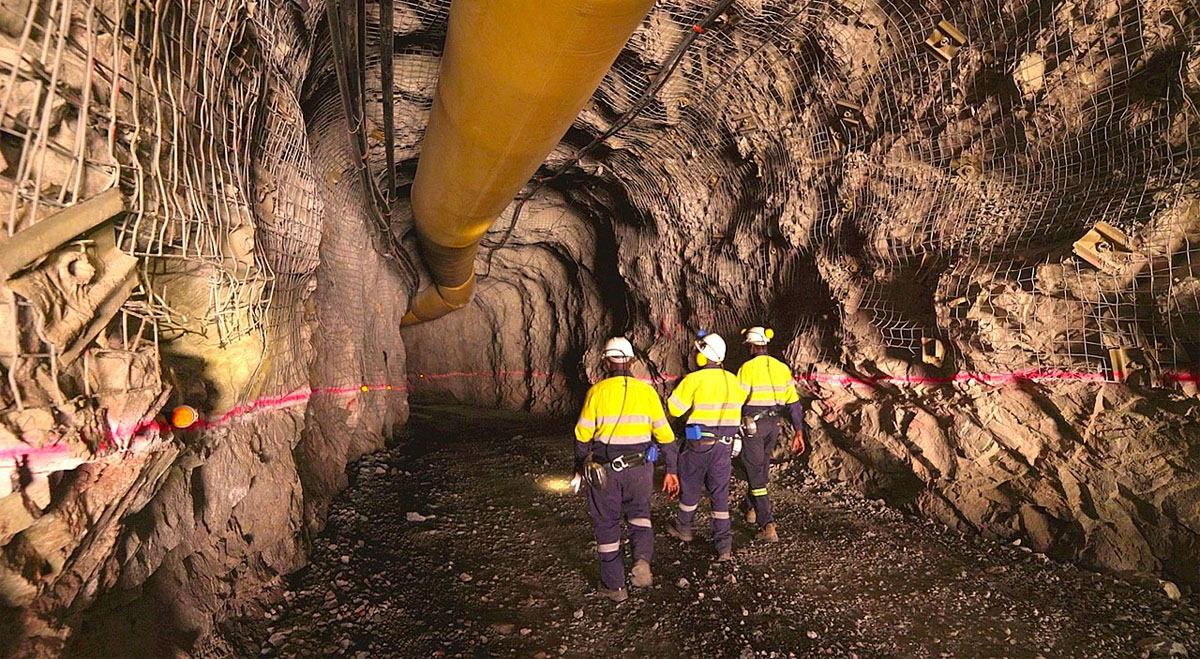
    Tungsten West (LSE:TUN) has confirmed that phased commissioning of the Hemerdon tungsten and tin mine will begin later this month, keeping the project on schedule in line with previously announced plans. Ahead of the production restart, the company has launched an expanded engagement programme with local communities and regulators to provide updates on the timing, scope and phased approach to the commissioning process.

    The recommissioning programme will start with the fines gravity circuit and downstream processing facilities during the third quarter of 2026, followed by the coarse gravity circuit in the fourth quarter. Full project commissioning remains targeted for the first quarter of 2027, with management expecting the redevelopment to be completed within budget. As preparations continue, Tungsten West has recruited more than 100 employees and expects its workforce to grow to around 350 people by early 2027, highlighting the project’s increasing operational readiness and contribution to the local economy.

    Despite continued operational progress, Tungsten West’s investment outlook remains constrained by ongoing losses, negative cash flow, increased debt and negative shareholders’ equity reported for the 2025 financial year. While recent share price momentum has been encouraging, the company’s valuation continues to reflect its loss-making position, with a negative price-to-earnings ratio and no dividend support.

    More about Tungsten West Plc

    Tungsten West Plc is a UK mining company focused on restarting production at the Hemerdon tungsten and tin mine in Devon. The project is intended to re-establish one of the world’s largest tungsten resources as a significant domestic supplier of strategically important metals. Alongside the mine’s redevelopment, the company is committed to working closely with local communities and building a predominantly local workforce to support long-term operations.

  • Shareholders Seek Board Changes at Union Jack Oil Following Requisition Notice (UJO)

    Shareholders Seek Board Changes at Union Jack Oil Following Requisition Notice (UJO)

    Union Jack Oil (LSE:UJO) has received a shareholder requisition from investors representing approximately 14.09% of the company’s voting rights, requesting that a general meeting be convened to consider significant changes to the board. The notice, dated 7 July 2026, proposes the removal of directors David Bramhill, Joseph O’Farrell and Zac Phillips, alongside the appointment of Craig Howie and John Americanos. The company confirmed that the board will arrange the meeting in accordance with the required statutory timetable and its articles of association.

    If approved, the proposed board changes could mark a significant shift in the company’s leadership and potentially influence its strategic direction. Investors will be closely monitoring the outcome of the meeting, as changes to the board of a publicly listed oil and gas company may affect corporate priorities, governance, market confidence and future business strategy.

    Union Jack Oil’s investment outlook continues to be weighed down by weak financial performance, following a substantial loss in 2025, negative operating cash flow and persistently negative free cash flow. Technical indicators also remain weak, with the shares trading below key short-term moving averages and momentum measures pointing to continued pressure. However, the company maintains a debt-free balance sheet, providing some financial resilience despite a negative price-to-earnings ratio and the absence of dividend support.

    More about Union Jack Oil

    Union Jack Oil plc is a UK-based oil and gas exploration and production company listed on the AIM market and the OTCQB in the United States. The company focuses on developing and producing hydrocarbon assets while pursuing exploration opportunities across the UK. As a publicly traded business, its strategic direction and corporate governance are ultimately determined by shareholder voting, with investors playing a direct role in key board and governance decisions.

  • ZIGUP Increases Cash Generation as UK and Ireland Simplification Strategy Progresses (ZIG)

    ZIGUP Increases Cash Generation as UK and Ireland Simplification Strategy Progresses (ZIG)

    ZIGUP plc (LSE:ZIG) delivered a solid performance for the year ended 30 April 2026, with underlying revenue increasing 5.2% as strong vehicle hire activity in Spain and the UK & Ireland supported growth. Underlying EBITDA rose 8.2%, while the group’s fleet expanded by 5.9% to more than 139,000 vehicles. Rental margins remained resilient, and steady-state cash generation climbed to £95.7m, reflecting stronger cash generation despite an increase in net debt linked to investment in the vehicle fleet.

    The company continued to execute its UK and Ireland simplification programme, including the launch of the Northgate Mobility brand as part of a broader operational transformation. Management is targeting annualised cost savings of £20m by the 2028 financial year while maintaining leverage within a range of one to two times. ZIGUP also highlighted healthy demand across its rental operations, a strong pipeline within its claims and services businesses and expects full-year profit growth to remain in line with market expectations. The company believes continued efficiency improvements and cost savings will support a target of generating more than £200m in steady-state cash flow by FY2028.

    Although recent operational progress and positive market momentum provide reasons for optimism, investors continue to balance these strengths against weaker underlying financial metrics, including pressure on revenue trends and cash flow. Nevertheless, the shares continue to benefit from an attractive valuation, supported by a relatively low price-to-earnings ratio and a strong dividend yield.

    More about ZIGUP plc

    ZIGUP plc is a London-listed provider of integrated mobility solutions, delivering services across the entire vehicle lifecycle. The company supports businesses, fleet operators, insurers, vehicle manufacturers and other customers through vehicle rental, fleet management, accident management, repairs, servicing and maintenance. It also helps organisations transition to lower-carbon transport through electric vehicle solutions and consultancy services.

    Operating primarily in the UK, Ireland and Spain, ZIGUP combines a large vehicle fleet with digital technology and specialist repair capabilities to provide integrated mobility services. The company focuses on long-term relationships with blue-chip customers and was recognised with the King’s Award for Enterprise 2025 for its contribution to opportunity and social mobility. Its long-term strategy centres on sustainable growth, operational efficiency and disciplined capital allocation across its diversified mobility platform.

  • IG Group Proposes Jersey Holding Company as International Growth Accelerates (IGG)

    IG Group Proposes Jersey Holding Company as International Growth Accelerates (IGG)

    IG Group Holdings (LSE:IGG) has unveiled plans to establish a new Jersey-incorporated holding company as part of a wider strategy to better align its corporate structure with its increasingly international business. The proposal will not affect the company’s London Stock Exchange listing, UK tax residency or London-based operations, while its existing Financial Conduct Authority-regulated group will continue to operate without change.

    Alongside the proposed restructuring, IG Group intends to simplify its organisational framework by combining its principal regional operations into a single consumer division, while continuing to manage its North American and institutional businesses independently. Management expects first-half 2026 revenue to increase by around 18% and has reaffirmed its upgraded full-year outlook, reflecting confidence in delivering sustained double-digit organic growth and EBITDA margins in the mid-40% range. The strategic review will also consider additional initiatives aimed at enhancing long-term shareholder value.

    IG Group’s outlook remains supported by strong profitability, healthy returns and generally moderate leverage, although fluctuations in cash flow continue to present a challenge. Positive technical momentum has supported the share price, but overbought indicators suggest there may be increased scope for short-term volatility. Overall, the company’s valuation remains reasonable, complemented by an attractive dividend yield.

    More about IG Group Holdings

    IG Group Holdings is a FTSE 100 financial technology company providing online trading, investing and financial services to more than 1.3 million customers worldwide. Through brands including IG, tastytrade, Freetrade, Independent Reserve and IG Prime, the group offers leveraged trading, share dealing, investment products and cryptocurrency trading via its proprietary technology platforms.

    Around two-thirds of the company’s revenue is generated outside the UK, reflecting its increasingly global customer base. Despite the proposed establishment of a Jersey holding company, IG Group will retain its primary listing in London, remain UK tax resident and continue to operate its London headquarters as a key centre for its global consumer, North American and institutional businesses.

  • System1 Delivers Record Second-Half Revenue as Investment Strategy Supports Future Growth (SYS1)

    System1 Delivers Record Second-Half Revenue as Investment Strategy Supports Future Growth (SYS1)

    System1 (LSE:SYS1) reported full-year revenue of £37m for the year ended 31 March 2026, broadly unchanged from the previous year as 3% growth in platform revenue offset a significant decline in bespoke consultancy work caused by tariff-related pressure on advertising budgets. Profit before tax fell to £2.1m from £5.3m, reflecting planned investment and weaker trading conditions during the first half. Despite lower earnings, the company retained a debt-free balance sheet and proposed an increase in its ordinary dividend.

    Trading strengthened considerably during the second half, with System1 delivering record revenue for the period and profit before tax increasing sixfold compared with the first half. The improved performance has given management confidence as the company enters the 2027 financial year. Strategic progress included accelerating platform growth in the United States, expanding AI-powered product capabilities and securing additional major global advertising clients, supporting expectations of improved margins and sustainable long-term growth. The company also confirmed it will move to providing market updates twice a year.

    System1 continues to benefit from high operating margins, a strong return on equity and a robust balance sheet with no debt, while recent share price performance has remained positive. However, the shares trade on a relatively high valuation, with a price-to-earnings ratio of 67.27, and technical indicators point to overbought conditions, suggesting the potential for increased short-term volatility.

    More about System1

    System1 Group plc is a London-listed marketing technology company that helps businesses assess and improve the effectiveness of advertising, product innovation and brand strategy. Using a proprietary database of emotional response benchmarks across 81 global markets, the company provides predictive marketing insights through a combination of data-driven testing platforms and consultancy services. Its client base includes more than 600 organisations, among them many of the world’s largest advertisers.

  • Galliford Try Secures Position on £1.5bn YORbuild Framework for Major Public Projects (GFRD)

    Galliford Try Secures Position on £1.5bn YORbuild Framework for Major Public Projects (GFRD)

    Galliford Try (LSE:GFRD) has been appointed to the £1.5bn YORbuild Major Works 2 framework, securing a four-year position to deliver major public sector construction projects valued above £10m and £30m. The appointment expands the company’s opportunities across Yorkshire, the Humber, the North East and parts of the Midlands, strengthening its regional presence and providing access to a substantial pipeline of public sector work.

    By securing places on key framework lots, Galliford Try has strengthened its ability to compete for large-scale construction projects commissioned by public sector organisations and third-sector bodies. The framework is expected to support a consistent flow of work for the group’s building division, reinforce relationships with regional clients and enhance its position within the UK’s public construction market.

    Galliford Try continues to benefit from solid financial performance, strong cash generation and supportive share price momentum, while its valuation remains relatively attractive with a price-to-earnings ratio of 12.44 and a dividend yield of 3.32%. However, investors continue to monitor slower revenue growth and relatively modest operating margins, which remain the principal challenges facing the business.

    More about Galliford Try

    Galliford Try Holdings plc is a leading UK construction and infrastructure company listed on the London Stock Exchange and a constituent of the FTSE 250 index. Operating through the Galliford Try and Morrison Construction brands, the group delivers building, engineering and infrastructure projects for clients across the public, private and regulated sectors throughout the UK.

  • Georgina Energy Completes Key Hussar Site Works Ahead of Planned September Drilling (GEX)

    Georgina Energy Completes Key Hussar Site Works Ahead of Planned September Drilling (GEX)

    Georgina Energy (LSE:GEX) has made further progress at its wholly owned Hussar EP513 project in Western Australia, completing major pre-drilling site preparation ahead of its planned third-quarter drilling campaign. Work has included clearing and grading drill pad locations, camp facilities and seismic access tracks, while upgrades to the on-site airstrip and improvements to the Gunbarrel Highway have enhanced access for heavy transport vehicles required during drilling operations.

    The company remains on schedule to spud the Hussar well in September 2026. The contracted Ensign 970 drilling rig is expected to mobilise once final ground levelling and compaction work has been completed in accordance with the approved Well Management Plan. The Hussar prospect, regarded as one of Australia’s largest onshore subsalt exploration targets for helium, hydrogen and hydrocarbons, will be drilled to a planned depth of 3,200 metres to evaluate formations with independently assessed multi-billion-dollar in-situ resource potential.

    Although operational milestones continue to be achieved, Georgina Energy’s investment outlook remains constrained by its early-stage financial profile, including the absence of revenue, ongoing losses, negative cash flow and negative shareholders’ equity alongside rising debt levels. Positive technical momentum provides some support, but valuation continues to be limited by the company’s lack of profitability and dividend payments.

    More about Georgina Energy plc

    Georgina Energy plc is a London-listed helium and hydrogen exploration company operating through its Australian subsidiary, Westmarket Oil & Gas. The group owns a 100% interest in the Hussar project in Western Australia and the Mt Winter prospect in the Northern Territory, giving it exposure to growing global demand for helium, hydrogen and associated natural gas resources.

    The company’s strategy is focused on advancing large onshore subsalt exploration projects, including Hussar together with the Mt Kitty and Dukas-related prospects. Independent resource assessments have identified substantial prospective resources across its portfolio, supporting Georgina Energy’s objective of developing strategically important gas assets in Australia.

  • Norman Broadbent Reports Strong Second-Quarter Recovery as Investment Strategy Supports Growth Plans (NBB)

    Norman Broadbent Reports Strong Second-Quarter Recovery as Investment Strategy Supports Growth Plans (NBB)

    Norman Broadbent (LSE:NBB) delivered a stronger trading performance during the second quarter of 2026, with net fee income increasing to £3.1m from £2.2m in the first quarter despite ongoing geopolitical uncertainty and a cautious hiring environment. Net fee income for the first half totalled £5.3m, compared with the record £6.0m achieved in the same period last year. Management also highlighted a significant improvement in retainer income, which it views as a positive indicator for future executive search placements.

    The company continues to pursue its long-term growth strategy through targeted investment in fee-earning consultants and selective acquisitions. Following the acquisition of Society Limited in February, Norman Broadbent added three new fee earners during the first half and has secured a further four appointments for the second half, while recruitment efforts remain ongoing. Combined with the expansion of its international operations and broader leadership advisory services, the board expects to achieve record net fee income during the second half of 2026.

    Norman Broadbent’s outlook is supported by improving profitability, stronger cash generation and significantly lower leverage, while its relatively modest valuation provides additional appeal. However, weaker technical indicators, including the shares trading below key moving averages and subdued momentum signals, suggest investor sentiment remains cautious in the near term.

    More about Norman Broadbent

    Norman Broadbent plc is a UK-based professional services firm specialising in executive search, senior interim management and leadership advisory services for organisations across the UK and international markets. Established in 1979 as the UK’s first executive search firm, the company has more than four decades of experience helping businesses recruit senior leaders across sectors including consumer, financial services, industrials, life sciences, investor relations and technology, media and telecommunications (TMT).

  • Ofgem Closes Smart DCC Procurement Investigation as Capita Subsidiary Strengthens Controls (CPI)

    Ofgem Closes Smart DCC Procurement Investigation as Capita Subsidiary Strengthens Controls (CPI)

    Ofgem has concluded its investigation into procurement practices at Smart DCC, the wholly owned but non-consolidated subsidiary of Capita (LSE:CPI) responsible for operating the UK’s national smart meter communications infrastructure. The regulator examined five contracts awarded between 2021 and 2024, including one contract that was not competitively tendered and another awarded to Capita.

    The investigation found no evidence of consumer harm. However, Smart DCC has agreed to make a £200,000 payment to Ofgem’s Voluntary Redress Fund and introduce enhanced procurement procedures, particularly for the award of Fundamental Service Capability contracts involving related parties. Capita noted that Smart DCC has successfully developed and operated the nationwide smart meter communications network since the licence began and confirmed that responsibility for the service is expected to transfer to a not-for-profit organisation over the coming year.

    Capita’s broader investment outlook continues to be influenced by weak underlying financial performance, including losses in 2025, pressure on profit margins, inconsistent free cash flow and relatively high leverage. At the same time, the shares have benefited from stronger technical momentum and are trading above key moving averages, although overbought conditions may increase the risk of near-term volatility. Valuation remains constrained by negative earnings and the absence of a meaningful dividend yield.

    More about Capita plc

    Capita plc is a UK-based outsourcing and professional services company that provides technology-enabled business process services to organisations across the public and private sectors. Operating in eight countries, the group helps customers improve operational efficiency, manage complex services and enhance user experiences through a combination of specialist expertise and digital technology. Its services support a wide range of essential functions relied upon by businesses, governments and millions of consumers.