Category: Market News

  • Alien Metals JV Confirms High-Grade Silver Intercepts at Elizabeth Hill Project (UFO)

    Alien Metals JV Confirms High-Grade Silver Intercepts at Elizabeth Hill Project (UFO)

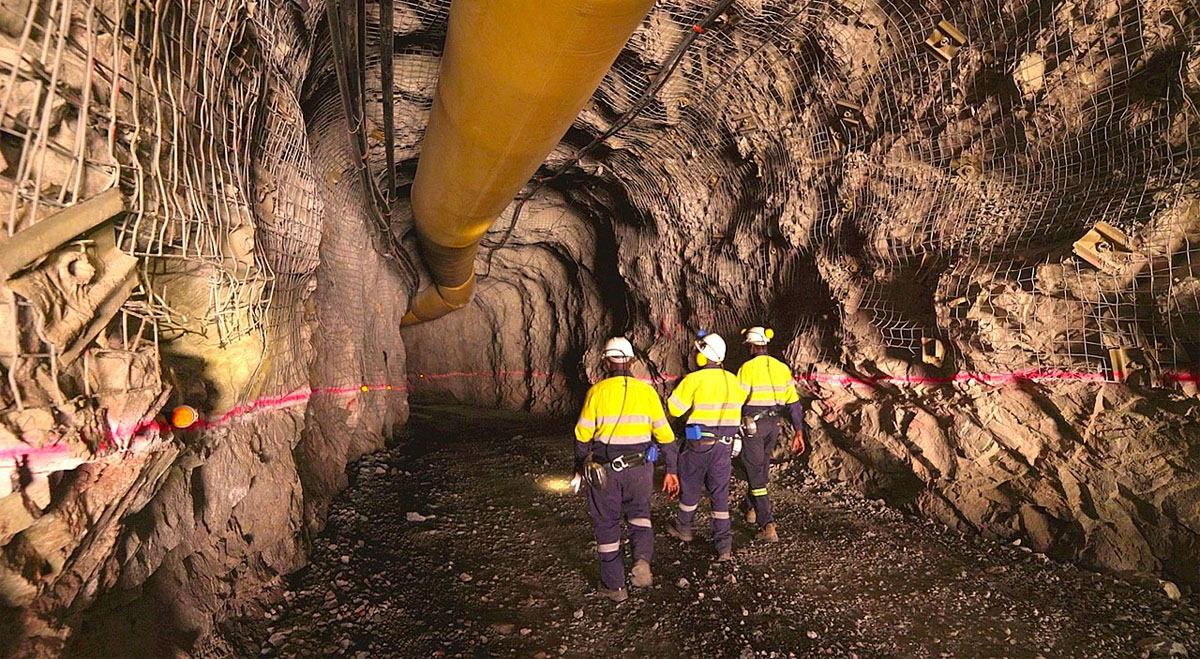
    Alien Metals (LSE:UFO) has announced that its joint venture partner, West Coast Silver, has delivered encouraging high-grade silver and base metal drilling results from the Elizabeth Hill Silver Project near Karratha in Western Australia’s Pilbara region. The latest diamond and reverse circulation drilling has identified a new zone of silver mineralisation beneath the historic mine workings, with several near-surface intersections extending beyond the boundaries of the current mineral resource estimate. Additional assay results are expected over the coming months.

    The latest drilling has also identified high-grade silver mineralisation alongside nickel, copper and palladium sulphides, further enhancing the project’s exploration potential. Alien Metals owns a 30% interest in the Elizabeth Hill project as well as an equity stake in West Coast Silver, meaning continued exploration success could strengthen the company’s exposure to both precious and base metals alongside its core iron ore portfolio. The results also improve the project’s long-term development potential and reinforce Alien’s strategic position within the Pilbara mining region.

    Despite the positive exploration update, Alien Metals continues to face financial challenges, with no current revenue generation, ongoing losses and consistently negative free cash flow weighing on its overall outlook. Technical indicators also continue to reflect generally weak market momentum. Valuation support remains limited, as the company reports negative earnings and does not currently offer a dividend.

    More about Alien Metals Ltd

    Alien Metals Ltd is an AIM-listed mining exploration and development company focused on advancing a diversified portfolio of mineral assets through exploration, technical studies, project development and strategic partnerships. Its flagship asset is the 90%-owned Hancock Iron Ore Project in Western Australia’s Pilbara region. The company also holds interests in a range of iron ore, silver and base metal projects, including a 30% stake in the Elizabeth Hill Silver Project and equity investments in several joint venture partners.
  • Spire Healthcare Extends Deadline for Toscafund’s Potential 250p-Per-Share Takeover Offer (SPI)

    Spire Healthcare Extends Deadline for Toscafund’s Potential 250p-Per-Share Takeover Offer (SPI)

    Spire Healthcare (LSE:SPI) has confirmed that funds managed by Toscafund Asset Management, the company’s second-largest shareholder, remain in discussions regarding a possible cash offer of 250 pence per share for the group’s entire issued and to be issued share capital. The proposal also includes an option allowing existing shareholders to receive unlisted rollover equity as an alternative. Any formal offer remains subject to customary conditions, including the completion of due diligence and the agreement of final transaction documentation.

    At Toscafund’s request, Spire’s board has agreed to a further extension of the Takeover Code “put up or shut up” deadline, moving it from 9 July to 6 August 2026. The company said Toscafund’s due diligence process and financing arrangements are now well advanced. However, there remains no certainty that a firm offer will be made. Toscafund also retains the right to amend the terms or value of any future proposal under certain circumstances. The latest extension signals that takeover discussions remain active and could have important implications for both shareholders and the wider UK private healthcare sector.

    Spire Healthcare’s investment outlook continues to benefit from stable operational performance and dependable cash generation. However, relatively high leverage and narrow net profit margins continue to weigh on the company’s financial profile. Technical indicators remain supportive following a sustained share price rally, although a very high Relative Strength Index (RSI) suggests the shares may be approaching overbought territory. Valuation appears broadly balanced, supported by a modest dividend yield.

    More about Spire Healthcare

    Spire Healthcare Group plc is one of the UK’s largest independent healthcare providers, operating 38 hospitals and more than 60 clinics across England, Wales and Scotland. Listed on the FTSE 250, the company works with more than 8,800 consultants and provides private healthcare, NHS-funded services and employer-sponsored medical care. It is also the UK’s largest private provider of knee and hip replacement procedures by volume.

    In addition to its hospital network, Spire operates private GP practices and workplace health services for more than 1,400 employers. The group is also the largest independent provider of NHS talking therapies in England. Almost all of its clinical facilities have been rated Good or Outstanding by healthcare regulators, serving self-pay patients, NHS commissioners, employers and private medical insurers through a nationwide network of nearly 100 locations.

  • Computacenter Raises Profit Expectations After Strong Second Quarter Performance (CCC)

    Computacenter Raises Profit Expectations After Strong Second Quarter Performance (CCC)

    Computacenter (LSE:CCC) has upgraded its profit outlook following a stronger-than-expected second quarter, building on an impressive start to 2026. The technology services group now expects adjusted profit before tax for the first half of the year to be approximately twice the level reported during the weaker comparative period in 2025, supported by robust demand for technology sourcing and professional services.

    Performance was particularly strong in North America, where business with hyperscale customers exceeded expectations, while the UK delivered an excellent contribution through technology sourcing activity, including projects linked to artificial intelligence. The company also reported a significantly higher committed product order backlog at the halfway stage of the year. Although the second half will face more demanding year-on-year comparisons, Computacenter said it still expects full-year 2026 results to be comfortably ahead of current market forecasts.

    Computacenter’s outlook continues to be underpinned by a strong balance sheet with relatively low leverage and healthy revenue growth. However, this is partly offset by weaker profitability and cash flow recorded during 2025. Technical indicators remain supportive following sustained share price momentum, although overbought signals suggest the potential for some near-term volatility. Valuation appears broadly balanced, with a price-to-earnings ratio of around 20 and a dividend yield of approximately 1.85%.

    More about Computacenter

    Computacenter is a leading independent provider of technology infrastructure, digital transformation and managed services for large corporate and public sector organisations. Listed on the London Stock Exchange and a constituent of the FTSE 100, the company employs more than 21,000 people globally and helps customers procure, deploy and manage technology solutions that support long-term digital transformation and operational efficiency.

  • Polar Capital Assets Under Management Rise 47% as Technology and AI Funds Drive Inflows (POLR)

    Polar Capital Assets Under Management Rise 47% as Technology and AI Funds Drive Inflows (POLR)

    Polar Capital Holdings plc (LSE:POLR) has reported a strong start to its new financial year after assets under management (AuM) climbed to £45.0 billion as of 30 June 2026, representing a 47% increase from £30.6 billion at the end of March. The growth was supported by £2.5 billion of net client inflows and a further £11.9 billion generated through favourable market movements and investment performance.

    Demand was led by the company’s Technology and Artificial Intelligence strategies, with additional inflows into Healthcare, Smart Energy, Global Absolute Return and Japan Value funds. These gains more than offset client-specific outflows from Emerging Markets Stars and Global Insurance strategies, highlighting continued investor appetite for Polar Capital’s specialist investment capabilities. The performance marks a positive beginning to the financial year and reinforces confidence in the company’s ability to deliver further growth through its active management approach.

    Polar Capital continues to position itself around high-conviction thematic investing, offering a broad range of open-ended funds, investment trusts and segregated mandates across sectors including Technology, Artificial Intelligence, Smart Energy and Healthcare. Management believes the current market environment, characterised by broader participation and greater stock-specific dispersion, provides favourable conditions for differentiated active investment strategies.

    The company’s outlook remains supported by strong financial fundamentals, including high profitability, robust cash generation and a conservatively positioned balance sheet. Technical indicators also remain favourable following a sustained share price uptrend, although some overbought signals point to potential short-term moderation. Valuation remains attractive, supported by a reasonable earnings multiple and a healthy dividend yield.

    More about Polar Capital Holdings

    Polar Capital Holdings plc is a specialist active asset manager offering high-conviction investment strategies through open-ended funds, investment trusts and segregated mandates. The firm focuses on specialist themes including Technology, Artificial Intelligence, Smart Energy, Healthcare and other niche sectors, aiming to generate long-term returns through active stock selection and differentiated portfolio management.

    The company offers a diversified investment platform with significant capacity across its strategies, enabling it to capture long-term client demand while delivering sustainable growth for investors and shareholders. Its product range is designed to provide exposure to structural growth themes alongside specialist regional and absolute return strategies.

  • Bango Delivers Strong H1 Growth as Recurring Revenue and EBITDA Increase (BGO)

    Bango Delivers Strong H1 Growth as Recurring Revenue and EBITDA Increase (BGO)

    Bango (LSE:BGO) reported a strong performance for the first half of 2026, supported by continued growth in recurring revenue from its subscription platform and improved cost discipline. Annual Recurring Revenue increased 31% to $20.4 million, while subscription revenue rose 13% to $12.3 million. Net Revenue Retention reached 119%, reflecting higher spending from existing customers and continued adoption of the company’s Digital Vending Machine® platform by global brands, financial institutions and telecommunications providers.

    Group revenue increased 3% to $25.9 million during the period, while Adjusted EBITDA rose 34% to at least $9.0 million. Cash EBITDA improved to $3.7 million, exceeding the company’s full-year result for the previous year, as Bango continued to phase out lower-margin legacy payment routes in favour of more profitable operations. Management said its payments business remains a strong source of cash generation, with net debt declining slightly to $8.7 million. The company also strengthened its corporate governance through the appointment of a new independent chair and audit committee leader, and said it remains on track to meet its full-year expectations while reinforcing its position in the subscription monetisation market.

    Despite the encouraging operational progress, Bango’s outlook continues to be affected by ongoing net losses, negative EBIT and higher leverage following 2025, although cash generation has improved. Technical indicators remain weak, with the shares trading below key moving averages and negative MACD signals pointing to softer momentum. Valuation is also constrained by the company’s negative price-to-earnings ratio, while the absence of a dividend provides little additional valuation support.

    More about Bango plc

    Bango plc is a UK-based technology company specialising in subscription bundling, digital payments and customer acquisition. Its flagship Digital Vending Machine® platform enables content providers, digital merchants and telecommunications companies to distribute and manage subscription services through a global network of partners. The company works with leading technology businesses, including Amazon, Google and Microsoft, to support growth in the global subscription economy.

  • Capita Warns Civil Service Pension Issues Will Weigh on 2026 Profit Despite Strong Contract Momentum (CPI)

    Capita Warns Civil Service Pension Issues Will Weigh on 2026 Profit Despite Strong Contract Momentum (CPI)

    Capita (LSE:CPI) has reported a solid operational performance during the first half of 2026, with adjusted revenue increasing by 1.6% as its Public Service and Pension Solutions businesses continued to expand. The company secured £1 billion of new contracts during the period, maintained strong key performance indicators and strengthened its financial flexibility by extending its revolving credit facility to £325 million. Capita also continued to simplify the business through the planned disposal of its private sector contact centre operations while expanding partnerships in artificial intelligence and cloud computing to support its strategy of becoming an AI-led outsourcing provider.

    Despite this progress, difficulties linked to the Civil Service Pension Scheme contract are expected to have a significant financial impact this year. Higher costs associated with clearing service backlogs and delivering remediation measures are now forecast to reduce adjusted operating profit by between £25 million and £40 million in 2026, while free cash flow is expected to be lower by £35 million to £50 million. Capita said it is working closely with the Cabinet Office to improve service levels, although the additional work is also creating disruption across parts of its wider pensions business. As a result, the company now expects group free cash flow to return to positive territory in 2027, excluding the effects of planned business disposals.

    Capita’s outlook continues to be constrained by weak underlying financial metrics, including losses reported in 2025, pressure on profit margins, inconsistent free cash flow generation and relatively high leverage alongside a limited equity base. While the shares have benefited from positive technical momentum and continue to trade above key moving averages, overbought indicators suggest some short-term risk. Valuation also remains challenged due to the absence of positive earnings and no stated dividend yield.

    More about Capita plc

    Capita plc is a UK-based provider of business process outsourcing and professional services, working predominantly with public sector organisations and pension schemes. The company delivers technology-enabled customer services, administrative support, pension administration and consulting services, while increasingly investing in artificial intelligence capabilities through partnerships with leading cloud and data platform providers.

  • LondonMetric Strengthens Portfolio Through Strategic Acquisitions and Disposals as Rental Income Grows (LMP)

    LondonMetric Strengthens Portfolio Through Strategic Acquisitions and Disposals as Rental Income Grows (LMP)

    LondonMetric Property (LSE:LMP) has delivered a positive trading update ahead of its annual general meeting, reporting continued strength across its £7.6 billion triple net lease portfolio. The company said occupancy has improved to 98.3%, while the average unexpired lease term remains a robust 17 years, underlining resilient tenant demand across its logistics and convenience-focused assets.

    Since 1 April 2026, LondonMetric has completed investment activity worth £139 million, comprising £96.7 million of property disposals and £42.5 million of acquisitions, with additional transactions currently in progress. Most of the assets sold originated from recent mergers and acquisitions and were disposed of broadly in line with their book values. Meanwhile, new purchases have focused on convenience food stores and drive-thru properties, further enhancing the overall quality of the portfolio.

    Active asset management also continued to support earnings, generating an additional £6.7 million of contracted annual rental income through 72 separate initiatives, including rent reviews, lease renewals and new lettings. Rent reviews across the logistics portfolio produced particularly strong uplifts, while vacancy has fallen to just 1.7%. Additional lettings currently progressing through legal completion are expected to provide a further boost to rental income.

    Management said the ongoing disposal of non-core properties and reinvestment into high-quality convenience retail assets occupied by financially strong tenants is improving both the quality and resilience of the REIT’s income stream. The company also highlighted a growing pipeline of investment opportunities, particularly in development funding and assets being brought to market by pension funds, supporting its long-term strategy of investing in secure, income-producing real estate.

    Alongside its consortium partners, LondonMetric continues to undertake due diligence and prepare documentation for a possible acquisition of Picton Property Income Limited. If completed, the transaction would expand the company’s presence in the UK income-focused property market, increase portfolio diversification and strengthen its position within the triple net lease sector.

    LondonMetric’s outlook remains supported by an attractive valuation, including a relatively low price-to-earnings ratio and a strong dividend yield, together with resilient rental income and dividend growth. However, higher leverage and weaker free cash flow growth over the latest financial year continue to represent key risks, while technical indicators remain broadly neutral to slightly negative.

    More about LondonMetric Property

    LondonMetric Property Plc is a UK-listed real estate investment trust specialising in triple net lease assets across logistics, convenience retail, healthcare, entertainment and leisure. The company manages an approximately £8 billion property portfolio designed to deliver stable, recurring and growing rental income by focusing on structurally supported sectors, long-duration leases and high-quality tenants.

  • ITM Power Wins £46.5m Government Grant to Expand Next-Generation Electrolyser Manufacturing (ITM)

    ITM Power Wins £46.5m Government Grant to Expand Next-Generation Electrolyser Manufacturing (ITM)

    ITM Power (LSE:ITM) has officially been awarded a £46.5 million grant from the Department for Energy Security and Net Zero, alongside a £40 million equity investment from Great British Energy, to accelerate production of its next-generation Chronos electrolyser stack. Designed to improve energy efficiency while reducing production costs, the Chronos platform is expected to strengthen ITM Power’s position in the growing green hydrogen sector and expand its commercial opportunities.

    The funding will finance the construction of a dedicated Chronos manufacturing line at the company’s Sheffield site, making use of the existing Trident production platform to minimise implementation risk. Once operational, the facility is expected to deliver up to 1 GW of annual manufacturing capacity through advanced automation, specialised equipment and cleanroom production processes, supporting wider deployment of green hydrogen technologies across industry.

    To ensure a smooth production ramp-up, ITM Power will also manufacture modular testing systems and validation equipment in-house. Management believes the investment represents an important milestone in the company’s strategy to achieve sustainable, profitable growth, while strengthening its position as a key supplier to UK hydrogen projects. The company also sees the development as an opportunity to help reshape Sheffield’s industrial heritage by establishing the city as a major centre for hydrogen technology manufacturing.

    Although ITM Power continues to report operating losses and negative operating and free cash flow, its balance sheet remains supported by relatively low leverage. Market momentum has improved, with the shares performing strongly against key moving averages, although technical indicators suggest near-term overbought conditions. Recent management commentary highlighted improving order quality and encouraging growth prospects, but uncertainties remain around the timing of profitability, cash outflows and valuation given the absence of earnings and a dividend.

    More about ITM Power

    ITM Power is a UK-based developer and manufacturer of industrial-scale electrolysers used to produce green hydrogen through proprietary proton exchange membrane (PEM) technology. The company combines vertically integrated manufacturing with standardised hydrogen plant designs to supply industrial and energy customers, while also offering hydrogen production through its Hydropulse build-own-operate model. ITM Power is listed on London’s AIM market and holds the Green Economy Mark.

  • Severn Trent Accelerates FY27 Capital Spending While Strengthening Funding Position (SVT)

    Severn Trent Accelerates FY27 Capital Spending While Strengthening Funding Position (SVT)

    Severn Trent (LSE:SVT) has reported a positive start to the 2027 financial year, with trading progressing in line with internal expectations and the company remaining confident of delivering at least £50 million in performance incentives. During the first quarter, Severn Trent invested around £440 million in its infrastructure programme and continues to target annual capital expenditure of between £2.2 billion and £2.5 billion. To support this increased investment, the group has expanded its committed bank facilities to £1.65 billion, reinforcing liquidity and maintaining strong access to debt markets.

    The larger financing facilities, arranged across both Severn Trent Water and Severn Trent Plc, strengthen the group’s funding position as it undertakes a period of elevated infrastructure investment and meets regulatory commitments. The latest trading update highlights continued progress on capital projects and operational delivery linked to regulatory incentives. Investors will now look ahead to the company’s FY27 interim results in November for further insight into cash generation, balance sheet performance and execution against regulatory targets.

    While Severn Trent continues to benefit from stable operations, supportive management guidance and ongoing progress in efficiency initiatives, its outlook remains constrained by relatively high balance-sheet leverage and continued negative free cash flow despite healthy operating cash generation. Technical indicators remain mixed, while valuation appears broadly balanced, with a relatively high price-to-earnings ratio offset in part by the company’s attractive dividend yield.

    More about Severn Trent

    Severn Trent Plc is a UK-based provider of regulated water and wastewater services, supplying clean water, sewage treatment and essential infrastructure across its operating regions. The company is focused on delivering long-term investment across its network while maintaining reliable access to debt markets to finance its regulated asset base and future infrastructure projects.

  • Wall Street Futures Slip as Trump Signals End of U.S.-Iran Ceasefire: Dow Jones, S&P, Nasdaq

    Wall Street Futures Slip as Trump Signals End of U.S.-Iran Ceasefire: Dow Jones, S&P, Nasdaq

    U.S. equity futures traded lower ahead of Wednesday’s opening bell, pointing to another weak session after renewed geopolitical tensions triggered fresh risk aversion across financial markets.

    Investor sentiment deteriorated after President Donald Trump said the U.S.-Iran ceasefire was “over,” raising concerns that the conflict in the Middle East could intensify once again.

    “As far as I’m concerned, it’s over,” Trump told reporters at the NATO summit in Ankara, Turkey, calling negotiations with Iran a “waste of time.”

    The announcement pushed oil prices sharply higher, with U.S. crude futures jumping by more than 4%.

    The spike in energy prices has renewed worries about inflationary pressures and the direction of interest rates ahead of the release of the minutes from the Federal Reserve’s June policy meeting.

    Trump’s comments followed an announcement from U.S. Central Command confirming that more than 80 targets in Iran had been struck during a fresh military operation launched in response to Iran’s latest attacks on commercial vessels transiting the Strait of Hormuz.

    Iran’s Revolutionary Guards claimed they targeted U.S. military sites in Bahrain and Kuwait hours after the U.S. strikes.

    Tuesday’s session saw stocks recover from early losses for a time before selling resumed in the afternoon, leaving all three major indexes in negative territory by the close.

    The Nasdaq led the declines, reflecting broad weakness in technology shares.

    The Nasdaq fell 302.47 points, or 1.2%, to 25,818.69. The S&P 500 declined 33.58 points, or 0.5%, to 7,503.85, while the Dow Jones Industrial Average lost 130.76 points, or 0.3%, to 52,925.15.

    Semiconductor companies suffered particularly heavy losses, sending the Philadelphia Semiconductor Index down 4.7%.

    The sell-off accelerated after South Korean chipmaker Samsung Electronics (USOTC:SSNHZ) dropped nearly 7%.

    Although Samsung reported second-quarter profit that was 19 times higher than a year earlier, investors remained cautious about AI-related investment levels and future demand.

    “Although Samsung’s results were stellar, investors are getting nervous about the scale of money ploughing into AI and whether it’s a bubble waiting to burst,” said Dan Coatsworth, head of markets at AJ Bell.

    Chip stocks also weakened after Reuters reported that Chinese startup DeepSeek is developing its own AI processor.

    Networking companies also posted steep declines, pulling the NYSE Arca Networking Index down 3.7%.

    Gold miners, airlines and computer hardware manufacturers also ended the session lower, while energy, pharmaceutical and healthcare shares outperformed.

    Energy stocks gained as oil prices surged, although higher crude prices contributed to broader concerns across equity markets.

    U.S. crude futures rallied following reports of projectile attacks against several commercial vessels travelling through the Strait of Hormuz.