Category: Market News

  • Time Out Expands Global Markets and Media Reach as Continuing Operations Grow

    Time Out Expands Global Markets and Media Reach as Continuing Operations Grow

    Time Out (LSE:TMO) expects to report group revenue of approximately £72 million for the year ended 30 June 2026, slightly below the previous year, while revenue from continuing operations increased 11% to around £61 million as both its Markets and Media businesses delivered growth.

    The Media division returned to adjusted EBITDA profitability, supported by stronger sales in the UK and US, improved client retention, new customer wins and measures aimed at increasing cost efficiency.

    The performance reflects Time Out’s ongoing shift towards an integrated model combining its global media audience with physical food, culture and entertainment destinations.

    Market Portfolio Reaches 13 Locations

    Time Out opened three new Markets during the year, in Budapest, New York Union Square and Vancouver, taking its operating portfolio to 13 locations. Collectively, the Markets welcomed around 12 million visitors.

    A further six Markets are in development, including a flagship location at Piccadilly Circus in London. The company has also continued expanding through capital-light franchise arrangements, including initiatives in India and Brazil.

    This approach allows Time Out to broaden its international footprint while reducing the amount of capital required to operate new locations directly.

    Global Media Audience Climbs 31%

    Time Out’s global monthly media reach increased 31% to approximately 280 million people, while the number of active registered users rose to 2.5 million.

    The Media division is increasingly prioritising higher-value direct relationships with advertisers alongside live experiences, commerce and commercial partnerships. Programmatic advertising now accounts for less than 10% of Media revenue, reducing the business’s reliance on that advertising channel.

    Live events and brand activations generated approximately £2.4 million during the year. These activities also allow Time Out to connect digital campaigns with physical experiences at its Markets and other locations, strengthening the relationship between the group’s media and hospitality operations.

    Capital-Light Strategy Gains Momentum

    Time Out further developed its franchise model by moving its Boston Market and several Media territories to franchise arrangements. The strategy replaces directly generated trading revenue with royalty income while reducing associated operating costs.

    The company is also continuing the refinancing process for its senior debt. Combined with the Media division’s return to adjusted EBITDA profitability, this represents progress towards improving financial resilience despite overall group revenue remaining broadly flat year on year.

    Oakley Capital Funding Supports London Flagship

    To help finance development of the new flagship Time Out Market at Piccadilly Circus, the group increased an existing loan note with shareholder Oakley Capital Limited from £1.1 million to £2.1 million.

    The financing constitutes a related-party transaction. Time Out’s independent directors, after consulting with the company’s adviser, determined that the terms were fair and reasonable for shareholders.

    The additional funding provides further backing for the London development as Time Out seeks to demonstrate the potential of combining its physical Markets with its international media platform.

    Financial Position Remains a Key Constraint

    Despite operational progress, Time Out’s wider financial position continues to present challenges. The company has experienced a sharp decline in reported revenue alongside substantially larger losses, renewed cash outflows, increased debt and negative equity.

    Technical indicators are also weak, with the shares trading well below key moving averages and momentum measures remaining negative.

    Valuation metrics offer limited support while the business remains unprofitable, resulting in a negative price-to-earnings ratio, while dividend yield data is unavailable. Continued progress towards profitability, improved cash generation and successful refinancing will therefore remain important factors in the group’s financial outlook.

    More about Time Out

    Time Out Group plc operates across the leisure, hospitality and media industries, combining a global digital media platform with a growing portfolio of food and cultural Markets.

    Time Out Market brings together selected local chefs, restaurants, bars and cultural experiences within major urban destinations. Its Media operation provides city-focused editorial content, guides, video, social media and experiences to audiences worldwide.

    The group’s media presence extends across more than 350 cities in over 50 countries, supporting revenues from advertising, partnerships, commerce, sponsorship and live events. Its growth strategy increasingly focuses on capital-light franchises and partnerships while integrating digital audiences with physical Market experiences.
  • Shuka Minerals Intersects High-Grade Near-Surface Zinc at Kabwe

    Shuka Minerals Intersects High-Grade Near-Surface Zinc at Kabwe

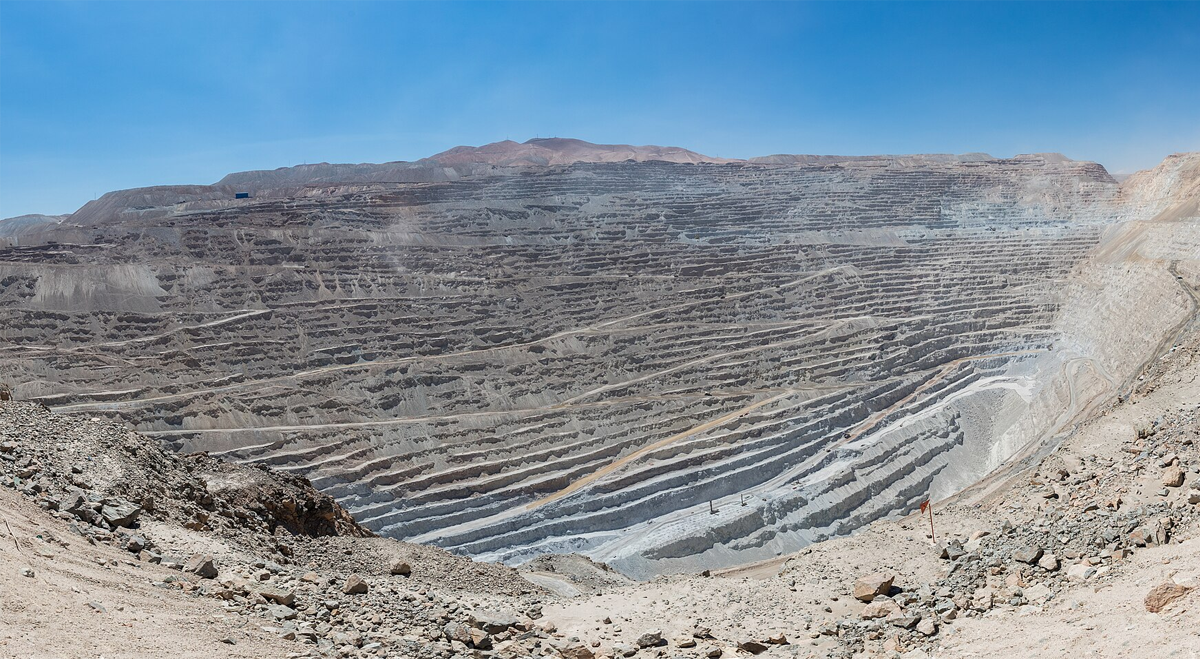
    Shuka Minerals (LSE:SKA) has completed its tenth drill hole at the Kabwe Zinc Mine in Zambia, reporting a substantial near-surface mineralised intersection from a newly identified orebody south of the existing Speaks and Mine Club zones.

    Drill hole KBDD10 encountered 61.5 metres of mineralisation starting from surface, with zinc grades reaching as high as 68%. The intersection also contained notable lead and copper values.

    The exceptionally high zinc grades indicate that portions of the mineralised material could potentially require relatively limited processing before being suitable for sale, although further evaluation will be needed as exploration progresses.

    New Orebody Could Expand Kabwe Resource Potential

    Shuka’s geological team believes the newly identified mineralisation forms part of a structurally controlled, pipe-like orebody. The zone appears to have more clearly defined boundaries than some of the other known orebodies at Kabwe, potentially making its geometry easier to interpret as additional drilling is completed.

    Importantly, the company believes the discovery could represent mineralisation additional to the resources currently reported at the Speaks and Mine Club areas.

    The results have encouraged Shuka to expand the initial drilling programme to 2,500 metres. Continued drilling will seek to establish the dimensions, continuity and grade distribution of the newly identified zone while providing further information on the wider mineralised system.

    If subsequent drilling confirms the initial geological interpretation, the discovery could indicate that Kabwe’s overall mineralised footprint is materially larger than currently recognised, potentially influencing the project’s future resource base, production potential and valuation.

    Financial Position Remains a Key Risk

    Despite the encouraging exploration results, Shuka Minerals continues to face significant financial challenges. Persistent losses, negative gross profit and ongoing cash consumption remain major constraints, while revenue has been unstable.

    Technical indicators provide only limited support. Although the shares have demonstrated some short-term strength, the MACD remains negative and the price is below its 200-day moving average, pointing to weaker longer-term momentum.

    Traditional valuation measures also offer limited insight while the company remains loss-making, resulting in a negative price-to-earnings ratio, while there is no dividend yield to provide additional shareholder return support.

    More about Shuka Minerals Plc

    Shuka Minerals Plc is an Africa-focused mining operator and developer with a primary listing on London’s AIM and a secondary listing on Johannesburg’s AltX.

    The company is advancing the Kabwe Zinc Mine in Zambia, where its activities are focused on zinc, lead, copper and associated metals. Alongside mine development and operations, Shuka is conducting exploration aimed at expanding the project’s resource base and establishing its longer-term production potential.

  • Diageo Appoints Former P&G Beauty Chief Alex Keith to Board

    Diageo Appoints Former P&G Beauty Chief Alex Keith to Board

    Diageo (LSE:DGE) has appointed R. Alexandra (Alex) Keith as a non-executive director, bringing more than 35 years of international consumer goods experience to the drinks group’s board.

    Keith is due to join the board on 5 November 2026, subject to shareholder approval, and will become a member of Diageo’s remuneration and nomination committees.

    She most recently served as chief executive of Procter & Gamble’s Beauty business, where her responsibilities included driving portfolio growth through product innovation, acquisitions and organisational transformation.

    Consumer Goods Experience Strengthens Board Expertise

    Keith brings extensive senior leadership experience across branded consumer products, including exposure to major markets in North America, Europe and Asia.

    Her appointment gives Diageo additional recent C-suite expertise as the company works to strengthen its competitive position and advance its broader strategic transformation.

    Chair Sir John Manzoni positioned the appointment as part of Diageo’s efforts to enhance the capabilities of its board and ensure the business remains responsive to changing consumer preferences. Keith’s experience in portfolio development, innovation and brand building could prove particularly relevant as the group adapts its product offering to evolving global drinking trends.

    Financial Strength Offset by Leverage and Softer Growth

    Diageo’s broader outlook is supported by solid underlying financial quality, including strong margins and an improvement in free cash flow. However, recent weakness in revenue and earnings, combined with elevated leverage, continues to weigh on the financial picture.

    Technical indicators are more supportive, with the shares trading above key moving averages and the MACD remaining positive. Signs that the stock may be overbought, however, moderate the strength of that technical momentum.

    Valuation remains relatively reasonable and the dividend yield provides additional support for shareholders, although the price-to-earnings multiple appears less compelling against the backdrop of the recent decline in profitability.

    More about Diageo

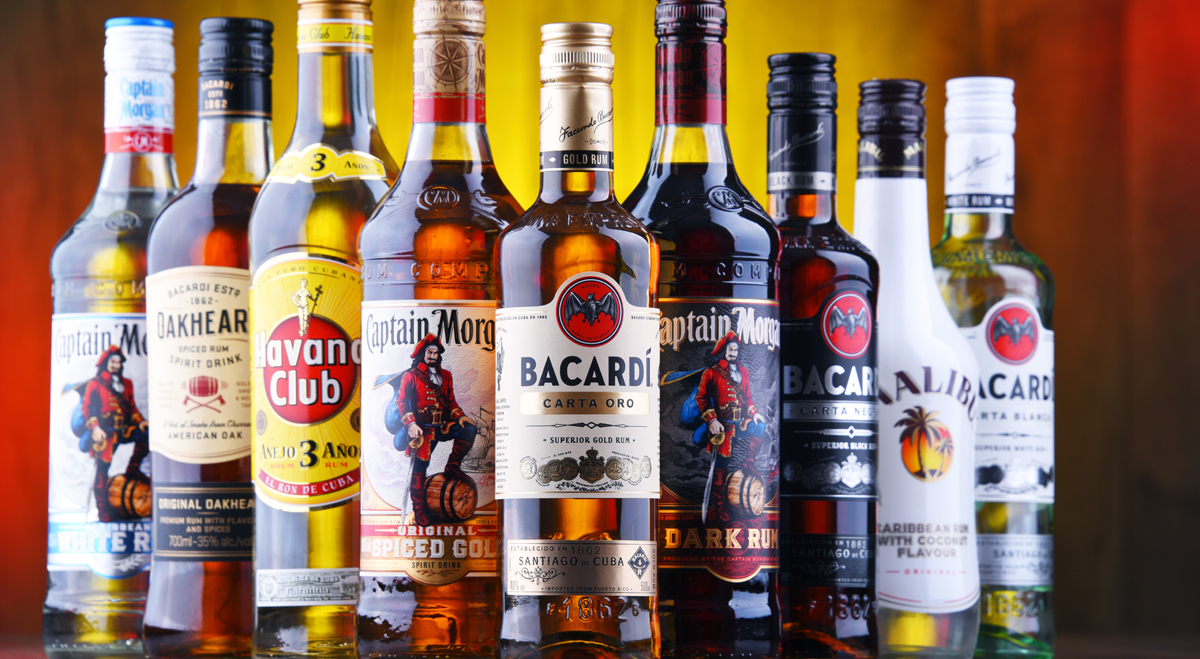
    Diageo is one of the world’s largest beverage alcohol companies, with a portfolio spanning spirits and beer brands including Johnnie Walker, Crown Royal, Smirnoff, Captain Morgan, Baileys, Don Julio, Tanqueray and Guinness.

    The company sells its products in nearly 180 countries and maintains listings on both the London Stock Exchange and the New York Stock Exchange, reflecting the international scale of its operations and shareholder base.

  • Huddled Group Launches Live-Commerce Platform and Creates Peeko Joint Venture

    Huddled Group Launches Live-Commerce Platform and Creates Peeko Joint Venture

    Huddled Group (LSE:HUD) has launched proprietary live-commerce software designed to centralise inventory, order processing and fulfilment across multiple sellers and online platforms as the company looks to expand its presence in the growing live-shopping market.

    The new system connects sellers to Huddled’s central stock and logistics infrastructure, allowing presenters to focus on live content, customer engagement and sales while the group handles back-end operations.

    Huddled believes the technology can support a scalable network of live-commerce channels while improving inventory utilisation and operational efficiency. The platform is also intended to strengthen fulfilment capabilities, including support for next-day delivery.

    Peeko Brand Expands Through AEWW Joint Venture

    Alongside the software launch, Huddled has established a joint venture with AEWW, which operates the AE Stores channel on live-shopping platform Whatnot.

    Under the arrangement, AE Stores will be rebranded as Peeko Gadgets and integrated with Huddled’s existing Peeko stores. The venture intends to accelerate live-auction activity and broaden the Peeko brand across Whatnot, where live-streaming, auctions and community interaction form a central part of the shopping experience.

    Further store launches are planned as the partnership develops. Huddled will provide the infrastructure supporting inventory and fulfilment, while AEWW is expected to benefit from greater operational scalability.

    The initiative gives Huddled another route to participate in the expansion of live commerce while using its centralised logistics platform across a wider network of sellers and channels.

    Financial Performance Remains a Key Challenge

    Despite the expansion of its live-commerce activities, Huddled’s financial position continues to present risks. The group remains loss-making, while negative and deteriorating free cash flow places additional pressure on its funding position.

    A reduction in the company’s equity and asset base also adds to financing concerns, particularly as Huddled invests in technology and seeks to scale its operations.

    Technical indicators remain weak, with the shares trading below major moving averages and continuing to exhibit a broader downward trend. Valuation measures offer limited additional support because negative earnings make the conventional price-to-earnings ratio less informative, while dividend yield data is unavailable.

    More about Huddled Group

    Huddled Group plc is an AIM-listed circular-economy e-commerce business developing live-commerce channels that combine live-streaming, auctions and online community engagement.

    The group operates centralised inventory and fulfilment infrastructure supporting both its own brands and third-party sellers. Its strategy is focused on improving stock utilisation, increasing operational efficiency and providing scalable fulfilment, including next-day delivery capabilities, across multiple online sales platforms.

  • Property Franchise Group Sets September Date for Interim Results and Investor Presentations

    Property Franchise Group Sets September Date for Interim Results and Investor Presentations

    The Property Franchise Group PLC (LSE:TPFG) will publish its interim results for the six months ended 30 June 2026 on 9 September 2026, giving investors an update on trading and financial performance across its extensive property and financial services network.

    The group is the UK’s largest multi-brand property franchisor, with more than 1,900 outlets operating under 18 brands. Its business spans residential property services and financial services, with a presence across both traditional high-street agencies and hybrid property models.

    The Bournemouth-headquartered company has been listed on AIM since 2013 and joined the AIM 100 index in 2024.

    Management Plans Analyst and Retail Investor Briefings

    Following the results announcement, management will hold separate live virtual presentations and question-and-answer sessions for analysts and retail investors.

    The retail investor presentation will be accessible online to both existing and prospective shareholders, providing a broader audience with an opportunity to hear directly from management about the interim performance and outlook.

    The initiative reflects the group’s focus on maintaining regular engagement with its shareholder base and improving access to company information. Wider participation in management presentations may also help investors gain greater insight into the group’s strategy and financial position.

    Strong Fundamentals Offset by Weaker Share Price Momentum

    The Property Franchise Group’s broader outlook is supported by solid financial fundamentals, including profitability, low leverage and strong conversion of earnings into free cash flow.

    Shareholder returns also provide support, with the group offering an attractive yield alongside what remains a relatively reasonable price-to-earnings valuation.

    Near-term technical indicators are less favourable. The shares are trading below important moving averages, while a negative MACD points to weak market momentum. These signals temper the near-term picture despite the company’s stronger underlying financial characteristics.

    More about The Property Franchise Group

    The Property Franchise Group PLC is the UK’s largest multi-brand property franchisor, operating more than 1,900 outlets across a portfolio of 18 brands.

    Founded in 1986 and headquartered in Bournemouth, the group provides residential property services alongside an established financial services operation. Its network incorporates both traditional high-street and hybrid agency models, while the financial services business participates in major UK mortgage networks.

    The company has traded on AIM since 2013 and became a constituent of the AIM 100 index in 2024.

  • Pulsar Group Addresses Market Speculation Over HMRC Tax Discussions

    Pulsar Group Addresses Market Speculation Over HMRC Tax Discussions

    Pulsar Group Plc (LSE:PULS) has moved to clarify its position following recent media reports concerning discussions with HM Revenue & Customs, confirming that it remains in regular contact with the UK tax authority regarding the timing of certain VAT and PAYE payments.

    The company said it has already made substantial payments towards its tax obligations and expects to meet its remaining liabilities through cash generated from normal collections. This suggests that the outstanding amounts are expected to be managed through the group’s existing cash flows rather than requiring alternative sources of funding.

    Board Says Trading and Operations Remain Stable

    Pulsar Group said underlying trading remains stable and that its operations are continuing as usual despite the ongoing discussions with HMRC.

    The Board expects the matter to reach a satisfactory conclusion and sought to reassure shareholders that the discussions do not currently undermine the group’s operational or financial stability. Further announcements will be issued if required as the situation develops.

    The clarification follows market speculation surrounding the company’s tax position and provides investors with additional context on its liquidity and ability to meet the outstanding payments.

    Financial Performance Continues to Weigh on Outlook

    Despite the reassurance surrounding its HMRC discussions, Pulsar Group’s broader financial picture remains challenging. Declining revenue, pressure on gross margins and continued net losses are among the main factors weighing on the outlook.

    Technical indicators are also weak, with the share price trading below key moving averages and the MACD remaining negative. Negative earnings additionally limit the usefulness of conventional valuation measures.

    There are some more supportive elements. Leverage remains relatively modest, while the return to positive operating and free cash flow in 2025 represents an improvement. However, continued cash-flow volatility and the absence of sustained profitability leave the overall financial position dependent on further operational progress.

    More about Pulsar Group Plc

    Pulsar Group Plc is a UK-based company listed on AIM under the ticker PULS. The group has said its underlying trading remains stable and that business operations are continuing normally while it maintains regular engagement with HMRC.

    Ongoing customer cash collections are expected to support the settlement of its remaining tax obligations as the company works towards resolving the timing of its outstanding VAT and PAYE payments.

  • Winvia Entertainment Secures £33 Million Barclays Loan to Support Prize Draw Expansion

    Winvia Entertainment Secures £33 Million Barclays Loan to Support Prize Draw Expansion

    Winvia Entertainment PLC (LSE:WVIA) has restructured its borrowing arrangements after securing a new £33 million three-year term loan from Barclays Bank, providing the entertainment group with additional financial flexibility as it targets further growth in the UK prize draw market.

    The new Barclays financing replaces Winvia’s previous banking facilities with Eurobank. Alongside the term loan, Barclays has made available a £5 million revolving facility intended to support acquisitions.

    That facility also includes an uncommitted accordion option allowing it to be increased by as much as £15 million, potentially giving Winvia additional funding capacity should suitable acquisition opportunities emerge.

    Funding Structure Supports Acquisition Strategy

    Winvia’s Board said the refinancing, together with the company’s net cash position of approximately £31.8 million at 30 June 2026, provides the group with a secure and low-leverage capital structure from which to pursue its expansion plans.

    The increased funding flexibility is particularly relevant to Winvia’s consolidation strategy in the fragmented UK prize draw industry. Management sees opportunities to combine organic growth with acquisitions, potentially allowing the company to expand its market presence and integrate additional businesses onto its existing technology platform.

    The new Barclays facilities could therefore provide greater capacity to pursue M&A opportunities while maintaining what the Board considers a prudent balance sheet position.

    More about Winvia Entertainment PLC

    Winvia Entertainment PLC is a technology-led entertainment business operating in the UK prize draw industry and the regulated Romanian online gaming market.

    The company is the UK’s second-largest prize draw operator by market share and owns brands including Best of the Best, Click Competitions and Rev Comps. Its Romanian online gaming portfolio includes Princess Casino, Royal Slots and Luck.

    Winvia’s operations are supported by a proprietary technology platform developed internally, which serves both its B2C and B2B activities and has contributed to improved operating performance.

    The group’s near-term strategy is focused on increasing its presence in the fragmented UK prize draw market through a combination of organic expansion and acquisitions, with acquired businesses potentially benefiting from integration with Winvia’s existing technology infrastructure.

  • Air China Reports Stronger July Passenger Traffic as Network and Fleet Expand

    Air China Reports Stronger July Passenger Traffic as Network and Fleet Expand

    Air China (LSE:AIRC) recorded stronger passenger activity in July 2026, with traffic growth comfortably outpacing the expansion in available capacity as the airline continued developing its domestic and international networks.

    Passenger capacity increased by 4.8% year on year during the month, while passenger traffic climbed 11.2%. As a result, the passenger load factor improved to 85.0%.

    Growth was led by domestic and international operations, contrasting with a contraction across regional routes. The figures indicate that Air China is continuing to concentrate capacity growth on its core mainland Chinese network and longer-haul international services.

    Cargo Load Factor Edges Lower

    Air China’s cargo operations delivered more moderate growth. Available cargo capacity rose 8.9% year on year in July, while cargo and mail traffic increased by 7.0%.

    With capacity expanding faster than demand, the cargo load factor slipped to 42.2%, highlighting a softer performance in freight compared with the airline’s passenger business during the period.

    New Routes Support Continued Network Expansion

    The airline continued to broaden its network during July, introducing new domestic connections from Chongqing and Nanchang alongside additional international services.

    New overseas routes included flights from Beijing to Venice and Bishkek, strengthening Air China’s connections with Europe and Central Asia.

    The group also expanded its fleet to 973 aircraft, supporting additional passenger capacity and the continued development of its international and domestic route portfolio.

    Air China noted that the operating figures were compiled from internal statistics and may differ from numbers subsequently presented in its periodic financial reports. Investors therefore need to take potential differences in reporting methodology into account when comparing the monthly operating data with future published results.

    More about Air China

    Air China Limited is one of China’s major airlines, providing passenger and cargo services across domestic, international and regional markets.

    The carrier operates a mixed fleet of nearly 1,000 aircraft through a combination of self-owned planes, finance leases and operating leases, giving it one of the largest aviation platforms in the Chinese market.

    Air China regularly adjusts its capacity, network and fleet composition as demand develops, while expanding services from major hubs including Beijing Capital and Chongqing. Its fleet renewal programme, including the addition of C919 and Boeing 737 aircraft, supports the group’s strategy of strengthening connectivity within China and across international markets including Europe and Central Asia.

  • Filtronic Publishes 2026 Annual Report and Sets AGM Date

    Filtronic Publishes 2026 Annual Report and Sets AGM Date

    Filtronic (LSE:FTC) has released its Annual Report and Accounts for the financial year ended 31 May 2026 alongside the notice for its upcoming Annual General Meeting, giving shareholders access to the latest corporate reporting and governance materials.

    The documents are now available electronically, while printed copies are being sent to shareholders who have previously requested paper communications. Filtronic’s 2026 AGM will take place on 30 October 2026 at the company’s NETPark facility in Sedgefield, County Durham.

    The meeting will provide shareholders with an opportunity to consider the formal business of the AGM and engage with the company on governance matters.

    Filtronic Encourages Shift to Digital Communications

    Alongside the publication of its annual report, Filtronic is encouraging investors to adopt electronic shareholder communications rather than continue receiving printed materials.

    The company said the transition can help reduce the environmental impact associated with producing and distributing physical documents while improving the efficiency of shareholder communications. Greater use of digital reporting could also streamline access to company information and meeting documents while reducing related administrative requirements.

    The initiative is consistent with Filtronic’s broader sustainability objectives and reflects the increasing use of electronic communications between listed companies and their shareholders.

    Outlook Reflects Stronger Fundamentals but Profitability Pressures

    Filtronic’s broader outlook combines improving underlying fundamentals and relatively low leverage with some areas of concern. A decline in profitability during 2026 and weaker conversion of earnings into free cash flow weigh on the financial picture.

    Market indicators also remain less supportive, with bearish technical signals and subdued momentum. Meanwhile, the company’s elevated price-to-earnings multiple provides limited valuation support, increasing the importance of future earnings delivery and cash generation.

    More about Filtronic

    Filtronic plc develops and manufactures advanced radio-frequency products and solutions for the space, aerospace and defence, and telecommunications infrastructure markets.

    Its technology is designed for demanding, high-performance communications applications, giving the company exposure to specialised areas of the global RF and connectivity industry.

  • RHI Magnesita Names Gustavo Franco as Successor to CEO Stefan Borgas

    RHI Magnesita Names Gustavo Franco as Successor to CEO Stefan Borgas

    RHI Magnesita (LSE:RHIM) has confirmed a planned change at the top of the refractory products group, with Gustavo Franco set to take over as chief executive from Stefan Borgas on 1 November 2026.

    Franco, a long-standing member of the company’s leadership team, brings around two decades of experience in the refractory industry. His appointment follows a structured succession process and will include a handover period with Borgas ahead of the leadership change.

    Franco also played an important role in the 2017 merger of RHI and Magnesita, which created the current group. His promotion is expected to provide continuity as RHI Magnesita pursues its existing strategy and seeks to generate sustainable long-term value for customers, employees and shareholders.

    Outlook Balances Operational Challenges With Deleveraging Potential

    The leadership transition comes as RHI Magnesita navigates a challenging operating environment. The company’s financial position remains adequate, although weaker revenue, pressure on margins and increased leverage have weighed on the overall picture.

    End-market conditions are also expected to remain subdued, with weak demand potentially continuing until at least 2027. Against this backdrop, management’s guidance has placed greater emphasis on execution, including opportunities to improve EBITA and reduce leverage.

    Supporting the outlook are constructive technical trends and a valuation profile that remains relatively favourable to shareholders. Progress on operational improvements and deleveraging could therefore become increasingly important if demand across the group’s major industrial markets remains soft.

    More about RHI Magnesita NV

    RHI Magnesita is a global supplier of refractory products, systems and services used in industrial processes operating at temperatures above 1,200°C. Its customers span the steel, cement, non-ferrous metals, glass and other process industries.

    The group employs more than 20,000 people and operates an extensive international network encompassing raw-material locations, manufacturing facilities, recycling centres and sales offices. RHI Magnesita is listed in London and also maintains a secondary listing in Vienna.

    Its portfolio combines refractory materials with technical expertise and related services, making the company an important supplier to heavy industry. The business has developed a geographically diversified footprint following the combination of RHI and Magnesita, with its strategy centred on customer partnerships, operational efficiency, sustainability, innovation and digitalisation.