Category: Market News

  • European stocks rise as lower yields and Fed pause expectations support sentiment: DAX, CAC, FTSE100

    European stocks rise as lower yields and Fed pause expectations support sentiment: DAX, CAC, FTSE100

    European equities moved modestly higher at the start of the week as declining government bond yields and a weaker U.S. dollar improved risk appetite, with investors increasingly expecting the Federal Reserve to keep interest rates unchanged at its September meeting.

    The pan-European Stoxx Europe 600 Index gained 0.2%, recovering some ground after ending a four-week winning streak on Friday. Among the major regional markets, Germany’s DAX advanced 0.2%, France’s CAC 40 was broadly unchanged and London’s FTSE 100 climbed 0.4%.

    European sovereign bond yields retreated from the multi-week highs reached recently, providing some relief to equity markets. The move was particularly supportive for growth-oriented sectors, which tend to be more sensitive to changes in borrowing costs and discount rates.

    At the same time, the U.S. dollar weakened against major currencies as investors reduced expectations for further near-term Federal Reserve tightening.

    Weak U.S. data pushes Fed pause probability towards 70%

    Money markets are now pricing in approximately a 70% chance that the Federal Reserve will leave its benchmark interest rate unchanged at its September policy meeting.

    Expectations have shifted following a series of softer U.S. economic releases that have weakened the argument for additional monetary tightening in the near term.

    Investors have recently digested several important data points, including a weaker-than-expected July employment report showing a contraction in payrolls, Consumer Price Index figures that met expectations, a flat Producer Price Index reading and an unexpected 0.6% month-on-month decline in July retail sales.

    Taken together, the figures have reduced concerns that inflationary pressures will require an immediate policy response. That has encouraged expectations that the Federal Reserve can maintain its current policy stance for longer while assessing the direction of the U.S. economy.

    For equity markets, the possibility of an extended pause has provided support by reducing fears of another increase in borrowing costs.

    Sparse European calendar keeps global risks in focus

    Europe’s economic calendar is unusually quiet this week, leaving regional equity markets more dependent on developments in the global economy, bond markets, currencies and commodities for direction.

    Several risks that influenced trading throughout August nevertheless remain unresolved.

    One of the most significant is the continuing disruption to shipping through the Strait of Hormuz. Diplomatic negotiations between Washington and Tehran over commercial transit remain deadlocked, keeping crude oil prices elevated and maintaining pressure on input costs for energy-intensive European companies.

    European equities have already enjoyed a strong summer rally that brought several benchmarks close to record highs. As a result, strategists remain divided over whether equity risk premiums have become too compressed relative to persistently high real borrowing costs.

    The second-quarter earnings season is also largely complete. The succession of better-than-expected corporate results that supported European stocks through late July has therefore faded, leaving macroeconomic developments as a more important driver of market direction.

    Markets turn to U.S. PMIs and Jackson Hole

    Attention is now shifting towards upcoming U.S. economic indicators that could provide the next significant catalyst for global markets.

    S&P Global’s preliminary August Purchasing Managers’ Index readings for U.S. manufacturing and services are due later this week. They will be followed by the Federal Reserve’s annual Jackson Hole Symposium the following week.

    Investors will examine the data for evidence that economic activity is cooling at a controlled pace. A gradual slowdown would strengthen expectations for a soft landing while supporting the case for the Federal Reserve to keep rates unchanged.

    Markets will also be watching closely for any signs that inflationary pressures are rebuilding, which could challenge the increasingly widespread expectation of an extended policy pause.

  • FTSE 100 rises as weak U.S. retail sales ease Fed tightening concerns

    FTSE 100 rises as weak U.S. retail sales ease Fed tightening concerns

    UK equities moved higher on Monday as weaker-than-expected U.S. retail sales reduced expectations for further near-term monetary tightening by the Federal Reserve, allowing London’s blue-chip index to recover some ground after falling 1.4% last week.

    The FTSE 100 gained 0.26% as of 03:25 ET (07:25 GMT). Elsewhere in Europe, Germany’s DAX slipped 0.03%, while France’s CAC 40 edged 0.05% lower. Sterling strengthened 0.22% against the dollar to $1.3562.

    Sentiment received support from U.S. retail sales data showing a 0.6% month-on-month decline in July. Economists had expected an increase of 0.1%, while the contraction was the steepest monthly fall since May 2025.

    The disappointing figures pushed U.S. Treasury yields and the dollar lower on Friday as investors scaled back expectations for tighter Federal Reserve policy, providing a more supportive backdrop for equities at the beginning of the new week.

    U.S.-Iran tensions keep Hormuz risks in focus

    Geopolitical uncertainty remained a significant consideration for markets. Speaking at Market Regulation Headquarters on Sunday evening, Iran’s vice president said Tehran would be successful in its “economic warfare” as Washington prepared to announce another round of sanctions this week.

    Shipping activity through the Strait of Hormuz remained severely restricted. Ship-tracking company Kpler recorded no commodity vessel crossings on Sunday and only five on Saturday, compared with 31 during the previous weekend.

    The 60-day memorandum of understanding between the U.S. and Iran, agreed in June to halt hostilities, expired on Monday without discussions taking place over an extension. Tehran has maintained that Washington must first meet its obligations under the original agreement.

    Regional security arrangements have also moved into focus. Saudi Arabia, Turkiye and Pakistan signed the Mecca Joint Defence Agreement on Aug. 7, establishing collective-defence provisions. Washington welcomed the agreement, while Turkish President Erdogan said the pact had “sent an important message to the world” and described Egyptian participation as “possible.”

    Jefferies analysts said on Monday that they saw no simple route towards resolving the confrontation, characterising the current situation as “no war and no peace” while the Strait of Hormuz remains closed.

    “The only possibility remains a fudge or look the other way arrangement by which some traffic can start to flow through the Strait while the US and Iran try to negotiate a deal,” strategist Mohit Kumar wrote in a morning note.

    Jefferies said the fragile truce could potentially survive until the U.S. mid-term elections before the threat of renewed escalation increases. From a market perspective, the broker said a crucial question is how far oil prices could rise before Washington becomes willing to make concessions.

    The firm also noted that Europe and Asia are more vulnerable than the United States to an extended disruption in the Strait because of their greater dependence on imported energy supplies.

    UK housing market remains under pressure

    Domestic housing figures added to the cautious UK economic backdrop. Asking prices fell 2% month-on-month in August to an average of £364,999, according to a media report citing Rightmove data.

    The decline was the largest recorded for August since 2018. Prices were also 1% lower year-on-year, representing the steepest annual decline since December 2023, while the number of homes available for sale reached a 12-year seasonal high.

    Rightmove lowered its forecast for house prices across the whole of 2026 to a range of 0% to minus 2%, compared with its previous expectation for growth of 2%.

    “The mini Burnham bounce and some renewed general optimism have brought a degree of improvement,” Rightmove’s Colleen Babcock was quoted as saying, “but whether that develops into a more sustained recovery will likely depend on confidence, mortgage rates and the new chancellor’s first budget this Autumn.”

    Oil slips while gold moves higher

    Energy prices edged lower as investors continued to assess the geopolitical outlook. Brent crude fell 0.30% to $88.26 a barrel, while WTI declined 0.70% to $80.90.

    Precious metals moved in the opposite direction. Gold futures advanced 0.36% to $4,453.35 an ounce, while spot gold gained 0.46% to $4,397.18.

    UK round up

    AstraZeneca (LSE:AZN) discontinued its Phase III eVOLVE-Lung02 study after an independent review concluded that the combination of volrustomig and chemotherapy was unlikely to achieve its progression-free survival or overall survival endpoints when compared with pembrolizumab plus chemotherapy.

    The trial enrolled 895 patients and identified no new safety signals. AstraZeneca said its other Phase III studies evaluating volrustomig will continue as planned.

  • Gattaca grows profit and net fee income as contract hiring drives FY26 performance

    Gattaca grows profit and net fee income as contract hiring drives FY26 performance

    Gattaca (LSE:GATC) delivered stronger results for the year ended 31 July 2026, with group net fee income increasing 11% to £43.2 million as rising demand for contract recruitment supported growth across its core specialist markets.

    Contract net fee income advanced 16% during FY26, driven by activity across infrastructure, defence, energy, mobility and digital technology. This growth helped offset subdued statement of work activity and a modest decline in like-for-like permanent recruitment fees.

    Improved sales productivity and continued cost discipline also contributed to a significant increase in profitability. Gattaca expects to report underlying profit before tax of approximately £6.1 million, almost double the level achieved in the previous financial year and slightly ahead of its guidance.

    The group finished FY26 with net cash of £15 million, leaving it with a strong balance sheet as it considers opportunities to invest in further growth. The financial position also provides support for continued shareholder distributions in accordance with Gattaca’s stated dividend policy.

    Management intends to make targeted investments in additional sales consultants as it seeks to capture greater market share across its specialist sectors. The company is also continuing to evaluate selective acquisition opportunities that could strengthen its capabilities or increase exposure to attractive niche markets.

    Despite continued uncertainty in the wider economy and cautious hiring decisions among some customers, the board expects further progress during the new financial year. Gattaca is forecasting another improvement in profit before tax in FY27.

    The company’s wider financial picture remains mixed. Its low-leverage balance sheet and improving operating margins provide support, although negative operating and free cash flow and relatively thin net profitability remain areas of concern.

    Technical indicators also suggest some caution, with momentum signals remaining weak despite the shares trading above major moving averages. Valuation is more supportive, with Gattaca trading on a relatively low price-to-earnings ratio while also providing a moderate dividend yield.

    More about Gattaca

    Gattaca plc is a specialist workforce solutions provider supplying contract and permanent professionals alongside statement of work services.

    The group focuses on industries requiring highly skilled technical talent, including infrastructure, defence, energy, mobility and digital technology. Gattaca has also expanded its capabilities through acquisitions such as InfoSec People, strengthening its presence in specialist and niche recruitment markets.

  • Seeing Machines launches Physical AI platform to expand into collaborative robotics

    Seeing Machines launches Physical AI platform to expand into collaborative robotics

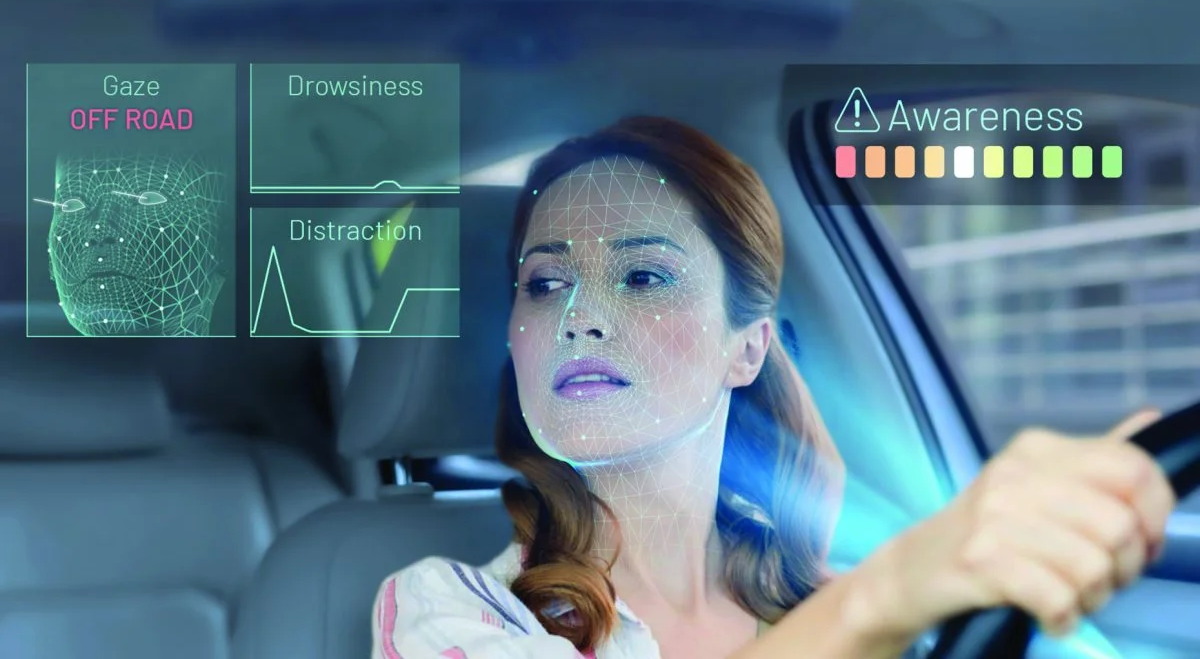
    Seeing Machines (LSE:SEE) has launched a new Physical AI Platform designed to extend its Human-Centred AI technology beyond transport safety and into the rapidly developing markets for humanoid robots, collaborative robotics and industrial automation.

    The platform gives machines a dynamic three-dimensional understanding of people, objects and their surrounding environment. By interpreting spatial relationships and human behaviour, the technology is intended to help robots interact with people more naturally while maintaining safety in shared environments.

    Rather than analysing people and objects as separate elements, Seeing Machines’ Physical AI technology processes them as components of a unified scene. This approach is designed to provide machines with greater contextual awareness and a better understanding of how people are likely to behave within changing surroundings.

    Such capabilities could be particularly important in complex and unpredictable environments including factories, warehouses, hospitals and public spaces, where robots increasingly need to work alongside people rather than within isolated or highly controlled areas.

    The launch represents a strategic expansion for Seeing Machines, which has built its technology around more than two decades of research into human behaviour and machine perception. The company is now applying that expertise to the emerging collaborative robotics market as advances in artificial intelligence and automation increase demand for machines capable of safely interpreting human activity.

    Physical AI could also broaden the company’s addressable market beyond its established transport safety operations. Potential applications span manufacturing, logistics, healthcare, aged care, mining and other areas of industrial automation, creating opportunities to diversify the group’s longer-term revenue base.

    Seeing Machines’ financial profile nevertheless remains mixed. Revenue growth has been particularly strong, but the company continues to report losses, a negative net margin and negative operating cash flow.

    Technical indicators provide a more supportive picture, with the shares trading above major moving averages and momentum ranging from neutral to positive. Traditional valuation measures remain difficult to apply while Seeing Machines is loss-making, resulting in a negative price-to-earnings ratio, while no dividend yield is available.

    More about Seeing Machines

    Seeing Machines is an Australian-headquartered technology company specialising in Human-Centred AI systems designed to help machines understand people and their surroundings, particularly in safety-critical environments.

    Drawing on more than 25 years of human factors research, the company develops vision-based monitoring technologies and Driver Monitoring Systems combining artificial intelligence algorithms, embedded processing and optics. These systems assess factors including human behaviour, attention and cognitive state across automotive, commercial transport, aviation, robotics and industrial automation applications.

    Its Safety AI portfolio includes Cabin AI, Cockpit AI and the new Physical AI platform, with the company’s technologies designed to improve real-time risk anticipation and support safer machine decision-making.

    Seeing Machines’ driver and occupant monitoring technology has been installed in more than eight million vehicles worldwide. The company works with major industry partners internationally and maintains operations across Australia, the U.S., Europe and Asia.

  • Telecom Plus starts five-year growth plan strongly and maintains FY27 guidance

    Telecom Plus starts five-year growth plan strongly and maintains FY27 guidance

    Telecom Plus (LSE:TEP) has reported an encouraging start to its new five-year growth strategy, with customer additions accelerating during the opening four months of FY27 and the company maintaining its full-year profit guidance.

    Annualised growth in multiservice customers is running slightly ahead of the group’s 10% target and at more than 2.5 times the pace recorded during the comparable period last year.

    Activity across the company’s Partner distribution network has also reached record levels. The number of active Partners has increased to approximately 4,900 per month, while the overall Partner network now exceeds 85,000 people. Telecom Plus is also expecting record attendance at its forthcoming sales conference, providing further evidence of increased engagement across its distribution channel.

    Cross-selling existing customers additional services represents another important element of the growth strategy. Around 17,000 additional core services have already been sold against the company’s full-year target of 50,000.

    Telecom Plus is simultaneously progressing the re-platforming of its insurance operations, which is expected to provide the infrastructure required for the planned introduction of motor insurance during the second half of the financial year.

    Investment in digitalisation is continuing alongside new marketing initiatives designed to increase brand awareness and customer acquisition. These include new advertising campaigns and partnerships such as Post Office Plus, which could provide additional routes for reaching potential customers.

    Following the strong start to the year, Telecom Plus reaffirmed its FY27 guidance for adjusted profit before tax of between £80 million and £90 million.

    The company is also maintaining its dividend while progressing a £40 million share buyback programme. These shareholder returns reflect management’s confidence in the group’s ability to generate sustainable earnings growth as its five-year strategy develops.

    From an investment perspective, Telecom Plus continues to demonstrate improving margins and strong return on equity, although rising leverage and fluctuations in cash flow provide some counterbalance. Valuation remains comparatively supportive, with a low price-to-earnings ratio and a high dividend yield.

    Technical indicators are considerably weaker, however, with the shares trading below all major moving averages and momentum indicators remaining negative.

    More about Telecom Plus

    Telecom Plus, which operates under the Utility Warehouse brand, is a UK-listed provider of essential household services offered primarily through subscription-style relationships.

    Its services include energy, broadband, mobile and insurance, which are delivered through an integrated platform and marketed through a nationwide network of local Partners. Utility Warehouse aims to provide customers with competitive pricing and the convenience of combining multiple household services into a single monthly bill.

    The business model is centred on recurring revenues, cross-selling additional services to existing households and maintaining high levels of long-term customer retention.

  • ECR Minerals secures up to A$3m funding for Creswick through Bold Gold joint venture

    ECR Minerals secures up to A$3m funding for Creswick through Bold Gold joint venture

    ECR Minerals (LSE:ECR) has entered into binding conditional farm-in and joint venture agreements with Australian explorer Bold Gold Resources that could provide up to A$3 million of exploration funding for the Creswick Gold Project in Victoria.

    Under the agreement, Bold Gold has a pathway to earn as much as an 80% interest in Creswick by financing exploration through a series of staged commitments. The arrangement brings additional capital, technical expertise and operating capacity to an asset ECR considers highly prospective but comparatively underexplored.

    Bold Gold is required to spend at least A$250,000 during the first year. It can subsequently earn a 51% interest in the project by investing A$1.25 million over three years.

    The Australian explorer can then increase its ownership to 80% by taking total expenditure to as much as A$3 million, subject to the renewal of certain licences. ECR will retain an interest in the project under the joint venture structure as well as potential exposure through royalties.

    The board views the transaction as strategically significant because it provides a route to accelerate exploration at Creswick without placing additional funding pressure on ECR’s own balance sheet.

    Bringing in a partner to finance and operate exploration at Creswick should also allow ECR to direct more of its capital and management resources towards its Queensland portfolio. The company is seeking to advance those assets towards production while continuing exploration across its broader portfolio of Australian gold projects.

    The company’s overall financial profile remains challenging, however. ECR currently generates no revenue and continues to report losses and cash outflows, indicating that future funding requirements remain an important consideration.

    Technical indicators are also weak, with the shares trading below all major moving averages. Some financial support comes from ECR’s debt-free balance sheet and improvements in losses and cash outflows compared with earlier periods, although these factors do not fully offset the company’s weaker underlying fundamentals.

    More about ECR Minerals

    ECR Minerals is a UK-listed gold exploration and development company with a portfolio of Australian assets spanning Victoria, Queensland, South Australia and Western Australia.

    Its projects include the Creswick Gold Project in Victoria’s established goldfields as well as the Maddens and Blue Mountain assets in northern Queensland. The company’s wider strategy combines exploration and project development with efforts to establish near-term production opportunities across its portfolio.

  • Tekmar secures €1m cable protection contract for European offshore windfarm

    Tekmar secures €1m cable protection contract for European offshore windfarm

    Tekmar Group plc (LSE:TGP) has secured a contract valued at approximately €1 million to provide concrete cable protection and stabilisation solutions for a major offshore windfarm in Europe.

    The award represents Tekmar’s first concrete protection order from an existing submarine cable contractor, expanding the scope of its relationship with the customer. Delivery of the products is scheduled to take place during 2026.

    Management views the contract as an important commercial milestone for the group’s concrete solutions business and further evidence of its growing presence within the European offshore wind sector.

    The order also contributes to Tekmar’s record backlog as the company progresses Project Aurora, an initiative designed to bring its asset protection technologies and offshore energy services together on a more integrated operating platform.

    Through Project Aurora, Tekmar is seeking to improve manufacturing throughput and operational efficiency while offering customers a broader range of complementary products and services. The strategy is intended to strengthen the group’s proposition across international offshore wind projects as well as the oil and gas sector.

    The latest contract provides additional visibility over future activity and builds on Tekmar’s established experience in protecting and stabilising critical subsea infrastructure.

    The company’s wider financial position nevertheless remains challenging. Tekmar has continued to report losses, while revenue contracted significantly and the business experienced cash burn during FY2025.

    Technical indicators provide a more supportive picture, with the shares trading above key moving averages and MACD remaining positive. Conventional valuation measures are less informative while the company remains loss-making, resulting in a negative price-to-earnings ratio, while no dividend data is available.

    More about Tekmar Group plc

    Tekmar Group plc is a UK-headquartered provider of asset protection technology and offshore energy services serving energy transition and marine infrastructure markets worldwide.

    Operating through its Asset Protection Technology and Offshore Energy Services divisions, the group provides engineering-led products and services designed to protect and stabilise critical offshore infrastructure. Its principal markets include offshore wind, subsea interconnectors and oil and gas.

    Tekmar has more than 40 years of industry experience and has supported over 120 offshore wind projects across 25 countries, representing more than 50GW of installed capacity worldwide.

    The group has deployed thousands of cable protection systems and subsea stabilisation products, supported by geotechnical and analytical expertise and scalable manufacturing capabilities. Its international customer base spans Europe, Africa, the Middle East, Asia-Pacific and North America.

  • ATOME advances Villeta project as Paraguay reviews power policy

    ATOME advances Villeta project as Paraguay reviews power policy

    ATOME PLC (LSE:ATOM) is continuing to advance its flagship Villeta industrial project in Paraguay as the country reassesses elements of its electricity policy following a series of political and regulatory changes.

    The power-intensive industrial developer holds a long-term power purchase agreement with state utility ANDE covering 145MW of reserved capacity. The US$665 million Villeta development is ready to build and is positioned to become the largest industrial foreign investment undertaken in Paraguay.

    ATOME expects the project to generate more than US$1 billion of revenue for ANDE over its lifetime while creating thousands of jobs. The development is also intended to establish a new industrial sector connected to Paraguayan agriculture and food security, increasing the amount of value generated domestically from the country’s resources.

    Recent developments in Paraguay’s energy sector have introduced additional considerations for the project. These include the revocation of previous presidential decrees, the resignation of ANDE’s former president and the creation of a new working group focused on energy policy.

    The changes have prompted a reassessment of electricity tariffs and governance arrangements. However, ATOME is regarded by ANDE as an existing customer and already holds a signed power purchase agreement that, for planning purposes, extends to 2050.

    The company is continuing discussions with relevant stakeholders as it seeks to preserve the commercial framework underpinning Villeta. It is also working alongside engineering, procurement and construction partner Casale S.A. to maintain progress and protect the project’s original development timetable.

    ATOME intends to provide a further update on the situation by the end of August.

    The company’s broader financial profile remains challenging because it is still pre-revenue and continues to report losses and negative free cash flow, leaving an ongoing requirement for funding as its projects progress.

    Technical indicators provide a more supportive picture, with the shares trading above major moving averages and MACD remaining positive. However, conventional valuation measures remain constrained by negative earnings, resulting in a negative price-to-earnings ratio, while no stated dividend yield is available.

    More about ATOME PLC

    ATOME PLC is a power-intensive industrial developer focused on its flagship Villeta green industrial project in Paraguay.

    The company has secured a long-term power purchase agreement with state-owned utility ANDE covering 145MW of reserved electricity capacity. Backed by US$665 million of international institutional investment, Villeta is positioned as Paraguay’s largest industrial foreign investment and is designed to establish a new value-added industry connected to agriculture and food security.

  • Blencowe advances defence applications for Orom-Cross graphite as premium offtake deal progresses

    Blencowe advances defence applications for Orom-Cross graphite as premium offtake deal progresses

    Blencowe Resources (LSE:BRES) has reported further progress in developing high-value applications for graphite from its Orom-Cross project in Uganda, with testing indicating potential uses in advanced defence technologies and a premium offtake arrangement moving towards commercialisation.

    Work conducted with partner American Energy Technologies has demonstrated the suitability of Orom-Cross graphite for specialist anti-radar and electromagnetic interference shielding coatings. These materials could be applied to unmanned aerial vehicles and other defence platforms where reducing radar signatures and controlling electromagnetic interference are important operational requirements.

    Blencowe is currently working with three European UAV manufacturers as it seeks to move these applications from technical testing towards commercial adoption. One potential offtake relationship has reached an advanced commercial stage and involves ultra-fine M635 material grading 97% total graphitic carbon.

    Indicative pricing for this specialist graphite product is close to $20,000 per tonne, substantially increasing the potential value compared with conventional graphite concentrate. Orom-Cross material is already being incorporated into high-fidelity demonstration projects as part of the ongoing evaluation process.

    The latest developments support Blencowe’s strategy of increasing the proportion of production directed towards specialist, higher-margin graphite markets. The company has previously undertaken testing for aerospace and rocket propulsion applications and is now seeking to convert successful technical validation into commercial demand.

    Non-binding offtake commitments have already exceeded the planned 20,000 tonnes per annum of production envisaged for Phase 1 at Orom-Cross. Blencowe is continuing to pursue additional agreements as it looks towards a potential Phase 2 production target of 70,000 tonnes per annum.

    Alongside its commercial discussions, the company is progressing project-level financing options intended to support the development of Orom-Cross while limiting dilution for existing shareholders. Establishing a broader portfolio of premium offtake agreements could strengthen those funding discussions and reinforce the project’s position within Western-aligned graphite supply chains.

    Blencowe is targeting markets seeking alternatives to Chinese graphite supplies, particularly across defence, aerospace and advanced materials industries where supply security and specialist product characteristics can command higher prices.

    The company’s broader financial profile remains challenging. Blencowe currently generates no revenue and continues to report recurring losses, while operating cash flow has deteriorated. Technical indicators are also bearish, with the shares trading below key moving averages and MACD remaining negative.

    A relatively low-leverage balance sheet provides some support, although negative earnings and the absence of a dividend continue to limit the usefulness of conventional valuation measures.

    More about Blencowe Resources Plc

    Blencowe Resources Plc is a London-listed resources company developing the 100%-owned Orom-Cross Graphite Project in Uganda.

    The company’s strategy centres on producing high-quality graphite concentrates for specialist and higher-value applications, with a particular focus on Western markets seeking non-Chinese sources of critical raw materials. Orom-Cross is being positioned to serve industries including defence, aerospace and advanced materials while helping customers diversify geopolitical and supply-chain exposure.

  • Predator Oil & Gas secures rig for Snowcap-3 as Trinidad and Morocco drilling advances

    Predator Oil & Gas secures rig for Snowcap-3 as Trinidad and Morocco drilling advances

    Predator Oil & Gas (LSE:PRD) has signed a rig contract with Star Valley Drilling for Rig 205 to drill the Snowcap-3 well in Trinidad, marking another step in the company’s planned exploration and appraisal programme across Trinidad and Morocco.

    Drilling at Snowcap-3 is scheduled to begin after the MOU-6 well in Morocco has been completed. Predator has arranged the sequence to allow management to maintain effective operational oversight as drilling activity progresses across the two jurisdictions.

    Snowcap-3 will primarily target the Herrera #8 Sand. Information obtained from Snowcap-2ST-1, Snowcap-1 and Rochard-1 indicates an extrapolated oil column of approximately 600 feet within the target interval.

    The new well is designed to test the reservoir at a structurally higher position than previous drilling. It will also investigate the Herrera #1 Sand as a secondary objective, again at a higher structural position than previously evaluated.

    Preparations for the drilling campaign are already well advanced. Predator said the required rig arrangements, environmental approvals, civil engineering works, technical programmes and service contractors are in place, positioning the company to move into an intensive period of drilling activity.

    Alongside its immediate drilling plans, Predator is evaluating additional opportunities that could broaden the commercial potential of its portfolio. In Trinidad, the company is considering whether surplus wellhead gas could be converted into electricity to supply hydrogen fuel cells and data centres.

    In Morocco, Predator is exploring the possibility of a technical collaboration focused on semi-conventional biogenic gas. Such a programme could provide additional development options for its gas assets while helping to reduce technical uncertainty ahead of future appraisal activity.

    The company’s wider financial position remains challenging. Predator continues to record substantial losses and cash outflows despite a recent improvement in revenue generation. Technical indicators are also moderately negative, with the shares trading below important moving averages and MACD remaining negative.

    Conventional valuation metrics provide limited support while Predator remains loss-making, resulting in a negative price-to-earnings ratio.

    More about Predator Oil & Gas Holdings Plc

    Predator Oil & Gas Holdings Plc is a Jersey-based oil and gas company with exploration and hydrocarbon production interests in Trinidad and Morocco.

    Its portfolio includes onshore gas assets in Morocco that could support compressed natural gas or micro-LNG developments. In Trinidad, the company is focused on onshore oil opportunities where production enhancement programmes and infill drilling could potentially be undertaken under favourable fiscal terms.