Category: Top Story

  • EasyJet Shares Slide as Wider Loss Forecast Signals Pressure from Middle East Tensions

    EasyJet Shares Slide as Wider Loss Forecast Signals Pressure from Middle East Tensions

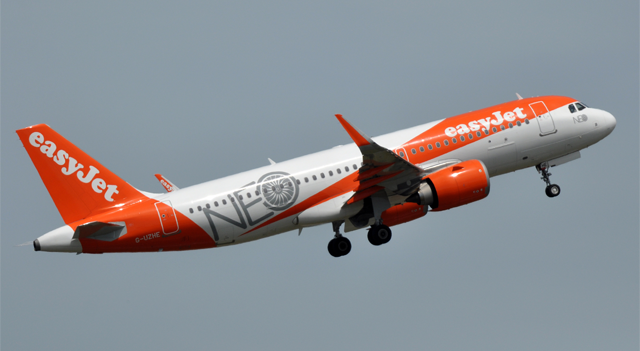
    EasyJet (LSE:EZJ) shares dropped more than 3% on Thursday after the airline warned of a larger-than-expected first-half loss, citing geopolitical tensions in the Middle East and volatile fuel costs as key headwinds heading into the peak summer season.

    In a trading update ahead of its half-year results, the company said it expects a headline loss before tax of between £540 million and £560 million for the six months to 31 March. This guidance is around 7% below analyst expectations at the midpoint, reflecting a £25 million increase in fuel costs during March and an additional £30 million in legal provisions.

    Chief executive Kenton Jarvis said demand remained “positive” following a strong Easter period but acknowledged that overall performance has weakened compared with last year, “impacted by the conflict in the Middle East and the competitive environment in some markets.”

    The airline noted that rising regional instability has led to a shorter booking window and “lower than normal forward visibility,” making demand trends harder to predict. While easyJet has hedged around 70% of its summer fuel requirements at $706 per metric tonne, the remaining exposure leaves it vulnerable to spot prices currently near $1,500.

    The company added that every $100 movement in fuel prices now translates into an estimated £40 million impact on second-half costs.

    Despite the negative share reaction, easyJet highlighted solid operational metrics, including a 90% load factor, up two percentage points year on year, and a 22% increase in customers within its holidays division. However, analysts at Morgan Stanley noted that pricing recovery is being limited by shorter booking cycles, with third-quarter revenue per available seat kilometre currently trending slightly lower and 63% of seats sold.

    “easyJet’s financial strength from our investment grade balance sheet and £4.7 billion of liquidity mean we are well placed to navigate current geopolitical challenges while remaining focused on our medium term target,” Jarvis added.
  • Tesco Boosts Profit and Cash Flow as Value Strategy Drives Market Share Gains

    Tesco Boosts Profit and Cash Flow as Value Strategy Drives Market Share Gains

    Tesco (LSE:TSCO) reported solid performance for the 53 weeks to 28 February 2026, with group sales excluding fuel rising 4.6% to £66.6 billion. Adjusted operating profit increased to £3.15 billion on a comparable 52-week basis, while statutory operating profit climbed 10.1%. Diluted earnings per share saw strong growth, and free cash flow improved to nearly £2 billion, enabling a higher dividend despite a rise in net debt following earlier banking disposals.

    Chief executive Ken Murphy said continued investment in price, quality, and service during a challenging cost-of-living environment and geopolitical uncertainty has helped Tesco achieve its highest UK market share in more than a decade. Progress under the company’s “Save to Invest” programme, alongside expanded value offerings and growth in rapid delivery, has supported performance. Tesco also highlighted its longer-term strategy focused on strengthening its food leadership, expanding everyday services, and deepening supplier partnerships, while continuing to invest in staff through wage increases and bonuses.

    The company’s outlook reflects generally stable financial performance, although there are some pressures on revenue growth and cash flow. Technical indicators point to positive momentum, and valuation appears reasonable. Management commentary remains upbeat, supported by improved profit guidance and a significant share buyback programme aimed at enhancing shareholder returns.

    More about Tesco plc

    Tesco plc is one of the largest grocery and general merchandise retailers in Europe, operating supermarkets, convenience stores, and online platforms across the UK, Ireland, and Central Europe. In addition to its core food retail business, the group operates wholesale distribution through Booker and offers a range of complementary services, including clothing, mobile, pharmacy, and financial products, serving a broad base of value-focused consumers.

  • Rentokil Initial Delivers Steady Q1 Growth as New CEO Sets Direction

    Rentokil Initial Delivers Steady Q1 Growth as New CEO Sets Direction

    Rentokil Initial (LSE:RTO) reported revenue of $1.68 billion for the first quarter of 2026, marking a 4.3% increase at constant currency, with organic growth of 3.4%. Performance was largely supported by its North American pest control division alongside solid contributions from international markets. Newly appointed CEO Mike Duffy pointed to strong workforce engagement and expressed confidence that the group remains on course to meet full-year expectations despite geopolitical headwinds.

    North America generated $995 million in revenue, delivering 3.9% organic growth. This was underpinned by effective pricing strategies, improved sales execution, and early seasonal demand within Business Services. Employee retention improved throughout the period, while customer retention levels held steady. Internationally, revenue rose 4.1% at constant currency, with 2.8% organic growth. Gains across Europe, Latin America, and the UK & Sub-Saharan Africa helped offset weaker conditions in the Pacific and MENAT regions. The company also remained active on acquisitions, completing nine smaller deals that together contributed around $19 million in annualised revenue prior to acquisition.

    The group’s outlook is supported by consistent revenue expansion, solid free cash flow generation, and improving leverage, alongside guidance focused on margin improvement through operational efficiencies. However, this is balanced by a relatively elevated valuation, reflected in a high price-to-earnings ratio, and mixed short-term technical signals, including a negative MACD despite a broader upward trend.

    More about Rentokil Initial

    Rentokil Initial is a global provider of pest control, hygiene, and wellbeing services, with a major presence in North America and a broad international footprint spanning Europe, Latin America, the UK & Sub-Saharan Africa, the Pacific, and MENAT regions. The company focuses on recurring service contracts across both commercial and residential markets, delivering pest management and hygiene solutions as part of its core offering.

  • Great Western Mining Advances Nevada Tungsten Project with Drilling Contractor Appointment

    Great Western Mining Advances Nevada Tungsten Project with Drilling Contractor Appointment

    Great Western Mining (LSE:GWMO) has appointed Major Drilling America to undertake a reverse circulation drilling programme at its wholly owned Defender-Pine Crow tungsten project in Mineral County, Nevada. The contract marks a key step in the company’s plan to establish a tungsten resource alongside its existing portfolio of copper, gold, and silver assets.

    The campaign will cover approximately 7,000 feet of drilling and is scheduled to begin in July, following preparatory groundworks in May. The programme is designed to support a maiden mineral resource estimate for Defender-Pine Crow, which the company is targeting for completion by late 2026. In addition, drilling will assess the extent and continuity of mineralisation across the Defender and Pine Crow zones, as well as the nearby M2 trend, potentially increasing the project’s overall scale and strategic value.

    Company management noted that the drilling forms part of a wider exploration effort that includes geological mapping, geophysical surveys, and additional channel sampling. These parallel initiatives aim to improve understanding of the broader mineralised system and strengthen the company’s positioning within the critical minerals space as the tungsten opportunity develops.

    Despite operational progress, the company’s financial profile remains a limiting factor, characterised by a lack of revenue, ongoing losses, and steady cash burn, albeit with relatively low debt levels. From a market standpoint, technical indicators are somewhat encouraging, with the share price holding above key averages and showing modest upward momentum. However, valuation remains difficult to justify due to negative earnings and the absence of dividend yield data.

    More about Great Western Mining

    Great Western Mining Corporation is an exploration and development company focused on strategic mineral assets across several fully owned claim groups in Mineral County, Nevada, a mining-friendly region in the United States. While maintaining exposure to copper, gold, and silver through projects such as Huntoon and tailings reprocessing initiatives, the company is increasingly prioritising tungsten as a critical mineral within its growth strategy.

  • Union Jack Oil Flags Minor Timing Slip for Oklahoma Crossroads Well

    Union Jack Oil Flags Minor Timing Slip for Oklahoma Crossroads Well

    Union Jack Oil (LSE:UJO) has announced a slight postponement to the spud date for the Crossroads well in southern Oklahoma. The delay follows maintenance requirements identified by operator Reach Oil and Gas Company Inc., with drilling now expected to begin before the end of April 2026, suggesting only limited disruption to the overall schedule.

    Union Jack retains a 43% stake in the project and has already covered its share of drilling expenditures using available cash. This confirms the well is fully funded, and the revised timeline is not expected to place pressure on the company’s short-term finances or alter its broader plan to strengthen its onshore presence in the United States.

    From a financial perspective, the group continues to benefit from a debt-free balance sheet and consistent profitability since 2022. However, performance has been weighed down by a sharp decline in profitability during 2024, alongside uneven and negative free cash flow trends. Market indicators point to near-term momentum, though conditions appear overbought, and the longer-term trend remains less robust. Valuation metrics are also challenging to assess, given the absence of a meaningful P/E ratio and dividend yield.

    More about Union Jack Oil

    Union Jack Oil is an AIM-listed oil and gas company engaged in onshore production, development, exploration, and investment across the UK and the United States. Its strategy centers on conventional hydrocarbon projects, with stakes in a range of drilling and producing assets, aiming to build a portfolio of reliable, cash-generating operations within established energy regions.

  • European Stocks Trade Mixed as Earnings Diverge and Iran-U.S. Talks Loom: DAX, CAC, FTSE100

    European Stocks Trade Mixed as Earnings Diverge and Iran-U.S. Talks Loom: DAX, CAC, FTSE100

    European equities showed little clear direction on Wednesday, as investors assessed a mixed batch of corporate earnings while also preparing for a potential new round of face-to-face negotiations between the United States and Iran, which could begin as early as this weekend.

    Reports suggest Washington has outlined two fresh conditions ahead of any renewed dialogue. According to Israel Hayom, the U.S. is seeking a full and unrestricted reopening of the Strait of Hormuz and continues to emphasize a reciprocal approach in negotiations.

    On the macroeconomic front, updated data from France’s statistics agency INSEE showed that harmonized consumer price inflation for March came in slightly higher than initially estimated.

    EU-harmonized inflation reached 2.0% for the month, above the preliminary reading of 1.9% and up from 1.1% in February.

    Domestic consumer price inflation in France was confirmed at 1.7%, rising from 0.9% the previous month and marking the fastest pace of increase since August 2024.

    Meanwhile, Eurostat reported that industrial production across the eurozone rose 0.4% in February compared with January.

    In equity markets, France’s CAC 40 was down 0.6%, while the UK’s FTSE 100 hovered around flat levels and Germany’s DAX edged up 0.1%.

    Hermes International (EU:RMS) dropped 10% after reporting slower first-quarter sales growth.

    Stellantis (BIT:STLAM) climbed 3.4% after announcing a 12% increase in global vehicle shipments for the first quarter.

    ASML (EU:ASML) gained 1.7% after lifting its 2026 sales outlook, supported by first-quarter results that exceeded expectations.

    Aegon (EU:AGN) declined nearly 2% following an agreement to sell its UK operations to Standard Life in a deal valued at £2 billion.

    Rank Group (LSE:RNK) surged 11% in London after raising its full-year underlying operating profit guidance, supported by a 5% year-on-year increase in fiscal third-quarter net gaming revenue.

    Antofagasta (LSE:ANTO) rose 3.2%. Despite reporting a decline in first-quarter copper output, the company said it expects production to increase progressively over the rest of the year.

  • European Stocks Flat as Trump Hints at Renewed Iran Talks: DAX, CAC, FTSE100

    European Stocks Flat as Trump Hints at Renewed Iran Talks: DAX, CAC, FTSE100

    European equities traded in a narrow range on Wednesday, as investors weighed fresh signals from Washington suggesting a renewed push toward ending the conflict with Iran.

    By 07:09 GMT, the pan-European STOXX 600 was marginally higher by 0.1%, while Germany’s DAX and the UK’s FTSE 100 each gained around 0.2%.

    France’s CAC 40 underperformed, falling 0.6%, dragged lower in part by a sharp decline in Hermès (EU:RMS), which reported slower quarterly sales growth amid weaker demand linked to the Iran conflict.

    Market sentiment found some support from ASML (EU:ASML), Europe’s most valuable listed firm. The company raised its full-year sales outlook, benefiting from strong demand tied to the artificial intelligence boom. Major chipmakers, including TSMC and Intel, continue to invest heavily in ASML’s technology to expand their AI capabilities.

    On the geopolitical front, U.S. President Donald Trump indicated that talks with Iran could resume within the next two days, following initial negotiations held in Pakistan over the weekend. Vice President JD Vance, who led the U.S. delegation in Islamabad, also struck an optimistic tone regarding progress.

    Despite this, the U.S. has maintained a blockade on Iranian ports. Officials said maritime trade to and from the country has effectively been halted after the latest round of talks failed to deliver an immediate ceasefire agreement, although expectations for a quick resolution had already been low.

    The restrictions have raised concerns about oil supply disruptions through the Persian Gulf, where flows have already slowed significantly. However, reports suggest that more than 20 commercial vessels have recently passed through the Strait of Hormuz, hinting at some easing in transit conditions.

    Oil prices remained below the $100 mark but stayed elevated compared with pre-conflict levels. Brent crude rose 0.3% to $95.10 a barrel, while U.S. West Texas Intermediate slipped 0.2% to $91.12.

  • Standard Life to Acquire Aegon UK in £2bn Deal to Build Retirement Leader

    Standard Life to Acquire Aegon UK in £2bn Deal to Build Retirement Leader

    Standard Life (LSE:SDLF) has agreed to acquire Aegon UK, the British pensions and insurance arm of Aegon, in a £2.0 billion transaction comprising cash, debt, and shares. As part of the deal, Aegon will become a 15.3% strategic shareholder and asset management partner. The combined business is expected to form the UK’s largest retirement savings and income platform, serving around 16 million customers and managing approximately £480 billion in assets, with completion targeted for late 2026 pending regulatory approval.

    The acquisition will significantly strengthen Standard Life’s market position, lifting it to number two in both workplace and retail pensions. The deal adds roughly £160 billion in assets and 3.8 million customers, while enhancing the group’s adviser platform, distribution network, and digital capabilities. Management expects the transaction to accelerate its transition toward capital-light, fee-based revenue streams, generate around £0.8 billion in net synergies, and support growth in operating cash flow and IFRS profitability. The group also expects to remain within its Solvency II leverage parameters, potentially improving long-term shareholder returns and competitive positioning in the expanding defined contribution and retail savings markets.

    From an investment perspective, the outlook is supported by positive strategic developments and encouraging signals from recent corporate activity, reflecting progress in scale and financial resilience. However, mixed underlying financial performance and valuation concerns—linked to profitability challenges—temper the overall picture. Technical indicators suggest a generally positive trend, offering some additional support for the shares.

    More about Standard Life plc

    Standard Life plc is a UK-based financial services provider specialising in retirement savings, pensions, and income solutions. The group offers workplace and retail pension platforms, annuities, and investment products, serving both corporate clients and individual savers across the UK retirement market.

  • Saga Delivers Profit Growth and Cuts Debt as Travel and Insurance Lead Recovery

    Saga Delivers Profit Growth and Cuts Debt as Travel and Insurance Lead Recovery

    Saga (LSE:SAGA) reported a strong set of results, with underlying revenue rising 11% to £654.6 million and trading EBITDA up 16%. Underlying profit before tax increased 19% to £44.2 million, while the group returned to statutory profitability with a £2.1 million profit. Performance was driven by solid contributions from both its Travel and Insurance divisions. The company also significantly improved cash generation, reducing net debt by 16% to £499.5 million and lowering leverage to 3.7x, keeping it on track to meet its long-term targets through to 2030.

    During the period, Saga completed a refinancing of its corporate debt through a long-term facility and sold its Insurance Underwriting business to Ageas. It also introduced a new partnership model for motor and home insurance, removing underwriting exposure and simplifying its broking operations. Operationally, the group aligned leadership across its Cruise and Holidays businesses, expanded its river cruise offering, and strengthened its partnerships through new financial products and publishing initiatives. Management expects further improvements in profit and cash flow over 2026/27 as the Ageas partnership becomes fully integrated and leverage continues to decline.

    Forward bookings in both ocean and river cruises remain strong, while the group noted limited direct exposure to geopolitical tensions in the Middle East and confirmed that near-term foreign exchange and fuel costs are fully hedged. Saga reiterated its confidence in delivering at least £100 million in annual underlying profit before tax and reducing leverage to below two times by January 2030, supported by its repositioned, lower-risk business model focused on the over-50s demographic.

    From an investment standpoint, the outlook reflects improving operational momentum, positive technical signals, and meaningful progress in reducing debt. However, these gains are balanced by structurally weak profitability in reported figures and still-elevated leverage levels. Valuation remains less compelling due to the negative price-to-earnings profile and the absence of a dividend yield.

    More about Saga plc

    Saga plc is a UK-based provider of travel, insurance, and financial services tailored to customers aged over 50. Its operations span ocean and river cruises, holiday packages, and motor and home insurance products, increasingly delivered through partnership models. The company focuses on offering premium, tailored experiences and services to its core demographic, supported by strong brand recognition and customer loyalty.

  • Barratt Redrow Reaffirms Guidance as Forward Sales Strengthen and Cash Position Builds

    Barratt Redrow Reaffirms Guidance as Forward Sales Strengthen and Cash Position Builds

    Barratt Redrow (LSE:BTRW) reported a robust third-quarter performance, supported by steady private reservation activity and an 11.2% increase in forward sales by value. The group has already secured sales for 94% of its expected FY26 completions, leaving it well positioned to deliver between 17,200 and 17,800 homes for the year, alongside adjusted profit in line with market forecasts. Although quarterly completions declined year-on-year due to a strong prior period comparison, the company continues to manage its pipeline carefully, scaling back land approvals and investment in response to ongoing geopolitical and cost uncertainties.

    The integration of Redrow is progressing as planned, with £100 million in cost synergies now confirmed. Barratt Redrow also maintained its five-star customer satisfaction rating and is targeting a year-end net cash position of £550 million to £650 million, supported by reduced land spend and continued share buybacks. These factors underline the group’s disciplined capital approach and operational resilience.

    From an investment standpoint, the outlook is underpinned by a strong balance sheet, consistent revenue performance, and an attractive valuation, including a price-to-earnings ratio of 13.2 and a dividend yield of 6.68%. However, these strengths are tempered by weak technical signals, with the share price trading below key moving averages and showing deeply oversold momentum. Recent pressure on cash flow also adds a note of caution.

    More about Barratt Redrow

    Barratt Redrow plc is one of the UK’s leading housebuilders, operating under the Barratt Homes, David Wilson Homes, and Redrow brands. The group delivers private and affordable housing developments nationwide, supported by a substantial land portfolio, in-house timber-frame manufacturing, and an expanding network of sales outlets.