Category: Top Story

  • FT ranks UK’s fastest-growing companies

    FT ranks UK’s fastest-growing companies

    The Financial Times has published a new report which ranks the fastest-growing companies in the UK. Collaborating with Statista, they have ranks the companies which grew the fastest between 2022 and 2025. This was the period when the country was still reckoning with the effects of the Covid-19 pandemic, as well as the war in Ukraine which brought about an energy crisis.

    The report ranks 150 companies across a wide spread of sectors. The most heavily represented category is Fintech, financial services and insurance, with 25 companies listed. Next is IT and software, with 25.

    Top of the FT’s list is Healf, an online retailer of wellness products for the mind and body, which had an compound annual growth rate of 669 per cent during the period. Second ranked is Energy group Fuse Energy, with a 455 per cent growth rate. Third is medical cannabis company Mamedica, at 409 per cent.

    Pathos (LSE:NEWS) is recognised by the FT as the fastest growing advertising/marketing company in the UK, with 56 per cent growth during the period. It is a technology-enabled public relations company that is number one in their field.

    Prime Minister Andy Burnham has targeted “good growth in every postcode”, while Chancellor John Healey says it is his mission “to make Great Britain, Growth Britain again — with more investment, more innovation and more jobs”. The companies in the FT’s list will be crucial to the success of this strategy.

    Click here to read the FT’s article and see the full rankings.

  • US Stock Futures Advance as Markets Weigh Micron Results and Lower Treasury Yields: Dow Jones, S&P, Nasdaq, Wall Street

    US Stock Futures Advance as Markets Weigh Micron Results and Lower Treasury Yields: Dow Jones, S&P, Nasdaq, Wall Street

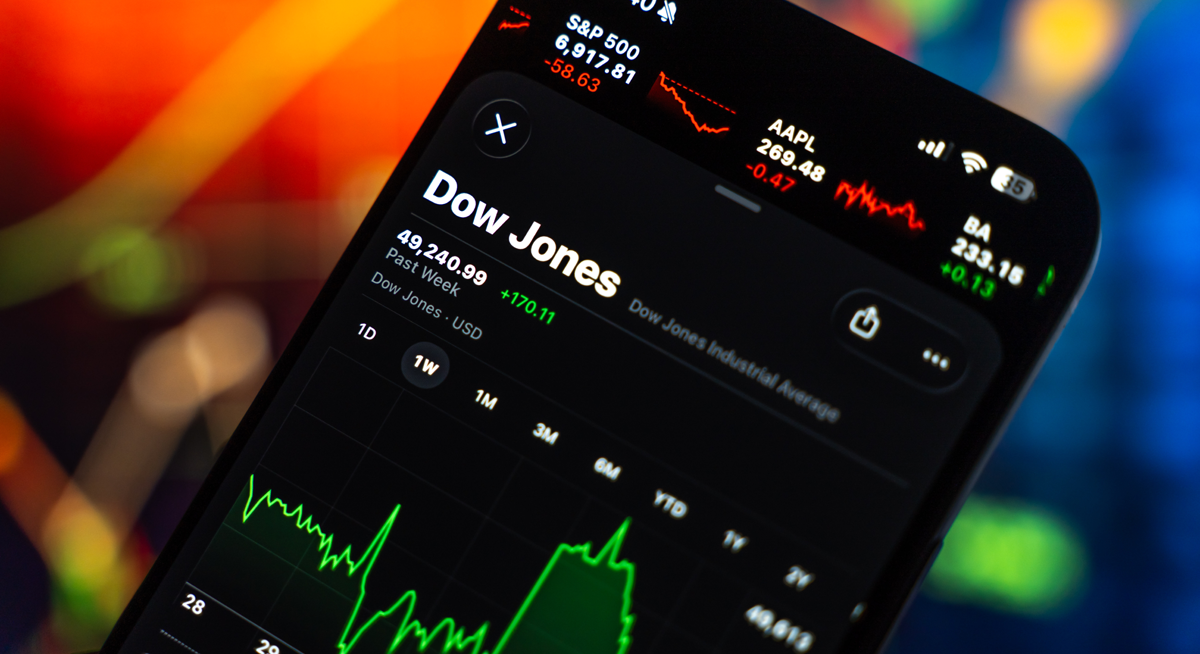
    US stock futures traded higher on Thursday as investors began the fourth quarter assessing a pullback in Treasury yields, Micron Technology’s latest results and upcoming US employment data.

    At 08:33 ET (12:33 GMT), S&P 500 futures were up 0.4%, Dow futures gained 0.5% and Nasdaq 100 futures advanced 0.6%.

    Treasury yields eased on Thursday morning following recent increases in the US bond market. Attention was also turning to September employment figures, which could provide further information on labour market conditions and expectations surrounding future Federal Reserve interest-rate decisions.

    Micron Reports Earnings Above Expectations

    Micron Technology (NASDAQ:MU) reported adjusted earnings of $33.42 per share for its fiscal fourth quarter, exceeding market expectations of $31.16.

    The memory chipmaker also forecast adjusted earnings of $38.15 per share, plus or minus $1.00, for the current quarter. That compared with market expectations of $36.02.

    Micron shares nevertheless traded slightly lower in premarket trading. The company indicated that gross margins would be slightly softer during the current quarter and forecast higher operating expenses for fiscal 2027.

    The results came as markets continued to assess demand associated with artificial intelligence and its implications for semiconductor companies. Chip stocks in Japan, South Korea and Taiwan also advanced during Thursday’s session.

    Technology stocks had experienced volatility during September amid concerns surrounding the development and safety of artificial intelligence, while several organisations in the sector have called for a slower pace of AI development.

    Investors Await Nike Quarterly Results

    Nike is scheduled to release its quarterly results after Thursday’s market close, with investors monitoring the company’s performance under CEO Elliott Hill.

    According to the supplied market data, Nike shares have declined by more than 44% since the beginning of the year.

    Wall Street Ends September With Mixed Performance

    The S&P 500 and Dow Jones Industrial Average declined on Wednesday, while the Nasdaq Composite finished higher as Treasury yields remained elevated.

    US Personal Consumption Expenditures inflation for August came in below market expectations. Treasury yields initially remained elevated following the data before easing on Thursday morning.

    For September, the S&P 500 declined 0.5% and the Dow fell 4.3%, while the Nasdaq gained 1.9%.

    Over the third quarter, both the S&P 500 and Nasdaq recorded their second consecutive quarterly gains and their fifth advances in six quarters. The Dow declined during the July-to-September period.

    “Q3 was a difficult one for markets, as the global economy grappled with a fresh inflationary impulse and the resumption of a globally synchronized rate hiking cycle,” Deutsche Bank analysts said in a note.

  • European Stocks Fall as Bond Yields, French Budget Plans and Inflation Remain in Focus: DAX, CAC, FTSE100

    European Stocks Fall as Bond Yields, French Budget Plans and Inflation Remain in Focus: DAX, CAC, FTSE100

    European stocks moved lower at the start of October and the fourth quarter on Thursday, as investors assessed higher sovereign bond yields, fiscal developments in France and continued energy-related inflation pressures.

    The pan-European STOXX 600 fell 1.4%, reaching its lowest level in more than three months. France’s CAC 40 declined 1.4%, Germany’s DAX lost 0.7% and the UK’s FTSE 100 fell 1.6%.

    Government bond yields have risen in recent weeks amid concerns over inflation and sovereign borrowing requirements.

    French Budget Plans Draw Attention as Bond Yields Rise

    Germany’s 10-year government bond yield, a benchmark for the euro area, increased by one basis point after reaching 3.6526% earlier in the week, its highest level since June 2009.

    France’s 10-year government bond yield reached its highest level since 2002 ahead of Prime Minister Sébastien Lecornu’s expected presentation of the government’s 2027 draft budget later in the session.

    The proposed budget targets €54 billion in spending reductions as the government seeks to address a deficit projected at 5.4% of gross domestic product.

    Higher borrowing costs can increase debt-servicing expenses for governments, companies and households, making sovereign bond markets an important focus for investors.

    Energy Prices and Inflation Remain in Focus

    Developments in the Middle East also remained a focus for European markets, with negotiations between the United States and Iran aimed at ending the seven-month conflict yet to produce an agreement.

    Crude oil and European natural gas prices remained elevated, contributing to concerns about the impact of energy costs on inflation.

    Preliminary September consumer price data showed inflation accelerating more than expected in several European economies, including France, Italy and Spain, with higher petrol, diesel and wholesale gas prices contributing to the increases.

    The inflation readings may influence expectations for European Central Bank monetary policy, although future interest-rate decisions will depend on incoming economic data and the ECB’s assessment of the inflation outlook.

    Markets Assess Softer US Economic Data

    Investors were also assessing softer-than-expected US economic data released during the previous session.

    August US Personal Consumption Expenditures inflation came in below market expectations, while European markets continued to contend with higher regional inflation readings, energy prices and elevated bond yields.

    Among individual stocks, Sanofi (EU:SAN) rose as much as 3.6% after the French pharmaceutical company agreed to pay Regeneron $1 billion upfront and potentially up to a further $7 billion as part of an expansion of their partnership.

  • AIC Investment Company Showcase 2026 Brings Investment Trust Opportunities Directly to Private Investors

    AIC Investment Company Showcase 2026 Brings Investment Trust Opportunities Directly to Private Investors

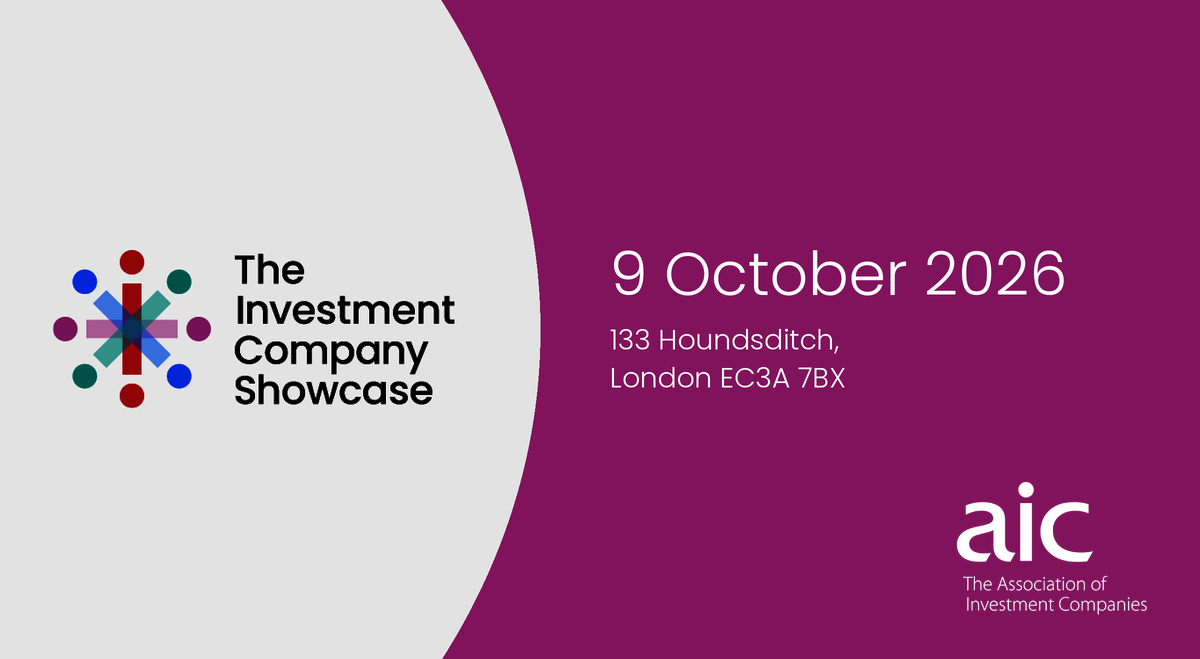
    The Association of Investment Companies (AIC) is bringing together more than 30 leading investment trust managers for its Investment Company Showcase 2026, giving private investors the opportunity to hear directly from the professionals managing investment companies across a broad range of markets and sectors.

    Taking place on Friday 9 October 2026 at Convene, 133 Houndsditch in London, the Showcase will bring together more than 500 private investors, with the event also being live streamed for those unable to attend in person.

    With investment trusts offering exposure to everything from global equities and emerging markets to infrastructure, private assets and specialist sectors, the event provides an opportunity for investors to explore different approaches to building and diversifying portfolios.

    Three programmes, one investment-focused day

    A key feature of this year’s Showcase is its three simultaneous conference programmes, allowing attendees to build a personalised agenda around the areas of investment that interest them most.

    The programme covers a wide range of themes, including opportunities in Japan, emerging markets, infrastructure and Europe, alongside insights from some of the investment managers responsible for running established investment companies.

    The format also gives private investors the chance to hear directly from fund managers rather than relying solely on published performance figures or investment commentary.

    For investors researching the investment trust sector, that direct access can provide a useful opportunity to understand how managers are approaching markets, where they are finding opportunities and how individual trusts are positioned.

    Leading names across the investment trust sector

    The Showcase has attracted support from a number of major investment businesses, including Aberdeen, Alliance Witan, Allianz Global Investors, Baillie Gifford, BlackRock, Columbia Threadneedle, Fidelity International, Greencoat UK, JPMorgan Asset Management, Liontrust and Schroders.

    The exhibitor line-up also includes investment companies and sector specialists covering a broad spectrum of strategies.

    Among them are Caledonia Investments, which invests across public companies, private capital and funds, Law Debenture Investment Trust, with its long history of income and capital growth, and Utilico Emerging Markets Trust, which focuses on essential infrastructure, utilities and related businesses across emerging markets.

    The breadth of the line-up highlights the variety available within the investment company sector, from global equities and income strategies to emerging markets, infrastructure and private markets.

    Direct access to fund managers

    The Showcase also reflects the growing importance of communication between investment companies and their underlying shareholders.

    The AIC has already been publishing a series of interviews ahead of the event, featuring fund managers including Job Curtis, Olivia Markham, Masaki Taketsume and Rhys Davies. These interviews provide investors with an early look at some of the themes and investment approaches that will feature at the Showcase.

    For private investors, being able to hear managers explain their strategies in their own words can add valuable context when researching investment companies and considering how different strategies might fit within a wider portfolio.

    A broad range of investment opportunities

    Investment trusts cover a particularly wide range of investment areas, making events such as the Showcase relevant to investors with very different objectives.

    Some investors may be looking for income and dividend growth, while others may be interested in global growth, emerging markets, infrastructure, private companies or specialist sectors.

    The AIC’s Showcase is designed around that breadth, giving attendees the ability to move between different sessions and focus on the areas most relevant to their own research.

    With more than 30 investment trust managers taking part, the event also provides an opportunity to compare different approaches to investing across markets and asset classes.

    Bringing investors and investment companies together

    The Investment Company Showcase 2026 comes at a time when the investment trust sector continues to offer private investors access to a diverse range of investment strategies through the listed market.

    By bringing fund managers and investors together in one venue, while also providing a live-streaming option, the AIC is creating a forum where investors can ask questions, explore new ideas and gain a better understanding of the companies and strategies available to them.

    For anyone researching investment companies, the Investment Company Showcase 2026 offers a chance to hear from a wide selection of managers and explore the opportunities available across the sector.

    The event takes place on 9 October 2026, with registration opening at 09:15 and the Showcase running from 10:00 to 16:30. Private investors can use the code SHOW26 to gain free entry.

    Register Here – https://www.theaic.co.uk/the-investment-company-showcase-2026
  • Market Open: Filtronic SpaceX Order, PHP Rental Growth

    Market Open: Filtronic SpaceX Order, PHP Rental Growth

    FTSE 100 falls as bond yields rise, while Filtronic wins a SpaceX order, PHP reports rental growth and Brent crude advances.

    Market Overview

    The FTSE 100 opened lower, falling 1.74 per cent to 10,421.16 as rising global bond yields weighed on UK equities. In Europe, the Euronext 100 declined 1.18 per cent to 1,862.71, while Germany’s DAX fell 0.91 per cent to 24,970.78 amid concerns over energy-driven inflation. On Wall Street, the Nasdaq closed higher at 26,861.06, while the S&P 500 closed lower at 7,651.54.

    Commodity markets were mixed, with copper, gold and natural gas lower while Brent crude advanced as Middle East supply risks remained in focus. Bitcoin strengthened slightly against sterling. The US dollar, Swiss franc and Australian dollar also strengthened against the pound, while the euro and Japanese yen weakened, as markets continued to assess elevated bond yields, inflation pressures and geopolitical uncertainty.


    Market Numbers

    FTSE 100: Down (-1.74%), 10,421.16
    Euronext 100: Down (-1.18%), 1,862.71
    DAX: Down (-0.91%), 24,970.78
    NASDAQ: Up, 26,861.06
    S&P 500: Down, 7,651.54


    In the Headlines

    SpaceX order – Filtronic (LSE:FTC)
    Filtronic secured a $68.1 million follow-on order from SpaceX for its Cerus E-band gallium nitride solid-state power amplifier units. The contract is expected to be delivered predominantly during the 2028 financial year, providing additional revenue visibility.

    Rental growth – Primary Health Properties (LSE:PHP)
    Primary Health Properties secured a £5.8 million increase in rental income as the healthcare property group completed the integration of Assura. The update highlights continued rental growth across the enlarged portfolio following the combination.


    Currencies (vs GBP)

    USD: Up (+0.21%), $1.3236
    CHF: Up (+0.06%), Fr.1.1078
    EUR: Down (-0.03%), €1.1714
    JPY: Down (-0.34%), ¥209.7015
    AUD: Up (+0.11%), $1.9077
    Bitcoin (BTC/GBP): Up, £63,113.99


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Down

  • Wall Street Futures Mixed Ahead of Nike Results and US Economic Data: Dow Jones, S&P, Nasdaq

    Wall Street Futures Mixed Ahead of Nike Results and US Economic Data: Dow Jones, S&P, Nasdaq

    US equity futures traded in different directions on Thursday as markets prepared for the opening session of the fourth quarter, with Micron’s (NASDAQ:MU) revenue outlook, upcoming Nike (NYSE:NKE) results and US economic data among the main areas of focus.

    At 03:34 ET (07:34 GMT), futures linked to the Dow Jones Industrial Average were down 219 points, or 0.4%. S&P 500 futures edged 4 points, or 0.1%, higher, while Nasdaq 100 futures gained 161 points, or 0.5%.

    Wall Street’s major indices also ended the previous session mixed. The S&P 500 and Dow declined, while the Nasdaq Composite closed higher.

    Treasury yields rose despite August US personal consumption expenditures inflation coming in below market expectations. Investors are now awaiting September employment figures for further indications about the Federal Reserve’s interest-rate outlook.

    For September, the S&P 500 lost 0.45% and the Dow declined 4.29%, while the Nasdaq advanced 1.86%. The S&P 500 and Nasdaq both recorded their second consecutive quarterly gains, while the Dow finished the July-to-September quarter lower.

    Micron Forecast Exceeds Market Expectations

    Micron shares gained in extended trading after the semiconductor company issued a quarterly revenue forecast above market expectations.

    The company also reported an increase in customer commitments under long-term supply agreements, which reached $32 billion compared with $22 billion in June.

    Investment in artificial intelligence infrastructure has increased demand for memory chips used in data centres. Micron’s customers include Nvidia.

    According to the supplied figures, Micron shares have more than tripled since the beginning of 2026.

    Nike Prepares to Release Latest Results

    Nike shares edged lower in after-hours trading ahead of its latest financial results.

    The announcement is expected to provide further information on the strategy being pursued under chief executive Elliott Hill, including the company’s focus on sports such as football and running, its relationships with wholesale partners and the introduction of new products.

    Nike has experienced weaker sales and increased competitive pressures. Its shares have declined by more than 44% since the beginning of the year, according to the supplied figures.

    During September, S&P Dow Jones removed Nike from the S&P 100 as part of its quarterly index rebalancing, ending an 18-year period in the index.

    ISM Manufacturing Report Due

    The September US manufacturing purchasing managers’ index from the Institute for Supply Management is also due.

    The headline index is forecast to increase to 54.8 from 54.6 in August. Readings above 50 indicate expansion in manufacturing activity.

    The prices-paid component is expected to rise to 72.9 from 71.1, indicating continued price pressures across the manufacturing sector.

    Tencent Reportedly Agrees $7 Billion Oracle AI Chip Lease

    The Financial Times separately reported that Tencent (NYSE:TME) had signed a five-year, $7 billion lease agreement with Oracle (NYSE:ORCL) for access to approximately 100,000 advanced artificial intelligence chips.

    The newspaper, citing two people with knowledge of the matter, said the agreement covers several Oracle data centres in Southeast Asia and includes an upfront payment of approximately 30%.

    The Financial Times reported that the transaction represents Tencent’s largest overseas lease agreement and provides the company with access to advanced chips unavailable in China.

    Oracle shares traded higher after hours following the report.

  • European Stocks Fall as Fourth Quarter Begins With Energy and Inflation Concerns: DAX, CAC, FTSE100

    European Stocks Fall as Fourth Quarter Begins With Energy and Inflation Concerns: DAX, CAC, FTSE100

    European stock markets moved lower on Thursday at the start of October and the fourth quarter, as investors continued to assess higher energy costs, inflation pressures and developments in the Middle East.

    The pan-European STOXX 600, Germany’s DAX and France’s CAC 40 each fell 0.6%, while the UK’s FTSE 100 declined 1.1%.

    Softer-than-expected US economic data provided some support to global markets, although this was offset by inflation concerns in Europe and uncertainty surrounding negotiations between the United States and Iran.

    Middle East Developments Keep Energy Prices in Focus

    Negotiations between the United States and Iran aimed at ending the seven-month conflict have stalled, with crude oil prices remaining elevated.

    Higher energy costs have continued to affect inflation across the eurozone. Preliminary September data showed consumer price inflation accelerating more than expected in several major economies, including France, Italy and Spain, amid increases in petrol, diesel and wholesale gas prices.

    The higher inflation readings have increased market attention on the European Central Bank’s monetary policy outlook and the possibility that restrictive policy could remain in place for longer.

    Markets Assess Softer US Economic Data

    Investors were also assessing weaker-than-expected US economic data released during the previous session.

    US Personal Consumption Expenditures inflation for August came in below market forecasts, reducing some of the immediate upward pressure on global government bond yields.

    However, geopolitical uncertainty and higher inflation readings in Europe coincided with continued weakness across European equity markets.

    Investors are also awaiting further regional economic data and corporate earnings releases as the fourth quarter gets underway.

  • FTSE 100 Falls as UK 30-Year Gilt Yield Reaches 6%

    FTSE 100 Falls as UK 30-Year Gilt Yield Reaches 6%

    The FTSE 100 fell on Thursday as a global government bond selloff pushed the UK 30-year gilt yield to 6%, its highest level since February 1998.

    The index was down 1.85% as of 08:00 GMT. Elsewhere in Europe, Germany’s DAX declined 1.33% and France’s CAC 40 fell 1.46%, while sterling weakened 0.24% against the US dollar to $1.3234.

    The increase in UK borrowing costs followed Tuesday’s syndication of new 10-year benchmark government bonds, which were priced to offer the highest yield for an issue of that maturity since 1999.

    US government bond yields also moved higher, with the 10-year Treasury yield reaching 5.306% on Wednesday amid investor attention on inflation, fiscal deficits and government bond supply.

    Bond Yields Remain in Focus

    Jefferies strategist Mohit Kumar said rates “continued to be the main market driver”, with the US 10-year Treasury yield moving above 5.30%.

    US core personal consumption expenditures inflation increased 0.2% in August, below forecasts, although Kumar said methodological changes accounted for most of the decline.

    Kumar expects “just one more hike, likely in December” from the US Federal Reserve.

    In Europe, the spread between French and German government bond yields approached 130 basis points.

    Strait of Hormuz Traffic Recovers

    Investors also continued to monitor developments involving Iran and the Strait of Hormuz, where traffic has recovered to nearly 80% of pre-war levels according to some estimates.

    US President Donald Trump told reporters the choice was a deal with Iran or to “blow them up”, while Defense Secretary Pete Hegseth said US forces had “destroyed” Iran’s military capacity.

    Axios reported that Secretary of State Marco Rubio had ordered Iran’s delegation to leave after talks collapsed. Iran’s mission to the United Nations disputed the report, calling it “baseless” and saying its delegation departed New York on Monday as scheduled.

    UK Prime Minister Andy Burnham separately told the BBC there were “strong indications that Iran played a part” in an alleged plot at RAF Fairford.

    UK House Price Growth Slows

    UK house price growth slowed to a nine-month low in September, according to mortgage lender Nationwide.

    Annual house price growth eased to 0.8% from 1.6% in August, while prices declined 0.2% month-on-month. Nationwide reported weaker regional growth across most of the country.

    The UK September manufacturing purchasing managers’ index is due later on Thursday.

    In company news, Micron reported results following Wednesday’s US market close, with Jefferies pointing to the results in relation to demand associated with artificial intelligence.

    Oil and Gold Prices Rise

    Brent crude futures increased 1.4% to $99.44 a barrel, while US West Texas Intermediate crude gained 1.35% to $91.64.

    Gold futures rose 0.25% to $4,196 an ounce, while spot gold increased 0.22% to $4,165.95.

  • Filtronic Secures $68.1 Million Follow-On Order From SpaceX

    Filtronic Secures $68.1 Million Follow-On Order From SpaceX

    Filtronic (LSE:FTC) has received a $68.1 million (£51.3 million) follow-on order from SpaceX for its Cerus E-band gallium nitride solid-state power amplifier units.

    The order is the largest contract Filtronic has received from SpaceX to date and follows a $62.5 million order placed by the U.S. launch and satellite operator in 2025.

    Filtronic expects the latest order to be delivered predominantly during its 2028 financial year.

    Order Supports Filtronic’s FY2028 Expectations

    The company said the contract supports its existing expectations for the 2028 financial year and extends its commercial relationship with SpaceX.

    The order covers Filtronic’s Cerus E-band solid-state power amplifier units, which use the company’s gallium nitride, or GaN, technology.

    According to Filtronic, its GaN technology provides higher power, increased efficiency and improved thermal performance compared with traditional gallium arsenide-based solutions.

    The equipment is used in high-frequency communications applications, including low Earth orbit satellite communications systems.

    Filtronic Supplies High-Frequency RF Technology

    Filtronic designs and manufactures high-frequency radio frequency products for the space, aerospace, defence and telecommunications infrastructure markets.

    The UK-based company supplies RF technologies for applications including satellite communications, defence systems and telecommunications networks.

  • Primary Health Properties Secures £5.8 Million Rental Increase as Assura Integration Completes

    Primary Health Properties Secures £5.8 Million Rental Increase as Assura Integration Completes

    Primary Health Properties PLC (LSE:PHP) reported £5.8 million of additional rental income from 480 rent reviews during the first nine months, as the healthcare property group completed its integration of Assura.

    The rent reviews produced an annualised increase of approximately 3.1%, with rental income growth running slightly ahead of the company’s guidance.

    PHP reported rental growth across its UK primary care, private hospital and Irish portfolios, which include properties leased to public healthcare bodies and private healthcare operators.

    PHP Progresses Healthcare Property Developments

    The company is continuing asset management and development activities across its portfolio, including projects to expand clinical space in Wakefield and Yeovil.

    PHP is also progressing a £6.5 million extension at Tees Valley Hospital.

    Five new-build projects are under development across the UK and Ireland, with the company reporting that the projects remain on schedule and within budget.

    Joint Venture Proceeds Targeted at Debt Reduction

    PHP is also progressing joint venture transactions as part of its capital management plans. The company intends to use proceeds from these transactions to reduce leverage.

    The group is targeting lower debt metrics following its combination with Assura and continues to integrate the acquired business into its operations.

    PHP also maintains a stated objective of continuing its record of progressive dividend growth, which has extended for 30 years.

    Primary Health Properties Portfolio

    Primary Health Properties is a real estate investment trust focused on healthcare properties in the UK and Ireland.

    Following its combination with Assura, the group owns a portfolio valued at approximately £6 billion, comprising assets including GP surgeries, NHS- and HSE-backed healthcare facilities and private hospitals.