Blog

  • Defence Holdings commits £2m to new UK defence technology fund

    Defence Holdings commits £2m to new UK defence technology fund

    Defence Holdings (LSE:ALRT) has committed £2 million as a cornerstone investor in a newly established UK Defence Fund designed to back early-stage companies developing technologies for the defence sector.

    The independently managed fund will target defence-native technologies spanning artificial intelligence, autonomous systems, cyber capabilities and secure infrastructure. It plans to make minority investments of between £250,000 and £1 million in companies at the pre-seed and seed stages.

    Additional funding is expected to come from other professional investors, while the vehicle could also gain access to UK public-backed capital. The structure is intended to give Defence Holdings exposure to a broader portfolio of emerging defence technologies without requiring the company to concentrate investment risk entirely on its own balance sheet.

    The fund also extends Defence Holdings’ existing operating model by allowing third-party capital to participate in opportunities sourced through its Meridian programme and other industry relationships. At the same time, the company intends to maintain its primary operational focus on developing its core sovereign software products.

    Independent directors approved the investment as a related-party transaction. They concluded that the structure provides Defence Holdings with economic exposure to the expanding UK and allied defence technology markets while limiting its financial obligations.

    The company will not be required to make additional capital commitments beyond those necessary to maintain its stake in the fund. The investment comes against a backdrop of rising national defence budgets and growing government interest in technologies capable of strengthening military capability, resilience and technological sovereignty.

    Defence Holdings nevertheless continues to face significant financial challenges. Its broader outlook is constrained by a sharp decline in revenue, continuing losses and recurring cash burn. Technical indicators provide little support, with the shares trading below all major moving averages.

    Traditional valuation metrics also remain difficult to apply because the company generates negative earnings and does not currently offer a dividend yield.

    More about Defence Holdings

    Defence Holdings PLC is a UK-listed, software-led defence technology company focused on developing and commercialising sovereign software capabilities for the UK and allied defence markets.

    Through government relationships, strategic partnerships and its Meridian Accelerator Programme, the group seeks exposure to emerging defence technologies including artificial intelligence, autonomous systems, cyber resilience and secure information infrastructure.
  • Arc Minerals begins major drilling programme at Botswana Virgo copper project

    Arc Minerals begins major drilling programme at Botswana Virgo copper project

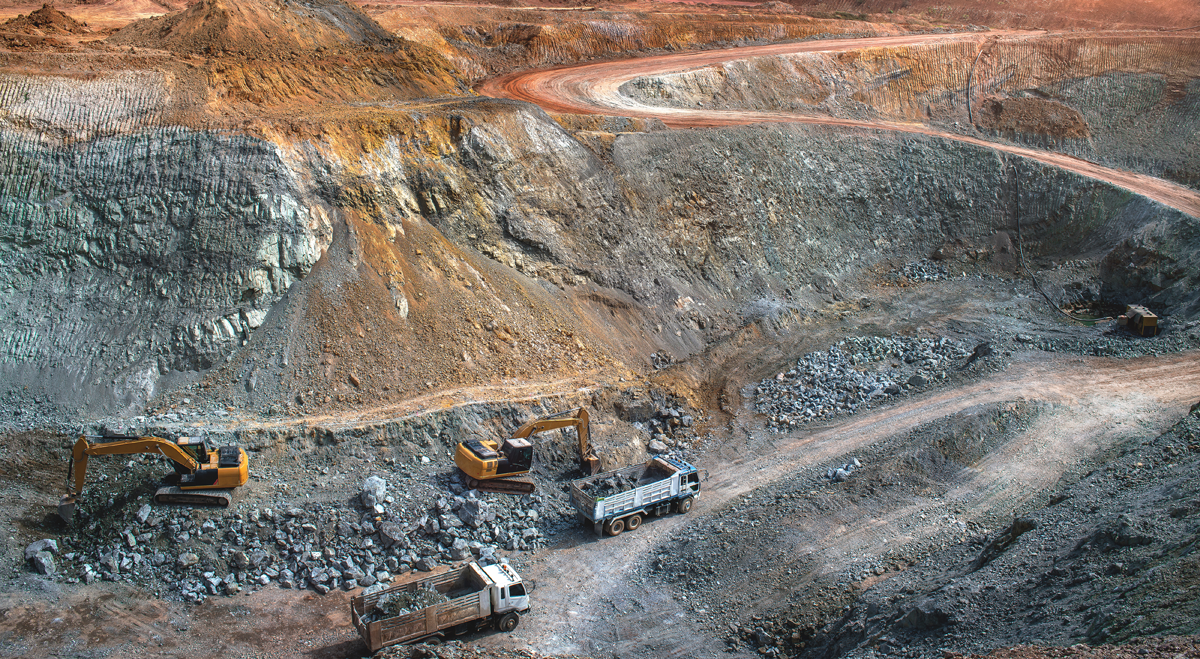
    Arc Minerals (LSE:ARCM) has appointed G D E Botswana Drilling & Exploration, part of Global Drilling & Exploration Group, to undertake a diamond drilling campaign at its PL135/2017 licence within the Virgo copper project in Botswana’s Kalahari Copper Belt.

    The phased exploration programme will investigate a series of high-priority targets across approximately 14 kilometres of interpreted contact between the D’kar and Ngwako Pan formations. Drilling will also focus on structurally complex areas that Arc believes could provide favourable traps for copper mineralisation.

    The programme has been designed to remain adaptive as drilling progresses and is expected to exceed 6,000 metres. Arc plans to use portable X-ray fluorescence analysis alongside laboratory assays to evaluate drill core, allowing geological information to be incorporated into decisions as the campaign advances.

    Management highlighted the strategic location of the Virgo project within the Zone 5 corridor, where Arc is the only junior company holding a licence. The company’s ground is situated close to MMG’s Khoemacau project, placing the exploration campaign within one of Botswana’s most prospective copper districts.

    Successful drilling could provide important evidence regarding the scale and continuity of mineralisation at Virgo. Positive results could also strengthen Arc’s position as it seeks to demonstrate the project’s discovery potential and attract greater attention from prospective investors and industry partners.

    Arc’s broader financial profile remains challenging. The company is pre-revenue and continues to report losses and cash outflows, while its equity and asset base contracted during 2025.

    Technical indicators provide a more supportive picture, with the shares trading above important moving averages and MACD remaining positive. However, conventional valuation measures offer limited support because Arc continues to generate negative earnings and does not currently provide a dividend yield.

    More about Arc Minerals

    Arc Minerals is an AIM-quoted copper exploration company focused on identifying and developing potentially Tier 1 copper deposits in Africa.

    Its principal interests include the Virgo Project in Botswana’s Kalahari Copper Belt, situated within MMG’s highly prospective Zone 5 corridor, and the Kabompo West Project in Zambia’s Central African Copper Belt. Both assets give Arc exposure to established, globally significant copper-producing regions.

  • Petards improves margins, cuts debt and expands order book as outlook strengthens

    Petards improves margins, cuts debt and expands order book as outlook strengthens

    Petards (LSE:PEG) has reported continued improvement in its financial performance during 2026, with stronger margins, lower debt and a growing order book supporting expectations for a full-year result ahead of current market forecasts.

    The company said margins have improved compared with both the first half and the full year of 2025, despite revenue being slightly lower. Petards expects to report growth in EBITDA for the first half when it publishes its interim results on 11 September.

    The group’s balance sheet has also strengthened, with total net debt reduced to £1.16 million. Meanwhile, its order book has increased to £9.6 million, providing greater visibility over future activity.

    Chairman Raschid Abdullah said the Group has generated cash, grown gross profit margins and profitability, and strengthened its order pipeline in the first half of the year.

    The progress has increased the board’s confidence in trading for the remainder of 2026. Petards now expects the business to continue performing well during the second half and anticipates delivering a full-year result ahead of current market expectations.

    The improving margins, cash generation and order pipeline provide positive indicators for the company’s operational trajectory. However, Petards’ broader investment outlook remains constrained by continuing losses and negative returns, despite signs of improving profitability and cash flow during 2025.

    Technical indicators are moderately supportive but remain mixed, with an elevated relative strength index suggesting the shares may be overbought in the near term. Traditional valuation measures also provide limited support because of the company’s negative price-to-earnings ratio and absence of a dividend.

    More about Petards

    Petards Group plc is an AIM-quoted technology company specialising in advanced security, communications and surveillance systems.

    The group develops technology designed to improve safety and operational efficiency, serving customers that require sophisticated monitoring, data collection and information management capabilities.

  • Tertiary Minerals identifies new shallow copper zone at Mushima North

    Tertiary Minerals identifies new shallow copper zone at Mushima North

    Tertiary Minerals (LSE:TYM) has identified a new area of shallow copper mineralisation at its Mushima North project in Zambia, potentially expanding the scale of the mineralised system currently being explored at Target A1.

    Scout drilling using portable X-ray fluorescence (pXRF) analysis outlined a new Western Zone, including an intersection of 25 metres grading 0.38% copper from a depth of 19 metres. This interval contained a higher-grade section of 13 metres at 0.53% copper from 29 metres.

    The newly identified zone is situated approximately 900 metres west-southwest of the existing Discovery Zone. Its location indicates that copper mineralisation may extend beyond the boundaries of the project’s current Exploration Target, providing Tertiary with an additional area for follow-up exploration.

    Initial interpretation of the pXRF results suggests the Western Zone contains predominantly copper-only mineralisation, although laboratory assays will be required to confirm the grades and geological characteristics.

    The discovery provides further support for Tertiary’s geological model, which indicates that Target A1 could form part of a larger mineralised system than has so far been defined at Mushima North.

    Exploration activity is continuing through a 39-hole Phase 4 drilling programme. Laboratory assay results and metallurgical testwork are also expected, with the resulting data set to contribute to resource modelling for the Discovery Zone and help determine the significance of the newly identified Western Zone.

    Progress at Mushima North could also strengthen Tertiary’s position within Zambia’s developing copper-silver exploration district as the company works towards defining a maiden mineral resource at Target A1.

    From a financial perspective, Tertiary remains constrained by persistent losses and continuing cash expenditure associated with its exploration activities. Technical indicators offer some support, with the shares trading above important moving averages, although negative earnings and the absence of a dividend mean conventional valuation measures remain limited.

    More about Tertiary Minerals

    Tertiary Minerals plc is an AIM-listed mineral exploration company focused on copper, silver and polymetallic opportunities. One of its principal assets is the Mushima North Copper Project in Zambia’s Iron-Oxide-Copper-Gold region.

    The Target A1 prospect hosts a silver-copper-zinc mineralised system and is located close to the historic Kalengwa mine. Tertiary is advancing exploration at the prospect with the objective of defining a maiden mineral resource estimate.

  • AstraZeneca reports Phase III survival benefit for Tagrisso–Orpathys lung cancer combination

    AstraZeneca reports Phase III survival benefit for Tagrisso–Orpathys lung cancer combination

    AstraZeneca (LSE:AZN) has reported positive results from the global Phase III SAFFRON trial, with a combination of Tagrisso and Orpathys delivering significant improvements in both progression-free survival and overall survival for certain patients with MET-driven, EGFR-mutated non-small cell lung cancer.

    The study evaluated the all-oral combination against platinum-based chemotherapy in patients whose disease had progressed following treatment with Tagrisso. Results showed that Tagrisso plus Orpathys produced statistically significant survival benefits compared with chemotherapy.

    The safety profile observed in the trial was consistent with the established profiles of the two individual medicines, providing further support for the potential use of the combination in this patient population.

    The findings strengthen AstraZeneca’s broader strategy of establishing Tagrisso as a backbone treatment across different stages and settings of EGFR-mutated lung cancer. They could also support regulatory submissions around the world for the biomarker-directed Tagrisso and Orpathys regimen.

    A successful expansion of the combination would further reinforce AstraZeneca’s position in targeted lung cancer therapies, where identifying specific genetic drivers such as EGFR mutations and MET alterations is increasingly shaping treatment decisions.

    From a broader investment perspective, AstraZeneca continues to benefit from strong underlying profitability, a constructive earnings outlook, reiterated guidance and continued momentum across its drug development pipeline. These strengths are partly offset by weaker technical indicators, with the shares trading below major moving averages.

    Cash conversion presents a more mixed picture following an increase in net debt during the first half, while the company’s valuation reflects relatively high expectations for future growth rather than presenting an obvious discount.

    More about AstraZeneca

    AstraZeneca is a global biopharmaceutical company focused on discovering, developing and commercialising prescription medicines across oncology and several other major disease areas.

    The company has established a significant presence in lung cancer, particularly in EGFR-mutated non-small cell lung cancer, through targeted treatments including Tagrisso. It is also developing combination therapies with partners such as HUTCHMED as part of efforts to address resistance mechanisms and extend the benefits of precision medicines to additional groups of patients.

  • Panther Metals reports encouraging first-phase magnesium recovery at Dotted Lake

    Panther Metals reports encouraging first-phase magnesium recovery at Dotted Lake

    Panther Metals (LSE:PALM) has announced positive results from the first phase of metallurgical testing at its Dotted Lake project in Ontario, Canada, where leaching trials achieved cumulative magnesium recoveries of approximately 38%.

    The testing was carried out on serpentine-rich ultramafic drill core using Extrakt’s proprietary leaching technology. Results also confirmed that the intrusive contains magnesium-rich material alongside elevated concentrations of other critical elements, providing Panther with initial metallurgical data that can be used to refine and optimise the recovery process.

    The findings represent an important step in assessing the potential of Dotted Lake beyond its geological characteristics. Management believes the results could help advance the project towards becoming a strategically relevant and potentially commercial source of magnesium, particularly as efforts intensify to establish secure North American supply chains for critical minerals.

    Further work will be required before the project’s commercial potential can be established. Panther stressed that the Phase 1 findings remain preliminary, with additional metallurgical testing, reproducibility studies and techno-economic analysis still needed.

    Future work is also expected to include optimisation of the reagent management system. These studies will help determine whether the process can ultimately progress towards pilot-scale testing and, potentially, the design of a commercial operation.

    Panther’s wider financial position remains a consideration for investors. The company is currently pre-revenue and continues to record recurring losses and negative cash flow. Traditional valuation metrics provide limited support, with a negative price-to-earnings ratio and no dividend yield available.

    Technical indicators are more supportive, with the share price trading above major moving averages and MACD remaining positive. However, an elevated relative strength index suggests the shares could be vulnerable to some near-term overheating following recent momentum.

    More about Panther Metals Plc

    Panther Metals Plc is a mineral exploration company focused primarily on Canadian projects targeting magnesium and other critical minerals, including nickel, cobalt, chromium and platinum group elements.

    Its Dotted Lake project in Ontario covers an ultramafic magmatic intrusive situated close to established transport infrastructure and near the long-standing Hemlo gold mining district. The company is evaluating the project’s potential to host strategically important minerals that could contribute to developing more secure North American supply chains.

  • Optima Health lifts revenue and margins as PAM acquisition strengthens UK occupational health position

    Optima Health lifts revenue and margins as PAM acquisition strengthens UK occupational health position

    Optima Health PLC (LSE:OPT) delivered a stronger performance in FY26, with revenue increasing 14.8% to £120.6 million and adjusted EBITDA reaching £20.1 million, meeting expectations and exceeding the company’s previous profit guidance.

    The occupational health provider maintained its adjusted EBITDA margin at 16.7% while generating more cash from operations during the year. Results also included £4.7 million of other operating income following the resolution of a procurement-related matter. However, net debt increased substantially as Optima invested in expanding the business.

    A major development during the period was the £100 million acquisition of PAM Healthcare, which increased the group’s scale and broadened its capabilities while reinforcing its position in the occupational health market across the UK and Ireland.

    Optima said the integration of PAM is progressing in line with plans, with initial cost synergies already being achieved. Alongside the integration, the company has developed a £33.9 million opportunity pipeline and is mobilising its significant UK Armed Forces Recruitment Service contract, which could be worth as much as £210 million over seven years.

    Looking further ahead, Optima is targeting annual revenue of £200 million and adjusted EBITDA of £40 million over the medium term. Management’s ambitions reflect expectations for continued demand for occupational health and wellbeing services from employers.

    The company’s broader financial picture remains mixed. Free cash flow was negative in 2025, while a price-to-earnings ratio of around 50 indicates a relatively demanding valuation despite thin margins. Profitability has nevertheless improved and leverage remains modest. From a technical perspective, momentum indicators are broadly neutral, although the shares remain below longer-term moving averages and volatility continues to weigh on confidence.

    More about Optima Health PLC

    Optima Health PLC is a UK provider of occupational health and wellbeing services, delivering clinically led and technology-supported solutions to corporate, public-sector and international customers.

    Following the acquisition of PAM Healthcare, the enlarged group employs more than 1,250 clinicians and works with over 1,000 associate practitioners. It delivers more than one million health interventions annually across the UK and Ireland, providing services designed to support employee health, wellbeing and workplace performance.

  • Hydrogen Utopia secures UK licence to advance waste-to-jet fuel technology

    Hydrogen Utopia secures UK licence to advance waste-to-jet fuel technology

    Hydrogen Utopia International PLC (LSE:HUI) has obtained a UK licence from U.S.-based InEnTec Inc. to use its PEM gasification technology in the production of sustainable aviation fuel, expanding the company’s footprint in the waste-to-fuel sector.

    The licence, valued at $500,000, allows Hydrogen Utopia to develop and operate systems across the United Kingdom that transform non-recyclable plastics, waste tyres and other discarded materials into syngas suitable for producing sustainable aviation fuel (SAF). The agreement builds on an existing exclusive licence covering the Middle East and North Africa.

    The expansion into the UK comes as government policy increasingly supports the development and adoption of lower-carbon aviation fuels. The UK Government is implementing its Low Carbon Fuels Fund alongside a statutory SAF mandate that requires sustainable fuels to account for a progressively larger proportion of aviation fuel demand.

    Hydrogen Utopia’s board believes these measures could create a supportive environment for waste-derived fuel projects. The company expects its new licence to improve its prospects of accessing public funding while providing a platform from which it can develop and scale waste-to-SAF infrastructure in the UK.

    Despite the potential commercial opportunity, Hydrogen Utopia remains at an early stage financially. The company is pre-revenue, continues to report losses and has generated predominantly negative operating cash flow. Its technical picture is also weak, with the share price trading below important moving averages and the MACD indicator remaining negative.

    Traditional valuation measures offer limited support at present because the company is loss-making, resulting in a negative price-to-earnings ratio, while it does not currently provide a dividend yield.

    More about Hydrogen Utopia International PLC

    Hydrogen Utopia International PLC develops waste-to-fuel technology designed to process non-recyclable mixed waste plastics into hydrogen, sustainable aviation fuel and other cleaner fuels, alongside advanced materials and renewable heat.

    Its proposed facilities use waste that cannot otherwise be recycled as feedstock for the production of syngas. The company ultimately aims to generate revenue from the sale of gases, electricity and heat, as well as fees charged for processing waste, with its development strategy focused on markets offering supportive government policies and significant private-sector investment.

  • Morgan Stanley Picks Its Favoured Market Areas as Earnings Rally Broadens

    Morgan Stanley Picks Its Favoured Market Areas as Earnings Rally Broadens

    The U.S. earnings recovery is becoming much less dependent on megacap stocks, prompting Morgan Stanley to favour quality businesses, artificial intelligence adopters, large-cap financials and consumer discretionary goods. Strategists led by Michael Wilson say the market is also distinguishing more clearly between companies merely delivering higher earnings and those converting that growth into stronger free cash flow.

    Earnings momentum spreads beyond megacaps

    Second-quarter reporting has produced one of the strongest earnings environments of the current cycle.

    Approximately 87% of S&P 500 companies have beaten earnings forecasts, improving from 82% in the previous quarter.

    Earnings revision breadth has rebounded to 23%, while 76% of industry groups are experiencing positive revisions.

    “The key point is that earnings strength is no longer confined to a narrow group of megacap stocks,” Morgan Stanley’s strategists said.

    The broadening suggests investors have a larger universe of companies capable of generating meaningful earnings growth.

    Russell 3000 profits accelerate

    The improvement is particularly evident across the wider U.S. equity market.

    Median Russell 3000 earnings growth has reached 15%, its strongest rate since 2021.

    Median revenue growth is approximately 8%, close to its strongest pace since 2023.

    Together, these trends suggest the earnings recovery has increasingly solid foundations as revenue growth accompanies improving profitability.

    Free cash flow separates winners from losers

    The market is becoming more selective as earnings growth spreads.

    Morgan Stanley found that the median S&P 500 company receiving positive revisions to both 2026 EPS and free cash flow subsequently outperformed by 1.6% on a relative basis.

    Companies receiving positive EPS revisions alongside declining free cash flow forecasts underperformed by 0.2%.

    For investors, that difference is significant.

    Morgan Stanley said “headline earnings growth alone is becoming less sufficient,” with investors increasingly focused on cash conversion, sustainability and operational quality.

    AI adoption becomes a stock-selection factor

    Companies successfully incorporating artificial intelligence into their operations remain another preferred group.

    Morgan Stanley’s targeted AI-adopter basket continues to outperform the broader market.

    The opportunity extends beyond traditional AI infrastructure suppliers.

    Businesses capable of using AI to automate processes, increase employee productivity, reduce expenses or improve customer experiences could generate measurable efficiency gains.

    That gives investors another way to participate in AI beyond semiconductors and data-centre infrastructure.

    Financials remain overweight

    Morgan Stanley maintains an overweight position in financials.

    Insurance and capital-markets companies are its preferred areas within the sector, supported by improving earnings revisions and favourable signals from the bank’s regime analysis.

    A steeper yield curve could reinforce the outlook, although a sharp increase in longer-term yields would introduce additional risks.

    Consumer goods positioned for recovery

    Consumer discretionary goods also feature among Morgan Stanley’s preferred exposures.

    The bank sees household wallet share shifting from services towards goods.

    Pricing conditions are improving at the same time that earnings revision breadth is recovering.

    Morgan Stanley believes these trends could support a performance catch-up after previous weakness.

    Hyperscalers offer better risk-reward than semis

    Technology remains important, but Morgan Stanley is selective within the sector.

    Semiconductor shares “can continue to participate tactically following the recent momentum unwind.”

    Over a longer, multi-month horizon, however, hyperscalers are the preferred exposure.

    Morgan Stanley points to their “resilient core businesses, attractive relative valuation and underappreciated optionality around AI-related ROI and adoption.”

    That provides hyperscalers with several potential drivers, including core cloud demand, AI adoption and improving returns from infrastructure spending.

    Bond yields and oil could challenge the outlook

    The main threats to Morgan Stanley’s constructive positioning are higher long-term interest rates and rising oil prices.

    Two-year Treasury yields have retreated from their late-July peak, helping produce a steeper yield curve.

    A rapid increase at the longer end of the curve would be less supportive.

    If inflation expectations or real yields rise sharply, higher long-term borrowing costs “could become a more meaningful risk.”

    That could increase companies’ cost of capital and place pressure on equity valuations.

    Quality takes priority as earnings breadth improves

    Morgan Stanley’s positioning reflects a market in which earnings opportunities are becoming broader but stock selection is becoming more important.

    The bank favours companies capable of combining earnings growth with strong cash generation rather than businesses producing headline EPS improvements without corresponding free cash flow.

    Its preferred areas are quality stocks, AI adopters, large-cap financials and consumer discretionary goods, while hyperscalers rank ahead of semiconductor companies within technology.

    With earnings growth spreading across the Russell 3000 and positive revisions appearing across most industry groups, Morgan Stanley sees a healthier market backdrop—but one where profitability, cash conversion and AI-driven efficiency increasingly separate the winners from the rest.

  • S&P 500 Could Reach 8,000 as AI Monetisation Fuels Earnings Boom, JPMorgan Says

    S&P 500 Could Reach 8,000 as AI Monetisation Fuels Earnings Boom, JPMorgan Says

    JPMorgan has become more bullish on the S&P 500 following a powerful second-quarter earnings season, raising its 2026 index target from 7,800 to 8,000. Stronger corporate profits and mounting evidence that hyperscalers are generating commercial returns from their enormous artificial intelligence investments underpin the upgrade, although the bank remains cautious about stretching market valuations further.

    JPMorgan upgrades earnings forecasts

    Second-quarter earnings have exceeded JPMorgan’s expectations across a wide range of industries.

    With 87% of S&P 500 companies having reported, strategists led by Dubravko Lakos-Bujas said performance “remains strong and broad-based across multiple sectors.”

    JPMorgan now expects S&P 500 EPS to reach $365 in 2026, compared with the consensus estimate of $358.

    That would represent annual growth of approximately 35%.

    The bank also raised its 2027 forecast to $420 per share, implying another 15% increase.

    Underlying EPS growth remains powerful

    Private-company investment gains have provided a notable boost to reported earnings.

    Based on valuations recorded during the first six months of 2026, JPMorgan calculates that these gains have added approximately $18 to index-level EPS.

    Stripping them out reduces normalised 2026 EPS to around $347.

    Even then, annual earnings growth would remain an impressive 28%, suggesting the market’s fundamental strength extends well beyond non-operating valuation gains.

    Higher target does not rely on multiple expansion

    JPMorgan continues to apply a forward valuation multiple of approximately 20 times earnings.

    That is despite describing the environment as “one of the strongest fundamental backdrops since GFC.”

    The bank remains reluctant to assume further multiple expansion because interest rates could stay higher for longer, geopolitical uncertainty remains elevated and financial markets must absorb significant amounts of equity and debt issuance.

    The path towards 8,000 therefore depends primarily on earnings growth rather than investors paying increasingly expensive multiples.

    Hyperscalers begin proving AI returns

    AI investment remains one of the most important forces shaping the market.

    The focus, however, is shifting.

    Rather than simply assessing how much hyperscalers are spending, investors increasingly want evidence that those investments can generate revenue, cash flow and acceptable returns on invested capital.

    JPMorgan sees signs that this process is underway.

    Google, Amazon and Microsoft stood out during earnings season as “stronger cloud growth, backlog expansion, and improved operating cash flow visibility cleared a high investor expectation bar.”

    AI spending could exceed $1.2 trillion

    Capital expenditure nevertheless continues to rise at an extraordinary rate.

    Consensus estimates suggest AI capex will reach approximately $900 billion by the end of 2026, representing 85% annual growth.

    By the end of 2027, spending is projected to exceed $1.2 trillion.

    The investment wave is creating enormous demand throughout the AI ecosystem, from semiconductors and servers to data centres, networking infrastructure, power generation and cooling equipment.

    Cloud growth provides evidence of monetisation

    Cloud results strengthened the argument that hyperscalers are beginning to translate AI investment into revenue.

    AWS expanded 37% year over year, Azure grew 43%, and Google Cloud delivered record growth of 82%.

    Backlog growth was equally striking.

    Google Cloud added $52 billion sequentially, taking its backlog to $514 billion.

    AWS backlog increased 36% from the previous quarter to $496 billion, almost 2.5 times the level recorded a year earlier.

    Those figures provide considerable visibility into future demand.

    AI capex creates a $430 billion cash flow gap

    The biggest concern is increasingly cash generation.

    Combined trailing-12-month hyperscaler net income has risen to $599 billion, while free cash flow stands at just $169 billion.

    That leaves a gap of approximately $430 billion.

    At the end of 2023, the two measures were roughly equal, illustrating how dramatically the AI capital-spending cycle has changed cash-flow dynamics.

    JPMorgan expects this pressure to persist.

    Apart from Microsoft, its analysts forecast that most hyperscalers will generate negative free cash flow through the 2026-2027 period.

    Earnings growth drives JPMorgan’s 8,000 target

    The combination of strong corporate earnings and improving AI monetisation has given JPMorgan greater confidence in further S&P 500 gains.

    The bank’s 2026 EPS estimate now stands at $365, rising to $420 in 2027.

    Rather than relying on further valuation expansion, JPMorgan has kept its forward multiple near 20 times, meaning stronger profits are doing most of the work behind the upgraded index forecast.

    While enormous AI investment is placing considerable pressure on free cash flow, accelerating cloud revenue and record backlogs provide increasing evidence that this spending is generating demand.

    JPMorgan consequently sees the S&P 500 reaching 8,000 in 2026.