Blog

  • Cohort’s ELAC SONAR Secures €140.7m Saab Contract for Polish Submarine Programme

    Cohort’s ELAC SONAR Secures €140.7m Saab Contract for Polish Submarine Programme

    Cohort (LSE:CHRT) has secured a major contract through its German subsidiary ELAC SONAR, which has been selected by Saab to provide integrated sonar systems for Poland’s Orka Submarine Programme.

    The contract is valued at €140.7 million, with work starting immediately and deliveries scheduled to continue into the mid-2030s. ELAC SONAR will supply advanced active and passive sonar technology for the Polish Navy’s new A26 submarines.

    The long-term award further strengthens ELAC SONAR’s position within the European submarine market and gives Cohort increased exposure to defence investment associated with maritime security in the Baltic Sea region.

    Contract expected to support future earnings

    Cohort said the contract, together with other recently secured orders, is expected to make a positive contribution to adjusted earnings per share from the next financial year onwards.

    The scale and duration of the programme also provide additional visibility for Cohort’s Sensors and Effectors division, strengthening its order book and supporting longer-term revenue generation.

    Management said the award reinforces ELAC SONAR’s standing as a specialist in naval hydroacoustic technology as the German business marks its centenary.

    Saab partnership expands Cohort’s European defence presence

    The agreement with Saab strengthens Cohort’s participation in major European defence programmes and expands its presence in the international submarine systems market.

    Supplying sonar systems for the Polish Navy’s A26 submarines also gives Cohort a role in a strategically important regional defence programme at a time of heightened focus on underwater capabilities and Baltic Sea security.

    The contract builds on ELAC SONAR’s expertise in sophisticated underwater detection technology and further establishes Cohort as a specialist supplier of naval sensors and defence systems.

    Growth and order momentum offset cash flow pressures

    Cohort’s wider outlook is supported by continued growth and a generally sound balance sheet, although weaker cash generation remains a concern after free cash flow moved into negative territory in 2026.

    Technical indicators remain supportive, with the shares continuing to trade within an established upward trend. Valuation is less favourable, however, due to a relatively high price-to-earnings ratio and a modest dividend yield.

    More about Cohort plc

    Cohort plc is an AIM-listed independent technology group serving defence and security markets through seven businesses operating across the UK, Australia, Germany, Italy, Canada and Portugal.

    The group is organised around its Communications and Intelligence and Sensors and Effectors divisions, supplying technologies including naval communications, electronic warfare, surveillance systems, sonar and other specialist defence capabilities.

    Its portfolio includes EID, EM Solutions, MASS, MCL, Chess Dynamics, ELAC SONAR and SEA, which together employ more than 1,700 core staff. Their capabilities range from satellite communications terminals and hydroacoustic systems to tracking, fire-control and training support services.

    Headquartered in Reading, Berkshire, Cohort has expanded through acquisitions since joining London’s Alternative Investment Market in 2006. Its combination of secure communications, intelligence, sonar, surveillance and sensor technologies positions the group as a specialist supplier to naval and military programmes internationally.
  • Touchstone Exploration Returns to Q2 Profit as Higher Prices Boost Cash Flow

    Touchstone Exploration Returns to Q2 Profit as Higher Prices Boost Cash Flow

    Touchstone Exploration (LSE:TXP) delivered a significant improvement in its second-quarter 2026 financial performance, returning to profitability as stronger commodity pricing lifted revenue, operating margins and cash generation.

    Funds flow from operations increased to $7.13 million, while net income reached $2.34 million, reversing the loss recorded in the previous quarter. Petroleum and natural gas sales climbed 39% sequentially to $17.47 million as realised prices strengthened across crude oil, natural gas liquids and natural gas.

    The improvement came despite average production declining 5% from the previous quarter to 4,433 barrels of oil equivalent per day, largely reflecting planned maintenance at Atlantic LNG.

    Stronger netbacks support debt reduction

    Touchstone’s operating netback increased 77% to $24.37 per boe, providing additional cash generation and helping the company reduce net debt by 10% to $68.71 million.

    Capital expenditure totalled $1.52 million during the quarter, with investment directed towards projects including the FR-1836 oil well and the Cascadura booster compressor.

    Touchstone also completed a multi-jurisdictional financing during the period. The subsequent repayment and full conversion into equity of an $8.40 million debenture simplified the group’s capital structure and provided additional financial flexibility to pursue future growth initiatives.

    Cascadura compressor begins operations

    Operational activity progressed across several of Touchstone’s Trinidad and Tobago assets. The Cascadura booster compressor was commissioned and started operations, while two development oil wells were completed on the WD-8 block.

    The company also successfully recompleted the BRE-1 well on the Central block, adding to efforts to strengthen production capacity and optimise its existing asset base.

    Gas output from Cascadura and Coho was temporarily restricted by third-party pipeline constraints associated with the Atlantic LNG Train 4 outage. However, early performance from the Cascadura compressor has exceeded expectations.

    Touchstone is carrying out several optimisation programmes across its operations and expects to have the potential to increase production as regional pipeline pressures return to more normal levels.

    More about Touchstone Exploration

    Touchstone Exploration Inc. is a Calgary-based oil and gas producer focused primarily on operations in Trinidad and Tobago, where it produces crude oil, natural gas and natural gas liquids.

    Its portfolio includes the Ortoire and Central blocks as well as gas-focused developments such as Cascadura and Coho. The company targets both liquids-rich and dry natural gas reservoirs while selling production into regional energy markets, including infrastructure connected to Atlantic LNG.

    Touchstone’s strategy combines onshore oil development with natural gas projects, production optimisation and investment in supporting infrastructure. The company is also focused on reducing leverage and strengthening its balance sheet to support longer-term growth.

    Its production mix is approximately one-third liquids and two-thirds natural gas, giving Touchstone exposure to both international oil prices and Caribbean gas market conditions. As a result, regional pipeline availability and LNG infrastructure uptime remain important factors affecting production and financial performance.

  • Iomart Names NatWest Veteran Matthew Waymark as New CFO

    Iomart Names NatWest Veteran Matthew Waymark as New CFO

    Iomart Group plc (LSE:IOM) has appointed Matthew Waymark as Chief Financial Officer and a director of the company, strengthening its senior leadership team as the secure cloud services provider looks to restore growth momentum and advance its strategic priorities.

    Waymark will formally take up the roles on 14 September 2026. A chartered accountant, he brings extensive financial experience from senior positions at NatWest as well as previous experience serving as CFO of a start-up bank.

    Waymark said he is joining Iomart at an important stage in the group’s development, with the business focused on rebuilding growth and delivering against its strategic objectives.

    Appointment follows extensive selection process

    Iomart’s board, led by Executive Chair Richard Last, said Waymark was selected following a rigorous recruitment process and is expected to bring additional financial leadership and expertise to the group.

    His arrival comes as Iomart seeks to sharpen strategic execution and strengthen financial discipline while pursuing opportunities within the competitive cloud services market.

    The company is aiming to use its existing technical credentials, customer relationships and extensive technology partner network to support future growth and ultimately enhance shareholder value.

    Financial and technical pressures weigh on outlook

    Iomart’s broader outlook remains affected by weaker financial performance, including continuing operating and net losses, margin pressure and substantially higher leverage following an erosion of equity. Free cash flow remains positive, although recent trends indicate some weakening.

    Technical indicators also remain under pressure, with Iomart shares trading below key moving averages and MACD in negative territory. Oversold readings provide some potential support but do not fully offset the weaker trend.

    Traditional valuation measures remain difficult to apply given the company’s negative earnings and resulting negative price-to-earnings ratio, while no dividend yield data is currently available.

    More about Iomart Group plc

    Iomart Group plc is a U.K.-based secure cloud managed services provider listed on AIM. Its services cover cloud infrastructure, modern workplace management and managed security, with the majority of its revenue generated from customers in the domestic market.

    The company holds a range of Microsoft credentials, including Azure Expert MSP status and multiple advanced specialisations. It is also a high-level partner of VMware Cloud and Commvault, supporting its capabilities across hybrid cloud infrastructure, data protection and cyber resilience.

    Iomart employs more than 600 specialists and focuses on helping businesses manage increasingly complex technology environments while scaling and operating securely. Its technology partnerships and certifications underpin a broad offering across cloud, data and cybersecurity services for U.K. organisations.

  • Kelso Urges The Works Shareholders to Back Board Appointment for Graeme Coulthard

    Kelso Urges The Works Shareholders to Back Board Appointment for Graeme Coulthard

    Kelso Group Holdings Plc (LSE:KLSO) is calling on shareholders of TheWorks.co.uk plc to support the appointment of major investor Graeme Coulthard to the retailer’s board at its forthcoming Annual General Meeting.

    Kelso is encouraging investors to vote in favour of Resolution 15, which proposes Coulthard’s election as a director. Kelso itself owns 10% of The Works, while Coulthard holds an 8% stake, giving the two shareholders significant exposure to the company’s future performance.

    Kelso challenges concerns over Coulthard’s retail experience

    Kelso has disputed The Works board’s assessment of Coulthard’s retail credentials, pointing to his previous involvement with Card Factory as evidence of his ability to contribute to shareholder value creation.

    The investment group argues that appointing Coulthard would represent a relatively modest governance change, expanding The Works board to six directors while introducing the perspective of a substantial shareholder.

    Kelso believes greater shareholder representation at board level could strengthen decision-making and help align the company’s strategic direction and capital allocation with the interests of its wider investor base.

    Financial performance remains a key concern

    Kelso’s own outlook continues to be constrained by weaker financial performance, including declining revenue, continuing losses and deterioration in operating and free cash flow.

    Technical indicators are relatively neutral, with some positive momentum but no clear directional trend. Valuation metrics offer limited additional support, with a reported price-to-earnings figure of 0.0 and no dividend yield data available.

    More about Kelso Group Holdings Plc

    Kelso Group Holdings Plc is a UK-listed investment company established in January 2023 to identify opportunities among undervalued small and mid-cap businesses.

    The company is backed by more than 80 business associates of its board alongside a small number of institutional investors. Its directors collectively have around 150 years of experience across UK-listed companies, including expertise in fund management, corporate broking, mergers and acquisitions, private equity and law. The board owns close to 20% of Kelso.

    Kelso typically maintains a concentrated portfolio of fewer than ten investments. Rather than operating as a passive shareholder, it seeks to engage with investee companies on areas including corporate strategy, capital allocation and investor relations.

    Through this activist-style approach, Kelso aims to identify and unlock value it believes is not adequately reflected in the market valuations of selected UK-listed businesses.

  • Mpac Group Confirms Half-Year Results Date and Investor Presentation

    Mpac Group Confirms Half-Year Results Date and Investor Presentation

    Mpac Group plc (LSE:MPAC) has confirmed that it will release its unaudited financial results for the six months ended 30 June 2026 on 15 September 2026, providing investors with an update on the engineering and automation group’s first-half performance.

    Management will also hold a briefing for analysts on the same day, continuing the company’s regular engagement with the professional investment community.

    Online investor presentation scheduled for 15 September

    Current and prospective shareholders will have an opportunity to hear directly from management through a live online presentation hosted on the Investor Meet Company platform.

    The presentation is scheduled to begin at 16:00 BST on 15 September 2026. Investors will be able to submit questions in advance of the event as well as during the live session.

    The online format is intended to make management commentary more widely accessible to shareholders and provide investors with further insight into Mpac’s financial performance, operations and strategic priorities.

    Financial pressures offset improving revenue trends

    Mpac’s broader outlook remains affected by financial pressures, including a net loss, negative operating and free cash flow and increased leverage. These factors are partly balanced by improving revenue growth and stronger gross margins.

    Technical indicators provide some support, with the share price trading above major moving averages and MACD remaining positive. However, elevated RSI and stochastic readings indicate potentially overbought conditions. Valuation also remains constrained by negative earnings, resulting in a negative price-to-earnings ratio, while no dividend yield data is available.

    More about Mpac Group PLC

    Mpac Group plc is an AIM-listed global engineering and technology company specialising in the design, precision engineering, manufacture and support of high-speed packaging machinery and end-of-line automation systems.

    The group serves customers across around 80 countries in the Americas, EMEA and Asia-Pacific, with a particular focus on the Food & Beverage and Healthcare markets. Its business combines original equipment sales with recurring service revenues.

    Through the BCA, Langen, Switchback and CSi product lines, Mpac provides automated packaging solutions covering processes from product assembly through to case packing and palletising. The group employs more than 900 people worldwide, including over 500 engineers and designers.

    Headquartered in Coventry, U.K., Mpac also has operations in the U.S., Mexico, Canada, the Netherlands, Romania, Malaysia and Singapore, supporting its strategy of using engineering innovation and automation technology to drive long-term growth.

  • Residential Secure Income Begins £38m Capital and Income Return Through B Share Scheme

    Residential Secure Income Begins £38m Capital and Income Return Through B Share Scheme

    Residential Secure Income plc (LSE:RESI) has launched the first stage of its B Share Scheme to return proceeds to shareholders following the disposal of its Retirement Group to Living REIT plc.

    The Retirement Group was sold for £108.3 million, including £45 million in cash. After accounting for transaction costs and settling historic expenses, Residential Secure Income plans to distribute approximately £35.2 million through redeemable B shares, equivalent to 19 pence for each ordinary share.

    Alongside the capital return, the company will make a property income distribution of approximately £2.8 million, representing 1.53 pence per share. Together, the two payments amount to an initial capital and income return of around £38 million.

    Shared Ownership disposal could lead to further distributions

    Residential Secure Income is also advancing the proposed sale of its Shared Ownership portfolio, which is expected to generate net proceeds of approximately £13.5 million.

    Once that transaction has completed, the company intends to make additional capital or income distributions to shareholders as it continues implementing its orderly wind-down strategy.

    The B Share Scheme uses unlisted redeemable shares to facilitate the return of substantial disposal proceeds. The structure forms a central part of RESI’s plan to distribute available cash to investors as its remaining assets are sold.

    Balance sheet strengthens as wind-down progresses

    Residential Secure Income’s financial position presents a mixed picture. Consistent cash generation and a significantly strengthened, debt-free balance sheet provide support, while declining revenue and continuing net losses remain areas of weakness.

    Technical indicators are moderately positive, with the share price trading above important moving averages. The company’s valuation also benefits from a high dividend yield, although negative earnings limit support from conventional earnings-based valuation measures.

    More about Residential Secure Income

    Residential Secure Income plc is a UK-listed real estate investment trust focused on residential property assets, historically including retirement housing and shared ownership homes.

    The company operates a tax-exempt property rental business and is currently pursuing an orderly wind-down. As assets are disposed of, RESI intends to return available proceeds to shareholders through mechanisms including its structured B Share Scheme.

  • TwentyFour Select Monthly Income Fund Releases July 2026 Factsheet and Commentary

    TwentyFour Select Monthly Income Fund Releases July 2026 Factsheet and Commentary

    TwentyFour Select Monthly Income Fund Limited (LSE:SMIF) has published its latest monthly factsheet and investment commentary, providing an update on the fund’s performance, portfolio positioning and market perspective through the end of July 2026.

    The newly released materials give professional and institutional investors further insight into the fund’s investment strategy and exposure to less liquid areas of the fixed-income market.

    Regular disclosures support investor transparency

    The publication forms part of TwentyFour Select Monthly Income Fund’s regular investor reporting programme, giving shareholders timely information on portfolio developments and the broader market environment.

    Consistent monthly reporting provides investors with greater visibility into the fund’s positioning and performance while supporting its role as an income-focused vehicle within the listed closed-ended investment fund sector.

    Financial position and dividend yield support outlook

    TwentyFour Select Monthly Income Fund’s investment profile is supported by a debt-free balance sheet and solid recent profitability, although historical fluctuations in earnings and cash generation remain factors for investors to consider.

    Technical indicators are also relatively supportive, with the share price trading above major moving averages and momentum remaining positive. From a valuation perspective, the fund offers a high dividend yield alongside a price-to-earnings ratio that sits within a more moderate range.

    More about TwentyFour Select Monthly Income Limited

    TwentyFour Select Monthly Income Fund Limited is a London-listed closed-ended investment company specialising in fixed-income markets.

    The fund seeks to generate attractive returns and income by investing across the debt spectrum, with a particular focus on less liquid fixed-income instruments. Its strategy is designed primarily for professional and institutional investors seeking income-oriented exposure to specialist areas of the credit market.

  • Afarak First-Half Revenue Falls as Alloy Demand and Geopolitical Pressures Weigh

    Afarak First-Half Revenue Falls as Alloy Demand and Geopolitical Pressures Weigh

    Afarak Group (LSE:AFRK) reported a weaker financial performance for the first half of 2026 as softer demand for specialty alloys, reduced production volumes and geopolitical disruption weighed on its operations.

    Revenue declined 25.9% year on year to €57.1 million, reflecting lower sales volumes of refined specialty alloys alongside a reduction in mined tonnage. EBITDA fell to €1.6 million, while the group moved into a €0.7 million loss for the period.

    Profitability was also affected by unfavourable fair-value adjustments related to currency forward contracts. Despite the earnings decline, operating cash flow improved and Afarak maintained relatively modest net interest-bearing debt.

    European ferrochrome demand remains subdued

    Management described the 2026 trading environment as challenging, particularly for low-carbon ferrochrome in Europe. Consumption has been affected by weaker activity in important end markets including the automotive and oil and gas industries.

    Geopolitical uncertainty has added further pressure, with conflicts involving Iran and Ukraine contributing to disruption across the wider market.

    In response to softer demand, Afarak has reduced ferrochrome production to better align output with current consumption levels and limit the impact of excess supply.

    Afarak sees potential recovery after summer

    Despite difficult first-half conditions, management expects the market to begin recovering after the summer. Low inventory levels could provide support if demand strengthens, while increasing Chinese demand for chrome ore and higher prices offer another potentially positive factor.

    Afarak is also working to diversify its operations and develop additional revenue streams, reducing its reliance on individual markets as it seeks to strengthen the group’s longer-term resilience.

    More about Afarak Group SE

    Afarak Group SE is a specialty alloys producer focused primarily on low-carbon ferrochrome and other processed alloy products.

    The company operates specialty metals businesses in Southern Europe alongside ferroalloy and chrome ore operations in South Africa. Afarak’s shares are listed on Nasdaq Helsinki and the London Stock Exchange.

  • Winking Studios Revenue Climbs as North American and AI Expansion Accelerates

    Winking Studios Revenue Climbs as North American and AI Expansion Accelerates

    Winking Studios (LSE:WKS) delivered strong revenue growth during the first half of 2026 as demand for its art outsourcing services remained robust, although increased investment in North America and artificial intelligence weighed on profitability.

    Unaudited revenue reached US$23.5 million, representing a 21.1% increase from the same period a year earlier, including organic growth of 8.9%. Adjusted EBITDA, however, declined to US$1.2 million as the group absorbed seasonally weaker contributions from Mineloader and increased spending to support its next stage of expansion.

    North American and AI investment steps up

    Winking Studios strengthened its presence in the North American market through the acquisition of Canadian studio Ampera in April 2026. The deal gives the group a direct foothold in the region and is intended to deepen relationships with Western customers.

    Around US$0.4 million has been committed to expanding the Ampera team and developing its market presence. At the same time, Winking Studios invested approximately US$0.9 million in AI-enabled game development capabilities.

    The group has already secured initial customer projects involving its AI capabilities and is seeking to establish itself as an end-to-end development partner as major game publishers increasingly look to work with larger, integrated outsourcing providers.

    Art outsourcing leads first-half growth

    Art outsourcing remained a key growth driver, with revenue from the division increasing 25.4% during the period. Revenue generated in Japan more than doubled to US$3.6 million, demonstrating further progress in an important gaming market.

    Repeat projects represented more than one-third of total sales, providing additional visibility over the group’s revenue base and highlighting continued demand from existing customers.

    Winking Studios also maintained a strong financial position. Cash, cash equivalents and bond investments stood at US$24.6 million, while gearing remained low, giving the company financial flexibility to continue funding its North American expansion and AI strategy.

    Second-half revenue expected to strengthen

    Winking Studios expects revenue in the second half of 2026 to exceed the level recorded during the first six months, supported by continued strength in its core art outsourcing operations.

    The company reported indicative bookings of US$51.6 million covering the next 24 months, providing a substantial pipeline of potential future work.

    Despite the positive revenue outlook, the board expects Winking Studios to record a modest adjusted EBITDA loss for the full year. The company is prioritising investment in AI-native development capabilities and the expansion of its North American platform as it seeks to compete for larger projects and establish sustainable long-term growth.

    More about Winking Studios Limited

    Winking Studios Limited is a Singapore-headquartered provider of AAA game art outsourcing and game development services, with listings in London and Singapore. The group operates 14 studios across Asia and North America and employs more than 1,400 people.

    Its global customer base includes 22 of the world’s 25 largest game publishers, with services spanning art outsourcing, game development and publishing.

    Winking Studios operates through three principal segments: Art Outsourcing, Game Development, and Global Publishing & Other Services. Its activities are delivered through four complementary brands — Winkingworks, Mineloader, Vertic and Ampera — giving the group an integrated platform within the increasingly consolidated global video game outsourcing industry.

  • Caledonia Mining Builds on Improved Gold Production with Bilboes Set to Drive the Next Phase of Growth

    Caledonia Mining Builds on Improved Gold Production with Bilboes Set to Drive the Next Phase of Growth

    For gold producers, delivering strong production and cash flow from an established mine is one thing. Building a second major growth engine capable of transforming the scale of the business is another.

    That is the opportunity increasingly coming into focus at Caledonia Mining, where a profitable producing operation at the Blanket gold mine is providing a strong foundation while the company advances its much larger Bilboes project and a pipeline of additional exploration opportunities.

    Speaking about the company’s latest results, Mark Learmonth, CEO of Caledonia Mining( NYSE AMERICAN, AIM and VFEX: CMCL), highlighted the significant improvement achieved during the second quarter and the growing potential across the wider portfolio.

    Stronger Quarter Highlights Operational Momentum

    Caledonia’s second-quarter performance demonstrated the benefits of improved grades at Blanket, with gold production increasing substantially from the first quarter.

    Learmonth explained that the improvement was driven mostly by higher grades, an important factor in the economics of an underground mining operation.

    With the company processing ore at a relatively fixed cost per tonne, higher grades can translate directly into stronger margins and increased cash generation.

    That operational improvement, together with a substantially higher realised gold price, was reflected in the financial numbers. Caledonia generated approximately $46 million of EBITDA during the quarter, alongside around $17.4 million of free cash flow after capital expenditure.

    The result reinforces the strength of Blanket as a cash-generating asset and gives Caledonia an important platform from which to fund its next stage of growth.

    As Learmonth put it, Caledonia is now a highly profitable operation, with Blanket continuing to provide the cash generation needed to support the company’s broader strategy.

    Blanket Provides the Foundation

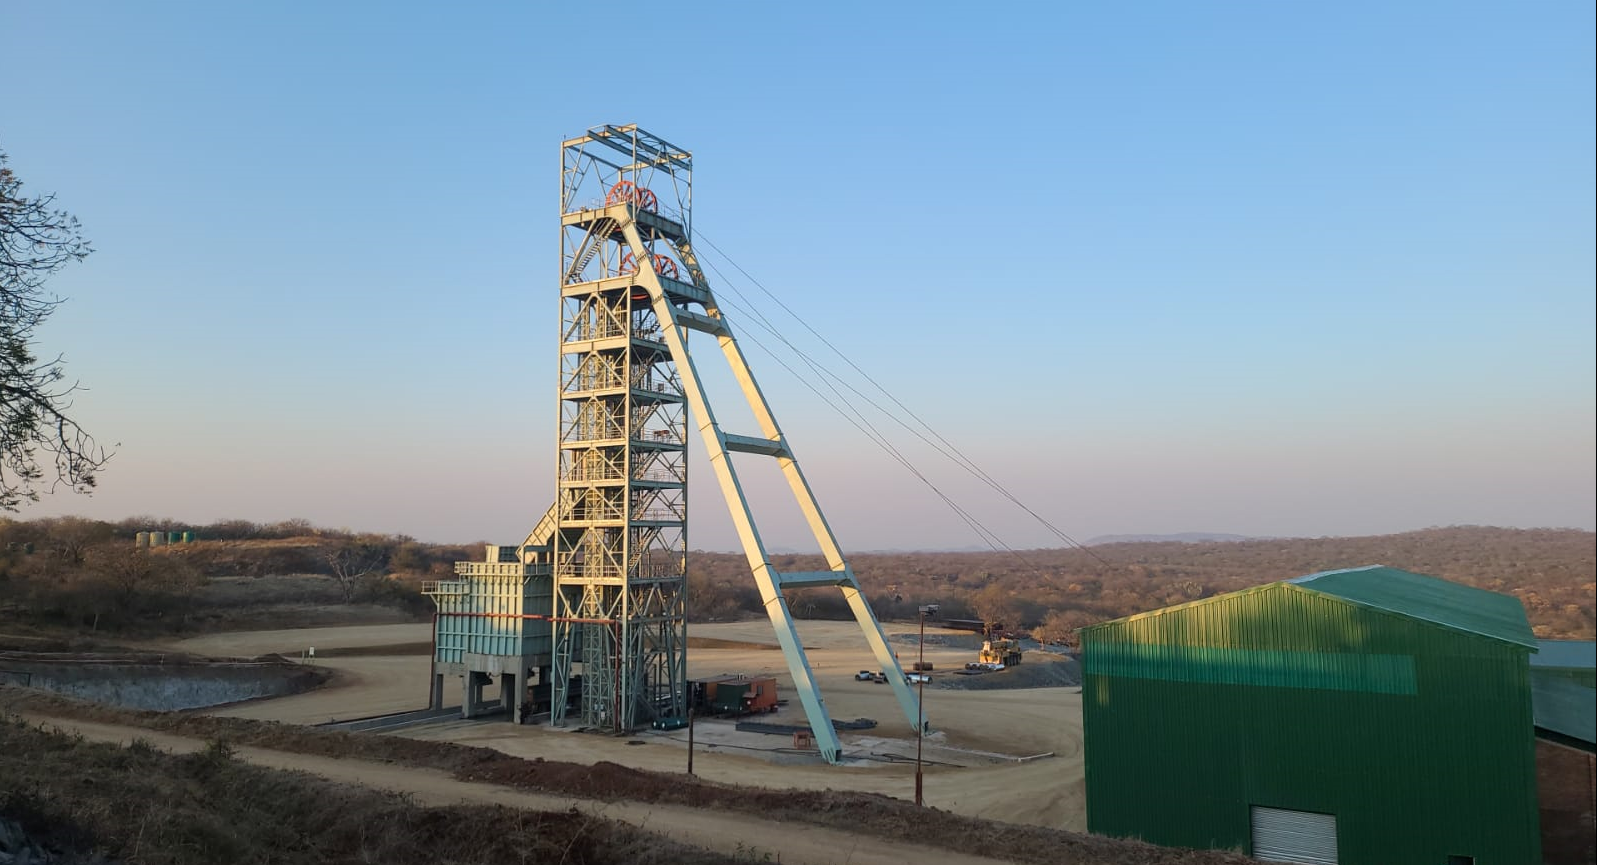
    The Blanket mine has a remarkable history, having been in operation for around 120 years.

    Today, the Zimbabwe-based operation produces approximately 75,000 ounces of gold per year, providing Caledonia with an established production base and a source of recurring cash flow.

    While Blanket remains central to the company, management’s focus is increasingly turning towards what the asset can help fund next.

    That brings Bilboes firmly into the spotlight.

    Bilboes Could Transform Caledonia’s Scale

    Described by Learmonth as the company’s major growth opportunity, Bilboes is a large, high-grade gold project that Caledonia is now advancing towards construction.

    The company is working on a funding package of approximately $600 million, supported by its existing cash generation and financing initiatives, including a successful convertible bond raise earlier in the year.

    With the financing process progressing and construction expected to begin later in 2026, Bilboes is moving from development concept towards becoming a significant future production asset.

    The current timeline points towards first gold towards the end of 2028, followed by the first full year of production in 2029.

    And the projected scale is significant.

    Bilboes is expected to produce approximately 200,000 ounces of gold per year in its first full year of production, more than double the current annual production level at Blanket.

    The project is also expected to benefit from a relatively low all-in sustaining cost of around $1,150 per ounce, reflecting the high-grade nature of the orebody.

    That combination of scale, grade and anticipated costs could make Bilboes a transformational asset for Caledonia.

    A Portfolio That Could Continue to Grow

    Bilboes is not the only growth opportunity within Caledonia’s portfolio.

    Immediately adjacent to Bilboes is the Motapa exploration project, where the company expects to publish an initial resource estimate in the coming weeks.

    While further exploration will be required to establish the project’s full potential, Motapa could ultimately provide additional flexibility for the Bilboes operation.

    It could potentially support higher production rates or extend the life of the mine, giving Caledonia another avenue through which to increase the value generated from its Zimbabwean portfolio.

    Meanwhile, the recently identified K-pits discovery at Blanket provides another near-term opportunity.

    Caledonia expects to publish a resource statement for K-pits in the coming weeks, with the potential for oxide mining and processing to generate relatively rapid cash flow.

    Longer term, the company is also optimistic about the possibility of identifying a deeper sulphide resource, which could build on the geological characteristics that underpin Blanket’s existing operation.

    From Producer to Growth Story

    What makes Caledonia increasingly interesting is therefore the combination of an existing cash-generating mine and a potentially transformational development project.

    Blanket provides production, cash flow and support for the company’s dividend, while the wider portfolio offers multiple opportunities for future growth.

    Bilboes represents the immediate focus, with construction potentially beginning this year and first gold targeted towards the end of 2028.

    Motapa could provide additional resources around Bilboes, while K-pits offers a potentially shorter-term opportunity at Blanket and the prospect of further sulphide discoveries adds longer-term exploration upside.

    For investors following the gold sector, that creates a compelling evolution in Caledonia’s story.

    The company is not simply looking to maintain production from an established mine. It is using the cash-generating strength of Blanket to advance a much larger, high-grade project that could dramatically increase production and cash flow over the coming years.

    With stronger second-quarter results demonstrating the underlying profitability of the business and Bilboes moving closer to construction, Caledonia Mining appears to be entering an important new chapter.

    For Mark Learmonth and his team, the objective is increasingly clear: use a profitable producing asset as the foundation for building a significantly larger gold business.

    And with Bilboes, Motapa and the K-pits all contributing to the company’s future growth pipeline, the next phase of Caledonia Mining’s story could prove considerably bigger than its current production base suggests.

    For more information visit – https://www.caledoniamining.com/