Blog

  • JD Sports shares slip as Nike warns turnaround will take longer than expected (JD.)

    JD Sports shares slip as Nike warns turnaround will take longer than expected (JD.)

    Nike outlook weighs on sports retail sector

    Shares in JD Sports (LSE:JD.) fell around 2% on Wednesday after sportswear giant Nike (NYSE:NKE) warned that its turnaround remains a work in progress, with further revenue declines expected as weakness in China continues to weigh on performance.

    Nike reported a 1% decline in fiscal fourth-quarter revenue and said sales are likely to fall further during the first half of fiscal 2027 as it continues to navigate intense competition and elevated inventory levels.

    Better-than-expected earnings fail to reassure investors

    Although Nike’s quarterly revenue came in slightly ahead of market expectations, the results did little to convince investors that the recovery strategy introduced by Chief Executive Elliott Hill nearly two years ago is gaining sufficient momentum.

    Nike shares have fallen around 35% since the start of the year and were down a further 3% in pre-market trading on Wednesday following the earnings release.

    China remains the biggest challenge

    Greater China continued to be Nike’s weakest-performing region, with sales declining 17% on a constant currency basis during the quarter, compared with a 10% fall in the previous reporting period.

    While the result was slightly better than Nike’s earlier forecast for a 20% decline, the company continues to lose market share to domestic competitors as consumers respond to stronger local product offerings. Greater China represents roughly 15% of Nike’s annual revenue and remains its third-largest market.

    Elsewhere, North American revenue increased 3%, supported by efforts to rebuild relationships with wholesale partners after the previous management team shifted its strategy towards direct-to-consumer sales.

    Nike also exceeded earnings expectations, reporting adjusted earnings of 20 cents per share, ahead of analysts’ consensus forecast of 13 cents, according to LSEG.

  • Market Open: Primark Profit Warning, Topps Tiles Heatwave Impact

    Market Open: Primark Profit Warning, Topps Tiles Heatwave Impact

    FTSE 100 opens steady as investors monitor PMI data and geopolitics while ABF warns on profits, Topps Tiles flags weaker trading and Brent crude rises.

    Market Overview

    UK markets opened mixed, with the FTSE 100 edging 0.001 per cent higher to 10,497.60, while the Euronext 100 slipped 0.02 per cent to 1,925.91, and the DAX fell 0.04% to 24,986.41. Overnight, the Nasdaq closed higher at 26,213.72 and the S&P 500 gained to 7,499.36 as investors balanced stronger US technology stocks against caution ahead of PMI data, eurozone inflation figures, central bank commentary and developments surrounding Iran-Qatar diplomacy.

    Commodity markets reflected ongoing geopolitical uncertainty. Brent crude firmed as hopes for renewed US-Iran engagement faded, while copper and natural gas weakened and gold also fell. Against sterling, the US dollar strengthened, the euro, Swiss franc and Australian dollar were little changed, while the Japanese yen weakened. Bitcoin traded slightly higher versus sterling.


    Market Numbers

    FTSE 100: Up (+0.00%), 10,497.60
    Euronext 100: Down (-0.02%), 1,925.91
    DAX: Down (-0.04%), 24,986.41
    NASDAQ: Up, 26,213.72
    S&P 500: Up, 7,499.36


    In the Headlines

    Profit warning – Associated British Foods (LSE:ABF)
    Primark owner Associated British Foods warned full-year profits are expected to be lower after higher natural gas prices increased costs at its sugar business. The update highlights continued pressure on energy-intensive operations despite resilient retail trading.

    Retail slowdown – Topps Tiles (LSE:TPT)
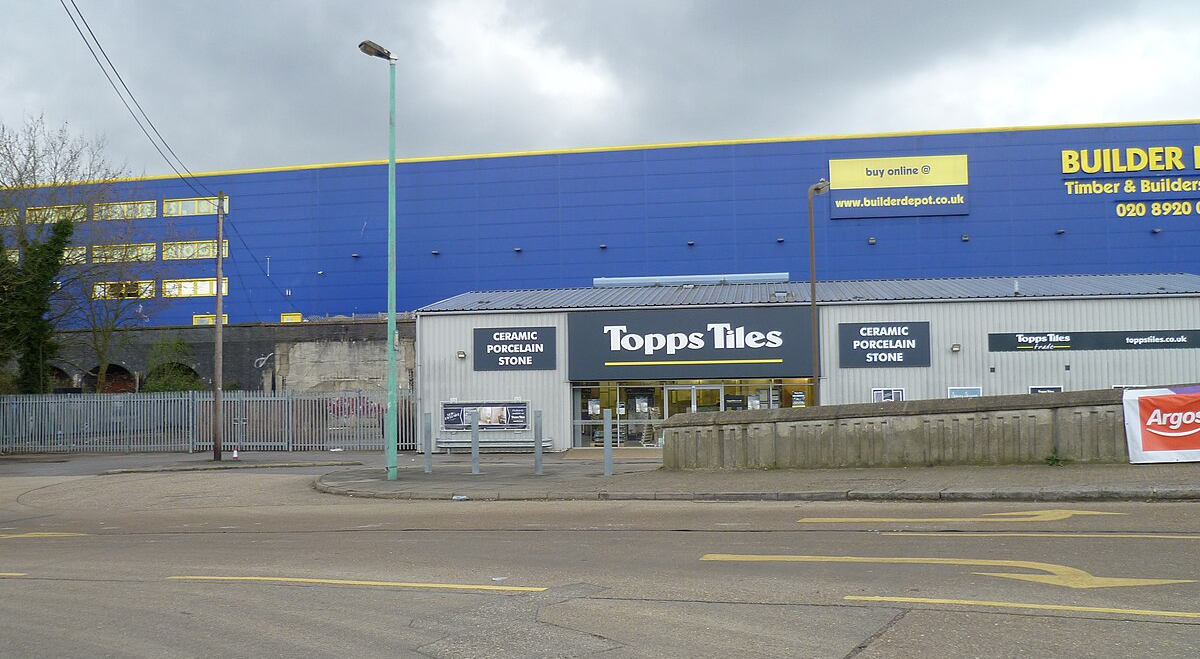
    Topps Tiles said prolonged hot weather added to already challenging trading conditions, with the heatwave reducing customer footfall. The update underlines the pressures facing UK discretionary retailers despite broader signs of consumer resilience.


    Currencies (vs GBP)

    USD: Down (-0.02%), $1.3250
    CHF: Up (+0.01%), Fr.1.0716
    EUR: Unchanged (0.00%), €1.1609
    JPY: Down (-0.01%), ¥215.4925
    AUD: Unchanged (0.00%), $1.9169
    Bitcoin (BTC/GBP): Up, £44,310


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Down

  • MedPal AI Opens Landmark Robotics Hub, Surpassing Major UK Pharmacy Facilities in Scale and Capacity

    MedPal AI Opens Landmark Robotics Hub, Surpassing Major UK Pharmacy Facilities in Scale and Capacity

    MedPal AI plc (LSE:MPAL) has announced the opening of Sarus Court, its largest and most advanced robotic pharmacy dispensing and distribution facility to date, marking a significant expansion in the company’s UK healthcare infrastructure.

    The NHS-approved site in Runcorn represents a major milestone in MedPal AI’s growth strategy, combining large-scale automation, AI-driven workflow systems and high-volume dispensing capability within a single integrated facility.

    A major leap in scale and automation

    Sarus Court spans approximately 23,000 sq ft when fully completed, making it the largest robotic pharmacy facility in MedPal AI’s network. The site is designed to process more than 10,000 prescription items per day at full capacity, scaling from an initial operational level of over 2,000 items per day as commissioning progresses.

    Backed by more than £1 million of investment in robotics, automation and proprietary pharmacy technology, the facility is engineered to deliver high-efficiency dispensing at scale, supporting both NHS and private prescription services through a direct-to-patient model.

    At full output, Sarus Court will be capable of handling more than 300,000 prescription items per month, placing it among the highest-capacity automated pharmacy operations in the UK.

    Positioned among the UK’s most advanced pharmacy hubs

    The company highlighted Sarus Court’s scale and design efficiency in comparison with other major UK pharmacy infrastructure developments.

    As part of its statement, MedPal AI CEO Jason Drummond said:

    “Sarus Court is a major statement of intent for MedPal AI. It is our largest robotic pharmacy distribution facility to date, NHS-approved for the new location, and designed to give us the operational headroom to scale from approximately 2,000 prescription items per day today to more than 10,000 items per day when fully completed.

    “We have invested over £1 million in robotics, automation and our pharmacy technology stack to create a platform that we believe can become one of the most sophisticated and lowest-cost dispensing operations in the UK.

    “The size and capacity of Sarus Court place MedPal AI firmly among the most ambitious technology-led pharmacy operators in the UK. At 23,000 sq ft when fully completed, the facility is larger by footprint than Boots’ recently opened 20,000 sq ft Basingstoke dispensing hub, while its designed item capacity is significantly above the monthly item levels currently reported by leading individual Well and Boots pharmacy entries on PharmData.

    “This facility gives MedPal AI the scale, automation and resilience required to support the next phase of our growth across NHS dispensing, private prescriptions, AI-enabled patient engagement and direct-to-patient pharmacy fulfilment.”

    Strengthening a national digital health platform

    Sarus Court will operate alongside MedPal AI’s existing Swaffham facility and replaces its previous Runcorn distribution site. The phased commissioning approach ensures immediate operational output while enabling a smooth ramp-up to full capacity.

    The facility forms a core part of MedPal AI’s broader digital health ecosystem, which integrates AI-powered wellness tools, clinical services and automated pharmacy fulfilment. Through its MedPal Health OS platform, the company connects user health data from wearable devices and health applications into a unified system designed to support personalised care pathways and efficient medication delivery.

    Building future-ready healthcare infrastructure

    With NHS approval secured and advanced robotic systems now being commissioned, Sarus Court represents a significant expansion of MedPal AI’s operational footprint. The facility strengthens the company’s position in the evolving UK pharmacy landscape, where automation, scale and digital integration are increasingly central to service delivery.

    As commissioning continues, Sarus Court is expected to play a key role in supporting MedPal AI’s long-term growth strategy across NHS dispensing, private prescriptions and AI-enabled healthcare services.

    For more information visit https://medpal.co/
  • Carclo improves profitability and launches Precision 2030 growth strategy (CAR)

    Carclo improves profitability and launches Precision 2030 growth strategy (CAR)

    Higher margins offset lower revenue in FY2026

    Carclo (LSE:CAR) reported lower revenue for the year ended 2026, but delivered a significant improvement in profitability as the precision engineering group continued its shift away from lower-margin business towards higher-value engineered solutions.

    Revenue declined to £114.2 million, while underlying operating profit increased 28.1% to £12.6 million. Return on sales improved to 11% and return on capital employed reached 29.1%, supported by operational efficiencies and the renewal of a key long-term contract in the life sciences sector despite mixed trading conditions across its end markets.

    Precision 2030 plan targets long-term organic growth

    Following the completion of its three-year turnaround programme, Carclo has introduced its new Precision 2030 strategy, setting long-term targets of more than 8% compound annual organic revenue growth, net debt below 0.5 times EBITDA, and minimum returns of 10% return on sales and 25% return on capital employed.

    Management expects future growth to be driven by expanding relationships with existing customers, entering adjacent high-growth markets including drug delivery and wearable technologies, and developing new precision engineering solutions. The company also expects continued strength in aerospace demand, while anticipating a recovery in life sciences volumes later this year.

    Operational progress balanced by financial challenges

    Carclo’s investment outlook continues to be constrained by financial risks, including negative shareholder equity and relatively weak net profitability.

    Technical indicators also remain negative, with the shares trading below key moving averages and supported by a negative MACD signal. These factors outweigh encouraging operational improvements and positive management commentary. In addition, the company’s valuation remains relatively demanding, with a price-to-earnings ratio of around 29 and no dividend yield to support the investment case.

    More about Carclo plc

    Carclo plc is a global precision engineering company supplying highly engineered components and assemblies for the life sciences, aerospace, safety and security sectors. Through its Carclo Technical Plastics and Speciality divisions, the group designs and manufactures precision injection-moulded products for customers operating in highly regulated and mission-critical industries.

  • CMC Markets raises FY2027 income guidance as B2B platform growth accelerates (CMCX)

    CMC Markets raises FY2027 income guidance as B2B platform growth accelerates (CMCX)

    Strong institutional demand drives upgraded outlook

    CMC Markets (LSE:CMCX) has raised its guidance for FY2027 after reporting rapid growth across its business-to-business trading platform operations, highlighting increasing demand from institutional and financial services partners.

    The company now expects net operating income of at least £550 million for FY2027, significantly above its previous guidance range of £460 million to £480 million. At the same time, CMC Markets reaffirmed its operating expense guidance, excluding variable remuneration, at approximately £280 million.

    Scalable platform supports higher margins

    Management said the improved outlook reflects exceptional growth in the group’s B2B platform business, where its established online and mobile trading infrastructure is supporting a growing network of institutional partnerships.

    The company believes the expansion is generating greater operational leverage and improving profit margins while creating a strong pipeline of future opportunities that are expected to deliver additional milestones over the next 12 months. CMC Markets continues to invest in its technology platform and broad product offering as it seeks to strengthen its position across global financial markets.

    Strong balance sheet offset by cash flow volatility

    CMC Markets’ investment outlook is supported by healthy profitability, a strong balance sheet and relatively low leverage, providing a solid financial foundation for future growth.

    Technical indicators also remain constructive, with the shares continuing to trade in an established upward trend. However, an elevated Relative Strength Index (RSI) suggests the stock may be approaching overbought levels, increasing the potential for near-term volatility. While valuation appears reasonable, the cyclical nature of the business limits its overall attractiveness.

    More about CMC Markets

    CMC Markets is a London-listed online trading and investment services provider founded in 1989. The company serves both retail and institutional clients through regulated operations in 12 countries, with major markets including the UK, Australia, Germany and Singapore. Its online and mobile platforms provide access to more than 12,000 financial instruments, including contracts for difference (CFDs), spread betting in selected markets and stockbroking services in the UK, Australia and Singapore.

  • Primary Health Properties refinances debt with new £800m unsecured banking facility (PHP)

    Primary Health Properties refinances debt with new £800m unsecured banking facility (PHP)

    New financing strengthens balance sheet and supports deleveraging (PHP)

    Primary Health Properties (LSE:PHP) has secured a new £800 million unsecured term loan and multi-currency revolving credit facility, replacing a number of existing borrowings as part of its strategy to simplify its financing structure and transition towards becoming a fully unsecured borrower.

    The facility has been arranged with a syndicate of eight banks, including three new lending partners, and is divided into three tranches with initial maturities of three and five years, together with extension options.

    Refinancing lowers borrowing costs and increases liquidity

    The company expects the refinancing to reduce its average cost of debt by around 40 basis points compared with the facilities being replaced once leverage returns to its target range.

    An initial £500 million has been drawn under the new facility and will be used to partially refinance the £1 billion bridge loan that funded the acquisition of Assura, while also repaying several secured and unsecured borrowing facilities. Following the refinancing, Primary Health Properties will have approximately £300 million of undrawn liquidity available, providing additional financial flexibility as it continues to reduce leverage.

    Attractive income profile balanced by leverage concerns

    Primary Health Properties’ investment outlook continues to benefit from an attractive valuation, supported by a moderate price-to-earnings ratio and a relatively high dividend yield.

    However, these strengths are offset by a mixed financial profile, with higher leverage levels and a significant deterioration in free cash flow during 2025. Technical indicators also remain weak, with the shares trading below key moving averages and a negative MACD signal pointing to subdued market momentum.

    More about Primary Health Properties plc R.E.I.T

    Primary Health Properties plc is a real estate investment trust specialising in healthcare properties across the UK and Ireland. The company owns, manages and finances primary care centres and other healthcare facilities, providing long-term property solutions for healthcare providers while generating rental income from a diversified portfolio of medical assets.

  • Supreme delivers record revenue as acquisitions and diversification fuel FY26 growth (SUP)

    Supreme delivers record revenue as acquisitions and diversification fuel FY26 growth (SUP)

    Sales reach new high despite margin pressure

    Supreme plc (LSE:SUP) reported record revenue for the year ended FY26, with sales increasing 17% to £270.2 million as recent acquisitions and continued growth in its Vaping division drove expansion across the business.

    Adjusted EBITDA remained broadly unchanged at £40.6 million despite lower margins and a decline in earnings per share. The company also generated strong operating cash flow, returned to an adjusted net cash position and increased its total dividend by 4%, highlighting the strength of its balance sheet and supporting continued investment in manufacturing capacity and brand development.

    Acquisitions expand drinks and wellness portfolio

    The group’s Drinks & Wellness division recorded revenue growth of 60% to £69.3 million, benefiting from the additions of SlimFast and Clearly Drinks.

    During the year, Supreme invested around £6 million in new production facilities, including its wellness manufacturing site, The Hive, and expanded tea production through Typhoo. The company also strengthened its portfolio through the acquisitions of SlimFast and 1001, secured new drinks licensing agreements with Carabao and Tonino Lamborghini, and continued expanding its international footprint. Management believes these initiatives position the business to benefit from consolidation within the vaping market while increasing diversification across multiple fast-moving consumer goods categories.

    Strong fundamentals offset weaker technical signals

    Supreme’s investment outlook is supported by robust financial performance, successful acquisitions and continued strategic expansion, all of which have contributed to strong revenue growth.

    The shares also benefit from an attractive valuation. However, technical indicators remain weaker, with recent price action pointing to negative short-term momentum that may temper investor sentiment.

    More about Supreme PLC

    Supreme plc is a UK-based manufacturer, distributor and brand owner operating across the Vaping, Drinks & Wellness, and Electricals & Household sectors. The company manages a vertically integrated business model spanning product development, manufacturing and distribution, supplying more than 3,000 business customers and approximately 55,000 retail outlets with a combination of proprietary and third-party consumer brands.

  • Clean Power Hydrogen launches up to £7.5m fundraising to accelerate electrolyser development (CPH2)

    Clean Power Hydrogen launches up to £7.5m fundraising to accelerate electrolyser development (CPH2)

    Capital raise to support commercial progress and technology validation

    Clean Power Hydrogen (LSE:CPH2) has announced plans to raise up to £7.5 million through a multi-stage equity fundraising priced at 1.5 pence per share.

    The fundraising includes a £2.54 million firm placing, a £0.46 million conditional placing, a proposed subscription of up to £4 million from West Hill clients, a £10,000 directors’ subscription and a retail offer targeting at least £0.5 million. The firm placing is expected to complete in early July, while the remaining elements are subject to shareholder approval later this month.

    The proceeds will be used to support the company’s capital-light strategy and continue the development and validation of its membrane-free electrolysis technology following the recent testing incident involving its 1MW MFE220 system.

    Membrane-free technology remains central to growth plans

    CPH2’s proprietary Membrane-Free Electrolyser technology is designed to eliminate the need for expensive membranes and critical raw materials while producing hydrogen with a purity of 99.999 mol% alongside 99.7% oxygen.

    The fundraising follows the company’s investigation into a non-injury incident during final factory testing of the MFE220 unit. Management said the review concluded that the core electrolyser stack was not responsible for the incident and confirmed that the company is seeking a manufacturing partner to complete the remaining testing programme. These steps are expected to be important in rebuilding market confidence, advancing commercialisation and strengthening CPH2’s position within the growing green hydrogen sector.

    Financial pressures continue despite improving technical outlook

    Clean Power Hydrogen’s investment outlook remains constrained by a weak financial profile, characterised by minimal revenue, widening losses, significant cash burn and a substantially reduced equity base.

    Technical indicators have improved, with the shares showing a positive trend and stronger market momentum. However, an elevated Relative Strength Index (RSI) suggests there is an increased risk of short-term share price volatility. Valuation remains difficult to assess given the company’s ongoing losses and the absence of a dividend.

    More about Clean Power Hydrogen PLC

    Clean Power Hydrogen plc is a UK-based developer of green hydrogen technologies specialising in patented membrane-free electrolysers capable of producing high-purity hydrogen and medical-grade oxygen. Its modular systems are designed for customers requiring advanced electrolysis and gas handling solutions, addressing a global electrolyser market estimated to be worth more than $14 billion.

  • Polar Capital reaches record £30.6bn in assets under management as technology funds drive growth (POLR)

    Polar Capital reaches record £30.6bn in assets under management as technology funds drive growth (POLR)

    Strong investment performance lifts assets to new high

    Polar Capital (LSE:POLR) delivered a strong performance for the year ended 31 March 2026, with assets under management (AuM) increasing 43% to a record £30.6 billion.

    Average AuM rose 14% to £26.0 billion, supported by £8.8 billion of investment performance and market appreciation, alongside net inflows of £902 million. Technology and artificial intelligence strategies generated the strongest investor demand, helping technology-focused funds account for 55% of total assets. The group also continued to diversify its client base geographically, with a lower proportion of assets originating from the UK and increased contributions from Europe and Asia.

    Higher profits support dividend and share buyback

    Financial performance improved during the year, with core operating profit rising 11% to £62.8 million and statutory profit before tax increasing 49% to £76.9 million.

    The company maintained its total dividend at 46.0p per share and announced a new £15 million share buyback programme. Management also introduced an updated corporate strategy focused on expanding through differentiated active investment strategies, increasing investment in data and artificial intelligence capabilities, and implementing a revised capital allocation policy that aims to return at least 50% of adjusted core profits to shareholders. The measures reflect confidence in the group’s long-term prospects despite continuing industry challenges facing active equity managers.

    Strong fundamentals support investment outlook

    Polar Capital’s investment outlook is underpinned by a strong balance sheet, low leverage, solid return on equity and an attractive valuation, supported by a relatively low price-to-earnings ratio and a high dividend yield.

    Technical indicators also remain favourable, with the shares trading above key moving averages and supported by a positive MACD signal. However, relatively high share price volatility and some pressure on profit margins temper the overall outlook.

    More about Polar Capital Holdings

    Polar Capital Holdings is a specialist active asset manager offering a range of investment strategies focused on sectors including technology, artificial intelligence, healthcare and smart energy. The company manages open-ended funds, investment trusts and segregated mandates for institutional and retail clients, with a growing international investor base spanning Europe, Asia and other global markets.

  • Topps Tiles maintains resilient sales as cost savings and digital growth support performance (TPT)

    Topps Tiles maintains resilient sales as cost savings and digital growth support performance (TPT)

    Market weakness weighs on third-quarter revenue

    Topps Tiles (LSE:TPT) reported third-quarter group revenue of £75.6 million, down 1.8% from the previous year as subdued consumer demand, CTD store closures and the closure of underperforming Topps Tiles locations affected sales.

    Excluding the impact of CTD, core revenue edged 0.6% higher, while like-for-like sales at the Topps Tiles brand remained unchanged. Although the company continued to outperform the declining UK home improvement market, trading was weaker than anticipated as customers shifted towards lower-priced products and periods of hot weather disrupted activity across construction sites.

    Cost-saving measures and online growth support margins

    The group said it continued to make progress on initiatives designed to improve efficiency and protect profitability, including optimising its store estate, introducing a more flexible labour model and consolidating head office operations.

    Digital sales continued to expand, with online revenue accounting for 23.3% of total sales during the quarter. The launch of a new trade-focused mobile app also supported professional customers, while newer hard surface categories such as acoustic panels and outdoor tiles delivered double-digit growth. Despite these positive developments, the company expects adjusted pre-tax profit for the year to be slightly above £6.5 million as broader economic challenges continue to affect demand.

    Cash generation offsets balance sheet concerns

    Topps Tiles’ investment outlook is supported by improving financial performance, strong cash generation and ongoing cost-saving initiatives, alongside a generally constructive earnings outlook.

    However, these strengths are balanced by relatively high balance sheet leverage and weaker technical indicators, including a negative MACD signal and a share price trading below key moving averages. The valuation also appears relatively demanding, although the company’s dividend yield continues to provide support for income-focused investors.

    More about Topps Tiles

    Topps Tiles is the UK’s largest specialist retailer of tiles and hard surface flooring products, supplying ceramic and porcelain tiles, flooring accessories and related materials to both retail and trade customers. The group operates its core Topps Tiles business alongside the recently acquired CTD brand and continues to expand its digital capabilities while serving the home improvement and commercial construction markets.