Blog

  • Journeo Secures £1.3m Metroline Manchester Deal to Supply Bus Safety and SaaS Solutions (JNEO)

    Journeo Secures £1.3m Metroline Manchester Deal to Supply Bus Safety and SaaS Solutions (JNEO)

    Metroline Manchester Selects Journeo for New Bus Fleet Technology

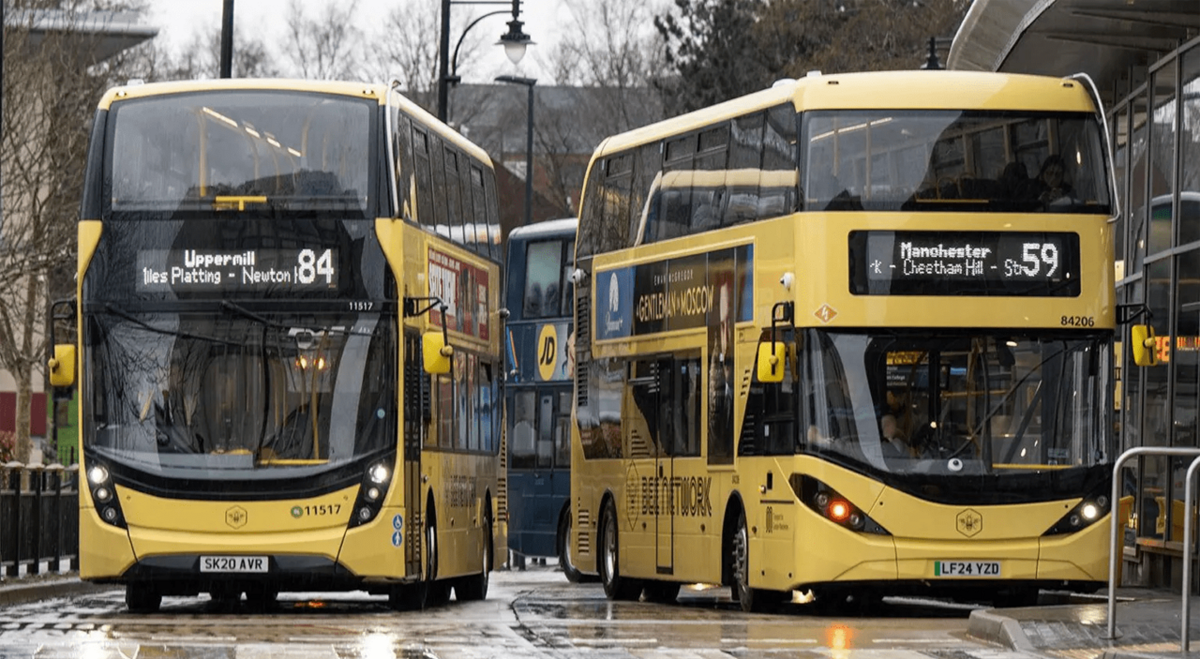
    Journeo (LSE:JNEO) has been awarded £1.3 million of purchase orders from Metroline Manchester to provide advanced onboard safety and connectivity systems for a new fleet of Wrightbus Electroliner vehicles.

    The contract includes the deployment of Journeo’s latest digital CCTV technology and digital wing mirror systems, designed to improve operational safety and support fleet management requirements.

    The agreement strengthens Journeo’s presence within the UK public transport sector and further expands its installed base of connected vehicle technologies.

    Cloud-Connected Platform Enhances Fleet Operations

    Each vehicle delivered under the contract will be equipped with a Journeo Edge gateway connected to the company’s cloud-based Journeo Portal platform.

    The integrated system enables authorised users to securely access video footage for incident investigations while also providing engineering teams with remote monitoring and diagnostic capabilities.

    Management believes the combination of onboard hardware and cloud-based software offers transport operators greater visibility, improved safety oversight and more efficient fleet maintenance.

    Long-Term SaaS Revenue Opportunity

    In addition to the hardware deployment, Metroline Manchester will become a user of Journeo’s high-security software-as-a-service platform.

    The arrangement is expected to generate recurring licence and support revenues extending through 2027 and beyond, increasing the proportion of predictable software income within the group’s revenue mix.

    Management continues to focus on expanding recurring revenue streams as part of its broader strategy to enhance earnings visibility and improve long-term margins.

    Contract Strengthens Position in UK Bus Market

    Metroline Manchester operates more than 400 buses across four Bee Network franchises in Greater Manchester and forms part of the international transport group ComfortDelGro.

    Winning the contract reinforces Journeo’s position as a preferred supplier of integrated safety, connectivity and information systems for public transport operators.

    The company believes growing demand for digital safety technologies, connected vehicle platforms and data-driven fleet management solutions continues to create attractive opportunities across the UK transport sector.

    Hardware Revenue to Support Near-Term Performance

    Most of the hardware-related revenue associated with the contract is expected to be recognised during the current financial year.

    The project therefore provides both near-term revenue visibility and a longer-term stream of recurring software income, supporting the company’s transition towards a more subscription-based business model.

    Management sees the combination of upfront hardware sales and ongoing SaaS revenues as an increasingly important driver of shareholder value.

    Outlook Supported by Growth and Recurring Revenue Expansion

    Journeo’s outlook continues to benefit from strong underlying business fundamentals, including revenue growth, improving profitability, lower leverage and stronger recent cash generation.

    The company’s growing base of recurring software revenues provides additional support to future earnings visibility and margin potential.

    While technical indicators remain weak and the shares continue to trade below key moving averages, management believes operational momentum and continued contract wins demonstrate the strength of the business.

    Valuation remains supportive, with the company trading on a relatively modest earnings multiple compared with its growth profile.

    More about Journeo

    Journeo plc is a UK-based provider of intelligent transport systems, connected vehicle technologies and critical infrastructure solutions.

    The company supplies digital CCTV, telematics, passenger information systems, fleet connectivity platforms and infrastructure security solutions to customers across the bus, rail, airport and critical national infrastructure sectors. Through its cloud-based SaaS and IoT-enabled technologies, Journeo helps transport operators improve safety, operational efficiency and passenger experience while generating recurring software and support revenues.
  • EnSilica Delivers Record Results as Supply Revenues and Contract Momentum Drive Growth (ENSI)

    EnSilica Delivers Record Results as Supply Revenues and Contract Momentum Drive Growth (ENSI)

    Revenue and EBITDA Reach New Highs

    EnSilica (LSE:ENSI) reported a record performance for the year ended 31 May 2026, with revenue increasing 51% to £27.5 million and EBITDA rising to £4.7 million.

    The company also strengthened its financial position through an oversubscribed £10 million equity fundraising, providing additional resources to support its growth strategy and expanding semiconductor supply operations.

    Management said the results reflect continued progress in transforming the business from a pure design services provider into a semiconductor design-and-supply platform capable of generating recurring long-term revenue streams.

    Lifetime Supply Revenues Continue to Expand

    A key driver of growth was the continued expansion of EnSilica’s semiconductor supply business.

    The group reported a 50% increase in lifetime supply revenues to $375 million, highlighting growing demand for its application-specific integrated circuits (ASICs) across multiple end markets.

    At the same time, the company’s sales pipeline expanded to approximately $600 million, spanning opportunities in the space, industrial and automotive sectors.

    Management believes this growing pipeline provides strong visibility for future revenue growth and supports the long-term scalability of the business.

    Shift Toward Supply Model Gains Momentum

    EnSilica’s strategic transition towards a design-and-supply model continued to gather pace during the year.

    The company now has five ASIC products in volume production, creating recurring semiconductor supply revenues alongside its traditional design activities.

    Several additional chip programmes are expected to move into production over the coming years, further increasing the contribution from higher-margin supply contracts.

    Management views this transition as a significant step in improving the predictability and profitability of the business.

    Strong Order Book Supports FY27 Expectations

    The company issued positive guidance for FY27, forecasting revenue of between £32 million and £34 million and EBITDA of £5.5 million to £6.5 million.

    EnSilica noted that approximately 80% of expected FY27 revenue is already secured through existing contracts and customer orders.

    This visibility is supported by a number of significant project wins, including satellite communications programmes and automotive semiconductor contracts.

    Management believes the high level of contracted revenue provides a solid foundation for continued growth in the year ahead.

    Space and Automotive Opportunities Offer Further Upside

    Several space-focused semiconductor programmes are still in development and have yet to make a meaningful contribution to financial performance.

    As these projects move into production and supply phases, management expects them to become increasingly important revenue drivers.

    The company also continues to benefit from growing demand for specialised semiconductors in automotive and industrial applications, where customers require high levels of reliability, safety and long-term product availability.

    These markets remain a central focus of EnSilica’s growth strategy.

    Outlook Supported by Recurring Revenue Growth

    EnSilica believes the increasing contribution from semiconductor supply revenues will support both earnings growth and margin expansion over time.

    The company is seeking to build a more balanced revenue mix, combining engineering services with recurring product supply income generated from long-term customer relationships.

    Management expects this model to enhance profitability, improve cash generation and strengthen the group’s competitive position in specialist semiconductor markets.

    Outlook Reflects Growth Potential Despite Ongoing Challenges

    While EnSilica has delivered strong operational progress and significant revenue growth, investors continue to assess the company’s path towards sustained profitability and stronger cash flow generation.

    Technical indicators remain supportive following recent share price momentum, although some measures suggest the stock may be approaching overbought territory.

    The absence of a dividend and the company’s ongoing investment requirements remain considerations, but management believes the expanding supply business and growing order book provide a compelling platform for future growth.

    More about EnSilica

    EnSilica is a UK-based fabless semiconductor company specialising in the design and supply of application-specific integrated circuits for communications, industrial, automotive and space applications.

    The company develops complex mixed-signal, RF, mmWave and digital semiconductor solutions, leveraging proprietary intellectual property and reusable design platforms. Its business model combines chip design services with long-term semiconductor supply contracts, creating recurring revenue opportunities across specialised, high-growth markets where performance, security and reliability are critical.

  • Telecom Plus Raises Profits, Announces £40m Buyback and Sets Out Ambitious Five-Year Growth Strategy (TEP)

    Telecom Plus Raises Profits, Announces £40m Buyback and Sets Out Ambitious Five-Year Growth Strategy (TEP)

    Revenue and Profit Continue to Grow as Customer Base Expands

    Telecom Plus (LSE:TEP), which operates under the Utility Warehouse brand, delivered another year of growth for the 12 months ended 31 March 2026.

    Revenue increased by 5.6% to £1.94 billion, while adjusted pre-tax profit rose 4.7% to £132.2 million. The company also recorded strong customer growth, with total customer numbers rising 23.3% to 1.43 million.

    The increase was supported by the acquisition of broadband customers from TalkTalk, which contributed to the expansion of the group’s multi-service customer base.

    Shareholder Returns Enhanced Through Dividends and Buybacks

    The company increased total shareholder distributions to 100 pence per share and unveiled a new £40 million share repurchase programme.

    The buyback forms part of a broader capital allocation framework under which Telecom Plus intends to return at least 80% of adjusted profit after tax to shareholders through a combination of dividends and share repurchases.

    Management indicated that buybacks will be used when the company’s shares trade below a predetermined earnings multiple, providing flexibility in how capital is returned to investors.

    The policy reflects the board’s confidence in the group’s cash generation and long-term growth prospects.

    Partner Network and Cross-Selling Strategy Drive Momentum

    Telecom Plus continued to expand its nationwide Partner network, which grew to 77,200 members during the year.

    The company also made progress integrating the TalkTalk broadband customer base, creating opportunities to cross-sell additional Utility Warehouse services and increase customer value over time.

    Management highlighted ongoing recognition for both value and customer service across its energy and broadband offerings, reinforcing the company’s competitive positioning in the UK household services market.

    New Five-Year Plan Targets Significant Customer Growth

    Alongside its annual results, Telecom Plus outlined a new five-year investment strategy extending to FY31.

    The plan aims to more than double the number of higher-quality multi-service customers to over one million and is centred on four key priorities: enhancing the customer proposition, expanding the Partner channel, increasing national brand awareness and strengthening digital capabilities.

    Management believes these initiatives will support sustained growth, deeper customer engagement and stronger long-term earnings quality.

    Investment Programme to Weigh on Near-Term Earnings

    While the company remains optimistic about its long-term growth trajectory, management acknowledged that increased investment will affect short-term profitability.

    As a result, adjusted profit guidance for FY27 has been reduced as the business commits additional resources to support customer acquisition, technology development and brand-building initiatives.

    The board believes these investments are necessary to create a larger, more resilient business capable of generating attractive returns over the long term.

    Outlook Balances Growth Ambition with Near-Term Challenges

    Telecom Plus’s outlook is supported by strong customer growth, an expanding Partner network and a clearly defined long-term strategy.

    The company’s investment programme is expected to strengthen its market position and enhance future earnings potential, although it will place pressure on profitability in the near term.

    Valuation remains attractive, supported by a strong dividend yield and a shareholder-friendly capital return policy.

    While technical indicators have been relatively weak recently, management believes the group’s growth opportunities and recurring revenue model provide a solid foundation for long-term value creation.

    More about Telecom Plus

    Telecom Plus, which trades as Utility Warehouse, is the UK’s only integrated provider of subscription-based household services.

    The company offers a range of essential services, including energy, broadband, mobile and insurance, through a single monthly bill. Its business model combines recurring customer revenues with a nationwide network of independent Partners who promote and distribute Utility Warehouse services.

    By bundling multiple household services together, Telecom Plus aims to improve customer retention, increase lifetime value and provide consumers with a convenient and cost-effective alternative to managing multiple providers.

  • Tern Shifts Focus to Portfolio Monetisation as Revised Valuations Reduce Asset Value (TERN)

    Tern Shifts Focus to Portfolio Monetisation as Revised Valuations Reduce Asset Value (TERN)

    Company Prioritises Value Realisation Over New Investments

    Tern plc (LSE:TERN) has released its audited results for 2025 and announced a General Meeting scheduled for 9 July 2026, where shareholders will be asked to approve the annual accounts, reappoint the company’s auditors and vote on the directors’ remuneration report.

    The investment company said its primary focus is now on generating returns from its existing portfolio rather than pursuing significant new investments. Management believes this approach better reflects current venture capital market conditions and aligns capital allocation decisions more closely with shareholder interests.

    The strategy marks a shift towards portfolio realisation as several investments mature and move closer to potential liquidity events.

    More Conservative Valuation Approach Reduces Reported Portfolio Value

    Tern disclosed that it has adopted a revised methodology for valuing its portfolio holdings, resulting in a lower reported fair value for its investments.

    The updated approach places greater emphasis on Tern’s specific ownership positions and takes account of factors such as preference share structures, bridge financing arrangements and other elements that can affect the value ultimately attributable to ordinary shareholders.

    Management stressed that the valuation adjustment reflects a more conservative accounting approach rather than a deterioration in the underlying operational progress of its portfolio companies.

    No Exits Completed During 2025 or 2026 to Date

    The company noted that no portfolio exits were completed during 2025 and that no disposals have been achieved so far in 2026.

    While the absence of exits has delayed value crystallisation for shareholders, management remains focused on positioning portfolio companies for future strategic transactions and liquidity events.

    The board reiterated its intention to return capital to shareholders following any material realisations achieved in the future.

    Core Portfolio Companies Continue to Make Progress

    Despite the reduction in reported portfolio value, Tern highlighted ongoing commercial progress across several of its key holdings.

    Management pointed to growing market traction at Device Authority, which operates in the Internet of Things security sector, as well as continued development at Talking Medicines, which applies artificial intelligence and data analytics to healthcare and pharmaceutical markets.

    The company believes these businesses, along with other core investments, continue to offer significant long-term value creation potential.

    Investor Communication Strategy Aims to Narrow Valuation Discount

    The board acknowledged the persistent gap between Tern’s market valuation and the underlying value of its investment portfolio.

    As part of its strategy, management intends to increase engagement with investors and improve communication around portfolio developments and valuation drivers.

    The company believes greater transparency may help narrow the discount at which its shares trade relative to net asset value.

    Outlook Reflects Ongoing Challenges and Long-Term Potential

    Tern’s outlook remains constrained by weak financial performance, including lower revenue, significant losses and negative operating and free cash flow.

    Technical indicators continue to suggest a prolonged period of share price weakness, although some measures indicate early signs of stabilisation following an extended decline.

    Valuation remains difficult to assess using conventional earnings-based metrics due to ongoing losses and the absence of a dividend.

    However, management maintains confidence in the long-term prospects of its portfolio and believes future exits could unlock substantial shareholder value.

    More about Tern

    Tern plc is an AIM-listed investment company focused on identifying, supporting and developing technology businesses operating in the Internet of Things, artificial intelligence, machine learning and data analytics sectors.

    The company takes active minority positions in early-stage and growth-stage businesses, providing strategic support alongside capital. Its portfolio includes investments in companies such as Device Authority, FundamentalVR and Talking Medicines, with exposure to markets including healthcare, industrial technology, automotive systems and cybersecurity.

  • Greencoat UK Wind Schedules Half-Year Results and Launches Share Buyback Programme (UKW)

    Greencoat UK Wind Schedules Half-Year Results and Launches Share Buyback Programme (UKW)

    Half-Year Results to Be Released in July

    Greencoat UK Wind PLC (LSE:UKW) has announced that it will publish its net asset value, quarterly dividend declaration and half-year results for the six months ended 30 June 2026 on 30 July 2026.

    The company will accompany the results release with a live webcast for investors and analysts, which will be accessible through its corporate website.

    In addition, Greencoat UK Wind will host a dedicated online presentation for retail investors on 31 July 2026 via the Investor Meet Company platform, giving both existing and prospective shareholders the opportunity to engage with management and submit questions before or during the session.

    Share Buybacks Form Part of Capital Allocation Strategy

    Alongside the results announcement, the board reaffirmed that share repurchases remain an important component of the company’s broader capital allocation framework.

    Management stated that buybacks will be deployed selectively when market conditions justify their use, alongside other priorities such as debt reduction and reinvestment in the portfolio.

    The company believes share repurchases can provide an effective mechanism for enhancing shareholder value when shares trade at a significant discount to underlying asset value.

    Jefferies Appointed to Execute Buybacks

    Greencoat UK Wind has appointed Jefferies International to manage share repurchases within the limits previously approved by shareholders.

    Any shares acquired under the programme may either be held in treasury or cancelled.

    Where shares are cancelled, the total number of shares in issue will decline, potentially increasing the ownership interest of remaining shareholders and improving the value of future dividend distributions on a per-share basis.

    Management views the programme as a flexible tool that can complement other capital allocation initiatives.

    Balancing Buybacks, Debt Reduction and Reinvestment

    The board emphasised that buybacks are only one element of its overall strategy for managing capital.

    The company continues to assess opportunities to strengthen the balance sheet through debt reduction while also evaluating reinvestment opportunities within its renewable energy portfolio.

    Management believes maintaining flexibility across these options allows the company to respond effectively to changing market conditions and maximise long-term shareholder returns.

    Dividend Yield Continues to Support Investment Case

    Greencoat UK Wind’s outlook remains influenced by recent earnings volatility, including losses and the absence of free cash flow generation during 2025.

    Technical indicators also remain relatively weak, with the shares trading below longer-term trend measures and momentum indicators remaining subdued.

    However, the company continues to benefit from one of the highest dividend yields in the listed renewable infrastructure sector, which remains a significant attraction for income-focused investors.

    Moderate leverage levels and positive operating cash flow generation also provide some support to the overall investment case.

    Outlook Focused on Long-Term Value Creation

    Management continues to focus on delivering stable long-term returns through a combination of portfolio performance, disciplined capital allocation and shareholder distributions.

    The company believes that the ability to repurchase shares opportunistically, alongside managing debt and reinvesting in attractive assets, provides multiple avenues to create value for investors over time.

    Upcoming half-year results are expected to provide further insight into portfolio performance, dividend sustainability and future capital allocation priorities.

    More about Greencoat UK Wind

    Greencoat UK Wind PLC is a London-listed renewable infrastructure investment company focused on owning and operating UK wind generation assets.

    The company invests in a diversified portfolio of onshore and offshore wind farms, providing investors with exposure to long-term renewable energy infrastructure and cash flows linked to electricity generation. Its strategy is centred on delivering stable income and attractive total returns through ownership of mature, operating wind assets across the UK.

  • Hardide Seeks Capital Reduction to Increase Financial Flexibility and Limit Shareholder Dilution (HDD)

    Hardide Seeks Capital Reduction to Increase Financial Flexibility and Limit Shareholder Dilution (HDD)

    Shareholder Approval Sought for Capital Reorganisation

    Hardide plc (LSE:HDD) has announced plans to undertake a capital reduction and has called a General Meeting to seek shareholder approval for the proposal.

    The company intends to cancel its share premium account together with a capitalised non-statutory reserve, creating approximately £3.2 million of distributable reserves.

    The transaction will also require approval from the High Court and is currently expected to be completed around the middle of August 2026.

    Management emphasised that the proposal will not affect the number of ordinary shares in issue, nor will it alter the rights attached to existing shareholders’ holdings.

    New Reserves Would Reduce Future Share Dilution

    A key objective of the capital reduction is to provide Hardide with greater flexibility when satisfying executive share option exercises.

    Rather than issuing new shares and diluting existing investors, the company would be able to purchase shares in the market using the newly created distributable reserves.

    Management believes this approach offers a more shareholder-friendly mechanism for meeting incentive-related obligations while helping to preserve existing ownership positions.

    Greater Flexibility for Future Capital Allocation

    The creation of distributable reserves would also give the board broader options when considering future capital allocation decisions.

    This could include the ability to return capital to shareholders through dividends or other distributions should the company generate sufficient profits and cash flow in the future.

    However, directors indicated that their current priority remains investing in the growth of the business rather than initiating dividend payments in the near term.

    Management believes reinvesting cash into expansion opportunities offers the best route to creating long-term shareholder value at this stage of the company’s development.

    Stronger Financial Performance Supports Strategic Options

    Hardide’s outlook has improved following a stronger FY2025 performance, which saw the company return to profitability and generate positive free cash flow.

    The turnaround has provided a more stable platform from which management can pursue growth opportunities while improving financial flexibility.

    Although leverage remains higher than ideal and operating margins are still relatively modest, recent progress has strengthened confidence in the business’s direction.

    Growth Remains the Primary Focus

    The company continues to prioritise investment in operational expansion and commercial development across its core markets.

    Management believes the proposed capital reduction complements this strategy by enhancing financial flexibility without altering the underlying capital structure of the business.

    The move is intended to support both future growth initiatives and more efficient capital management as the company continues to build on its recent operational improvements.

    Outlook Balances Momentum with Valuation Considerations

    Hardide’s outlook is supported by improving financial performance, stronger cash generation and a return to profitability following its recent turnaround.

    Technical indicators remain favourable, reflecting positive momentum in the company’s shares, although some measures suggest the stock may be approaching overbought territory.

    Valuation remains a consideration for investors, with the shares trading on a relatively elevated earnings multiple and no current dividend yield to support the investment case.

    Nevertheless, management believes the company’s improved operational performance and strategic initiatives provide a solid foundation for future growth.

    More about Hardide

    Hardide plc is a UK-based engineering technology company specialising in advanced tungsten carbide and tungsten metal matrix coatings for industrial components.

    Its patented coating technology is designed to improve resistance to abrasion, erosion and corrosion while maintaining durability in demanding operating environments. The company serves customers across the energy, aerospace, industrial gas turbine, precision engineering, valve and pump sectors, providing surface treatment solutions for complex components and internal geometries that are difficult to protect using conventional coating methods.

  • Dialight More Than Doubles Operating Profit as Transformation Programme Delivers Results (DIA)

    Dialight More Than Doubles Operating Profit as Transformation Programme Delivers Results (DIA)

    Margin Expansion Offsets Lower Revenue Performance

    Dialight (LSE:DIA) reported revenue of $166.9 million for the year ended 31 March 2026, representing a 9% decline compared with the previous year as customers delayed capital spending on projects within its core Lighting division.

    Despite the softer revenue performance, the company delivered a substantial improvement in profitability. Underlying operating profit more than doubled to $10.3 million, while gross margin increased by 340 basis points.

    Management attributed the stronger earnings performance to the continued execution of its Transformation Plan, which has focused on improving efficiency, reducing costs and strengthening operational performance across the business.

    Transformation Programme Drives Operational Improvements

    The group’s ongoing transformation initiatives generated benefits across multiple areas of the organisation.

    Key actions included product portfolio rationalisation, workforce restructuring, procurement efficiencies and productivity enhancements.

    These measures helped improve profitability while also supporting stronger cash generation and a more streamlined operating model.

    Management said the programme continues to create a more efficient platform capable of supporting sustainable long-term growth.

    Cash Flow Strengthens and Debt Falls Sharply

    Dialight delivered operating cash flow of $34.2 million during the year, reflecting the benefits of improved profitability and tighter working capital management.

    The stronger cash generation enabled the company to significantly reduce net bank debt, which fell to just $1.9 million by year end.

    In addition, the group fully settled its liability with Sanmina, removing a longstanding financial obligation and further strengthening its balance sheet.

    Signals & Components Provides Growth Support

    While the Lighting business faced a challenging environment, Dialight’s Signals & Components division delivered a strong performance.

    Revenue from the segment increased by 13.7%, excluding the Traffic business, helping to offset some of the weakness experienced in Lighting.

    Management noted that geopolitical uncertainty and tariff-related concerns contributed to customer caution in several markets, leading to delays in project orders rather than outright cancellations.

    New Financing Facility Supports Future Growth

    The company also secured a new £15 million revolving credit facility, which includes an additional £10 million accordion option.

    The enhanced financing arrangement provides greater flexibility to support future investment and growth initiatives while maintaining a prudent capital structure.

    Dialight’s strengthened financial position gives management additional confidence as it continues to execute its strategic priorities.

    Growing Order Book Supports Positive Outlook

    Management highlighted improving trading momentum, with order intake strengthening during the year and the company’s backlog increasing by more than 25% compared with the previous year.

    The group has also identified three additional production-related transformation projects that are expected to contribute further profit growth and cash generation in the coming years.

    Reflecting the progress achieved, Dialight has raised its medium-term return-on-sales target, signalling confidence in the sustainability of recent operational improvements.

    Outlook Supported by Operational Momentum

    Dialight’s outlook benefits from a combination of strong operational execution, improving profitability and a healthier balance sheet.

    Technical indicators remain supportive, reflecting positive momentum in the company’s share price and investor sentiment.

    While challenges remain, including the need to sustain profitability improvements and navigate uncertain end-market conditions, management believes the business is now significantly better positioned than in recent years.

    The combination of a growing order book, ongoing efficiency initiatives and improved financial flexibility is expected to support further progress over the medium term.

    More about Dialight

    Dialight plc is a UK-listed industrial technology company specialising in LED lighting and signalling solutions for demanding industrial environments.

    The group operates across North America, Europe, Asia-Pacific and the Middle East, supplying products designed to improve energy efficiency, enhance workplace safety and reduce maintenance costs. Its solutions are used across sectors including oil and gas, mining, manufacturing, power generation and transportation, where reliability and durability are critical operational requirements.

  • LondonMetric Confirms Delivery of Post-Acquisition Commitments Following Urban Logistics REIT Deal (LMP)

    LondonMetric Confirms Delivery of Post-Acquisition Commitments Following Urban Logistics REIT Deal (LMP)

    Company Confirms Compliance One Year After Takeover Completion

    LondonMetric Property (LSE:LMP) has confirmed that it has fulfilled all of the post-offer commitments made in connection with its recommended cash-and-share acquisition of Urban Logistics REIT.

    The transaction was completed in June 2025 through a scheme of arrangement, and the company has now reached the 12-month milestone that requires a formal update under Rule 19.6(c) of the UK Takeover Code.

    As part of this process, LondonMetric submitted confirmation to the UK Takeover Panel that it has acted in accordance with the intentions outlined during the acquisition process.

    Integration Plans Proceeding as Expected

    Management stated that all commitments made at the time of the offer have been implemented as originally described.

    The confirmation provides reassurance that the integration of Urban Logistics REIT has progressed in line with the strategy and objectives presented to shareholders and regulators during the takeover process.

    By formally confirming compliance with its stated intentions, the company has demonstrated adherence to the governance and transparency requirements associated with major UK public market transactions.

    Strategic Focus Remains on Logistics and Income Growth

    The acquisition of Urban Logistics REIT formed part of LondonMetric’s broader strategy of expanding its exposure to logistics and urban distribution assets.

    Management continues to focus on building a portfolio of high-quality, income-generating properties capable of delivering long-term rental growth and attractive shareholder returns.

    The successful integration of Urban Logistics REIT further strengthens the group’s position within one of the most resilient segments of the UK real estate market.

    Supportive Fundamentals Underpin Outlook

    LondonMetric’s outlook continues to benefit from an attractive valuation profile, supported by a relatively low earnings multiple and a strong dividend yield.

    Recent trading updates have highlighted resilient rental income performance and continued dividend growth, reinforcing the company’s income-focused investment proposition.

    Management remains focused on generating stable cash flows through disciplined asset management and selective investment opportunities.

    Balance Sheet and Cash Flow Remain Areas of Focus

    While the company’s earnings outlook remains constructive, investors continue to monitor certain financial metrics, including higher leverage levels following recent acquisitions and softer free cash flow growth in the latest financial year.

    Technical indicators currently suggest a broadly neutral market trend, with limited signs of strong positive or negative momentum.

    Despite these considerations, LondonMetric’s income profile and asset quality continue to support its long-term investment case.

    More about LondonMetric Property

    LondonMetric Property plc is a UK-listed real estate investment trust focused on acquiring, managing and developing income-producing property assets.

    The company has a particular emphasis on logistics, distribution and urban warehousing properties, alongside other long-income real estate sectors. Its strategy centres on generating reliable rental income, delivering dividend growth and creating long-term capital value for shareholders through active portfolio management and disciplined investment decisions.

  • Iomart Grows Revenue While Accelerating Shift Towards Higher-Value Cloud Services (IOM)

    Iomart Grows Revenue While Accelerating Shift Towards Higher-Value Cloud Services (IOM)

    Revenue Increases Despite Ongoing Organic Headwinds

    Iomart Group plc (LSE:IOM) reported revenue of £154.9 million for the year ended 31 March 2026, representing growth of 8% compared with the previous year.

    The increase was largely driven by a full-year contribution from the Atech acquisition. However, underlying organic revenue declined as the business experienced customer churn and a greater mix of lower-margin Microsoft-related services.

    Despite these challenges, management highlighted encouraging progress in reshaping the group’s service portfolio toward areas with stronger long-term growth and profitability potential.

    Profitability Impacted by Business Transition

    The company’s transition towards higher-value cloud and managed services weighed on short-term earnings performance.

    Adjusted EBITDA declined to £25.6 million during the year, while Iomart reported an adjusted pre-tax loss of £4.0 million.

    Management noted that profitability improved during the second half of the year as restructuring initiatives gained traction and operational efficiencies began to deliver benefits.

    The group also maintained strong cash generation despite the weaker earnings performance.

    Cost Savings and Operational Restructuring Progress

    Iomart successfully delivered approximately £4 million of cost savings during the year as part of a broader programme aimed at improving efficiency and supporting future margin recovery.

    Several strategic initiatives were completed, including the integration of Extrinsica into Atech, the continued expansion of the company’s operations in India and the separation of its data centre infrastructure activities into a standalone entity.

    These measures form part of a wider transformation strategy designed to streamline operations and better align the business with evolving customer demand.

    Focus Shifts to Higher-Margin Cloud and Security Services

    Management continues to reposition Iomart towards higher-value offerings across cloud infrastructure, cyber security and data protection services.

    The company believes its strong relationships with Microsoft and VMware position it well to benefit from changing customer requirements and evolving licensing structures in the cloud computing market.

    Upcoming VMware licensing changes are expected to create new commercial opportunities, while Iomart’s established Microsoft expertise remains a key competitive advantage.

    The group expects these trends to support improved margins and stronger growth prospects in FY27 and beyond.

    Banking Facilities Extended to Support Growth Plans

    Alongside its operational transformation, Iomart extended its banking facilities, providing additional financial flexibility as it executes its long-term strategy.

    Management believes the company’s strong cash generation and improved financing position provide a solid foundation for future investment and business development.

    The focus remains on driving organic growth, improving profitability and increasing exposure to higher-value recurring services.

    Outlook Reflects Transformation Challenges and Long-Term Opportunities

    Iomart’s outlook continues to be shaped by near-term financial pressures, including reduced profitability, increased leverage and weaker free cash flow generation.

    However, management believes the strategic repositioning of the business creates opportunities for stronger long-term growth and margin expansion.

    Technical indicators remain supportive, although recent share-price strength suggests the stock may be approaching overbought territory in the short term.

    Valuation remains constrained by current earnings losses, while the absence of a meaningful earnings multiple limits traditional valuation comparisons.

    More about Iomart Group

    Iomart Group plc is a UK-based provider of secure cloud-managed services, delivering solutions across cloud infrastructure, modern workplace management and cyber security.

    The company supports businesses seeking to modernise and simplify their IT environments while improving resilience, scalability and data protection. Leveraging strong Microsoft credentials and leading Broadcom VMware partnerships, Iomart provides hybrid cloud, managed security and data protection services to customers across the UK.

  • Severfield Pursues Margin Recovery Following Restructuring and Strategic Refocus (SFR)

    Severfield Pursues Margin Recovery Following Restructuring and Strategic Refocus (SFR)

    Profitability Pressured Despite Stable Revenue Performance

    Severfield (LSE:SFR) reported revenue of £454.3 million for FY26, broadly unchanged from the previous year, but faced a significant decline in underlying profitability as challenging market conditions weighed on performance.

    Margins came under pressure from intense pricing competition, delays to project delivery schedules and weaker activity levels across certain core end markets. As a result, the company recorded a sharp reduction in underlying profit and reported a statutory loss for the year.

    Despite these headwinds, Severfield strengthened its financial position by reducing net debt to £28.2 million and securing an extension to its banking facilities through to 2029.

    Dividend Suspended to Protect Balance Sheet Strength

    The board elected not to recommend a final dividend, prioritising balance sheet resilience and financial flexibility amid a difficult trading environment.

    Management believes retaining capital will support the group’s ongoing transformation programme and provide additional resources to execute its long-term growth strategy.

    The reduction in debt and extension of financing arrangements are viewed as important steps in improving the company’s financial foundation during a period of transition.

    Portfolio Simplification and Operational Restructuring Continue

    During the year, Severfield made further progress in streamlining its business portfolio.

    The group advanced its planned exit from the Modular Solutions division while continuing work on a significant bridge remedial programme, which has generated substantial costs but has also been partially offset by insurance recoveries.

    Management said these actions form part of a broader effort to simplify operations, improve efficiency and focus resources on areas with stronger long-term return potential.

    New Strategy Targets Higher-Margin Growth

    Severfield has launched a refreshed strategic plan aimed at improving profitability and reducing capital intensity across the business.

    The strategy focuses on higher-margin opportunities, tighter operational controls, stronger project selection and increased use of strategic partnerships to support growth.

    Management has outlined medium-term targets of £500 million to £550 million in annual revenue and operating margins of between 7% and 8%.

    The company also expects its expanding Indian operations to play an increasingly important role in future growth, particularly in higher-value commercial and infrastructure projects.

    FY27 Expected to Be a Transitional Year

    While management remains confident in the long-term opportunity, FY27 has been identified as a transition year as the company implements its strategic reset.

    The focus will remain on improving execution, rebuilding margins and repositioning the business for more sustainable growth.

    Management believes the actions taken during FY26 have established a platform from which the group can deliver improved financial performance over the medium term.

    Outlook Reflects Challenges but Also Strategic Progress

    Severfield’s outlook remains influenced by a difficult financial backdrop, with pressure on profitability and margins continuing to weigh on performance.

    However, the company’s strategic initiatives, improving balance sheet position and ongoing restructuring efforts provide positive indicators for future recovery.

    Technical indicators have shown some improvement, while management’s alignment with long-term performance objectives offers additional confidence in the execution of the group’s strategy.

    Although valuation metrics remain under pressure and liquidity considerations continue to be monitored, the company believes its strategic repositioning can support stronger returns over time.

    More about Severfield

    Severfield plc is one of the UK’s leading structural steel specialists, providing design, fabrication and installation services for major infrastructure, industrial and commercial developments.

    The group operates across the UK, Europe and India and has extensive experience in sectors including nuclear energy, advanced manufacturing, logistics, transport infrastructure and large-scale urban construction projects. Through its Indian joint venture and growing international presence, Severfield is increasingly focused on higher-margin opportunities and long-term infrastructure growth markets.