Blog

  • Power Metal Expands Uranium Focus as Fermi Joint Venture Delivers Exploration Progress (POW)

    Power Metal Expands Uranium Focus as Fermi Joint Venture Delivers Exploration Progress (POW)

    Power Metal Resources (LSE:POW) reported its audited 2025 results, pointing to stronger market sentiment and an improved financial position following a period of portfolio restructuring and targeted investment activity. The company continued to advance its project incubator strategy by reducing exposure to non-core assets while increasing its participation in emerging opportunities such as Minestarters and Apex Royalties.

    Management said these initiatives have helped streamline the portfolio and position the business to pursue growth opportunities across a range of commodities and jurisdictions.

    Uranium Exploration Activities Advance Across Athabasca Basin

    A major area of focus during the year was the company’s North American uranium joint venture, Fermi Exploration, which continued to progress several projects within the Athabasca Basin.

    Exploration work identified new intrusion-related and basement-hosted uranium targets while advancing multiple drilling and geophysical programmes. Although certain assets, including the West Hawkrock project, were temporarily paused, several active licences generated encouraging geological results.

    Projects such as Tait Hill, Fortin River, Drake Lake-Silas, Perch River, Badger Lake and East Hawkrock all recorded indicators supportive of further exploration. The results reinforce Power Metal’s strategy of increasing exposure to uranium opportunities while continuing to develop assets across its broader portfolio.

    Portfolio Strategy Supports Long-Term Growth Ambitions

    Beyond its uranium interests, the company continued pursuing growth opportunities in other regions, including ongoing expansion efforts within the Arabian Shield.

    Power Metal’s approach remains focused on identifying, advancing and monetising exploration assets through a combination of direct ownership, partnerships and strategic investments. Management believes this diversified model helps spread risk while creating multiple pathways to value generation.

    Financial Strength Balanced by Operational and Market Challenges

    The company’s outlook is supported by strong revenue growth and a healthy balance sheet, reflecting the benefits of portfolio optimisation and disciplined capital management.

    However, ongoing operational challenges and negative cash flow generation continue to weigh on the investment case. From a valuation perspective, management believes the shares may offer upside potential, although technical indicators suggest investors should remain cautious given prevailing bearish market trends.

    More About Power Metal Resources Plc

    Power Metal Resources Plc is a London-listed mineral exploration company with interests in a broad portfolio of early-stage and advanced resource projects around the world.

    The company maintains exposure to multiple commodities and jurisdictions, with a growing emphasis on uranium and other future-oriented sectors. In addition to conventional exploration assets, Power Metal is pursuing opportunities in royalty structures and tokenised projects as part of its strategy to diversify risk and unlock shareholder value.
  • British American Tobacco Reaffirms 2026 Outlook as New Category Expansion Gains Pace (BATS)

    British American Tobacco Reaffirms 2026 Outlook as New Category Expansion Gains Pace (BATS)

    British American Tobacco (LSE:BATS) said it remains on course to deliver its full-year 2026 guidance, supported by strong performance across its U.S. business and continued growth in its New Category portfolio.

    The company expects revenue from New Categories to increase by a mid-teens percentage rate this year, driven by rising demand for modern oral nicotine products and vapour offerings. Management highlighted continued momentum for the Velo and Vuse brands globally, while also pointing to plans for an innovation-led recovery in its glo heated tobacco business during the second half of the year.

    Performance in the Americas and Europe remained resilient, helping offset a slower recovery in Asia-Pacific and Middle Eastern markets, where trading conditions continue to stabilise.

    Growth Strategy Remains Intact Despite Market Headwinds

    British American Tobacco reaffirmed its medium-term financial framework, although management indicated that 2026 results are likely to fall toward the lower end of its targeted ranges for revenue growth, profit expansion and earnings per share.

    The company also warned that global cigarette volumes are expected to decline slightly faster than previously anticipated and noted that foreign exchange movements could create additional pressure on reported results.

    Despite these challenges, management remains confident in the business outlook, supported by continued progress in reduced-risk products and a diversified geographic footprint.

    Cash Generation and Shareholder Returns Remain Priorities

    The group expects operating cash flow conversion to exceed 95% during the year and confirmed plans to complete a £1.3 billion share repurchase programme alongside its progressive dividend policy.

    British American Tobacco also reiterated its objective of reducing leverage to between 2.0 and 2.5 times EBITDA by the end of 2026. The company believes these measures will support ongoing shareholder returns while maintaining financial flexibility in a competitive and evolving nicotine market.

    Balanced Outlook Supported by Income Appeal

    The company’s investment profile continues to benefit from solid profitability, although this is partially offset by leverage levels and a notable decline in cash flow recorded during 2025.

    Valuation remains supported by a relatively moderate price-to-earnings multiple and an attractive dividend yield, while technical indicators present a broadly neutral picture. Management’s guidance and capital return commitments provide additional support, though investors continue to monitor competitive pressures in vapour products, illicit trade activity and softer performance in certain regions.

    More About British American Tobacco

    British American Tobacco is one of the world’s largest tobacco and nicotine companies, generating the majority of its revenue from traditional combustible cigarette products while expanding its presence in reduced-risk categories.

    Its New Category portfolio includes Velo nicotine pouches, Vuse vapour products and glo heated tobacco devices. The company maintains a significant presence in the United States, Europe and a range of emerging markets as it seeks to accelerate the transition toward alternative nicotine products.

  • Helix Isotope Results Support Deep Helium Reservoir Model and Highlight Potential Argon Opportunity at Rudyard (HEX)

    Helix Isotope Results Support Deep Helium Reservoir Model and Highlight Potential Argon Opportunity at Rudyard (HEX)

    Helix Exploration (LSE:HEX) has released the results of independent noble gas isotope testing conducted on gas samples from its three producing wells and processed gas stream at the Rudyard Helium Project. The analyses identified elevated helium-3 to helium-4 ratios, with consistent isotope signatures recorded across the project area.

    According to the company, the findings support the presence of a deep-seated, ancient and well-isolated noble gas reservoir that serves as the source of Rudyard’s helium production. The results also provide further validation of the geological model being used to guide future development of the project.

    Argon Findings Could Open Additional Commercial Opportunities

    The isotope study also delivered encouraging results for argon, with values comparable to those found at the world’s only commercial underground argon source.

    If forthcoming argon-39 testing confirms that the gas has been shielded from cosmogenic radiation, Rudyard could potentially represent only the second known commercial underground source globally. Such a development could position Helix to participate in the specialized market for ultra-pure argon, which is used in advanced scientific applications including dark matter detection experiments.

    Management believes the discovery could add a significant new dimension to the project’s value proposition, complementing its existing helium production strategy while creating additional scientific and commercial opportunities.

    Strong Market Momentum Balances Early-Stage Financial Challenges

    Helix’s outlook continues to be influenced by its early-stage development status. The company remains pre-revenue, continues to report losses and has experienced increasing cash outflows despite maintaining a debt-free balance sheet.

    However, these financial challenges are partially offset by strong technical performance in the shares, which have exhibited positive momentum and a sustained upward trend. Valuation metrics remain limited by the absence of earnings and dividend distributions, reflecting the company’s current development-stage profile.

    More About Helix Exploration Plc

    Helix Exploration PLC is a helium exploration and development company focused on advancing projects within the Montana Helium Fairway in northern Montana, United States.

    The company’s flagship Rudyard Helium Project targets helium-bearing nitrogen gas within the Souris and Red River formations. By utilizing existing infrastructure and low-cost processing methods, Helix aims to establish a scalable production platform supported by multiple wells and long-term revenue generation potential.

  • Tower Resources Progresses African Farm-Out Strategy and Strengthens Funding Position (TRP)

    Tower Resources Progresses African Farm-Out Strategy and Strengthens Funding Position (TRP)

    Tower Resources (LSE:TRP) reported its preliminary results for 2025, outlining advances across its African asset portfolio and measures taken to reinforce its financial position. The company continues to focus on developing its Thali licence in Cameroon while progressing exploration opportunities in Namibia and South Africa, seeking to capitalize on a favorable oil market environment.

    Cameroon Farm-Out Supports Upcoming Drilling Activity

    In Cameroon, Tower reached an agreement to farm out a 42.5% non-operated stake in the Thali licence to Prime Global Energies. Under the arrangement, Prime will contribute US$15 million toward the licence work programme, while a jack-up drilling rig has been secured for the planned NJOM-3 well.

    The company is also pursuing a one-year extension to the licence’s initial exploration period. In parallel, Tower revised its commercial arrangements with Pegasus Petroleum, introducing a structure based on future production-linked payments and a significant share issuance designed to better align the interests of all parties as the project moves toward potential development.

    Namibia Transactions Increase Exposure While Sharing Risk

    Tower has also taken steps to expand its participation in Namibia’s offshore PEL96 licence by increasing its direct interest by 5%. At the same time, the company agreed to a 25% farm-in by Prime, which includes reimbursement of historical costs.

    The Ministry of Industries, Mines and Energy (MIME) has confirmed the licence’s entry into its first renewal period, providing additional support for future exploration activities. Management believes the transaction structure allows Tower to maintain meaningful exposure to one of Africa’s most closely watched exploration regions while reducing funding requirements through partner participation.

    Capital Raises Provide Liquidity for Strategic Priorities

    To support ongoing operations, Tower implemented a series of financing initiatives during 2025 and early 2026. The company secured an unsecured convertible bridge loan facility of up to £1 million during 2025 and subsequently completed multiple equity subscriptions that raised more than £2.7 million.

    The proceeds enabled the full repayment of the bridge loan and provided working capital to advance key licence commitments while awaiting regulatory approvals for the Cameroon and Namibia farm-out transactions. Although the funding programme resulted in substantial shareholder dilution, management views the additional capital as critical to maintaining momentum across its portfolio.

    Financial Challenges Continue to Weigh on Outlook

    Despite operational progress, Tower’s outlook remains constrained by its financial profile. The company continues to report no revenue generation, recurring losses and negative free cash flow, although leverage remains relatively low.

    Technical indicators also remain weak, with the shares trading below major moving averages and momentum measures such as MACD remaining negative. Valuation metrics provide limited support given the company’s loss-making status and the absence of a dividend yield.

    More About Tower Resources

    Tower Resources is an AIM-listed oil and gas exploration and production company focused on developing a diversified portfolio of African energy assets.

    The company’s strategy combines near-term development opportunities in Cameroon, aimed at generating future cash flow, with exploration projects in Namibia and South Africa. Through seismic acquisition and partner-led risk sharing, Tower seeks to unlock value from emerging hydrocarbon provinces across the continent.

  • GEO Exploration Completes Airborne Survey at Gorge Gold Project to Support Next Exploration Phase (GEO)

    GEO Exploration Completes Airborne Survey at Gorge Gold Project to Support Next Exploration Phase (GEO)

    GEO Exploration Limited (LSE:GEO) has finished a fixed-wing airborne magnetic and radiometric survey across its Gorge Project in Western Australia. The programme was completed ahead of schedule by contractor MAGSPEC Airborne Surveys, providing the company with a new geophysical dataset that will support future exploration activities.

    The survey results are expected to enhance geological and structural interpretations of the project area, assist in identifying priority drill targets and help guide upcoming geochemical exploration programmes. GEO’s Exploration Manager is currently undertaking field reconnaissance and mapping work to integrate the new information into the project’s evolving geological model.

    Historical Results Highlight Significant Gold Potential

    The Gorge Project continues to demonstrate strong exploration potential, supported by historical exploration that identified widespread gold mineralisation along a strike length of approximately five kilometres.

    Previous work has returned high-grade rock chip and soil sample results, elevated gold values in drainage samples and multiple discoveries of shallow gold nuggets. These findings have reinforced the project’s prospectivity and support management’s view that the area could host a significant gold system.

    According to the company, the newly completed airborne survey represents an important step toward refining exploration targets and prioritising follow-up drilling programmes. Successful targeting could further enhance the strategic value of the asset within GEO Exploration’s portfolio.

    Exploration Strategy Focused on Greenfields Discovery

    Management believes the combination of geophysical data, field mapping and future geochemical programmes will provide a stronger understanding of the project’s geology and help accelerate exploration efforts.

    The Gorge Project is viewed as a key component of GEO’s strategy to pursue greenfields gold discoveries in Western Australia, offering investors exposure to an early-stage exploration opportunity with significant upside potential.

    More About GEO Exploration Limited

    GEO Exploration Limited is an AIM-listed mineral exploration company focused on the discovery and development of gold resources in Western Australia.

    Through its wholly owned subsidiary, Gorge Gold Pty Ltd, the company controls the Gorge Project licence within the Proterozoic Capricorn Orogen. The project covers approximately 81 square kilometres and is prospective for both large-scale orogenic and Carlin-style gold mineralisation, forming the foundation of GEO’s exploration strategy in the region.

  • GoldStone Expands Sierra Leone Operations as Early Processing Identifies Coarse Gold (GRL)

    GoldStone Expands Sierra Leone Operations as Early Processing Identifies Coarse Gold (GRL)

    GoldStone Resources (LSE:GRL) has reported further progress at its Sierra Leone joint venture, MinCorp SL, where the company owns a 50% interest in a number of small-scale gold mining licences located adjacent to the significant Baomahun gold deposit.

    The venture enhances GoldStone’s presence in West Africa alongside its producing Homase mine in Ghana and supports the company’s strategy of increasing exposure to prospective gold-producing regions across the area.

    Initial Processing Results Deliver Encouraging Signs

    Since making its investment in March 2026, MinCorp SL has advanced several key operational activities, including the commissioning of a wash plant and the launch of test trenching work using excavator equipment.

    During initial gravity recovery operations, visible coarse gold was identified, a development the company considers a positive indication of the mineral potential within the licence areas. GoldStone has also deployed local technical and management personnel to support the project’s advancement.

    Under the terms of its memorandum of understanding, the company expects to receive initial revenues from early gold sales. Looking ahead, management intends to implement more structured processing programmes aimed at improving recovery rates, refining mining methods and supporting future mine planning activities.

    The project continues to receive support from Sierra Leone’s National Minerals Agency as development work progresses.

    Strong Market Momentum Offsets Financial Challenges

    GoldStone’s investment outlook remains constrained by ongoing financial pressures, including continued losses, weaker margins, negative free cash flow and increasing leverage.

    However, these concerns are partially balanced by strong technical performance, with the shares trading above key moving averages and maintaining positive price momentum. Valuation metrics remain challenging due to the company’s loss-making status, reflected in a negative price-to-earnings ratio and the absence of dividend support.

    More About GoldStone Resources

    GoldStone Resources Limited is an AIM-listed gold exploration, development and production company focused on assets in Ghana.

    Its flagship Akrokeri-Homase project, located in southwestern Ghana, contains a JORC-compliant gold resource of 602,000 ounces across a 4-kilometre section of the Homase Trend. The project incorporates two historic high-grade gold mines and forms the cornerstone of the company’s strategy to build a broader portfolio of assets along the highly prospective Birimian Gold Belt.

  • Paragon Banking Group Releases Half-Year Results and Announces Interim Dividend (PAG)

    Paragon Banking Group Releases Half-Year Results and Announces Interim Dividend (PAG)

    Paragon Banking Group PLC (LSE:PAG) has published its Half Year Financial Report and Pillar III disclosures for the six months ended 31 March 2026. The documents have been made available through the National Storage Mechanism, the London Stock Exchange platform and the company’s investor relations website.

    The publication provides investors and other stakeholders with updated financial and regulatory information, reflecting the group’s commitment to transparency and adherence to reporting obligations.

    Board Approves 15.1p Interim Dividend

    The board has declared an interim dividend of 15.1 pence per ordinary share for the 2026 financial year. Shares will trade ex-dividend from 2 July, with a record date of 3 July and payment scheduled for 24 July.

    The dividend announcement highlights management’s confidence in the bank’s financial performance and capital strength, while delivering a cash return to shareholders in accordance with the established timetable.

    Valuation Strength Balanced by Financial Risks

    Paragon’s investment profile continues to benefit from a relatively low price-to-earnings valuation and an attractive dividend yield. Technical indicators also remain supportive, with the shares trading above key moving averages.

    However, these strengths are offset by certain financial risks, including higher leverage levels and volatility in both revenue and cash flow. These factors create some uncertainty around the sustainability and consistency of recent operating performance.

    More About Paragon Banking Group PLC

    Paragon Banking Group PLC is a UK specialist banking institution offering a range of lending and savings products to both retail and commercial customers.

    The group operates across several segments, including mortgage lending and specialist financing, and is subject to the UK’s regulatory and financial reporting framework. Through its banking operations, Paragon provides tailored financial solutions while maintaining a focus on prudent risk management and shareholder value.

  • Wizz Air Posts Strong May Passenger Growth as Network Expansion Continues (WIZZ)

    Wizz Air Posts Strong May Passenger Growth as Network Expansion Continues (WIZZ)

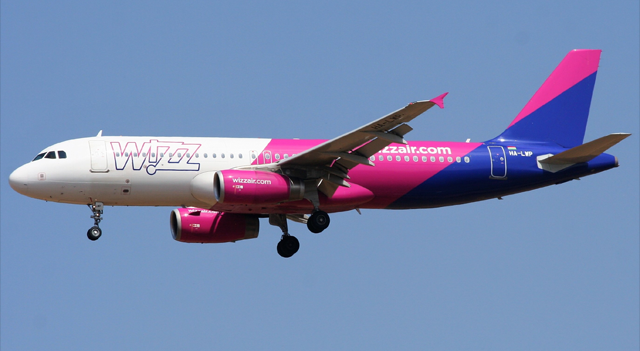
    Wizz Air (LSE:WIZZ) delivered robust traffic growth in May 2026, transporting 7.13 million passengers, a 26% increase compared with the same month last year. The airline expanded capacity by 25.4% to 7.77 million seats, while its load factor improved to 91.7%, reflecting strong demand across its network.

    The carrier also reported continued progress on operational efficiency, with carbon dioxide emissions per passenger-kilometre declining 3.2% year over year to 49.4 grams.

    Tel Aviv Services Restart and Italian Operations Expand

    During the month, Wizz Air resumed flights to Tel Aviv following previous suspensions related to tensions in the Middle East. The restart reconnects Israel with a wide range of destinations across Europe and restores an important segment of the airline’s network.

    The company also strengthened its footprint in Italy by assigning additional aircraft to bases in Milan Malpensa, Naples and Catania. Alongside its network expansion, Wizz Air broadened its corporate travel reach through a new partnership with travel technology provider Atlas.

    The airline further supported major sporting events by operating 77 special flights for fans attending the UEFA Champions League final in Budapest, with aircraft operating at near-full capacity.

    Financial Recovery Supports Outlook Despite Industry Challenges

    Wizz Air’s investment outlook is supported by improving profitability trends and a recovery in free cash flow, alongside a valuation that remains relatively attractive based on earnings multiples.

    However, several challenges continue to weigh on sentiment. Technical indicators remain weak, with the share price trading below key moving averages and momentum measures remaining negative. Investors are also monitoring execution risks highlighted by management, including breakeven profitability targets, pressure on unit revenues and temporary cost increases associated with the airline’s transition and growth initiatives.

    More About Wizz Air Holdings

    Wizz Air Holdings is a European ultra-low-cost airline group operating short- and medium-haul routes across Europe and the Middle East.

    The company primarily serves Central and Eastern European markets while continuing to expand its network and fleet. Wizz Air has been increasing its presence in strategic markets such as Italy and focuses on attracting leisure travellers and those visiting friends and relatives through its low-fare model.

  • Itaconix Advances Growth Strategy Following Record Performance as Demand for Plant-Based Polymers Expands (ITX)

    Itaconix Advances Growth Strategy Following Record Performance as Demand for Plant-Based Polymers Expands (ITX)

    Itaconix (LSE:ITX) said trading during FY2026 remains on track with management expectations after delivering record results in FY2025. The company expects to achieve another record first-half performance while maintaining stable gross margins.

    The business continues to benefit from disruptions affecting suppliers of fossil fuel-derived specialty chemicals, creating opportunities to win market share. According to the company, customers are increasingly valuing the reliability of supply and sustainability credentials offered by its plant-based ingredient portfolio, which could support further revenue growth.

    New Product Initiatives and Market Expansion Efforts

    To accelerate growth, Itaconix is investing in product innovation and market development. Among its latest initiatives is the launch of deeperclean.com, a platform aimed at North American detergent brands that showcases a plant-based dishwashing tablet and is expected to support future consumer testing programs.

    The company is also broadening the application of its technologies beyond its core markets. Development work is underway with a specialist partner to create paints incorporating BIO*Asterix technology, while agricultural field trials are being conducted using BioVail GRZ 200L crop treatments. Initial findings are expected following harvest, with longer-term data anticipated over multiple growing seasons.

    Profitability Challenges Continue Despite Operational Progress

    While operational momentum remains positive, Itaconix continues to face financial headwinds. The company remains loss-making and continues to consume cash, factors that weigh on its overall outlook despite improvements in margins and a manageable debt position.

    Technical indicators also remain weak, with the share price trading below key moving averages and a negative MACD signal suggesting continued downward momentum. From a valuation perspective, the absence of earnings profitability results in a negative price-to-earnings ratio, while the lack of dividend support further limits valuation appeal.

    More About Itaconix

    Itaconix PLC is a specialty chemicals company focused on the development and manufacture of high-performance polymers derived from renewable plant-based materials.

    Its Itaconix Performance Ingredients division supplies ingredients primarily for detergent formulations, including technologies designed for scale control and odour neutralisation. The company targets consumer and industrial brands seeking sustainable alternatives to traditional fossil-based specialty chemical ingredients.

  • British Land Appoints Joanne McNamara as Chief Executive Officer (BLND)

    British Land Appoints Joanne McNamara as Chief Executive Officer (BLND)

    British Land (LSE:BLND) has selected Joanne McNamara as its next Chief Executive Officer, bringing in the current Executive Vice President for Europe at Oxford Properties to lead the business. McNamara is expected to take up the role no later than the end of November 2026.

    McNamara arrives with more than 20 years of experience in the real estate sector and has played a key role in expanding Oxford Properties’ European platform. British Land’s board believes her track record and industry expertise make her well suited to execute the company’s growth plans across its core UK commercial real estate markets.

    Leadership Transition Backed by Long-Term Incentives

    As part of her appointment, McNamara will receive an annual base salary of £800,000. Her compensation package also includes awards designed to replace bonuses and long-term incentives forfeited upon leaving her current employer, alongside additional restricted and performance-based share awards.

    The structure of the package is intended to align management interests with those of shareholders while supporting long-term value creation. British Land said the appointment reflects its focus on combining strong leadership with expertise in private capital markets as it seeks to strengthen its position in key segments including London campuses and retail parks.

    Outlook Supported by Valuation and Financial Strength

    British Land’s investment case continues to be supported by what it views as an attractive valuation, characterised by a relatively low price-to-earnings ratio and a strong dividend yield. The company also points to a solid balance sheet and improving cash flow trends.

    Market momentum and technical indicators remain favourable, although earnings volatility associated with property revaluations remains a consideration. Additional challenges include higher financing costs and the execution risks linked to development and project delivery activities.

    More About British Land Company plc

    British Land Company plc is one of the UK’s leading commercial property owners and developers, with a strategic focus on sectors benefiting from strong operational fundamentals, particularly London campuses and retail parks.

    As of 31 March 2026, the company owned or managed a property portfolio valued at £15.8 billion. Its strategy centres on creating, developing and managing high-quality, sustainable destinations while generating long-term value through active asset management and development expertise.