Blog

  • Henderson High Income Trust Posts Solid Half-Year Performance with 11.9% NAV Gain

    Henderson High Income Trust Posts Solid Half-Year Performance with 11.9% NAV Gain

    Henderson High Income Trust PLC (LSE:HHI) has delivered a strong set of unaudited results for the six months ending June 30, 2025. The trust reported a net asset value (NAV) total return of 11.9%, surpassing its benchmark by 3.9%. Its share price achieved an even greater total return of 14.4%, supported by a narrowing discount to NAV. The portfolio remains primarily invested in equities, with gearing reduced slightly to 18%. Despite ongoing global economic uncertainty, the trust continues to generate attractive income for investors, underpinned by healthy corporate earnings and steady dividend growth, particularly from UK banking stocks.

    The trust’s overall investment profile is strengthened by its consistent financial results and stable valuation. Strategic measures such as share repurchase programs and lower management fees have reinforced confidence in future performance. That said, technical indicators point to short-term caution, with the shares currently trading under their near-term moving averages.

    About Henderson High Income Trust PLC

    Henderson High Income Trust PLC is an investment trust that aims to provide shareholders with a reliable stream of high dividends alongside the potential for capital appreciation. Its portfolio spans both large-cap names and smaller businesses, balancing equity exposure with fixed income investments to deliver long-term value.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Clontarf Energy Pushes Forward in Lithium and Magnesium Extraction

    Clontarf Energy Pushes Forward in Lithium and Magnesium Extraction

    Clontarf Energy (LSE:CLON) has reported encouraging progress in its trials of direct extraction methods for lithium and magnesium. The breakthrough suggests new potential revenue streams and could strengthen the company’s standing in the resource market. Work is advancing at its pilot facility in India, while expansion into Bolivia is under consideration, supported by a more favorable political environment and the prospect of financial backing from the European Union. With global concerns over resource security, Clontarf is positioning itself to supply the rising demand for high-grade lithium and magnesium.

    About Clontarf Energy

    Clontarf Energy plc is focused on developing clean lithium brine projects in Bolivia, alongside oil and gas exploration in Australia and Africa. The company is working to refine direct extraction technologies for lithium and magnesium from brines, aiming to raise purity levels and accelerate production—potentially reshaping standards across the sector.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • DAX, CAC, FTSE100, European Stocks See Mixed Moves Amid France Political Turmoil and U.S. Inflation Watch

    DAX, CAC, FTSE100, European Stocks See Mixed Moves Amid France Political Turmoil and U.S. Inflation Watch

    European equities showed a mixed performance on Tuesday, with France’s ongoing political turmoil and looming U.S. inflation data capturing investor attention.

    Data released on French industrial production indicated a 1.1% drop in July compared with June, largely due to a slowdown in aircraft manufacturing, though markets largely shrugged off the figures.

    In terms of indices, Germany’s DAX fell 0.4%, while the U.K.’s FTSE 100 advanced 0.3%, and France’s CAC 40 gained 0.4%.

    ASML Holding (EU:ASML), the Dutch chipmaking equipment firm, edged higher following news of its €1.3 billion ($1.5 billion) investment in French AI startup Mistral.

    Vodafone (LSE:VOD) also saw gains after the U.K. telecom announced a cash tender offer to buy back its $500 million in outstanding capital securities due 2081.

    Shares of Anglo American (LSE:AAL) surged after the miner unveiled a $50 billion merger agreement with Canada’s Teck Resources.

    Italy’s Monte dei Paschi di Siena (BIT:BMPS) climbed sharply after securing a controlling stake in Mediobanca SpA (BIT:MB).

    On the downside, homeware retailer Dunelm (LSE:DNLM) fell, citing ongoing weakness in consumer demand and no clear signs of recovery. Mining giant BHP (LSE:BHP) also retreated after reaching a settlement agreement in the Australian Samarco shareholder class action.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dow Jones, S&P, Nasdaq, Futures, Wall Street Poised for Uneven Trading Ahead of Key Inflation Reports

    Dow Jones, S&P, Nasdaq, Futures, Wall Street Poised for Uneven Trading Ahead of Key Inflation Reports

    U.S. stock futures are signaling a mostly flat open on Tuesday, suggesting limited directional movement after markets closed modestly higher in the previous session.

    Investors appear cautious ahead of the release of crucial inflation figures later this week, likely tempering large trades or bold positioning.

    The Labor Department is set to release the producer price index (PPI) on Wednesday, followed by the consumer price index (CPI) on Thursday. These reports are expected to provide fresh guidance on the trajectory of Federal Reserve interest rate policy.

    Friday’s weaker-than-expected jobs report had bolstered expectations that the Fed will cut rates at its upcoming meeting. However, the new inflation data could shape how aggressive any rate reductions might be.

    Economists forecast that the annual producer price increase will remain steady at 3.3% in August, unchanged from July. Meanwhile, consumer prices are projected to rise 2.9% year-over-year, up from 2.7% in July. Core consumer prices, excluding food and energy, are expected to remain at 3.1%.

    According to CME Group’s FedWatch Tool, the market currently assigns a 92.1% probability to a 25-basis-point rate cut and a 7.9% chance of a half-point reduction.

    On Monday, U.S. stocks gained ground after recovering from Friday’s lows. The tech-heavy Nasdaq hit a new record closing high, while all major averages finished higher. The Nasdaq climbed 98.31 points, or 0.5%, to 21,978.70; the Dow added 114.09 points, or 0.3%, to 45,514.95; and the S&P 500 rose 13.65 points, or 0.2%, to 6,495.15.

    Optimism around the Fed’s rate outlook contributed to the strength, particularly following last week’s disappointing employment figures.

    Trading activity remained relatively subdued, as investors awaited the upcoming inflation reports, which could further influence interest rate expectations.

    Among sectors, software stocks led the gains, lifting the Dow Jones U.S. Software Index by 1.2%. Rising gold prices also buoyed precious metals stocks, with the NYSE Arca Gold Bugs Index climbing 1.2%. Networking and retail shares performed well, while telecom, utilities, and natural gas stocks moved lower.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Magnum outlines growth plans ahead of spin-off from Unilever

    Magnum outlines growth plans ahead of spin-off from Unilever

    Magnum, the ice cream label owned by Unilever (LSE:ULVR), has unveiled a set of financial targets as it gets ready to split from its parent company later this year.

    Ahead of a capital markets day presentation, Magnum projected medium-term organic sales growth of 3% to 5% beginning in fiscal 2026. The forecast assumes overall market growth of 3% to 4% and, according to management, should not be expected to materialize every year.

    RBC Capital Markets noted that Magnum’s goals exceed current Visible Alpha consensus estimates for Unilever’s ice cream unit, which sit at 2.7% for 2026 and 2.8% for 2027. The company also stressed that its business model faces only a limited seasonal impact.

    The brand also laid out further targets, including annual adjusted EBITDA margin improvements of 40 to 60 basis points starting in 2026. Free cash flow is expected to fall between €0.8 billion and €1 billion in 2028 and 2029 once capital expenditures normalize at 4% to 5% of sales.

    Magnum plans to maintain a consistent dividend strategy, with a payout ratio of 40% to 60% of adjusted net income. Its first dividend is slated for 2027, tied to fiscal 2026 results.

    The formal separation from Unilever is set for mid-November 2025, after which Magnum will trade independently as a listed company. Following the split, Unilever will retain a minority stake of under 20%.

    RBC analysts called Magnum’s objectives “ambitious,” citing the gap between management’s projections and broader market expectations for the division’s performance.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • FTSE 100 edges up as Anglo surges on merger news, Mobico slumps

    FTSE 100 edges up as Anglo surges on merger news, Mobico slumps

    London’s FTSE 100 traded slightly higher on Tuesday, supported by strength in the mining sector after Anglo American unveiled a major merger deal. By 10:04 GMT, the benchmark index was up 0.2%, while sterling gained 0.3% against the dollar to trade at 1.35.

    On the continent, Germany’s DAX slipped 0.3%, whereas France’s CAC 40 advanced 0.4%.

    Big movers on the FTSE

    Anglo American PLC (LSE:AAL) led the gains, jumping 9.5% after announcing an all-share merger with Canada’s Teck Resources. Teck’s U.S.-listed stock also soared more than 11% in premarket dealings. The tie-up is set to create one of the globe’s largest copper producers.

    According to the terms of the agreement, Teck investors will receive 1.3301 Anglo shares for each Teck share, valuing the Canadian group at roughly £30.39 ($41.20) per share—or about £14.86 billion ($20.17 billion)—based on Anglo’s latest close.

    In sharp contrast, Mobico Group PLC (LSE:MCG) tumbled more than 22% after reporting weaker-than-expected half-year results. Adjusted operating profit dropped 12.7% to £59.9 million, missing consensus estimates of £64.4 million, while statutory losses widened. Still, the company reiterated its full-year guidance. On a constant currency basis, the profit decline was limited to 4.8%, with adjusted pre-tax profit down to £19.8 million from £28.8 million in the same period last year.

    Elsewhere, Dunelm Group PLC (LSE:DNLM) slid 8.3%, the biggest drop on the FTSE 250, after cautioning that consumer demand remains fragile.

    Phoenix Group Holdings PLC (LSE:PHNX) recovered 2.3% after heavy losses in the previous session, when it revealed a rebrand to Standard Life from March 2026 alongside a larger-than-expected decline in book value.

    Among the day’s gainers, Gamma Communications PLC (LSE:GAMA) rose more than 5% on upbeat first-half revenue growth, while Computacenter (LSE:CCC) advanced over 2% after signaling a strong start to its third quarter.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dollar steadies ahead of U.S. jobs data; euro dips on French political turmoil

    Dollar steadies ahead of U.S. jobs data; euro dips on French political turmoil

    The U.S. dollar held steady on Tuesday, rebounding slightly after falling to a seven-week low as investors awaited critical employment and inflation figures likely to reinforce expectations for a Federal Reserve rate cut next week.

    At 04:15 ET (08:15 GMT), the Dollar Index, which measures the greenback against a basket of six major currencies, inched up 0.1% to 97.447, recovering some ground after its slide to the weakest level since late July.

    Payrolls revisions loom

    The dollar has trended lower in recent sessions following data pointing to a softening U.S. labor market. Last Friday’s nonfarm payrolls report revealed a sharp slowdown in job creation for August, while unemployment climbed to nearly a four-year high.

    Later in the day, the U.S. Bureau of Labor Statistics is set to release preliminary benchmark revisions for payrolls covering April 2024 through March 2025. Economists expect a downward adjustment of up to 800,000 jobs, which could indicate the Fed lagging in its pursuit of maximum employment.

    “This time last year, the preliminary revision was -818k and it looks like we would need to see a bigger number than that to trigger a fresh leg lower in short-term U.S. interest rates and the dollar,” said analysts at ING in a note.

    This week also brings the release of the U.S. consumer price index for August, with markets closely monitoring the impact of the Trump administration’s tariffs on inflation.

    Bank of America forecasts U.S. inflation will remain “sticky” in August, projecting headline CPI to rise from 2.7% to 2.9% year-on-year, its highest since last July, while core CPI is expected to hold at 3.1%.

    The Federal Reserve’s next policy meeting is scheduled for next week, where a rate-cut cycle is widely anticipated following a year of steady interest rates.

    Euro pressured by French political uncertainty

    In Europe, EUR/USD slipped 0.1% to 1.1750, pressured by France’s parliament voting down the government on Monday over plans to curb rising national debt, intensifying political uncertainty in the eurozone’s second-largest economy.

    “The question now is whether the discordant political parties decide to agree on the ’what’ (how to reach an agreement on the budget) before agreeing on ’who’ to lead the government. None of this can be seen as good news for the euro,” said ING.

    The European Central Bank is widely expected to keep rates unchanged at its policy meeting on Thursday.

    GBP/USD edged up 0.1% to 1.3560, with the pound benefiting from the weaker dollar, following a gain of more than 0.5% on Friday.

    Yen experiences volatility

    USD/JPY fell 0.3% to 147.07 after wild swings on Monday triggered by Prime Minister Shigeru Ishiba’s unexpected resignation. Ishiba’s departure heightens political uncertainty in Japan, which may delay further rate hikes by the Bank of Japan.

    USD/CNY traded down 0.1% to 7.1270, with the yuan reaching its strongest level since November 2024. This follows the People’s Bank of China setting its highest yuan midpoint in 10 months, amid signs Beijing is strengthening the currency to ease tensions with the U.S. A stronger yuan combined with a softer dollar makes American exports to China more competitive.

    AUD/USD rose 0.3% to 0.6609, reaching a seven-week high, despite a private survey showing that Australian consumer sentiment declined in September and remains weak amid uncertainty over interest rates and slower economic growth.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dow Jones, S&P, Nasdaq, Wall Street, U.S. Futures Tick Higher Ahead of BLS Labor Revisions; Oracle, Anglo Teck, ASML in Focus

    Dow Jones, S&P, Nasdaq, Wall Street, U.S. Futures Tick Higher Ahead of BLS Labor Revisions; Oracle, Anglo Teck, ASML in Focus

    U.S. stock futures inched up on Tuesday as investors prepared for the release of revised employment data, which could shed light on a cooling U.S. labor market. Meanwhile, software giant Oracle (NYSE:ORCL) is set to report after the closing bell, potentially offering fresh insights into the artificial intelligence boom. Corporate developments also grabbed attention, with Anglo American (LSE:AAL) and Teck Resources (NYSE:TECK) agreeing to merge, and ASML (EU:ASML) taking a $1.5 billion stake in French AI start-up Mistral.

    Futures show modest gains

    By 03:42 ET, S&P 500 futures were up 15 points, or 0.2%, Nasdaq 100 futures had gained 69 points, or 0.3%, and Dow futures rose 81 points, or 0.2%. Investors are eyeing the preliminary nonfarm payrolls benchmark revision and upcoming inflation data later this week.

    Wall Street’s major indices advanced in the previous session, with the Nasdaq Composite reaching a fresh record high. Optimism was driven by expectations that the Federal Reserve may soon cut interest rates to support a slowing labor market.

    Individual stocks saw notable movements: shares of retail app Robinhood and software publisher AppLovin rose on inclusion plans for the S&P 500 index. Chipmaker Broadcom jumped 3.2% after signaling strong AI-driven revenue growth, giving it a market cap of $1.6 trillion, making it Wall Street’s seventh-largest company.

    BLS benchmark revisions

    Traders are awaiting the Bureau of Labor Statistics’ preliminary nonfarm payrolls benchmark, with economists projecting a potential downward revision of up to one million jobs for the year through March. This would reinforce signs of a softening labor market, possibly predating President Donald Trump’s sweeping reciprocal tariffs introduced in early April.

    Analysts also point to stricter immigration enforcement and the rise of AI as contributing factors to slower job growth. Last week’s BLS data showed weaker-than-expected gains in August, and June saw the first job losses in four-and-a-half years, reinforcing expectations that the Fed will likely cut rates by at least 25 basis points at its September meeting.

    Oracle earnings spotlight

    Oracle is scheduled to report after the bell on Tuesday, with markets watching for indications of the AI-driven business boom. Analysts at Vital Knowledge highlighted two key metrics: backlog, measured by remaining performance obligations, expected near $150 billion, and free cash flow, projected at $1.8 billion after a negative $2.9 billion last quarter due to higher capital expenditures.

    In June, Oracle raised its annual revenue forecast, citing strong demand for cloud services supporting AI infrastructure. CEO Safra Catz indicated fiscal 2026 revenue would reach at least $67 billion, implying 16.7% growth compared with the previous outlook of 15%.

    Anglo American and Teck merge

    Anglo American and Teck Resources announced a merger to form a new entity, Anglo Teck, valued at over $53 billion. The combined company will become one of the world’s top copper producers, capitalizing on growing demand for copper in renewable energy and AI data centers. Both miners operate adjacent copper mines in Chile.

    Under the merger, London-listed Anglo American will hold 62.4% of the new company, while Canada’s Teck will retain 37.6%.

    ASML invests in Mistral AI

    ASML also revealed a strategic investment in French AI start-up Mistral, acquiring a $1.5 billion stake (1.3 billion euros) and becoming the largest shareholder. The partnership will allow ASML to explore AI applications across its product lines and R&D operations.

    The investment is part of Mistral’s $2 billion Series C funding round, valuing the start-up at $11.7 billion (10 billion euros), potentially making it Europe’s most valuable AI company. Mistral is considered a European rival to U.S. AI leaders like OpenAI and Google, and ASML’s advanced lithography equipment plays a critical role in chipmaking for major customers such as TSMC and Intel, supporting AI-driven growth.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
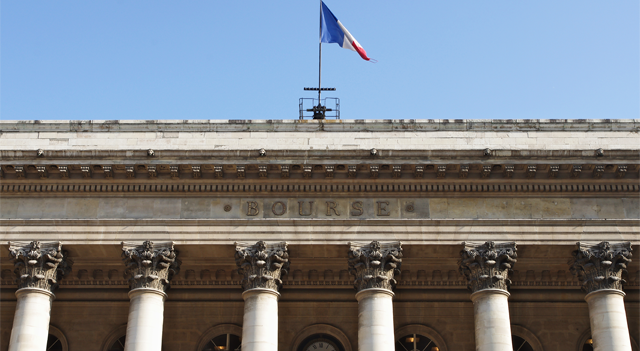
  • DAX, CAC, FTSE100, European Stocks Trade Sideways as French Political Uncertainty and U.S. Inflation Data Loom

    DAX, CAC, FTSE100, European Stocks Trade Sideways as French Political Uncertainty and U.S. Inflation Data Loom

    European equities moved in narrow ranges on Tuesday as investors weighed the latest political developments in France and awaited crucial U.S. inflation figures.

    At 07:05 GMT, Germany’s DAX slipped 0.1%, France’s CAC 40 advanced 0.2%, and the U.K.’s FTSE 100 inched up 0.1%.

    French Political Instability

    France’s minority government led by Prime Minister François Bayrou collapsed on Monday after he lost a confidence vote, with Parliament voting 364-194 in favor of his removal. The defeat came after Bayrou failed to secure backing from opposition factions on both the right and left for 2026 budget plans aimed at narrowing the country’s large deficit.

    President Emmanuel Macron must now appoint France’s fifth prime minister in under two years. While he is expected to select another centrist ally to lead a minority government, this solution is unlikely to resolve underlying political instability. French markets will face additional scrutiny on Friday when Fitch Ratings reviews the country’s AA- rating with a negative outlook, following last year’s downgrade by Moody’s after the prior government’s collapse.

    U.S. Inflation in Focus

    Despite political turbulence in Europe, market losses are expected to remain modest as investors anticipate upcoming U.S. inflation data, which will help gauge whether the Federal Reserve will cut interest rates next week. Market expectations are high for a September 16-17 rate reduction, though it is still unclear if the Fed will opt for a standard 25-basis-point cut or a larger 50-bps move.

    Corporate Highlights

    In corporate news, Dutch chip equipment maker ASML (EU:ASML) invested €1.3 billion ($1.5 billion) in French AI startup Mistral AI, becoming its largest shareholder. The companies also agreed on a strategic partnership to explore AI applications across ASML’s products and R&D.

    Swiss pharmaceutical firm Novartis (BIT:1NOVN) announced plans to acquire U.S.-based Tourmaline Bio (NASDAQ:TRML) for $48 per share, valuing the biotech at $1.4 billion fully diluted.

    Oil Prices Rise on Modest OPEC+ Production Increase

    Crude continued higher after OPEC+ agreed to increase output in October by only 137,000 barrels per day, far below the monthly hikes of 555,000 bpd in September and August, and 411,000 bpd in previous months.

    At 03:05 ET, Brent futures rose 0.8% to $66.57 a barrel, while U.S. West Texas Intermediate crude advanced 0.9% to $62.81 a barrel. Prices were also supported by speculation of additional sanctions on Russia, as U.S. President Donald Trump indicated he was ready to move to a “second phase” of restrictions following continued attacks on Ukraine.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
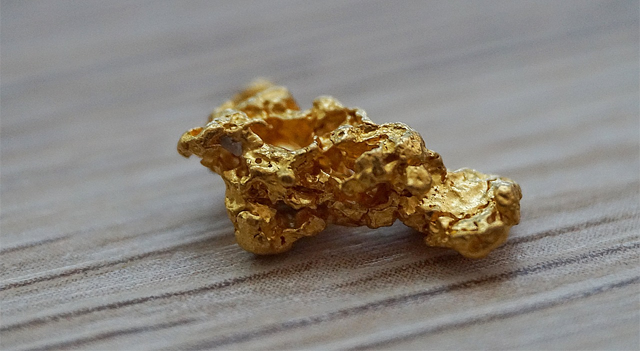
  • Gold Climbs to Record Above $3,650/oz on Rate Cut Speculation and Safe-Haven Demand

    Gold Climbs to Record Above $3,650/oz on Rate Cut Speculation and Safe-Haven Demand

    Gold prices surged to new record levels in Asian trading on Tuesday, extending strong gains from previous sessions amid mounting expectations of a Federal Reserve interest rate cut next week and a softer U.S. dollar.

    Investor demand for safe-haven assets was further supported by political instability in France, where Prime Minister Francois Bayrou resigned following a failed vote of confidence in the National Assembly. Additional uncertainty in Japan, after PM Shigeru Ishiba stepped down, and the possibility of further U.S. sanctions on Russia following Moscow’s deadly weekend strike against Ukraine, also bolstered gold’s appeal.

    At 00:44 ET (04:44 GMT), spot gold traded 0.6% higher at a record $3,656.70 an ounce, while December Gold Futures peaked at $3,695.25/oz.

    Fed Easing Expectations Propel Gold

    Bullion has climbed sharply since last week, driven by data showing a cooling U.S. labor market, most notably nonfarm payrolls, which indicated minimal job growth in August. These reports fueled expectations that the Fed will cut interest rates in September, with markets pricing in a 92.4% chance of a 25-basis-point reduction during the Fed’s September 16-17 meeting, according to CME FedWatch. A 7.6% probability of a larger 50-basis-point cut is also factored in.

    Several Fed officials have signaled openness to rate cuts amid the softening labor market but have cautioned that inflation remains persistent, particularly with price increases stemming from U.S. President Donald Trump’s trade tariffs. Markets will monitor U.S. inflation data for August for further signals, as most of Trump’s tariffs took effect last month. Lower rates generally support gold and other non-yielding metals by reducing the opportunity cost compared with government bonds.

    Broader Metal Markets Show Gains

    Other precious metals also rose on Tuesday. Platinum Futures were up 0.6% at $1,397.25/oz, while Silver Futures added 0.2% to $41.30 an ounce, slightly below last week’s 14-year high.

    Copper prices inched higher, with London Metal Exchange benchmark futures up 0.2% at $9,940.15 a ton, and U.S. Copper Futures rising 0.2% to $4.58 per pound.

    “Uncertainty over US tariffs on copper imports shifted supply from China to the US in the first half of the year. This trend may reverse in the second half, as Trump has delayed plans for a 50% tariff on refined copper for now,” ING analysts noted.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.