Blog

  • Vesuvius Delivers Solid H1 2025 Results Despite Global Market Headwinds

    Vesuvius Delivers Solid H1 2025 Results Despite Global Market Headwinds

    Vesuvius plc (LSE:VSVS) has released its financial results for the first half of 2025, reporting outcomes largely aligned with market expectations amid a tough global environment. The company successfully expanded its market presence and executed effective cost-saving initiatives. However, it continued to face headwinds from subdued demand and pricing pressures, particularly in European and Chinese markets.

    The steel segment performed notably well, gaining market share—especially in India—while the foundry division maintained a steady course. Additionally, Vesuvius made headway in integrating its PiroMet acquisition and enhanced the efficiency of its R&D operations, with a strong emphasis on boosting sales of newly developed products. The firm expects a similar performance trend in the second half of the year, and remains optimistic about its long-term growth prospects and improved profitability.

    From a financial perspective, Vesuvius retains a strong and balanced profile, marked by solid operating margins and signs of undervaluation. Positive corporate developments continue to support the company’s position, though technical indicators reflect bearish investor sentiment, and slowing revenue growth poses an ongoing concern.

    About Vesuvius plc

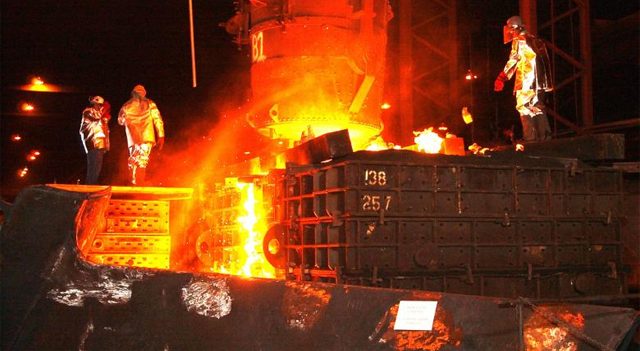
    Vesuvius is a global leader in molten metal flow engineering, offering advanced technologies to process industries operating under extreme temperatures. Its product suite includes high-performance flow control systems, advanced refractory materials, and technical services tailored to improve operational safety, efficiency, and environmental sustainability. With a global footprint of cost-effective production sites and technology hubs, the company is focused on delivering long-term, profitable, and sustainable growth for shareholders.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • abrdn European Logistics Income PLC Progresses with Asset Disposals and Shareholder Returns

    abrdn European Logistics Income PLC Progresses with Asset Disposals and Shareholder Returns

    abrdn European Logistics Income PLC (LSE:ASLI) has completed the sale of its logistics facility in Zeewolde, Netherlands, for €27.2 million. This transaction is part of the company’s ongoing managed wind-down, aimed at gradually divesting its portfolio. To date, the firm has raised more than €320 million by offloading 17 of its original 27 properties. The company intends to continue returning capital to investors and has made substantial progress in cutting its debt levels. However, the future tax impact from unrealized capital gains remains unclear and will depend on the structure of upcoming transactions.

    The outlook for abrdn European Logistics Income PLC is mixed. While recent financial performance has stabilized, the company has a track record of volatility. From a technical perspective, there are signs of upward momentum, though indicators also point to potential overbought conditions. Its valuation is relatively high, reflected in a stretched price-to-earnings ratio, but the dividend yield offers some support. Strategic decisions and corporate activity suggest further changes ahead, which could affect both operational performance and income distribution.

    About abrdn European Logistics Income PLC

    Operating within the European logistics real estate market, abrdn European Logistics Income PLC specializes in acquiring and managing logistics assets across the continent. The company is currently in the process of winding down its operations, aiming to liquidate its portfolio and return proceeds to shareholders.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • U.S. Stocks Tick Higher as Palantir Surges, Trade Gap Narrows

    U.S. Stocks Tick Higher as Palantir Surges, Trade Gap Narrows

    U.S. stock index futures moved modestly higher on Tuesday, pausing after recent volatility as earnings season presses on.

    As of 09:35 ET, the Dow Jones Industrial Average was up 60 points (0.1%), while the S&P 500 and NASDAQ Composite each rose 0.1%.

    Markets rebounded on Monday from last week’s sharp declines, which had been triggered by fresh tariff threats and weaker-than-expected U.S. jobs data.

    Rate Cut Optimism Supports Markets

    Investor sentiment has improved amid rising expectations for a Federal Reserve rate cut in September. The odds of a rate reduction next month have climbed to roughly 90%, up from 63% a week ago, according to CME FedWatch data.

    President Donald Trump renewed trade tensions on Monday by threatening higher tariffs on Indian goods due to its purchases of Russian oil. Yet, the market shrugged this off, instead focusing on the potential for Fed stimulus following soft economic data.

    On the economic front, attention turns Tuesday to the ISM non-manufacturing PMI, forecast to edge up to 51.5 in July from 50.8 in June. A reading above 50 signals expansion in the crucial services sector, which makes up more than two-thirds of the U.S. economy.

    Meanwhile, the U.S. trade deficit shrank more than expected in June, narrowing by 16% to $60.2 billion from $71.7 billion in May. The drop, driven by a pullback in imports, outperformed economist forecasts of $62.6 billion.

    Palantir Headlines Corporate Earnings

    Earnings have generally come in strong, with upbeat guidance and relatively muted concerns over tariffs helping support equities.

    Palantir Technologies (PLTR) surged after reporting its highest quarterly revenue since going public, fueled by increased demand for its AI-driven software from both governments and businesses. The company has benefited from the White House’s AI initiatives and the Pentagon’s interest in working with non-traditional tech vendors.

    Other corporate highlights:

    • Pfizer (PFE) gained after beating Q2 earnings and revenue estimates, and raising its full-year profit outlook.
    • Marriott International (MAR) also climbed on better-than-expected Q2 earnings, despite trimming its full-year forecast due to reduced federal spending and softer business travel.
    • Caterpillar (CAT), however, fell after reporting Q2 earnings that missed forecasts, even as revenue topped expectations.

    Oil Prices Extend Declines

    Crude prices slipped again Tuesday, extending losses following OPEC+‘s decision to boost output despite an uncertain demand backdrop.

    As of 09:35 ET, Brent crude was down 1% at $68.10 per barrel, while WTI dropped 1.1% to $65.57. Both benchmarks posted their fourth straight session of losses on Monday, settling at their lowest levels in a week.

    OPEC+ announced on Sunday it would increase production by 547,000 barrels per day in September, fully reversing previous cuts totaling 2.5 million bpd, or roughly 2.4% of global demand.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • DAX, CAC, FTSE100, European Stocks Edge Higher as Earnings Drive Momentum and U.S. Rate Cut Hopes Grow

    DAX, CAC, FTSE100, European Stocks Edge Higher as Earnings Drive Momentum and U.S. Rate Cut Hopes Grow

    European markets kicked off the week with solid gains as investors weighed a series of corporate earnings results and looked ahead to potential monetary easing from the U.S. Federal Reserve.

    Sentiment improved further after economic data showed a slight improvement in Eurozone business activity. The HCOB Eurozone Composite PMI, compiled by S&P Global, ticked up to 50.9 in July from 50.6 in June, though it remained just under the flash estimate of 51.0. Separately, Eurostat (EU:ETL) reported that producer prices in the bloc rose 0.8% month-over-month in June.

    Major indices across the continent moved higher:

    • Germany’s DAX climbed 0.8%
    • France’s CAC 40 added 0.3%
    • The UK’s FTSE 100 rose 0.4%

    Key Stock Movers on Earnings:

    • Gerresheimer (TG:GXI) rallied nearly 3% after revealing plans to carve out and eventually sell its underperforming molded glass business.
    • Rational AG (TG:RAA) advanced 2.2% after affirming its annual growth forecast, backed by improved Q2 figures.
    • Continental AG (TG:CON) slipped 1.3% as lower second-quarter sales disappointed investors.
    • Hugo Boss (TG:BOSS) jumped 7% on stronger-than-expected quarterly operating profit.
    • Infineon Technologies (TG:IFX) surged 4.7% after beating Q3 expectations and raising its operating margin forecast.
    • Fresenius Medical Care (NYSE:FMS) dropped 3.4% after delivering weaker quarterly results.
    • Aurubis AG (TG:NDA) rose 3.3% after exceeding profit forecasts for the first nine months of its fiscal year.
    • Adecco Group (BIT:1ADEN) lost 2%, with Q2 revenue showing only moderate growth.
    • Travis Perkins (LSE:TPK) climbed 6.5% on improved pre-tax profits for the first half of the year.
    • Smith & Nephew (LSE:SN.) soared 15% after announcing a $500 million share buyback program, alongside a strong H1 earnings report.
    • Domino’s Pizza Group (LSE:DOM) plunged 14% after cutting its full-year profit guidance.
    • BP Plc (LSE:BP.) gained 2.2% following a return to profitability in the second quarter.
    • Diageo (LSE:DGE) rose 6.5% despite a 30% drop in annual profit, suggesting investors looked past the earnings dip.
    • Fresnillo (LSE:FRES) popped 7.6% as the miner posted a fourfold surge in first-half net income.

    With more earnings on the way and speculation building over potential rate cuts in the U.S., European markets appear poised to maintain their upward trajectory — at least in the short term.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dow Jones, S&P, Nasdaq, Wall Street Futures Signal Further Gains After Strong Market Rally

    Dow Jones, S&P, Nasdaq, Wall Street Futures Signal Further Gains After Strong Market Rally

    U.S. stock index futures suggest a modestly higher open on Tuesday, indicating that investors are likely to build on the solid gains seen in the previous trading session.

    Tech shares look set to continue their upward momentum, boosted by Palantir’s (NASDAQ:PLTR) impressive quarterly earnings report. The software company’s shares jumped nearly 7% in pre-market trading after revealing a nearly 50% surge in sales during the second quarter, driven by strong demand for AI services.

    DuPont (NYSE:DD) is also showing notable pre-market strength after posting better-than-expected Q2 results and raising its outlook.

    In contrast, Caterpillar (NYSE:CAT) shares could face downward pressure following weaker-than-anticipated earnings for the quarter. Similarly, telehealth firm Hims & Hers Health (NYSE:HIMS) may see a decline after missing revenue estimates for Q2.

    Trading volumes might be relatively light as market participants pause to digest recent volatility.

    On Monday, stocks climbed sharply at the open and maintained gains throughout the session. The rally helped recover much of the losses from the previous two days. By the close, the major indexes hovered near session highs: the Nasdaq gained 403.45 points (2.0%) to finish at 21,053.58, the S&P 500 rose 91.93 points (1.5%) to 6,329.94, and the Dow added 585.06 points (1.3%) to close at 44,173.64.

    This rebound came as investors snapped up shares following last week’s sell-off, which pushed the Nasdaq and S&P 500 significantly below their record highs. Friday’s drop was fueled by concerns over new tariffs announced by President Donald Trump, disappointing jobs data, and a sharp pullback in Amazon’s (NASDAQ:AMZN) stock.

    Optimism that weaker employment figures could prompt the Federal Reserve to cut interest rates next month also supported buying. The CME Group’s FedWatch tool now shows a 91.9% probability of a 25-basis-point rate cut in September, up from 63.1% just a week ago.

    On the economic front, the Commerce Department reported a sharp 4.8% decline in factory orders for June, reversing the revised 8.3% surge seen in May. Economists had predicted a 5% drop, following an initially reported 8.2% gain the previous month.

    Networking stocks led the charge on Monday, with the NYSE Arca Networking Index soaring 10% to a record closing level. CommScope (NASDAQ:COMM) was a standout, rocketing 86.3% after announcing the sale of its connectivity and cable solutions division to Amphenol (NASDAQ:APH).

    Gold miners also gained, buoyed by a rising gold price, pushing the NYSE Arca Gold Bugs Index up 4.7%. Other sectors such as software, brokerage, and computer hardware also experienced solid advances alongside most major market groups.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • UK Services Sector Experiences Sharpest Decline in New Orders Since Late 2022

    UK Services Sector Experiences Sharpest Decline in New Orders Since Late 2022

    New order volumes in the UK services industry fell in July at their steepest rate since November 2022, according to a Tuesday survey that may intensify the Bank of England’s worries over economic growth.

    The S&P Global Purchasing Managers’ Index (PMI) for UK services dropped to 51.8 in July from 52.8 in June, a decline less severe than an earlier estimate of 51.2.

    While the index remains above the 50 threshold that indicates expansion, the sector also saw the quickest pace of job cuts in six months.

    This report comes ahead of the Bank of England’s interest rate announcement on Thursday, where a rate cut from 4.25% to 4% is widely anticipated, marking the fifth reduction in the current tightening cycle.

    However, some members of the policymaking committee may favor holding rates steady due to inflation surging well beyond the 2% target.

    The softer services data adds complexity to the bank’s balancing act between curbing inflation and supporting a slowing economy.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Ryanair Reports 2.5% Passenger Increase in July, Reaching 20.7 Million Travelers

    Ryanair Reports 2.5% Passenger Increase in July, Reaching 20.7 Million Travelers

    Ryanair (LSE:0RYA) announced on Tuesday that its passenger traffic in July grew by 2.5%, totaling 20.7 million travelers, with a strong load factor of 96%.

    The Irish budget airline remains confident about achieving its full fiscal year 2026 forecast of 206 million passengers, consistent with market expectations.

    Analysts estimate that Ryanair will transport around 61 million passengers during the second quarter.

    To meet its annual goal, the airline is expected to sustain roughly 2% passenger growth in August and September.

    Supporting this outlook, aviation data from Cirium indicates seat capacity increases that align with anticipated growth rates of 2% in August and 1% in September.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • BP’s Q2 profit slips year-on-year but surpasses forecasts

    BP’s Q2 profit slips year-on-year but surpasses forecasts

    BP (LSE:BP.) posted second-quarter earnings that exceeded analyst expectations on Tuesday, rebounding despite recent turbulence in the global oil and gas landscape.

    The company’s underlying replacement cost (RC) profit for Q2 rose to $2.4 billion, up from $1.4 billion in the first quarter, driven by stronger results across its business units.

    Although this represented a decrease from the $2.76 billion recorded in the same quarter last year, it outperformed the consensus estimate of $1.81 billion compiled by LSEG.

    Operating cash flow reached $6.3 billion, a significant increase from $2.8 billion in Q1, despite factoring in a $1.1 billion payment related to a Gulf of Mexico settlement.

    The oil production segment delivered an underlying RC profit of $2.3 billion, falling short of last year’s figures due to weaker prices realized and higher depreciation charges.

    Production grew 2.5% year-over-year, reaching 1.52 million barrels of oil equivalent per day, while realized liquids prices declined to $59.74 per barrel from $73.05 a year earlier.

    Gas and low carbon energy generated $1.5 billion in underlying RC profit, remaining largely flat year-on-year as reduced production was balanced by improved margins. Production in this segment dropped 13% following divestments in Egypt and Trinidad.

    The customers and products division saw underlying RC profit climb to $1.5 billion from $1.1 billion a year ago, supported by stronger trading and midstream activities that offset softer refining margins. BP’s refining availability remained robust at 96.4%.

    “We are delivering our plan with operational reliability above 96%,” said CEO Murray Auchincloss. “We remain fully focused on delivering safely and reliably, maintaining capital discipline and driving performance improvement.”

    He added that BP is undertaking a strategic review of its portfolio to “ensure we are maximizing shareholder value.”

    Capital expenditure for the quarter totaled $3.4 billion. Net debt decreased to $26.0 billion from $27.0 billion in Q1, aided by $1.4 billion in divestment proceeds.

    BP also increased its dividend by 4% to 8.32 cents per share and announced a new $750 million share repurchase program.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Spectris shares climb as KKR sweetens takeover bid

    Spectris shares climb as KKR sweetens takeover bid

    Spectris PLC (LSE:SXS) shares rose 1.7% on Tuesday following an announcement that KKR has raised its cash offer to acquire all outstanding and forthcoming shares of the company.

    The updated bid values Spectris at £41.75 per share, consisting of £41.47 in cash plus an interim dividend of 28 pence per share.

    This offer is 1.8% higher than Advent International’s previous bid of £41.00 per share, placing Spectris’s overall valuation at around £4.2 billion and implying an enterprise value of approximately £4.8 billion.

    KKR’s increased proposal, to be executed via a court-approved scheme of arrangement, represents a substantial premium of 104.9% compared to Spectris’s closing price of £20.38 on June 6, 2025 — the last trading day before the offer period commenced.

    In light of the improved offer, Spectris’s board has unanimously withdrawn its prior recommendation for Advent International’s bid and now urges shareholders to support the KKR scheme at the forthcoming court and general meetings set for August 27, 2025.

    The deal is anticipated to complete by or before Q1 2026, pending satisfaction of all customary closing conditions.

    KKR plans to fund the additional cash component through a mix of equity from its managed funds and debt financing. Some equity co-investors, including groups managed by Neuberger Berman and Pathway Capital Management, will hold passive minority stakes.

    The bid values Spectris at 20.3 times adjusted EBITDA and 23.9 times adjusted EBIT for the fiscal year ended December 31, 2024.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.

  • XP Power posts weak first-half 2025 results but stays optimistic

    XP Power posts weak first-half 2025 results but stays optimistic

    XP Power Ltd (LSE:XPP) reported Tuesday an EBITA of £4.8 million for the first half of 2025, missing analyst forecasts by 42%, largely due to a £2.3 million foreign exchange headwind.

    Revenue declined 11% year-over-year on a constant currency basis, totaling £111 million, and was down 13% on a reported basis.

    Despite the headwinds, the company’s book-to-bill ratio improved to 1.02x for the period, up from 0.7x in the first half of 2024.

    Order intake rose 28% year-over-year to £113 million across all sectors. By segment, semiconductors posted a book-to-bill of 0.88x, industrial technology led with 1.20x, and healthcare came in at 0.94x.

    Adjusted earnings per share fell sharply to 0.4p, a 98% drop compared to last year. Net debt was reduced by 44% to £57.9 million, aided by a share placement, with the net debt to EBITDA ratio at 1.8x.

    On a brighter note, gross margin improved by 80 basis points year-on-year despite revenue pressures. The company also announced new cost-saving measures expected to deliver £5.5 million in savings in the second half of 2025.

    Management expects “healthy sequential progress” during the second half, highlighting early signs of improvement in key markets.

    However, they cautioned that full-year results will depend on the strength of the fourth-quarter order book, with a “range of outcomes” possible.

    Shares of XP Power are currently priced at 851.00p. Jefferies analysts maintain a hold rating and set a price target of 900.00p, implying about 6% upside.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.