Blog

  • US Stock Market Wrap: S&P 500 Ends Flat as EU Tariff Threats Resurface

    US Stock Market Wrap: S&P 500 Ends Flat as EU Tariff Threats Resurface

    U.S. stocks ended Friday on a mixed note, with the S&P 500 closing flat amid renewed trade tensions with Europe. Despite the muted session, the benchmark index posted a gain for the week.

    By the closing bell, the Dow Jones Industrial Average fell 142 points (0.3%), the S&P 500 was virtually unchanged, and the NASDAQ Composite ticked up 0.1%.

    Market sentiment took a hit after the Financial Times reported that President Donald Trump is considering tariffs of 15% to 20% on goods imported from the European Union. The proposed levy—well above the 10% the EU had hoped for—suggests trade negotiations may have stalled. With the August 1 deadline fast approaching, the move appears designed to pressure the EU into making broader concessions.


    Earnings Season Gathers Momentum

    Investors continue to digest second-quarter earnings, which have been largely better than expected so far:

    • American Express (AXP) climbed after the credit card company beat profit estimates, fueled by strong spending from high-income consumers.
    • 3M (MMM) rose after raising its full-year earnings outlook, benefiting from cost-cutting efforts and a shift toward higher-margin products.
    • Charles Schwab (SCHW) advanced after reporting strong quarterly results driven by asset growth and improved net interest margins.
    • Netflix (NFLX) delivered solid earnings and raised its revenue guidance for the year, but shares pulled back slightly as results fell short of sky-high analyst expectations. Even so, Netflix stock is up over 43% year-to-date, supported by confidence in its dominance in the streaming sector.

    Looking ahead, the earnings calendar remains busy next week, with reports expected from Coca-Cola (KO), Texas Instruments (TXN), Alphabet (GOOGL), and Tesla (TSLA).


    Consumer Sentiment Improves as Inflation Expectations Ease

    The University of Michigan’s consumer sentiment index rose to 61.8, slightly above expectations of 61.5. One-year inflation expectations dropped to 4.4%, down from 5.0% previously—an encouraging sign for consumers and policymakers.

    Recent economic data has shown resilience: retail sales beat forecasts, weekly jobless claims declined, and June inflation remained largely in line with estimates. However, tariffs are beginning to put upward pressure on select consumer goods.

    Amid these developments, the Federal Reserve has adopted a cautious, wait-and-see stance. Still, Fed Governor Christopher Waller said Thursday that a rate cut at the Fed’s next meeting could be warranted, citing growing risks to the economy.

    Waller also emphasized that the recent inflation uptick driven by tariffs is likely temporary and shouldn’t alter the Fed’s broader policy outlook.

    Meanwhile, President Trump continues to push the Fed to act more aggressively in lowering interest rates to support economic growth.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • DAX, CAC, FTSE100, European Markets Show Divergent Moves as Tariff Concerns Ease Amid Strong US Data

    DAX, CAC, FTSE100, European Markets Show Divergent Moves as Tariff Concerns Ease Amid Strong US Data

    European equities exhibited a mixed bag of results on Friday, buoyed in part by encouraging U.S. economic indicators and solid technology sector earnings, which have temporarily eased fears surrounding tariffs.

    The German DAX slipped 0.3%, while the French CAC 40 edged up 0.1%, and London’s FTSE 100 gained 0.2%.

    On the economic front, German producer prices continued their downward trend, falling for the fourth consecutive month in June, driven by lower energy costs, according to Destatis. The producer price index registered a 1.3% decline year-over-year, accelerating from May’s 1.2% drop.

    In corporate news, engineering firm Senior (LSE:SNR) rallied after announcing the sale of its Aerostructures business for up to £200 million and unveiling a £40 million share repurchase plan.

    Luxury goods company Burberry Group (LSE:BRBY) also saw its shares climb following a better-than-anticipated performance in first-quarter comparable sales.

    Chemical industry heavyweight BASF SE (TG:BAS) rose after finalizing a decade-long natural gas supply contract with Equinor.

    Defense contractor Saab (BIT:1SAAB) jumped after reporting stronger-than-expected profits and sales for the second quarter.

    Conversely, Salzgitter AG (TG:SZG) shares tumbled after the German steelmaker lowered its full-year outlook due to a sluggish second quarter.

    Pharmaceutical giant GSK (LSE:GSK) faced pressure after a U.S. FDA advisory panel advised against approval of its blood cancer treatment, Blenrep.

    Lastly, Electrolux, the Swedish appliance manufacturer, dropped sharply despite posting second-quarter operating profits above forecasts.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dow Jones, S&P, Nasdaq, U.S. Stocks Poised for Further Gains in Early Trading

    Dow Jones, S&P, Nasdaq, U.S. Stocks Poised for Further Gains in Early Trading

    U.S. stock futures indicate a modestly higher open on Friday, potentially extending gains from the past two sessions. Positive economic data and strong corporate earnings are supporting investor optimism despite ongoing trade war concerns.

    Shares of 3M (NYSE:MMM) jumped 2.7% pre-market after reporting better-than-expected Q2 results and raising full-year sales guidance. American Express (NYSE:AXP) also looks set for gains following its strong quarterly earnings.

    Conversely, Netflix (NASDAQ:NFLX) fell 2.9% pre-market despite beating Q2 estimates, due to a warning about lower operating margins in the second half.

    Housing stocks may benefit from a Commerce Department report showing new U.S. residential construction rebounded more than expected in June.

    On Thursday, the Nasdaq and S&P 500 reached record closing highs, with the Nasdaq up 0.7%, S&P 500 up 0.5%, and Dow up 0.5%.

    Economic reports showed retail sales rose 0.6% in June, beating forecasts, and first-time jobless claims fell to a three-month low of 221,000. Import prices increased less than expected.

    Market sectors performing well include networking, oil services, financials, steel, and software. Pharmaceutical and healthcare stocks lagged.

    Chris Zaccarelli, CIO of Northlight Asset Management, noted that despite tariff concerns, the strong economy and consumer spending continue to fuel stock market gains.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • CFI Partners with Etihad Arena to Elevate Trading Brand Across UAE Entertainment Scene

    CFI Partners with Etihad Arena to Elevate Trading Brand Across UAE Entertainment Scene

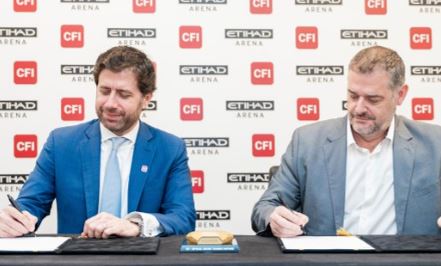
    In a bold move to fuse finance with entertainment, CFI Financial Group has been named the Official Online Trading Partner of Etihad Arena, the UAE’s largest indoor venue and a regional hub for world-class events.

    The partnership grants CFI premium brand visibility across Etihad Arena’s packed calendar of concerts, sporting spectacles, and cultural showcases. As part of the deal, CFI will operate a dedicated fan activation space, host clients in a luxury hospitality suite, and offer VIP experiences including meet-and-greets and exclusive giveaways.

    “Etihad Arena has become a regional hub for entertainment, sports and culture, and we are thrilled to join forces with a venue that shares our passion for high performance and innovation,” said Ziad Melhem, CEO of CFI Financial Group.

    The collaboration reflects CFI’s strategy to deepen engagement with audiences through lifestyle platforms, complementing its existing partnerships with AC Milan, MI Cape Town, and the Department of Culture and Tourism – Abu Dhabi.

    Marcus Osborne, General Manager at Etihad Arena, welcomed the alliance: “This partnership reflects our shared vision of delivering extraordinary experiences to fans while championing innovation and excellence.”

    With this latest move, CFI continues to expand its footprint across the MENA region, blending financial literacy with immersive brand experiences and positioning itself as a dynamic force in both trading and entertainment.

  • Helium One Gains Tanzania Mining Licence and £10M Institutional Backing to Advance Helium Projects

    Helium One Gains Tanzania Mining Licence and £10M Institutional Backing to Advance Helium Projects

    Helium One Global Ltd (LSE:HE1) has officially received a mining licence for its Southern Rukwa helium site in Tanzania and secured a £10 million investment from three institutional investors, marking a major step forward in its plans to develop two potentially valuable helium sources.

    The AIM-listed exploration company, which also holds a 50% stake in the Galactica-Pegasus venture in Colorado, said the fresh capital will be used to fund upcoming testing activities in Southern Rukwa and support the U.S. project’s progress toward first gas and initial cash flow by Q4.

    In addition to the institutional backing, Helium One intends to launch a £1 million retail offering, giving current shareholders a chance to take part in the company’s fundraising efforts.

    The £10 million funding, facilitated by Marex Financial, is structured as an advance that can be converted into equity at the investors’ discretion, using a predetermined discount on the company’s share price. Any portion not converted must be repaid within 12 months—either in cash, shares, or a mix of both.

    Chairman James Smith described the raise as “an important step” that will help advance both the Tanzania and U.S. projects toward production and revenue generation.

    CEO Lorna Blaisse emphasized the significance of the developments, stating that the mining licence approval and new funding represent “a key milestone” for the Southern Rukwa site, particularly at the Itumbula West discovery.

    Now holding a 480km² mining licence and operating under the joint venture Songwe Helium, the company is preparing for further testing in the final quarter of the year. This will involve re-entering the previously drilled ITW-1 well and using an electric submersible pump to initiate artificial lift, increasing gas flow and enabling better measurement of helium content in target rock layers.

    The results will inform final planning for development and processing infrastructure. Regulatory details for Southern Rukwa are still being finalized, and a formal signing date remains pending. However, the Tanzanian government has already agreed to a 17% free carried interest in the project.

    Meanwhile, the Galactica-Pegasus project in Colorado, operated by Blue Star Helium, is also expected to benefit from the new funding, with initial gas production targeted before the year’s end.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Exness Halts New Registrations in India Amid Regulatory Uncertainty

    Exness Halts New Registrations in India Amid Regulatory Uncertainty

    Global forex broker Exness has abruptly suspended new client registrations in India, sparking concern among traders and affiliate partners. The move, which took effect late last week, blocks access to account creation for users with Indian IP addresses. Visitors are now redirected to a simplified login page, with no option to sign up.

    The company has yet to issue a formal statement explaining the decision or clarifying whether the restriction is temporary. Affiliate partners were notified to cease all client acquisition efforts in India, further fueling speculation about the broker’s future in the region.

    Despite the registration freeze, existing Indian clients remain unaffected. Users with active accounts can continue trading without disruption, according to current access paths.

    India has long been a key growth market for offshore brokers like Exness, which operated locally through affiliates and introducing brokers. However, the country’s tightening regulatory landscape — including stricter oversight from the Securities and Exchange Board of India (SEBI) and the Reserve Bank of India (RBI) — may be prompting a strategic retreat.

    As of now, Exness has not indicated whether similar restrictions will be applied in other jurisdictions. The situation remains fluid, with industry observers awaiting further updates.

  • Dow Jones, S&P, Nasdaq, Futures climb; Netflix earnings in focus; Michigan sentiment report incoming — market movers

    Dow Jones, S&P, Nasdaq, Futures climb; Netflix earnings in focus; Michigan sentiment report incoming — market movers

    U.S. stock futures edged up Friday as investors focused on upcoming corporate earnings and economic indicators. Netflix (NASDAQ:NFLX) beat earnings expectations but shares slipped as analysts noted the results fell short of very high hopes. Meanwhile, a key consumer sentiment report is due soon, and Bitcoin advanced after the U.S. House passed three bills aimed at providing clear regulatory guidelines for digital assets.

    Futures gain ground

    U.S. futures climbed slightly Friday, hinting at a continuation of the previous session’s gains, which were driven by upbeat second-quarter earnings and signs of steady economic growth despite ongoing tariff concerns.

    By 03:51 ET, Dow futures were up 64 points (0.1%), S&P 500 futures rose 8 points (0.1%), and Nasdaq 100 futures added 27 points (0.1%).

    Wall Street’s main indexes gained Thursday, buoyed by a wave of positive corporate earnings and optimistic executive commentary. Economic data this week also suggests the U.S. economy is picking up speed, though inflation pressures linked to President Donald Trump’s aggressive trade policies persist.

    Economists caution that tariffs may raise prices and slow growth, but uncertainty remains about how severe the impact might be.

    “[O]ur base case remains that the tariffs ultimately imposed will not cause a recession — though we expect growth to slow,” Capital Economics analysts wrote in a note.

    Netflix earnings

    Netflix shares dipped slightly in after-hours trading despite solid Q2 earnings and guidance. The streaming giant posted a diluted EPS of $7.19, beating estimates of $7.08, helped by the huge success of its hit series “Squid Game,” according to LSEG data cited by Reuters.

    The company also raised its full-year revenue forecast to between $44.8 billion and $45.2 billion, up from $44.5 billion previously.

    The improved outlook partly reflects a weaker U.S. dollar, which analysts at Vital Knowledge described as a “low-quality source.”

    Investing.com analyst Thomas Monteiro added the guidance “now feels quite conservative,” calling this “problematic for a stock priced for perfection.” Netflix’s shares have surged over 43% this year on expectations it will further solidify its streaming dominance.

    Michigan sentiment report on deck

    Investors are gearing up for the University of Michigan’s monthly consumer sentiment index, expected to show a slight rise in July with inflation expectations holding steady.

    “We’ll see whether 1-year inflation expectations have continued to drop: they are currently at 5%, though opinions diverge sharply between Democrat (very high) and Republican (very low) responders,” ING analysts said in a note.

    The report follows strong retail sales and lower-than-expected jobless claims this week, reinforcing signs of a resilient U.S. economy despite tariffs pushing some prices higher.

    Fed’s Waller supports rate cut

    Amid this backdrop, the Federal Reserve has mostly taken a wait-and-see stance on interest rates. However, Fed Governor Christopher Waller said Thursday that a rate cut at the central bank’s upcoming meeting is justified, citing growing economic risks.

    He noted the tariff-driven inflation rise is likely temporary, not a persistent problem.

    “It makes sense to cut” the policy rate by 0.25 percentage points at the Fed’s July 29-30 meeting, Waller said at an event.

    Waller’s remarks come as Fed Chair Jerome Powell faces increasing pressure from President Trump to quickly reduce borrowing costs. Powell, emphasizing the Fed’s independence, prefers a cautious approach to assess tariffs’ full impact.

    Bitcoin rises after U.S. House passes crypto bills

    Bitcoin briefly climbed above $120,000 in Asian trading Friday, on track for its fourth straight weekly gain after the U.S. House approved three bills to create a new regulatory framework for cryptocurrencies.

    As of 03:52 ET, Bitcoin was up 1.1% at $119,583.3.

    The cryptocurrency hit record highs above $123,000 earlier this week but profit-taking and concerns about the bills’ final passage capped gains.

    The “GENIUS Act,” passed by a bipartisan 308-122 vote, mandates stablecoin issuers maintain dollar-backed reserves with regular audits, and sets both federal and state oversight.

    Two other bills also passed: the CLARITY Act, which aims to clarify whether digital tokens fall under SEC or CFTC jurisdiction; and the Anti-CBDC Surveillance State Act, which prevents the Fed from issuing a central bank digital currency without Congress’s explicit approval.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Dollar Softens Slightly, But Maintains Weekly Strength on Resilient U.S. Data

    Dollar Softens Slightly, But Maintains Weekly Strength on Resilient U.S. Data

    The U.S. dollar edged lower during early trading on Friday but remained poised to secure its second straight weekly gain. A stream of upbeat economic indicators continued to reinforce the belief that the Federal Reserve will hold off on interest rate cuts for now.

    As of 04:15 ET (08:15 GMT), the Dollar Index—which tracks the greenback against six major currencies—was down 0.4% at 98.100. Still, it was on pace to finish the week up by approximately 0.7%, extending gains of nearly 1% from the prior week.

    Greenback Benefits From Strong Economic Signals

    Investor demand for the dollar has stayed firm, fueled by signs of ongoing economic strength in the U.S., which is bolstering the case for the Fed to maintain higher interest rates longer than initially anticipated.

    Fresh data on Thursday revealed that retail sales climbed more than forecast in June, while initial jobless claims dropped to their lowest level in three months—both highlighting resilience in the consumer sector.

    Earlier this week, figures showed consumer prices increased at their fastest pace in five months, raising the possibility that new tariffs may be contributing to a slight uptick in inflation.

    “One of our key calls this summer is that this return to dollar ‘functionality’ reduces the likelihood of new selloffs – unless Trump fires Fed Chair Jay Powell (as Wednesday’s brief dollar collapse showed) or escalates protectionism beyond markets’ current tolerance, particularly against China,” noted analysts at ING in a research note.

    “We don’t expect either, and still see some dollar support in the coming months as the 14bp priced into the Fed’s September contract unwinds,” they added.

    Market pricing currently reflects around 45 basis points of Fed rate cuts for the remainder of the year—slightly less than the 50 basis points priced in earlier this week.

    Friday’s economic docket includes U.S. housing data and the University of Michigan consumer sentiment surveys.

    Weak U.K. Growth Data Hits Pound, Euro Recovers

    The euro climbed 0.3% to 1.1623 against the dollar, bouncing back after hitting a three-week low of 1.1556 on Thursday. However, it was still facing a 0.6% decline for the week.

    German producer price data matched expectations, falling 1.3% year-over-year in June, while eurozone inflation held steady at 2.0%, consistent with the European Central Bank’s target.

    Despite subdued inflationary trends in Germany—the bloc’s largest economy—any monetary policy easing by the ECB could be complicated by President Donald Trump’s proposed 30% tariffs on EU imports.

    After its June policy meeting, the ECB signaled a likely hold on rates this month. However, ING suggested there’s still potential for surprises.

    “That said, the ECB meeting may prove less dull than expected,” said ING. “A cut is highly unlikely given recent communication, but tariff risks and a strong euro could revitalise a dovish front that otherwise seemed settled on a neutral pivot.”

    Meanwhile, GBP/USD edged up 0.2% to 1.3432 but was still on track for a 0.5% weekly drop. U.K. economic indicators—including a surprise uptick in the unemployment rate and a monthly contraction in GDP for May—have strengthened expectations for further rate cuts by the Bank of England.

    Yen Under Pressure from Political Concerns

    The dollar rose 0.1% to 148.63 yen, with the Japanese currency heading toward a 0.8% weekly decline. Markets reacted to signs that Japan’s ruling coalition may lose its parliamentary majority, which could give more power to opposition groups pushing for cuts to the consumption tax to ease the strain of inflation.

    Inflation data out Friday showed core CPI in Japan eased slightly in June but still remained above the Bank of Japan’s 2% goal.

    Aussie, Yuan Also Active

    In other currencies, the Australian dollar gained 0.5% to 0.6516, rebounding after falling to its lowest point in over three weeks following weaker-than-expected employment data, which heightened bets on a Reserve Bank of Australia rate cut.

    The Chinese yuan also saw minor movement, with USD/CNY dipping 0.1% to 7.1782.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Gold Prices Stall as Dollar Strengthens on Solid U.S. Data; Platinum Surges Past Resistance

    Gold Prices Stall as Dollar Strengthens on Solid U.S. Data; Platinum Surges Past Resistance

    Gold traded flat in Asian markets on Friday, weighed down by a stronger U.S. dollar and a rise in investor risk appetite following upbeat American retail sales figures. The precious metal was on track for a modest weekly decline, with growing confidence that the Federal Reserve will keep interest rates elevated dampening safe-haven demand.

    By 05:16 GMT, spot gold held steady at $3,339.61 per ounce, while September gold futures hovered around $3,344.62. Despite recent gains, the yellow metal was headed for a 0.5% drop on the week, snapping a two-week winning streak.

    Fed Outlook, Strong Retail Data Curb Safe-Haven Demand

    Robust U.S. economic data — particularly stronger-than-expected June retail sales — reinforced views that the Fed may hold off on rate cuts in the near term. This has buoyed the dollar, which climbed roughly 0.7% this week, marking its second consecutive weekly gain.

    Risk appetite also climbed on the back of positive corporate earnings, further sidelining demand for gold and other traditional hedges.

    Uncertainty around President Donald Trump’s trade tariff threats provided only limited support for gold, as markets largely brushed off the geopolitical risk in favor of riskier assets.

    Platinum Extends Rally, Outshines Peers

    While gold and silver remained under pressure, platinum emerged as the standout performer. Spot platinum surged to $1,465.43 per ounce, up 5.5% for the week, after breaking through the critical $1,400 resistance level. The metal is now trading at levels not seen in over 11 years.

    Analysts at ANZ said this breakout could signal further upside for platinum, supported by expectations of tightening supply and firming industrial demand.

    Platinum — along with silver — has significantly outperformed gold in 2025, as investors rotate into less expensive alternatives amid elevated bullion prices.

    Broader Metals Mixed Amid Dollar Strength

    Elsewhere in the metals space, spot silver slipped to $38.1225 per ounce, marking a 0.5% weekly decline, as dollar strength continued to weigh on prices.

    Copper prices were little changed this week. Benchmark contracts on the London Metal Exchange rose 0.3% to $9,706.50 per ton, while COMEX copper futures ticked up 0.6% to $5.5320 per pound, both showing sideways momentum.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.
  • Oil Prices Steady After Iraq Field Strikes, But Weekly Losses Loom

    Oil Prices Steady After Iraq Field Strikes, But Weekly Losses Loom

    Oil prices remained largely flat in Asian trading on Friday, as the market digested recent supply concerns stemming from drone strikes in Iraq. The previous day’s gains, driven by fears of disruption in Iraqi Kurdistan, were not enough to reverse an overall bearish weekly trend.

    By 21:56 ET (01:56 GMT), September Brent crude hovered at $69.51 per barrel, while WTI crude held at $67.51, both unchanged from the prior session. On Thursday, prices had climbed more than 1.5% but were still tracking losses of over 1% for the week.

    Geopolitical Tensions Fuel Supply Risks

    Thursday’s rally was underpinned by fresh attacks on oil installations in Iraqi Kurdistan, which temporarily knocked out nearly half of the region’s production. The strikes, allegedly carried out by Iran-aligned militias, renewed concerns over Middle Eastern output security.

    Despite the unrest, Baghdad announced a tentative agreement to restart crude exports from Kurdistan to Turkey after a two-year pause. While the Kurdistan Regional Government has yet to formally confirm the arrangement, the move points to progress in negotiations between federal and regional authorities.

    U.S. Policy Shift Weighs on Market Outlook

    Earlier support for oil prices from the possibility of new U.S. sanctions on Russia faded after President Donald Trump opted to give Moscow a 50-day window to wind down the war in Ukraine. The softer stance defused expectations of imminent restrictions, which had helped push prices higher last week.

    Inventory Draw Signals Tight Supply

    Fresh data from the U.S. Energy Information Administration showed a surprise inventory draw of 3.9 million barrels, far exceeding the 1.8 million-barrel drop forecast by analysts. The report reinforced views that underlying market conditions remain tight.

    In addition, the International Energy Agency (IEA) recently noted that supply-demand dynamics could be tighter than headline figures suggest, as global refinery activity picks up to meet summer fuel demand.

    Despite a recent increase in production quotas from OPEC+, both the IEA and OPEC continue to project stable demand growth through 2025 and 2026, pointing to a cautiously optimistic outlook for crude markets.

    This content is for informational purposes only and does not constitute financial, investment, or other professional advice. It should not be considered a recommendation to buy or sell any securities or financial instruments. All investments involve risk, including the potential loss of principal. Past performance is not indicative of future results. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions.