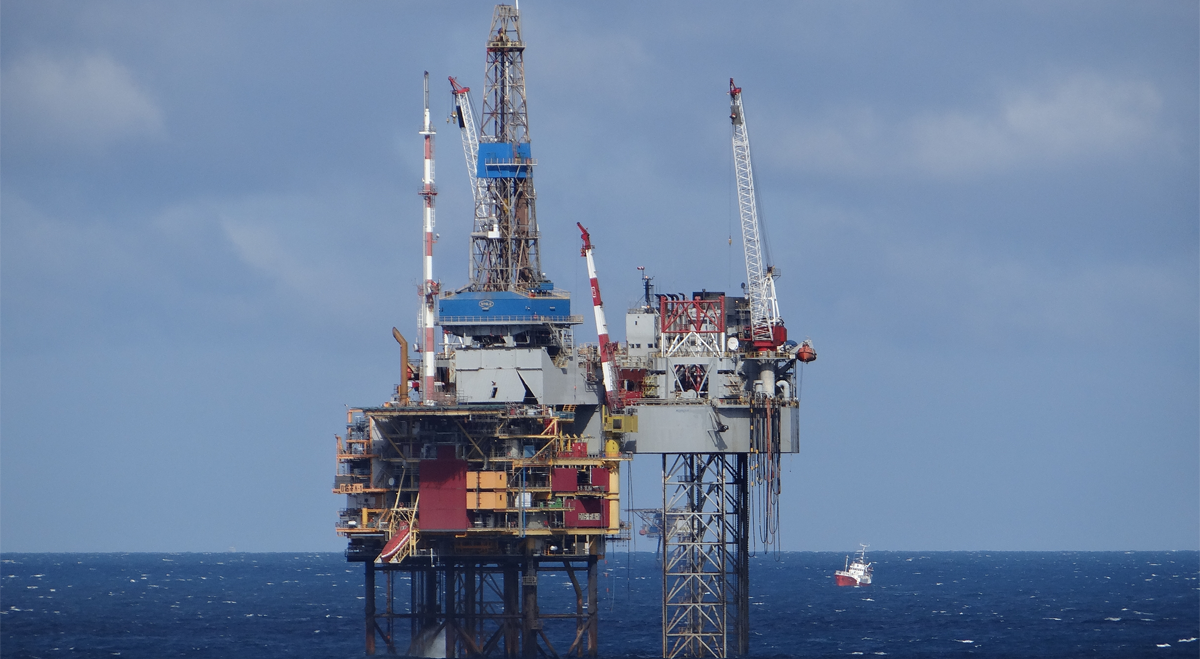
Serica Energy plc (LSE:SQZ) reported a 44% year-on-year increase in average production to 37,100 barrels of oil equivalent per day (boepd) for the nine months ended 30 September 2026, while revenue more than doubled to $905 million.
The UK North Sea oil and gas producer maintained its post-tax cash flow guidance of $450 million to $475 million, despite extended maintenance work at the Triton floating production, storage and offloading (FPSO) vessel.
Current production is approximately 40,000 boepd, with Serica expecting output to increase to around 65,000 boepd once Triton returns to operation.
The company reported net debt of $73 million and total liquidity of $685 million, while progressing drilling programmes across its existing portfolio and evaluating potential acquisitions.
Serica is also preparing to transfer its listing from AIM to the London Stock Exchange’s Main Market.
Nine-Month Production Rises 44% to 37,100 Boepd
Serica reported average production of 37,100 boepd during the first nine months of 2026, an increase of 44% compared with the corresponding period of 2025.
The company operates oil and gas assets across the UK Continental Shelf, including the Bruce, Keith and Rhum fields in the Northern North Sea and interests connected to the Triton FPSO in the Central North Sea.
Production during the period was affected by an extended maintenance programme at Triton, which has delayed the return of associated output.
Serica said current production is approximately 40,000 boepd and expects this to increase to around 65,000 boepd following the return of Triton.
The anticipated increase remains dependent on the completion of maintenance activities and the resumption of production from the affected fields.
The company also holds operated and non-operated interests in other North Sea assets, including a developing position in the Southern North Sea gas basin.
Revenue More Than Doubles to $905 Million
Serica reported revenue of $905 million for the nine months to September, more than double the amount recorded in the corresponding period of the previous year.
The increase accompanied higher average production across the group’s portfolio.
The company maintained its post-tax cash flow guidance of $450 million to $475 million for 2026.
At the reporting date, Serica recorded net debt of $73 million and total liquidity of $685 million.
The company said its financial position reflected its approach to capital expenditure and shareholder distributions, including dividend payments.
The reported liquidity provides financial resources for ongoing operations and planned investment activities, although future cash generation will remain dependent on production levels, commodity prices and expenditure.
Drilling Programme Targets Existing North Sea Assets
Serica is progressing an organic development programme across its operated and non-operated interests.
The programme includes a multi-well drilling campaign at the Bruce field and other production hubs.
The company is also planning infill drilling at several non-operated fields, targeting additional production from existing reservoirs and infrastructure.
Alongside these activities, Serica is advancing the Skerryvore exploration well.
The planned drilling operations are intended to evaluate additional resources and support future production from the group’s UK Continental Shelf portfolio.
The scale and timing of any resulting production increases will depend on drilling outcomes, development decisions and operational performance.
Tornado Gas Processing Discussions Continue
Serica is holding discussions concerning the potential processing of gas from the Tornado field through the Shetland Gas Plant.
The proposed arrangement would involve using existing processing infrastructure to handle production from Tornado.
The company said the potential agreement could contribute to extending the operational life of the Shetland Gas Plant.
Discussions remain ongoing, and no completed processing agreement has been announced in the supplied update.
Any future arrangement would depend on the outcome of negotiations and the relevant technical and commercial requirements.
North Sea and International Acquisitions Under Review
In addition to its drilling and development programme, Serica is evaluating potential merger and acquisition opportunities.
The company is reviewing assets in the North Sea and international markets as part of its wider growth strategy.
Serica’s existing portfolio comprises a combination of operated and non-operated oil and gas interests, with production distributed across several UK offshore regions.
The company has not announced a specific new acquisition or binding transaction arising from its current screening activities.
Any future investments would be subject to the relevant commercial assessments and transaction conditions.
Main Market Transfer Could Support FTSE 250 Eligibility
Serica is preparing to transfer its stock market listing from AIM to the Main Market of the London Stock Exchange.
The proposed move forms part of the company’s plans to broaden access to institutional investors and increase its visibility in the public equity market.
A Main Market listing could also make Serica eligible for consideration for inclusion in the FTSE 250 index, subject to the applicable index requirements.
Index inclusion would not be automatic following the transfer.
The company has not provided a confirmed date for completion of the proposed listing change in the supplied update.
Full-Year Cash Flow Guidance Maintained
Serica maintained its 2026 post-tax cash flow guidance of $450 million to $475 million following the nine-month operational and financial update.
The company expects production to increase from approximately 40,000 boepd to around 65,000 boepd once the Triton FPSO returns to operation.
Its development priorities include the Bruce drilling programme, infill wells across non-operated assets, the Skerryvore exploration well and discussions concerning Tornado gas processing.
Serica is also continuing its review of potential acquisitions while preparing for the proposed Main Market listing.
The group enters the final quarter of 2026 with nine-month revenue of $905 million, average production of 37,100 boepd, net debt of $73 million and total liquidity of $685 million.
Leave a Reply