Author: Fiona Craig

  • Goldman Sachs Warns of Rising Concentration Risk and Recommends Five Portfolio Strategies

    Goldman Sachs Warns of Rising Concentration Risk and Recommends Five Portfolio Strategies

    AI-Led Rally Has Increased Market Concentration

    Goldman Sachs believes investors should begin preparing for greater portfolio diversification after years of strong equity performance pushed global allocations heavily toward U.S. stocks and the technology sector.

    The investment bank said portfolios have become increasingly exposed to a narrow group of assets, raising the potential impact of any reversal in market leadership.

    Technology Profitability Could Become a Risk

    Christian Mueller-Glissmann said the post-2022 recovery has been dominated by U.S. equities and artificial intelligence, fundamentally reshaping the global “World Portfolio.”

    He warned that “the current AI capex boom increases the risk that falling profitability for mega-cap Tech stocks materially drags on equity returns before benefits from AI adoption show up.”

    Goldman also highlighted inflation volatility and fiscal uncertainty as additional challenges, saying they are “creating headwinds for balanced portfolios, with less of a buffer from bonds and more risk of rate shocks.”

    Long-Term Returns May Moderate

    According to the bank’s macroeconomic forecasts, long-term equity returns appear likely to remain below historical norms under most economic scenarios.

    Only a highly favourable combination of resilient growth and an extended AI investment cycle would produce returns above long-term averages.

    Momentum Still Favours Equities

    Even so, Goldman cautioned investors against exiting the market too early.

    The bank noted that equities “deliver some of their strongest returns in the final years of a bull market, often led by the sector that outperformed in the preceding years.”

    Goldman’s Five Portfolio Ideas

    To remain invested while improving resilience, Goldman recommends:

    • Investing selectively in real assets.
    • Diversifying across investment styles and factors.
    • Increasing regional diversification.
    • Using long-dated call options where appropriate.
    • Adding alternative investments with low correlation to traditional portfolios.
  • IEA says China’s rare earth restrictions could disrupt trillions of dollars in global industry

    IEA says China’s rare earth restrictions could disrupt trillions of dollars in global industry

    The International Energy Agency has cautioned that China’s proposed export controls on rare earth minerals could have far-reaching consequences for global manufacturing, with as much as US$6.5 trillion in production outside China potentially exposed to supply chain disruption.

    Although Beijing postponed full implementation of the restrictions by one year, the agency warned that the concentration of critical mineral production continues to present a major strategic risk.

    Supply chains remain heavily concentrated

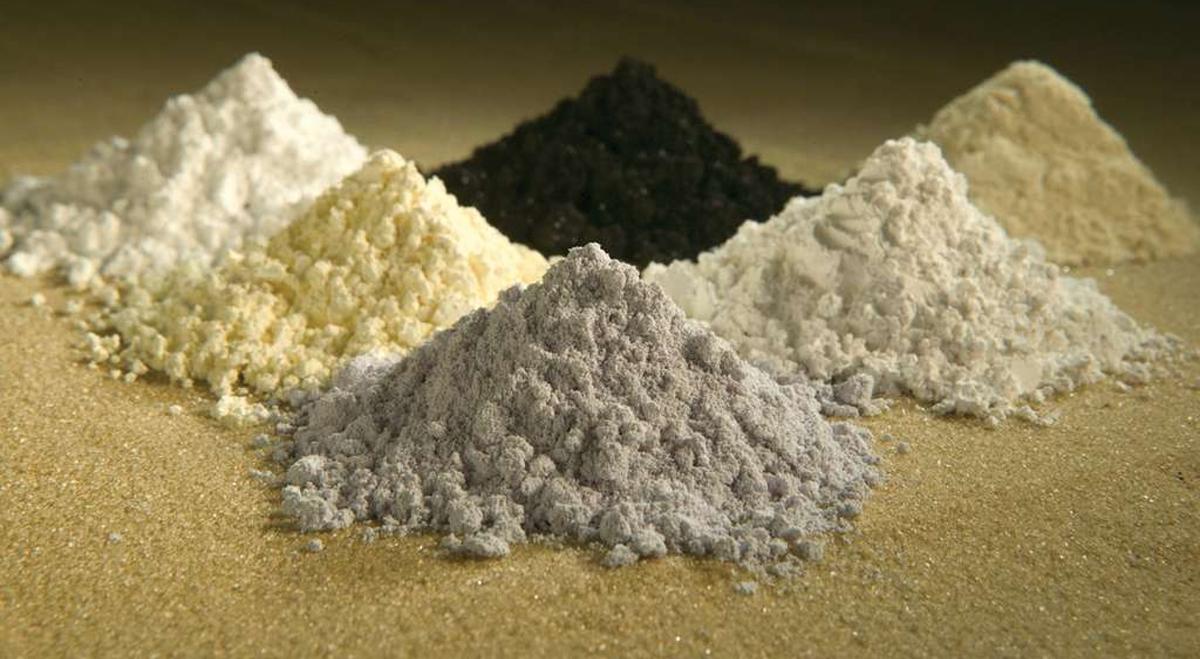
    Rare earth elements play a vital role in modern manufacturing despite being used in relatively small quantities. They are essential components in electric vehicles, aerospace equipment, defence systems, electronics and renewable energy technologies.

    The IEA’s latest Global Critical Minerals Outlook estimates that a full rollout of China’s export controls could affect around US$6.5 trillion of downstream manufacturing activity, with the United States and Europe facing nearly half of the potential economic impact.

    “Our latest analysis shows that vast amounts of economic value depend on relatively small volumes of critical minerals, whose supply chains remain highly concentrated and are therefore vulnerable,” said IEA Executive Director Fatih Birol.

    Graphite controls could add to supply pressures

    The agency also highlighted proposed Chinese restrictions on graphite exports, another critical material used in electric vehicle batteries.

    If implemented, the graphite measures could place an estimated US$300 billion of industrial production outside China at risk. China currently accounts for more than 90% of global processed graphite production.

    Investment in alternative sources increases

    Western governments have responded by expanding investment in domestic and allied critical mineral supply chains.

    According to the IEA, public funding commitments for new mining and refining projects climbed to US$65 billion between 2023 and 2025.

    The report also noted that new refining facilities in the United States and Malaysia have already reduced China’s share of global rare earth refining from 90% in 2023 to 85% last year. If planned investments move ahead, that share could decline to around 70% by 2035.

  • Eurozone inflation slows to 2.8% in June as price pressures continue to ease

    Eurozone inflation slows to 2.8% in June as price pressures continue to ease

    Annual inflation across the Eurozone declined to 2.8% in June from 3.2% in May, according to final figures released by Eurostat on Friday.

    The reading confirmed the preliminary estimate published earlier this month and came in below economists’ expectations of 3.0%. On a monthly basis, consumer prices in the 21-country single currency bloc fell by 0.1%, matching the initial estimate.

    Lower energy and food prices weigh on inflation

    The latest data mean headline inflation averaged 3.0% during the second quarter, below the European Central Bank’s projection of 3.2%.

    Economists at Capital Economics said the moderation was driven in part by lower fuel prices during June, which reduced energy inflation. They also noted that food inflation continued to soften.

    Core inflation also eased to 2.4%, reversing the increase recorded in May that had been driven by higher prices for tourism-related services. The June reading returned to the level last seen in February.

    According to Capital Economics, airlines may have absorbed much of the increase in jet fuel costs caused by oil supply disruptions linked to the conflict involving Iran, limiting the impact on consumer prices.

    ECB continues to monitor inflation risks

    While energy prices eased during June following a fragile ceasefire between the United States and Iran, the recent resumption of military exchanges has once again pushed crude oil prices higher, raising concerns that inflationary pressures could strengthen again.

    The European Central Bank raised interest rates last month in an effort to contain inflation, warning that the conflict in the Middle East could generate additional upward pressure on prices.

    Excluding energy and unprocessed food, harmonised consumer price inflation across the Eurozone stood at 2.1% year-on-year and increased 0.2% compared with the previous month.

  • Gold rebounds from selloff but remains headed for steep weekly decline

    Gold rebounds from selloff but remains headed for steep weekly decline

    Gold prices posted modest gains on Friday as investors stepped in to buy after the previous session’s heavy losses. Even with the recovery, bullion remained on course for its sharpest weekly drop since early June as geopolitical tensions and inflation concerns continued to favour the U.S. dollar.

    At 03:12 ET (07:12 GMT), spot gold (XAU/USD) advanced 0.47% to $3,995.35 an ounce, while Gold Futures rose 0.18% to $3,999.22. Silver (XAG/USD) slipped 0.18% to $55.43 an ounce and platinum (XPT/USD) fell 2% to $1,589.57.

    Inflation concerns continue to weigh on gold

    Despite Friday’s rebound, gold remained about 3% lower for the week as investors continued shifting towards yield-generating assets and the U.S. dollar.

    The latest decline followed renewed U.S. military strikes on Iranian targets after an attack on an oil tanker near Iran’s principal export terminal. The prolonged conflict has kept oil prices elevated, increasing concerns that higher energy costs could slow progress in bringing inflation under control.

    Persistent inflation could encourage the Federal Reserve to keep interest rates elevated for longer, supporting Treasury yields while reducing the attractiveness of gold, which does not generate income.

    Although recent U.S. inflation reports showed softer consumer and producer prices, investors remain cautious that rising oil prices could reverse the recent improvement.

    Federal Reserve officials remain cautious

    Federal Reserve policymakers continue to stress that inflation remains above target despite encouraging economic data.

    Tony Sycamore, Senior Market Analyst at IG, said the weak reaction following softer U.S. CPI and PPI data was “not a particularly encouraging sign” for gold.

    He added: “The overnight decline now brings a stern test to the view that gold has formed a base around the late-June low of $3,942.”

    According to Sycamore, a fall below that support could expose the October 2025 low near $3,886, while a move above resistance around $4,140 would strengthen the technical outlook.

    “For now, the metal starts the day in a delicate spot, feeling the weight of a stronger dollar and risk aversion flows,” he added.

    Gold has remained close to the key $4,000-an-ounce level as Federal Reserve officials continue to signal that inflation is still too high to justify lowering interest rates. Markets remain focused on incoming economic data and energy prices for clues about the future direction of monetary policy.

  • Oil set for strong weekly gains despite muted trading as Middle East risks persist

    Oil set for strong weekly gains despite muted trading as Middle East risks persist

    Oil prices posted modest gains on Friday, with both Brent and West Texas Intermediate on course for their strongest weekly advance in months as geopolitical tensions between the United States and Iran continued to support the market.

    At 04:10 ET (08:10 GMT), Brent crude futures were up 0.2% at $84.38 a barrel, while U.S. West Texas Intermediate (WTI) crude added 0.6% to $78.71 a barrel.

    Although price movements were relatively limited during Friday’s session, both benchmarks remained on track to gain more than 10% for the week after the latest military escalation injected a significant geopolitical premium into crude markets.

    Tamas Varga, an analyst at PVM Oil Associates, said “there is a lack of urgency in oil circles at present.”

    He added: “There have been some quite significant developments without which the experience of the last few months would have crude prices harrying triple digits.”

    Iran’s armed forces announced new strikes against U.S. military facilities across the Middle East early Friday, including what officials described as the country’s first direct attack on Syria.

    The latest retaliation followed a sixth straight night of U.S. military operations targeting Iranian military infrastructure.

    Concerns remain centred on the Strait of Hormuz, the strategic shipping route that carries roughly 20% of global oil supplies. Shipping traffic has slowed again following the renewed U.S. naval blockade of Iranian ports.

    Market participants continue to assess whether supply interruptions could become prolonged or whether increased production elsewhere would help offset any disruptions.

    Diplomatic initiatives remain active, with reports indicating that Qatar, Egypt and Pakistan are still attempting to revive negotiations despite the apparent collapse of June’s ceasefire agreement.

    Meanwhile, recent U.S. inventory figures continued to support prices.

    The Energy Information Administration (EIA) reported a decline of 1.7 million barrels in crude inventories during the week ended July 10, bringing total stockpiles to 409.7 million barrels. Gasoline inventories also fell by 1.5 million barrels.

    Earlier data from the American Petroleum Institute (API) showed a draw of around 564,000 barrels in crude inventories over the same period, below analysts’ forecasts.

  • U.S. futures decline as Netflix outlook disappoints and geopolitical risks mount: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. futures decline as Netflix outlook disappoints and geopolitical risks mount: Dow Jones, S&P, Nasdaq, Wall Street

    U.S. equity futures traded lower on Friday as investors balanced weaker-than-expected guidance from Netflix (NASDAQ:NFLX), renewed concerns over artificial intelligence spending and escalating tensions between the United States and Iran.

    At 02:57 ET (06:57 GMT), Dow Jones futures were down 336 points, or 0.6%, while S&P 500 futures lost 66 points, or 0.9%. Nasdaq 100 futures led the declines, falling 488 points, or 1.7%.

    Wall Street ended Thursday’s session in negative territory, with the Dow Jones Industrial Average slipping 0.2%, the S&P 500 falling 0.5% and the Nasdaq Composite retreating 1.47%.

    Market attention remained firmly focused on the technology sector. Analysts at Vital Knowledge said investors continue to question the sustainability of heavy AI investment and the financial returns expected from the industry’s rapid expansion.

    Vital Knowledge analysts wrote: “[T]he list of things worrying people will sound familiar to anyone following the space: the absence of free cash flow for hyperscalers/neoclouds, costs that seem to scale higher with revenue, the reliance on capital markets […] to fund capex […], the huge pipeline of debt/equity supply that’s washing over markets, the increasingly poor financial/fundamental prospects for bleeding edge frontier labs […], and questions about data center overcapacity.”

    Netflix guidance disappoints investors

    Netflix (NASDAQ:NFLX) fell more than 8% in extended trading after issuing third-quarter guidance that failed to meet market expectations.

    The streaming company forecast earnings per share of $0.82, below analysts’ consensus of $0.84, while expected revenue of $12.86 billion also missed estimates of $13.0 billion.

    Despite the softer guidance, Netflix told investors that its business “remains solid” and said it is “on track to meet our objectives for the year.”

    The company also confirmed that, beginning in January 2027, viewing-hours data will be published annually instead of twice each year, continuing its strategy of placing greater emphasis on financial performance rather than engagement metrics.

    Earnings season continues

    Investors are also preparing for fresh quarterly updates from The Travelers Companies (NYSE:TRV), Truist Financial Corporation (NYSE:TFC), Fifth Third Bancorp (NASDAQ:FITB) and Regions Financial Corporation (NYSE:RF).

    According to Vital Knowledge, management commentary across corporate America has remained broadly constructive despite concerns surrounding AI spending, energy markets and geopolitical uncertainty.

    Recent U.S. economic data have also remained supportive, with resilient retail sales, lower jobless claims, stronger regional manufacturing activity and softer-than-expected inflation readings.

    Oil rises as conflict escalates

    Military exchanges between the United States and Iran continued for a sixth consecutive day, with both sides launching new strikes.

    U.S. Central Command said its latest operations were designed to weaken Iranian military capabilities while “holding Iran accountable” for attacks on commercial shipping.

    Iranian media reported damage to civilian infrastructure, including bridges and a railway station, while renewed uncertainty surrounding shipping through the Strait of Hormuz supported oil prices.

    Brent crude gained 0.7% to $84.81 per barrel, while West Texas Intermediate rose 1.0% to $79.76.

    SpaceX postpones Starship test

    SpaceX (NASDAQ:SPCX) delayed the launch of its Starship rocket after several engines failed to ignite properly during the countdown in Texas.

    Chief Executive Elon Musk suggested another launch attempt could take place next week. Shares fell more than 4% in after-hours trading following the announcement.

  • Market Open: Burberry Q1 Sales Growth, Wise Q1 FY27 Growth

    Market Open: Burberry Q1 Sales Growth, Wise Q1 FY27 Growth

    Markets opened cautiously as Middle East tensions weighed on sentiment. Burberry and Wise reported strong updates while Brent crude moved higher.

    Market Overview

    The FTSE 100 opened broadly unchanged at 10,572.39, while the Euronext 100 slipped 0.14 per cent and Germany’s DAX fell 0.53 per cent at the open. Overnight, the Nasdaq closed lower at 25,881.95 and the S&P 500 finished at 7,533.77, with both US benchmarks declining as investors reacted to renewed US-Iran tensions. Market sentiment remained cautious amid geopolitical uncertainty, although stronger corporate earnings helped limit losses across European markets.

    Macro sentiment was shaped by firmer energy prices as Brent crude advanced on escalating Middle East tensions and concerns over potential disruption to Red Sea shipping. Gold edged higher on safe-haven demand, copper weakened, and natural gas eased slightly. Against sterling, the US dollar, Swiss franc and euro strengthened marginally, while the Japanese yen and Australian dollar were little changed. Bitcoin was down.


    Market Numbers

    FTSE 100: Up (0.001%), 10,572.39

    Euronext 100: Down (-0.14%), 1,917.90

    DAX: Down (-0.53%), 24,783.56

    NASDAQ: Down, 25,881.95

    S&P 500: Down, 7,533.77


    In the Headlines

    Luxury Retail – Burberry Group (LSE:BRBY)

    Burberry reported a 5 per cent rise in first-quarter comparable sales as strong demand in the Americas and China offset weaker trading across Europe. The update suggests the group’s turnaround efforts are gaining traction despite uneven regional consumer spending.

    Fintech Growth – Wise plc (LSE:WSE)

    Wise delivered strong first-quarter FY27 growth as customer numbers and cross-border payment volumes continued to increase. The performance highlights ongoing demand for low-cost international money transfers and supports confidence in the company’s long-term growth strategy.


    Currencies (vs GBP)

    USD: Up (0.03%), $1.3478

    CHF: Up (0.02%), Fr.1.0897

    EUR: Up (0.02%), €1.1776

    JPY: Up (0.01%), ¥218.8535

    AUD: Unchanged (0.00%), $1.9253

    Bitcoin (BTC/GBP): Down, £46,662.10


    Commodities

    Copper: Down

    Gold: Up

    Brent Crude: Up

    Natural Gas: Down

  • European shares retreat as Middle East tensions offset strong earnings momentum: DAX, CAC, FTSE100

    European shares retreat as Middle East tensions offset strong earnings momentum: DAX, CAC, FTSE100

    European equity markets moved lower on Friday as renewed military escalation in the Middle East lifted oil prices and revived inflation concerns. Even so, a solid start to the second-quarter earnings season helped limit losses, leaving major indexes on course to finish the week in positive territory.

    The pan-European STOXX 600 slipped 0.6% during early trading but was still on track for a weekly advance of around 0.4%. Strong corporate results, particularly from leading banking groups, have supported investor sentiment throughout the week and helped cushion the broader market.

    Investor confidence was challenged after the United States and Iran exchanged military strikes for a sixth consecutive day. The latest escalation pushed crude oil prices sharply higher, fuelling concerns that sustained energy inflation could slow the global disinflation process and complicate future monetary policy decisions by major central banks.

    Despite the geopolitical backdrop, European markets proved more resilient than their Asian counterparts, where technology stocks led a much steeper sell-off overnight. Europe’s comparatively smaller exposure to mega-cap technology companies helped limit the downside.

    Within the semiconductor sector, STMicroelectronics (BIT:STMMI) declined 5%, while ASML (EU:ASML) fell 3.5%.

    Investors continued to focus on encouraging corporate earnings and signs of easing inflation in the United States earlier this week, both of which helped reduce immediate concerns over higher global interest rates despite the worsening geopolitical environment.

    Attention is now turning to next week’s European Central Bank policy meeting.

    Most economists expect the ECB to leave its benchmark deposit rate unchanged. However, the recent jump in oil prices has led money markets to increase expectations that interest rates could move higher later if inflationary pressures persist.

    The central bank is expected to balance weakening economic growth across the eurozone against the risk that higher energy costs could generate fresh inflationary pressures.

    Across Europe’s major markets, London’s FTSE 100 fell 0.3% but remained on course for a weekly gain, supported by banking shares. France’s CAC 40 declined 0.6%, Germany’s DAX eased 0.5%, while Italy’s FTSE MIB lost 1% and Spain’s IBEX 35 slipped 0.3% as investors reduced exposure to risk assets.

    Among individual companies, Danske Bank (TG:DSN) declined 2.5% following the release of its latest quarterly results.

  • FTSE 100 slips as renewed U.S.-Iran conflict dampens market sentiment

    FTSE 100 slips as renewed U.S.-Iran conflict dampens market sentiment

    London equities came under pressure on Friday after giving up early gains, as a sixth consecutive night of U.S. military strikes on Iran weighed on global risk appetite. The cautious mood followed broad declines across Asian markets, prompting investors to move away from risk assets.

    At 03:17 ET (07:17 GMT), the FTSE 100 was 0.05% higher, although gains proved fragile. Germany’s DAX declined 0.42%, while France’s CAC 40 fell 0.53%. Sterling eased 0.03% against the U.S. dollar to $1.3472.

    Asian markets endured a sharp sell-off led by Japan, where the Nikkei 225 dropped 3.96% and the TOPIX lost 2.72%. Semiconductor shares came under pressure despite a positive long-term outlook from TSMC.

    In Taiwan, TSMC recovered from earlier losses to close 1.23% higher as investors assessed the company’s increased capital expenditure guidance alongside broader concerns over artificial intelligence spending.

    Chinese equities also weakened. The Shanghai Composite declined 3.05%, the CSI 300 fell 3.60%, and Hong Kong’s Hang Seng Index closed 2.1% lower.

    Geopolitical tensions intensified after U.S. Central Command confirmed it had completed a sixth straight night of strikes against Iran. CENTCOM said fighter aircraft, drones and warships targeted “dozens” of military sites, adding that more than 50,000 U.S. personnel are now deployed across the region.

    The latest military action follows the collapse of a 14-point memorandum of understanding agreed in June.

    Iranian state media reported that overnight strikes hit an airport, railway station and bridges in Hormozgan province near Bandar Abbas. Casualty reports varied, with state television initially reporting three deaths and nine injuries before other state outlets later revised the death toll to “at least seven” while maintaining that nine people were wounded.

    Iran responded by targeting U.S. military infrastructure in Kuwait, Bahrain and Qatar. Kuwait’s military said it was “confronting attacks by hostile drones” from Iran, although no confirmed damage to U.S. facilities was reported.

    Speaking on Thursday, U.S. President Donald Trump said the United States was “winning big” in Iran and that Americans would see “the fruits” of the campaign “very, very shortly,” although he did not provide further details during his televised address on election security.

    Earlier in the day, White House press secretary Karoline Leavitt said Iran “very much continues to talk” with Washington despite the ongoing strikes, which she said were carried out in response to Iran attacking commercial vessels in breach of the June agreement.

    Commodity markets reflected the heightened geopolitical uncertainty. Brent crude rose 0.33% to $84.50 a barrel, while U.S. West Texas Intermediate crude gained 0.73% to $79.52. Spot gold advanced 0.56% to $3,998.72 an ounce, with gold futures adding 0.26% to $4,002.32.

    UK market round-up

    Wise (LSE:WSE) reported a 25% increase in first-quarter net revenue, supported by continued growth in cross-border payment volumes and customer balances. The fintech group also reaffirmed its guidance for the full financial year.

    Burberry (LSE:BRBY) posted 5% growth in first-quarter comparable store sales, matching market expectations as robust demand in the United States offset weaker consumer spending across Europe and the Middle East amid ongoing regional tensions.

  • Burberry releases Q1 FY27 trading update and holds investor webcast (BRBY)

    Burberry releases Q1 FY27 trading update and holds investor webcast (BRBY)

    Burberry Group PLC (LSE:BRBY) has published its trading update for the first quarter of the 2027 financial year, providing investors with the latest overview of trading performance at the British luxury fashion group.

    The update has been released through the London Stock Exchange’s regulatory disclosure service and is also available in the Results, Reports and Presentations section of Burberry’s corporate website.

    To accompany the announcement, the company is hosting a virtual presentation for investors and analysts at 9:00 a.m. UK time. The webcast is being streamed live through Burberry’s website, with presentation slides available during the event and an indexed replay scheduled to be published afterwards.

    The presentation forms part of Burberry’s ongoing investor relations programme, providing shareholders and analysts with an opportunity to review the company’s latest financial and operational performance while maintaining transparency around its strategic progress.

    Burberry’s broader outlook remains mixed. While recent profitability has come under pressure and leverage has increased, the business continues to benefit from resilient cash generation, and management has expressed greater confidence in performance during FY27. Technical indicators remain weak, with the shares trading below key moving averages, while the company’s valuation continues to appear demanding based on its elevated price-to-earnings ratio.

    More about Burberry

    Burberry Group PLC is a British luxury fashion house headquartered in London and is internationally recognised for its premium clothing, accessories and signature Burberry Check pattern. The company is listed on the London Stock Exchange as a constituent of the FTSE 100 and also has American depositary receipts (ADRs) trading in the United States.

    Its portfolio includes globally recognised trademarks such as the Burberry Check, the Equestrian Knight Device and the Thomas Burberry Monogram. Serving customers worldwide through a combination of retail stores, digital platforms and wholesale partnerships, Burberry remains one of the UK’s best-known luxury brands.