Author: Fiona Craig

  • Zotefoams Reports Strong Early 2026 Growth as International Expansion Balances Footwear Weakness (ZTF)

    Zotefoams Reports Strong Early 2026 Growth as International Expansion Balances Footwear Weakness (ZTF)

    Zotefoams (LSE:ZTF) reported a 26% increase in revenue to £64.1 million for the four months ended 30 April 2026, supported by strong demand across its key markets and the contribution from Overseas Konstellation Company (OKC). The growth helped offset an anticipated slowdown in the company’s Footwear division. Performance was broad-based geographically, with revenue in EMEA rising 24%, North American sales increasing 30% on an organic basis, and Asian revenue approximately doubling year-on-year.

    The company said the performance was supported by additional manufacturing capacity, operational efficiency improvements and strong cash generation. Integration of OKC is progressing in line with expectations, while major expansion projects in Vietnam and South Korea remain on schedule. Zotefoams is also continuing to invest in AI-driven productivity initiatives and has launched a new Global Approved Partners programme aimed at strengthening customer and supply-chain relationships.

    Despite ongoing macroeconomic uncertainty, instability in the Middle East and continued cost pressures, the board maintained its expectations for the full 2026 financial year. Current market forecasts indicate revenue of approximately £190.8 million and adjusted profit before tax of around £26.3 million, reflecting management confidence in the group’s long-term growth strategy and operational outlook.

    The company’s outlook is primarily supported by relatively attractive valuation metrics, including a low price-to-earnings ratio and a dividend yield of around 2%, alongside a stronger financial performance during 2025 and moderate leverage levels. However, these positives are partly offset by weaker technical indicators, with the shares trading below key moving averages and showing bearish momentum signals.

    More about Zotefoams

    Zotefoams plc (LSE:ZTF) is a global manufacturer of high-performance foam materials used across sectors including consumer products, lifestyle goods, transportation, smart technologies and industrial applications. The company serves international markets through its core EMEA operations and expanding presence in North America and Asia, including new facilities in Vietnam and a Footwear Innovation Centre in South Korea.
  • ImmuPharma Reduces Losses and Strengthens Funding Position as P140 Autoimmune Programme Progresses (IMM)

    ImmuPharma Reduces Losses and Strengthens Funding Position as P140 Autoimmune Programme Progresses (IMM)

    ImmuPharma (LSE:IMM) reported a reduced loss of £1.8 million for 2025, while maintaining broadly stable operating costs and ending the year with a cash balance of £1.4 million. The company subsequently strengthened its financial position through a £6.47 million equity fundraising completed in April 2026, providing additional support for the advancement of its development pipeline.

    During the year, ImmuPharma continued progressing its P140 autoimmune platform through the generation of new mechanistic data, alongside the filing of a patent covering both a companion diagnostic and precision treatment approach targeting Type M immune disorders. The company is also preparing the platform for late-stage clinical development and potential licensing discussions. Management said these developments could position P140 as a potential future standard of care across several autoimmune disease indications, while ongoing talks with prospective partners are aimed at securing a value-enhancing licensing agreement during 2026.

    ImmuPharma additionally advanced Kapiglucagon as a strategic metabolic disease asset by beginning IND-enabling studies and evaluating a potential 505(b)(2) regulatory pathway. The company also strengthened its leadership structure through internal scientific promotions and the appointment of a new independent non-executive director.

    The company’s outlook continues to be weighed down by weak financial fundamentals, including minimal revenue generation, ongoing losses, persistent cash burn and negative shareholder equity. Technical indicators are mixed but moderately supportive relative to the long-term 200-day moving average, while valuation remains constrained by the absence of earnings and dividend yield support.

    More about ImmuPharma

    ImmuPharma PLC (LSE:IMM) is a UK-listed biotechnology company focused on the discovery and development of peptide-based therapeutics targeting autoimmune and metabolic diseases. Its lead programme is the P140 autoimmune technology platform, while additional pipeline assets include Kapiglucagon for metabolic disease and Type 1 diabetes applications. The company’s strategy centres on precision medicine approaches and partnering opportunities with larger global pharmaceutical groups.

  • Watkin Jones Maintains Profitability Despite Lower Revenue as Diversification Strategy Expands Pipeline (WJG)

    Watkin Jones Maintains Profitability Despite Lower Revenue as Diversification Strategy Expands Pipeline (WJG)

    Watkin Jones (LSE:WJG), the UK developer specialising in residential-for-rent assets, reported interim revenue of £100.2 million for the six months ended 31 March 2026, compared with £129.2 million in the prior-year period, as weaker transactional activity continued to weigh on overall revenue performance. Despite the decline in turnover, the company maintained operating profit at £0.4 million, supported by strong construction execution, expansion of its Development Partnerships and Refresh operations, and disciplined cost and cash management. Adjusted net cash stood at £61.3 million at the period end.

    The group continued to progress its diversification strategy through two additional projects, including a purpose-built student accommodation scheme in Bristol and a hotel development in Wimbledon. Watkin Jones also secured planning approval for approximately 800 new residential units and increased its partnership-led development pipeline by 20%. Management highlighted a secured pipeline valued at £1.3 billion, including around £300 million of forward-sold revenue, and said a combination of forward-funded and partnership-backed schemes currently being marketed could support stronger trading in the second half of the financial year. The company believes its positioning leaves it well placed to benefit from resilient demand across the UK residential rental market despite broader macroeconomic pressures.

    Watkin Jones’ outlook remains challenged by declining revenues, weaker profitability and liquidity concerns, which continue to weigh on investor sentiment. Technical indicators also point to a bearish market trend, adding further pressure to the shares.

    More about Watkin Jones

    Watkin Jones (LSE:WJG) is a UK-based developer and manager of residential rental properties, specialising in purpose-built student accommodation, build-to-rent housing and affordable residential schemes. The group operates a capital-light development model for institutional investors and also owns Fresh, a property management platform overseeing more than 21,000 student beds and residential apartments across the UK.

  • Cohort Surpasses Expectations as Defence Order Book Reaches Record Level (CHRT)

    Cohort Surpasses Expectations as Defence Order Book Reaches Record Level (CHRT)

    Cohort (LSE:CHRT) reported stronger-than-expected results for the year ended 30 April 2026, with revenue increasing 12% to approximately £303 million and adjusted operating profit reaching around £36 million. Both figures came in ahead of market forecasts. The group’s net margin improved to 11.9%, while Cohort ended the financial year with net funds of £2.9 million following a significant recovery in cash generation during the second half. The company also secured a new £175 million five-year banking facility to support future growth.

    Performance was led by the Communications and Intelligence division, where revenue rose to £159 million and operating margins approached 20%, helped by a full-year contribution from EM Solutions. In contrast, the Sensors and Effectors division reported broadly flat revenue and lower margins, remaining below the group’s medium-term profitability targets. Order intake increased by roughly 10% to £313 million, lifting the total order book to a record £620 million. Management said the backlog now provides coverage for around 80% of expected revenue for the 2026/27 financial year, creating a strong platform for additional investment opportunities and potential acquisitions.

    The company’s outlook is primarily supported by strong financial performance, including healthy revenue growth and a conservatively leveraged balance sheet. Technical indicators also remain supportive, reflecting positive momentum and trend strength, although elevated RSI and stochastic readings suggest the shares may face some near-term volatility. Valuation metrics are less favourable due to the company’s relatively high price-to-earnings ratio and modest dividend yield.

    More about Cohort plc

    Cohort plc (LSE:CHRT) is an AIM-listed defence technology group headquartered in Reading, employing more than 1,600 people across the UK, Australia, Germany and Portugal. Through its Communications and Intelligence and Sensors and Effectors divisions, the company provides advanced communications systems, electronic warfare technologies, surveillance equipment, sonar systems and wider defence and security services to customers globally.

    Its Communications and Intelligence operations include EID, EM Solutions, MASS and MCL, which specialise in naval and military communications, satellite communications terminals, surveillance systems and data technologies. The Sensors and Effectors division comprises Chess Dynamics, ELAC SONAR and SEA, supplying surveillance and fire-control systems, underwater sonar technologies and broader defence solutions for both domestic and export markets.

  • Hollywood Bowl Increases Earnings and Shareholder Returns as UK and Canadian Expansion Continues (BOWL)

    Hollywood Bowl Increases Earnings and Shareholder Returns as UK and Canadian Expansion Continues (BOWL)

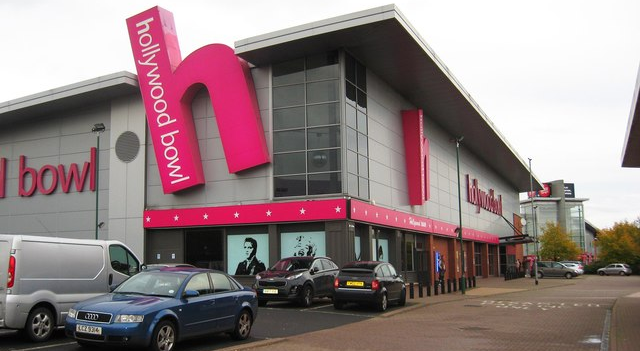
    Hollywood Bowl Group (LSE:BOWL) reported strong first-half results for the six months ended 31 March 2026, with revenue rising 9.5% to £141.5 million and adjusted EBITDA after rent increasing 8.9% to £42.2 million. Growth was supported by resilient consumer demand for affordable leisure activities and higher spend per game across the estate. Like-for-like sales increased 2.3% overall, including a 2.6% rise in the UK and modest growth in Canada despite weather-related disruption. The company said disciplined cost management helped offset labour and broader input cost pressures during the period.

    Adjusted profit before tax climbed 8.1% to £32.1 million, while net cash improved to £26 million. The stronger balance sheet supported a 10.2% increase in the interim dividend and the launch of a £5 million share buyback programme. Hollywood Bowl is continuing to accelerate its growth strategy through new site openings and refurbishments across both the UK and Canada. Management reiterated long-term targets of reaching 95 UK locations by 2035 and 35 Canadian centres by 2032, supported by initiatives including dynamic pricing, AI-driven marketing and a highly cash-generative operating model designed to support both expansion and shareholder returns.

    Hollywood Bowl’s outlook continues to be driven by strong financial performance and relatively attractive valuation metrics. Although some technical indicators point to potential short-term weakness, the group’s solid underlying fundamentals and appealing dividend yield continue to support a positive longer-term view.

    More about Hollywood Bowl

    Hollywood Bowl Group (LSE:BOWL) is the largest operator of ten-pin bowling centres in the UK and Canada, offering experience-led leisure activities including bowling, food and beverage services, and amusement attractions. The company focuses on family entertainment and social outings, targeting growth through investment in prime locations, venue refurbishments and expansion within two fragmented leisure markets.

  • Hardide Secures £2.4m North American Energy Contract and Upgrades FY26 Expectations (HDD)

    Hardide Secures £2.4m North American Energy Contract and Upgrades FY26 Expectations (HDD)

    Hardide (LSE:HDD) has won £2.4 million of new orders from a major customer operating in the North American energy sector, covering the remainder of the company’s financial year ending 30 September 2026. The contract value exceeds previous board expectations and has led management to improve its revenue and performance outlook for FY26.

    The majority of the work will be delivered through Hardide’s Martinsville facility in the United States, alongside production from its UK operations. The company said recent operational improvements have enhanced its ability to support higher demand, while pricing surcharges introduced to offset raw material cost inflation are also contributing to performance. Hardide added that gas supply arrangements have now been secured through the remainder of FY26 and into the first half of FY27, supporting operational continuity as it strengthens its relationship with the customer and develops a more structured order pipeline for the following financial year.

    The company’s outlook is primarily supported by improving financial performance, including a return to profitability and positive free cash flow generation, alongside constructive technical momentum with the share price trading above key moving averages. However, these positives are partly balanced by higher leverage levels, relatively thin operating margins and technically overbought trading conditions. Valuation remains supportive due to the company’s comparatively low price-to-earnings ratio.

    More about Hardide

    Hardide plc (LSE:HDD) is a UK-based specialist in advanced surface coating technology, developing and applying patented tungsten carbide and tungsten metal matrix coatings to engineering components. Its coatings are designed to extend component lifespan and improve performance in highly demanding environments. The company serves customers across sectors including energy, valve and pump manufacturing, industrial gas turbines, precision engineering and aerospace.

  • Nanoco Plans London Market Exit and Private Company Transition to Reduce Costs (NANO)

    Nanoco Plans London Market Exit and Private Company Transition to Reduce Costs (NANO)

    Nanoco Group (LSE:NANO) has announced plans to cancel the listing of its ordinary shares from the London Stock Exchange’s Main Market and re-register as a private limited company, subject to approval from at least 75% of shareholders at a general meeting scheduled for June. Management said the move is expected to generate annual cost savings of approximately £0.7 million, extending the company’s £10.1 million cash runway, supporting its path toward medium-term break-even and allowing greater focus on high-potential development projects.

    The board stated that maintaining a public listing has exposed the company to significant regulatory expenses, limited trading liquidity and elevated share price volatility. Nanoco also argued that UK equity markets continue to undervalue smaller early-stage technology businesses, particularly those with concentrated customer exposure. As a privately held company, management believes Nanoco will gain greater strategic flexibility, including increased freedom to explore potential future sale opportunities. However, shareholders will no longer have access to a formal public trading market and will instead rely on a matched bargain facility to facilitate limited off-market share transactions.

    The company’s outlook remains constrained by weak financial fundamentals, including ongoing losses, weak operating cash flow and negative shareholder equity. Technical indicators offer some support, with positive MACD momentum and the share price trading above key short-term moving averages, while valuation appears superficially inexpensive on a price-to-earnings basis. Nevertheless, these factors remain secondary to the company’s balance sheet and profitability challenges.

    More about Nanoco Group plc

    Nanoco Group plc (LSE:NANO) is a UK-based nanomaterials technology company specialising in cadmium-free quantum dots and related nanotechnology materials used in display, imaging and sensing applications. The company’s business model is centred on intellectual property development, licensing agreements and joint development partnerships with major Asian electronics and chemical companies, primarily at the pre-commercialisation stage.

  • Kendrick Highlights US$400m Teufelskuppe Valuation as Namibia Rare Earth Projects Advance (KEN)

    Kendrick Highlights US$400m Teufelskuppe Valuation as Namibia Rare Earth Projects Advance (KEN)

    Kendrick Resources (LSE:KEN) has completed an internal assessment of historic and recent exploration work across its flagship Teufelskuppe and Kieshöhe rare earth projects in southwest Namibia, where the company is earning a 70% interest through Bonya Exploration. The review produced an unaudited in-house net present value estimate of approximately US$400 million for the verified in-situ light rare earth oxide-bearing carbonatites at Teufelskuppe alone. The estimate is based on a current resource tonnage of 14 million tonnes at an average head grade of 3.12%, with evidence suggesting mineralisation continues at depth and could support a materially larger resource base.

    Management said high-grade zones containing up to 4.5% total rare earth oxides are concentrated within the central area of the Teufelskuppe project. The company also noted that neodymium and praseodymium — two key magnet rare earth elements — account for around 70% of the project’s light rare earth economic value. Kendrick believes this positions the asset favourably within a global market expected to expand significantly by 2034 and still heavily dominated by Chinese supply chains.

    Supported by recent fundraising activity, the company is advancing a Tier 1 “mine to magnet” strategy focused on accelerating development of the projects. Kendrick aims to deliver a maiden resource estimate by the end of the third quarter of 2026 while also finalising an optimised metallurgical flowsheet. Management said the programme is designed to reduce project risk and improve the assets’ attractiveness to downstream rare earth industry participants and potential investors.

    The company’s outlook remains constrained by very weak financial fundamentals, including the absence of revenue, ongoing losses, negative cash flow and a significantly weakened balance sheet with negative equity. However, technical indicators remain strongly positive and continue to support market sentiment. Valuation metrics remain difficult to assess given negative earnings and the lack of dividend support.

    More about Kendrick Resources PLC

    Kendrick Resources Plc (LSE:KEN) is a mineral exploration and development company focused on identifying and advancing resource projects through exploration, technical evaluation and resource development activities. The company aims to move projects toward production through joint ventures, strategic partnerships or asset sales. Kendrick has increasingly concentrated its portfolio on critical minerals opportunities in southern Africa, particularly the Bonya rare earth project in Namibia and the Blue Fox licence area in northwest Zambia.

  • Arrow Exploration Delivers Higher Q1 Profit, Cash Flow and Production Following Colombian Growth and Icaco Discovery (AXL)

    Arrow Exploration Delivers Higher Q1 Profit, Cash Flow and Production Following Colombian Growth and Icaco Discovery (AXL)

    Arrow Exploration (LSE:AXL) reported strong first-quarter 2026 financial and operational results, with average production increasing 15% year-on-year to 4,715 barrels of oil equivalent per day. Growth was primarily driven by new production from the Mateguafa Attic field within the company’s Tapir block in Colombia. Revenue rose 21% to US$23.5 million, while adjusted EBITDA climbed 22% to US$14.1 million. Net income almost doubled to US$5.2 million, supported by stronger realised oil prices and improved corporate operating netbacks of US$41.05 per boe.

    The company also highlighted a cash balance of US$24 million as of 1 May 2026, which management said provides sufficient flexibility to fund its ongoing drilling programme through internally generated cash flow while continuing planned capital investment. Following the end of the quarter, Arrow announced an oil discovery at its Icaco-1 exploration well, commenced drilling at the Icaco-2 appraisal well and advanced additional development drilling at the Mateguafa Attic field. Management believes these activities could significantly increase future production levels and further strengthen the company’s position within Colombia as it seeks an extension to the Tapir block licence.

    More about Arrow Exploration Corp

    Arrow Exploration Corp. (LSE:AXL) is a Calgary-based oil and gas producer focused on high-growth hydrocarbon operations in Colombia, alongside a smaller portfolio of assets in Alberta, Canada. The company’s operations are centred on crude oil developments within the Tapir block, including the Carrizales Norte, Mateguafa Attic, Alberta Llanos and Icaco areas, with a strategy focused on light oil production and self-funded operational growth.

  • Physiomics Secures More Than £345,000 in New Drug Development Contracts (PYC)

    Physiomics Secures More Than £345,000 in New Drug Development Contracts (PYC)

    Physiomics plc (LSE:PYC) has announced a series of new contract wins during May valued at more than £345,000, including both new and repeat business with UK and international biotechnology and oncology-focused organisations. Among the agreements is work for a NASDAQ-listed clinical-stage biotechnology company. The contracts draw on Physiomics’ capabilities in modelling, simulation and data science to support Phase 1 and Phase 2 clinical analysis, first-in-human dose selection and wider clinical development programmes.

    The projects are expected to generate revenue through to the end of 2027 while strengthening the company’s order book, client relationships and standing within the biotechnology and pharmaceutical industries. Management said the latest contract awards further demonstrate demand for Physiomics’ specialist expertise across oncology and drug development services.

    The company’s outlook continues to be weighed down by weak financial performance, including ongoing net losses and recurring negative operating and free cash flow, despite maintaining a relatively low-debt balance sheet. Technical indicators are more supportive, with the share price trading above key moving averages and showing positive MACD momentum. Valuation remains mixed due to the company’s negative price-to-earnings ratio and the absence of a dividend yield.

    More about Physiomics

    Physiomics plc (LSE:PYC) is a UK-based specialist in mathematical modelling, data science and biostatistics focused on supporting biotechnology and pharmaceutical companies in drug development and personalised medicine. The company uses modelling and simulation, biometrics, bioinformatics and its proprietary Virtual Tumour platform to optimise discovery, pre-clinical and clinical programmes, working with a range of major pharmaceutical and oncology-focused biotechnology clients.