Author: Fiona Craig

  • Market Open: Wickes Revenue Rises, Anglo American Copper Falls

    Market Open: Wickes Revenue Rises, Anglo American Copper Falls

    FTSE 100 and European stocks decline as Wickes reports revenue growth, Anglo American copper output falls and Brent crude advances amid supply risks.

    Market Overview

    The FTSE 100 opened 0.35 per cent lower at 10,726.93, as concerns over French civil unrest and tensions involving Iran weighed on investor sentiment. European markets also declined, with the Euronext 100 falling 0.68 per cent to 1,849.01 and Germany’s DAX losing 0.73 per cent to 25,133.83. On Wall Street, the Nasdaq closed higher at 26,430.89, while the S&P 500 advanced to 7,690.73, providing a more positive backdrop from US equities.

    Commodity markets were mixed, with copper and gold moving lower, while Brent crude and natural gas advanced. Oil prices remained supported by concerns over supply disruption around the Strait of Hormuz, where attacks have threatened efforts to restore energy shipments. Against sterling, the US dollar, euro, Japanese yen and Australian dollar weakened, while the Swiss franc strengthened marginally. Bitcoin declined against the pound, reflecting a cautious tone across digital assets.


    Market Numbers

    FTSE 100: Down (-0.35%), 10,726.93
    Euronext 100: Down (-0.68%), 1,849.01
    DAX: Down (-0.73%), 25,133.83
    NASDAQ: Up, 26,430.89
    S&P 500: Up, 7,690.73


    In the Headlines

    Quarterly Revenue Growth – Wickes Group (LSE:WIX)
    Home improvement retailer Wickes reported a 4.5 per cent increase in third-quarter revenue to £439 million and maintained its 2026 profit outlook. The update indicates continued sales growth while providing investors with confirmation of the company’s full-year earnings expectations.

    Copper Production Declines – Anglo American (LSE:AAL)
    Diversified mining group Anglo American reported a 5 per cent decline in third-quarter copper production but maintained its 2026 production guidance. The update highlights lower quarterly output while indicating that the company continues to expect to meet its annual targets.


    Currencies (vs GBP)

    USD: Down (-0.28%), $1.3346
    CHF: Up (+0.01%), Fr.1.1004
    EUR: Down (-0.11%), €1.1883
    JPY: Down (-0.00%), ¥210.9885
    AUD: Down (-0.10%), $1.908
    Bitcoin (BTC/GBP): Down, £61,055.20


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Up
  • FTSE 100 Falls as French Unrest and US-Iran Tensions Offset UK Labour Market Data

    FTSE 100 Falls as French Unrest and US-Iran Tensions Offset UK Labour Market Data

    UK equities declined on Tuesday as political unrest in France and continued uncertainty surrounding the US-Iran conflict weighed on European markets, despite signs of easing pressure in Britain’s labour market.

    The FTSE 100 fell 0.36%, while Germany’s DAX declined 0.80% and France’s CAC 40 lost 0.43%. Sterling strengthened 0.30% against the US dollar to $1.3346 as of 07:31 GMT.

    UK employment figures presented a mixed picture ahead of Wednesday’s inflation report. The unemployment rate fell to 4.7% in the three months to August, below economists’ expectations of 4.9%.

    However, job vacancies declined to 691,000, their lowest level since 2014 excluding the pandemic period. Annual growth in total pay slowed to 3.7% from 3.9%, suggesting a moderation in wage pressures.

    The figures provide additional information for the Bank of England as it assesses labour market conditions and the outlook for inflation.

    Geopolitical developments remained a significant influence on market sentiment. US President Donald Trump said Washington continued to apply economic and military pressure on Iran, while uncertainty persisted over the prospects for negotiations.

    Speaking at the Global Security Forum in Doha, US envoy Tom Barrack questioned the effectiveness of previous American interventions in the region but said Washington had no intention of withdrawing.

    Meanwhile, Iranian media reported that Pakistani army chief Field Marshal Asim Munir was expected in Tehran on Tuesday, following a visit by Russian Foreign Minister Sergey Lavrov.

    Iran’s Revolutionary Guards also claimed to have shot down a US MQ-9 drone over the Strait of Hormuz. The claim, reported by Iranian state broadcaster IRIB, had not been independently confirmed by US authorities in the information available.

    Concerns about the financial consequences of the conflict also continued. Five Democratic senators, led by Elizabeth Warren, requested further disclosure of US military spending, with reported costs reaching $43.6 billion through 3 September, excluding damage to military bases.

    Separately, an Iranian Revolutionary Guards spokesman threatened undersea communications cables in the Strait of Hormuz, adding to concerns about regional infrastructure.

    In Europe, French authorities introduced partial curfews in several cities following nationwide unrest over the weekend.

    Paris imposed restrictions on public gatherings from 8 pm, alongside an overnight curfew between 11 pm and 6 am in areas surrounding Place de la République and Les Halles.

    Oil prices advanced amid the continuing geopolitical uncertainty. Brent crude futures rose nearly 1% to $110.59 a barrel, while US West Texas Intermediate gained 0.85% to $99.39.

    Precious metals moved in the opposite direction, with gold futures declining 0.26% to $4,150 an ounce and spot gold falling 0.24% to $4,130.22.

    UK Corporate Updates

    Wickes (LSE:WIX) reported a 4% increase in third-quarter like-for-like sales, supported by demand from price-conscious consumers. The home improvement retailer said customers continued to favour lower-priced products despite modest price inflation.

    Anglo American (LSE:AAL) recorded a 5% decline in third-quarter copper production, reflecting disruption from record snowfall in Chile. The mining group maintained its 2026 copper production guidance while increasing its diamond output forecast.

    Bunzl (LSE:BNZL) reported 3.7% growth in third-quarter underlying revenue, supported by its North American operations. The distribution group also reaffirmed its full-year outlook.

    Investors will now be monitoring Wednesday’s UK inflation figures for further indications of the Bank of England’s potential monetary policy direction.

    Developments in the Middle East, oil price movements and the situation in France are also likely to remain important influences on European market sentiment.

  • AstraZeneca Partners With Oracle to Apply AI to Clinical Research and Healthcare Processes

    AstraZeneca Partners With Oracle to Apply AI to Clinical Research and Healthcare Processes

    AstraZeneca (LSE:AZN) has announced a partnership with Oracle (NYSE:ORCL) to explore the use of artificial intelligence, cloud computing and data management technologies in clinical research and healthcare delivery.

    The collaboration will focus on improving connections between scientific research and clinical workflows, rather than using AI primarily to identify new drug targets.

    According to AstraZeneca, the companies intend to investigate practical applications of Oracle’s technology in several areas of clinical research and patient care.

    These include improving patient recruitment for clinical trials, supporting earlier disease diagnosis and enhancing drug safety monitoring.

    The first programme under the agreement will focus on hypertension care and clinical research in Abu Dhabi, in collaboration with healthcare technology company M42.

    The initiative will examine how AI and data management systems can be applied to clinical processes associated with the diagnosis, treatment and study of high blood pressure.

    AstraZeneca said the broader partnership will involve multiple international projects across the United States, the Middle East and Europe.

    The collaboration is expected to cover the pharmaceutical company’s principal therapeutic areas, including oncology, cardiovascular, renal and metabolic diseases, respiratory and immunology conditions, and rare diseases.

    Oracle will contribute its AI, cloud infrastructure and data management capabilities, while AstraZeneca will provide its pharmaceutical research and clinical development expertise.

    The announcement did not disclose the financial terms of the partnership, specific investment commitments or expected revenue contributions for either company.

    It also did not provide implementation timelines or measurable performance targets for the planned international projects.

    For investors, the agreement represents an expansion of AstraZeneca’s use of external technology partnerships to support clinical research and healthcare operations.

    The potential significance will depend on whether the proposed applications lead to measurable improvements in clinical trial processes, diagnostic workflows or drug safety monitoring.

    The collaboration also provides Oracle with an opportunity to apply its enterprise technology systems within pharmaceutical research and healthcare environments.

    However, the announcement outlines planned applications rather than completed deployments or demonstrated clinical outcomes.

    Looking ahead, investors will be monitoring progress on the initial hypertension programme in Abu Dhabi, the launch of additional projects and any reported operational results from the partnership.

    Further details on implementation schedules, commercial arrangements and the effectiveness of the AI applications will be relevant to assessing the collaboration’s longer-term impact.

  • Capita Shares Fall 3.4% as Company Postpones Capital Markets Event to December

    Capita Shares Fall 3.4% as Company Postpones Capital Markets Event to December

    Capita (LSE:CPI) shares declined 3.4% on Tuesday after the UK outsourcing group announced the postponement of its planned capital markets event.

    The event, originally scheduled for 4 November 2026, has been rescheduled for December, when it will take place alongside the company’s regular trading update.

    Capita said the decision reflects its current focus on improving the performance of its civil service pension scheme administration contract with the UK Cabinet Office.

    The contract has experienced operational difficulties, prompting the company to prioritise efforts to address the issues before holding its investor presentation.

    The postponement delays the opportunity for investors to receive the information that Capita had planned to present at the November event.

    However, the company has not announced any changes to its financial guidance or disclosed additional financial implications arising from the contract in the supplied update.

    For investors, the immediate development is the delay to the capital markets presentation and the company’s continued focus on resolving difficulties with the Cabinet Office contract.

    The share price decline followed the announcement, although the information provided does not establish the extent to which the postponement alone accounted for the market movement.

    The next scheduled update in December will provide an opportunity for Capita to report on trading performance and potentially offer further details about progress with the pension administration contract.

  • BHP Reports 19% Decline in Q1 Copper Production but Maintains FY27 Guidance

    BHP Reports 19% Decline in Q1 Copper Production but Maintains FY27 Guidance

    BHP Group (LSE:BHP) reported a 19% decline in copper production for the first quarter of its 2027 financial year, reflecting lower ore grades, scheduled maintenance and operational disruptions at several mining sites.

    The mining group produced 400,700 metric tonnes of copper during the three months ended 30 September 2026, compared with 493,600 tonnes in the corresponding period last year.

    Production was affected by lower planned concentrator feed grades at the Escondida and Spence operations in Chile.

    In Australia, severe weather and a conveyor belt failure disrupted operations at the Carrapateena copper mine, contributing to the overall reduction in output.

    Despite the decline, BHP maintained its full-year copper production guidance of between 1.65 million and 1.8 million tonnes for FY27.

    Iron ore production increased to 66.5 million metric tonnes during the quarter, compared with 64.1 million tonnes a year earlier, representing growth of approximately 3.7%.

    The increase was supported by performance across BHP’s Western Australia Iron Ore operations, including its mining, rail and port infrastructure.

    The company reported quarterly production records at both its mines and port facilities despite significant planned maintenance during the period.

    BHP also reaffirmed its full-year iron ore production guidance of between 260 million and 272 million tonnes.

    Commodity pricing trends varied across the group’s principal products.

    BHP reported a 53% year-on-year increase in its average realised copper price to $7.01 per pound, providing additional revenue support despite lower production volumes.

    Meanwhile, the average realised iron ore price declined by 9% to $76.27 per wet metric tonne.

    The contrasting price movements highlight differences in market conditions affecting the company’s copper and iron ore businesses.

    BHP also addressed workplace safety following fatal incidents at its Escondida and Peak Downs operations.

    The company said investigations into both incidents were underway and reiterated that safety remained a priority.

    For investors, the quarterly update presents a combination of lower copper volumes, higher realised copper prices and increased iron ore production.

    The rise in copper prices may help offset some of the financial impact of reduced output, although the overall effect on earnings will depend on production costs and other operating factors.

    Maintaining full-year guidance indicates that BHP has not revised its annual production expectations following the first-quarter disruptions.

    Looking ahead, investors will be monitoring copper production recovery, operational conditions at Escondida, Spence and Carrapateena, and the group’s progress towards its FY27 output targets.

    Changes in realised commodity prices and the findings of the ongoing safety investigations will also remain relevant to the company’s operational and financial performance.

  • Ocado Shares Rise 5.8% to 52-Week High Following Morgan Stanley Upgrade and JPMorgan Price Target Increase

    Ocado Shares Rise 5.8% to 52-Week High Following Morgan Stanley Upgrade and JPMorgan Price Target Increase

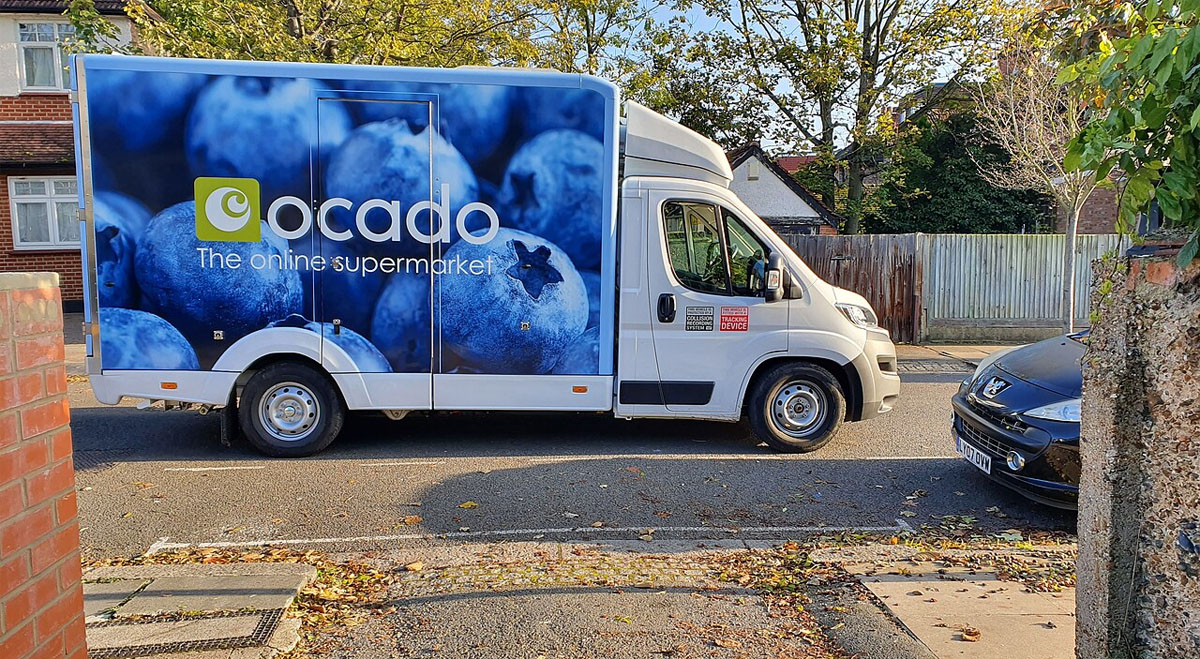
    Ocado Group (LSE:OCDO) shares rose 5.8% to 335.49p, reaching a new 52-week intraday high of 340p, following positive analyst revisions from Morgan Stanley and JPMorgan.

    The UK online grocery technology and automation company’s share price advance followed Morgan Stanley’s decision to upgrade its rating from Underweight to Equal Weight and increase its price target to 300p from 170p.

    Morgan Stanley said much of the negative news affecting Ocado in recent years was now behind the company, prompting a reassessment of its outlook.

    JPMorgan also increased its price target for Ocado to 460p from 290p, while maintaining its Overweight rating.

    The revised targets represent increases of approximately 76% from Morgan Stanley and 59% from JPMorgan, reflecting changes in the investment banks’ assessments of the company’s prospects.

    Research from JPMorgan and Berenberg has also highlighted the potential contribution of Ocado’s software and robotics technology to future contracts in the automated grocery fulfilment market.

    The analyst revisions follow operational developments reported by Ocado during the first half of 2026.

    The company reported revenue and EBITDA growth, supported by its international technology operations and retail business.

    Ocado Retail recorded 15% year-on-year growth, while international volumes increased by 27% over the same period.

    Management has also outlined cost reduction measures and organisational changes intended to improve the group’s financial performance.

    Ocado expects these initiatives to support positive cash flow in the second half of 2026 and during the 2027 financial year, although these remain company forecasts.

    The group has continued to secure technology agreements, including a contract announced in July to develop a large automated customer fulfilment centre for a European national retailer.

    The agreement forms part of Ocado’s international technology operations, which provide automated warehouse systems and related software to grocery retailers.

    Ocado’s latest share price increase followed a gain of 8.93% in the previous trading session, during which the FTSE 250 declined by 0.63%.

    The difference in performance indicates that Ocado shares moved independently of the broader mid-cap UK equity market during that session.

    For investors, the principal developments are the upward revisions to analyst ratings and price targets, alongside the company’s reported growth in retail and international operations.

    The Morgan Stanley upgrade is particularly relevant because it represents a change from a previously negative assessment to a neutral rating.

    However, analyst price targets reflect individual research forecasts and do not guarantee future share price performance.

    Ocado’s progress towards its cash flow objectives also remains an important consideration, particularly as the company continues investing in its automated fulfilment technology.

    Looking ahead, investors will be monitoring additional technology contract announcements, international deployment activity, operating profitability and progress towards the company’s stated cash flow targets.

    Further analyst revisions and developments in Ocado’s commercial pipeline may also influence market assessments of the business.

  • Gulf Marine Services Reports 10% Revenue Growth to $151.8 Million but Defers Shareholder Distributions

    Gulf Marine Services Reports 10% Revenue Growth to $151.8 Million but Defers Shareholder Distributions

    Gulf Marine Services (LSE:GMS) has reported a 10% increase in adjusted revenue to $151.8 million for the first nine months of 2026, while announcing that shareholder distributions will be deferred amid continuing geopolitical uncertainty in the Gulf region.

    The offshore support vessel operator said revenue growth was supported by higher average vessel day rates and the deployment of a newly acquired mid-class vessel in Latin America.

    Adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) remained broadly unchanged at $81.5 million during the period.

    However, vessel utilisation declined to 80%, reflecting operational disruption associated with the conflict in the Gulf.

    The company estimated that the disruption resulted in approximately $10.1 million of lost revenue, while additional war risk insurance costs also affected operations.

    Despite these challenges, Gulf Marine Services reported an increase in its contracted order backlog to $616 million, providing visibility over future vessel activity.

    The group operates a fleet of 15 self-propelled, self-elevating support vessels used in offshore oil, gas and renewable energy operations.

    Its vessels support activities including platform maintenance, well intervention and offshore wind construction across international markets.

    The company’s expansion into Latin America represents a further step in its geographical diversification strategy, with the recently acquired vessel contributing to revenue during the reporting period.

    However, the acquisition was partly financed through additional borrowing, contributing to an increase in net bank debt.

    Gulf Marine Services reported leverage of 1.55 times, remaining below its stated target ceiling of 2.0 times.

    Management maintained its full-year 2026 adjusted EBITDA guidance of between $105 million and $115 million.

    The company also confirmed that it would postpone shareholder distributions until there is greater clarity regarding geopolitical risks affecting its Gulf operations.

    No revised timetable for distributions was provided in the supplied update.

    For investors, the trading statement highlights the contrast between higher revenue and a growing order backlog on one hand, and disruption-related costs and increased borrowing on the other.

    The $616 million backlog provides an indication of contracted future work, although revenue recognition will depend on project schedules and operational delivery.

    The decision to defer shareholder distributions also changes the near-term capital return outlook, despite the company maintaining its full-year EBITDA expectations.

    Looking ahead, investors will be monitoring vessel utilisation, the financial impact of Gulf-related disruption, developments in war risk insurance costs and progress in reducing leverage.

    The timing of any resumption in shareholder distributions and performance against the $105 million to $115 million EBITDA guidance will also remain relevant to the group’s financial outlook.

  • GB Group Reports £139.5 Million First-Half Revenue and Maintains FY27 Guidance

    GB Group Reports £139.5 Million First-Half Revenue and Maintains FY27 Guidance

    GB Group (LSE:GBG) has reported constant currency revenue of £139.5 million for the first half of its 2027 financial year, with growth in its core Identity and Location businesses offset by weaker performance in other operations.

    The identity verification and location technology specialist said its core Location and Identity segments achieved combined revenue growth of 4.5% during the period.

    Performance was supported by growth in the Location business and higher Identity revenue across Europe, the Middle East and Africa (EMEA).

    However, the group’s non-core Global Fraud Solutions business recorded a revenue decline, while its Americas Identity operations were affected by customer attrition.

    The differing performances across business segments contributed to more moderate overall revenue growth than that achieved by the core operations.

    GBG said it was accelerating operational efficiency measures as part of its efforts to manage costs and maintain profitability.

    The company also reported a goodwill impairment relating to its Americas business, reflecting an adjustment to the carrying value of that operation.

    The supplied trading update did not specify the impairment amount or provide a revised valuation for the affected business.

    Despite these developments, GBG maintained its full-year financial guidance.

    The company continues to expect revenue growth of between 1% and 3% for FY27, with adjusted operating profit anticipated to be in line with current market expectations.

    GBG provides identity verification, location intelligence and fraud prevention technology to more than 20,000 customers worldwide.

    Its services are used by businesses across sectors including financial services and gaming to verify customer identities, validate location information and support digital transactions.

    For investors, the first-half update highlights the difference between growth in GBG’s principal business segments and weaker performance in its non-core and Americas operations.

    The 4.5% growth recorded by Location and Identity provides an indication of demand within the company’s core activities, while customer losses in the Americas remain a factor affecting overall performance.

    The goodwill impairment is also relevant to the group’s reported financial results, although its impact on statutory earnings cannot be quantified from the information provided.

    Looking ahead, investors will be monitoring revenue trends in the Americas Identity business, the performance of Global Fraud Solutions and the financial impact of the company’s cost efficiency measures.

    Progress towards the full-year revenue growth target of 1% to 3% and delivery of adjusted operating profit in line with market expectations will remain the principal measures of performance during the second half.

  • Gear4music Reports 6% First-Half Revenue Growth to £85.4 Million as Warehouse Costs Affect EBITDA

    Gear4music Reports 6% First-Half Revenue Growth to £85.4 Million as Warehouse Costs Affect EBITDA

    Gear4music (LSE:G4M) has reported a 6% increase in revenue to £85.4 million for the six months ended 30 September 2026, with growth across its UK and international operations.

    The online musical instruments and equipment retailer said trading was in line with board expectations despite challenging comparative figures and continued pressure on discretionary consumer spending.

    UK revenue increased by 3% during the period, while sales in Europe and the Rest of World rose by 11%, reflecting faster growth across the group’s international markets.

    Gross profit is expected to reach £23.6 million, although earnings before interest, tax, depreciation and amortisation (EBITDA) are forecast to decline to £5.7 million.

    The company attributed the reduction in EBITDA to previously announced setup costs associated with its new automated UK warehouse.

    The investment forms part of Gear4music’s efforts to develop its distribution infrastructure and improve its operational capabilities.

    Alongside the warehouse project, the group continues to invest in its proprietary e-commerce platform, which supports online sales across multiple countries and currencies.

    Gear4music operates distribution facilities in the UK and Europe, including locations in Sweden, Germany, Ireland and Spain.

    The company sells musical instruments, audio equipment and related products through its own brands and third-party manufacturers, serving customers in more than 190 countries.

    Management said the first-half trading performance remained consistent with its expectations, with the important seasonal peak trading period still ahead.

    The board maintained its full-year outlook and continues to expect financial performance to be in line with current market consensus.

    No revised full-year revenue or profit figures were provided in the supplied trading update.

    For investors, the results highlight revenue growth across both domestic and international markets, alongside the short-term impact of investment in logistics infrastructure on operating earnings.

    The difference between revenue growth and the expected reduction in EBITDA reflects the additional costs associated with establishing the automated warehouse.

    The company’s ability to manage these costs while maintaining sales growth will remain relevant to its profitability as the new facility becomes operational.

    Looking ahead, investors will be monitoring performance during the peak trading season, progress with the warehouse project and whether full-year results meet market expectations.

  • Physiomics Secures £102,000 Drug Development Contract as Recent Awards Exceed £970,000

    Physiomics Secures £102,000 Drug Development Contract as Recent Awards Exceed £970,000

    Physiomics (LSE:PYC) has secured a new contract worth £102,000 for model-informed drug development (MIDD) services, bringing the total value of contracts announced since May 2026 to more than £970,000.

    The UK-based mathematical modelling and biostatistics specialist said the latest agreement covers pharmacokinetic and pharmacodynamic modelling, which is used to assess how drugs behave in the body and their effects over time.

    The new contract adds to a series of commercial awards secured by Physiomics during recent months, with their combined announced value now exceeding the company’s most recently reported annual revenue.

    Physiomics reported revenue of £941,222 for the 2026 financial year, meaning the value of contracts announced since May has surpassed that figure.

    However, contract awards do not necessarily translate into revenue within the same accounting period, as income recognition depends on the timing and delivery of the contracted services.

    The company provides computational modelling, simulation, data science and biostatistics services to pharmaceutical and biotechnology businesses developing new treatments.

    Its work supports drug development activities across discovery, preclinical research and clinical trials, including the use of its proprietary Virtual Tumour modelling technology.

    Alongside the contract announcement, Physiomics outlined measures intended to improve its operating cost structure.

    These include reducing reliance on external contractors, implementing cost-saving initiatives and investing in information technology systems to improve operational efficiency.

    Management expects these measures to support improved profitability as the company works to increase revenue.

    Physiomics also addressed investor speculation regarding the profitability of its commercial agreements, rejecting suggestions that it deliberately accepts loss-making contracts.

    The company reiterated its focus on securing additional business while maintaining control over operating expenditure.

    For investors, the latest announcement provides an indication of recent commercial activity, with announced contract values exceeding the company’s previous full-year revenue.

    The financial significance will depend on how much of this contracted work is delivered and recognised as revenue in future reporting periods.

    The company’s cost reduction programme is also relevant to its profitability outlook, although the announcement did not quantify the expected savings or provide updated earnings guidance.

    Looking ahead, investors will be monitoring the conversion of contract awards into recognised revenue, further commercial wins and the impact of operating cost reductions on financial performance.