Author: Fiona Craig

  • Strategic Minerals (SML) Expands Redmoor Drilling Programme Following Strong Mineralisation Results

    Strategic Minerals (SML) Expands Redmoor Drilling Programme Following Strong Mineralisation Results

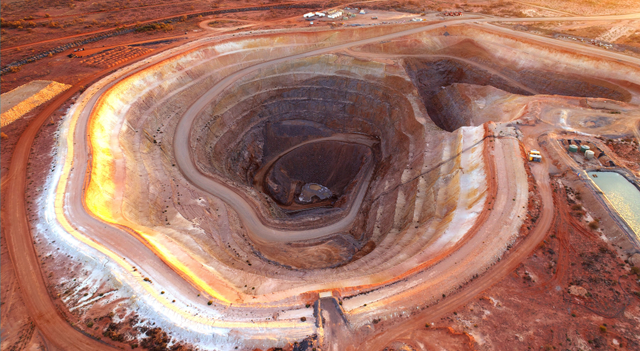
    Strategic Minerals (LSE:SML) has completed drillhole CRD042 at its Redmoor tungsten, tin and copper project in Cornwall, with the company reporting extensive mineralisation across the Sheeted Vein System and beyond the main target structure.

    The drillhole intersected significant occurrences of wolframite, cassiterite and chalcopyrite mineralisation, reinforcing confidence in the scale and continuity of the Redmoor deposit. Strategic Minerals also highlighted the successful use of navigational and wedge drilling techniques to achieve the tighter infill spacing required for ongoing resource development work.

    Samples from drillhole CRD042 have now been sent for laboratory analysis, while drilling operations have already advanced to hole CRD043 from the same drill pad.

    Supported by £8.7 million in funding raised earlier this year and a recent resource upgrade, the company has expanded its fully funded Redmoor drilling campaign to 22,500 metres across a minimum of 44 drillholes.

    The enlarged programme is intended to complete infill drilling, improve the project’s exploration target and provide technical data for geotechnical, metallurgical and hydrogeological studies that will contribute to a future prefeasibility study.

    Cornwall Resources, the company’s wholly owned subsidiary, has also submitted planning applications to deploy two additional drilling rigs, which are currently on standby pending approvals. Management believes the addition of further rigs could accelerate project development timelines and strengthen Redmoor’s strategic importance within the European critical minerals supply chain.

    The company’s outlook is supported by improving financial performance during 2024 and favourable technical momentum indicators. However, valuation metrics remain demanding due to a relatively high price-to-earnings ratio and the lack of dividend support, while overbought technical conditions may increase short-term volatility risks.

    More about Strategic Minerals plc

    Strategic Minerals plc is an international mineral exploration and production company focused on the development of critical metals projects. Through its subsidiary Cornwall Resources Limited, the group is advancing the Redmoor tungsten, tin and copper project in Cornwall, which is regarded as one of Europe’s highest-grade undeveloped tungsten resources and is positioned to support regional supply chain security for critical minerals.
  • Seeing Machines (SEE) Secures US$3.8m Autonomous Fleet Monitoring Contract

    Seeing Machines (SEE) Secures US$3.8m Autonomous Fleet Monitoring Contract

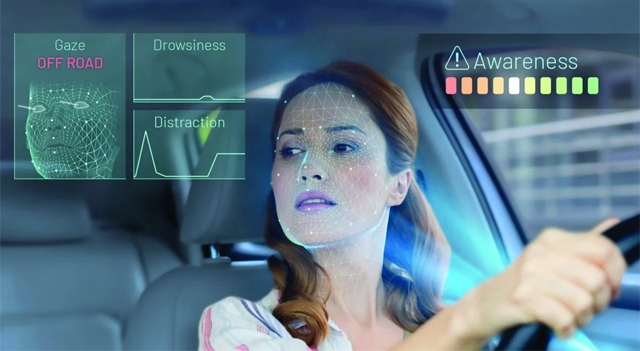
    Seeing Machines (LSE:SEE) has received a US$3.8 million purchase order for its Guardian Backup-driver Monitoring System from a major North American autonomous driving company, extending an existing relationship as the customer expands its autonomous vehicle testing operations internationally.

    The agreement reflects increasing demand for human oversight technology within autonomous mobility programmes, particularly in ride-hailing and fleet testing environments where safety operators are still required. Seeing Machines said its Guardian platform delivers real-time monitoring of backup drivers, helping support safer deployment of autonomous systems and regulatory compliance.

    The contract is also expected to contribute to a meaningful increase in aftermarket revenue during the current quarter.

    Management highlighted the importance of the company’s newly formed Future Mobility Group, which has been established to support the gradual rollout of autonomous transport technologies while human supervision remains necessary across many deployments.

    By combining driver monitoring expertise with tools specifically designed for autonomous fleet operations, Seeing Machines aims to strengthen its role as a technology partner to major autonomous vehicle developers and mobility operators.

    The company’s outlook continues to be affected by weak profitability and uneven cash flow performance despite strong revenue growth. Technical indicators remain relatively supportive, with the share price trading above key moving averages and momentum signals remaining positive, although elevated RSI levels suggest some potential for near-term volatility. Valuation metrics remain constrained by the company’s loss-making position and the absence of dividend income.

    More about Seeing Machines

    Seeing Machines is an Australia-headquartered technology company specialising in AI-powered vision systems designed to monitor driver and occupant behaviour. Listed on London’s AIM market, the company develops safety-focused monitoring solutions for automotive, commercial transport, off-road equipment and aviation applications. Its technology is used globally to improve operator safety and support the transition toward increasingly autonomous mobility systems.

  • Angling Direct (ANG) Delivers Record UK Sales and Raises Medium-Term Growth Ambitions

    Angling Direct (ANG) Delivers Record UK Sales and Raises Medium-Term Growth Ambitions

    Angling Direct (LSE:ANG) reported record full-year revenue of £103.9 million for the year ended 31 January 2026, supported by strong growth across both its retail store network and online operations.

    UK sales increased 14.8% to £99.2 million during the period, helping drive a significant improvement in profitability. Adjusted EBITDA rose 42.9% to £4.8 million, while gross margin expanded to 37.6%.

    The fishing tackle retailer also maintained a strong balance sheet, ending the year with a net cash position of £10.9 million. During the period, the company returned £2 million to shareholders through a share buyback programme that reduced the total share count by approximately 6%.

    Operationally, Angling Direct continued expanding its MyAD loyalty and membership platform, with UK membership increasing nearly 47% to more than 600,000 users. The company also opened six additional stores during the year, taking its estate to 58 locations.

    Management acknowledged softer recent trading conditions and some modest cost pressures linked to disruption stemming from the conflict in the Middle East. However, the company said it remains comfortable with FY27 expectations and has upgraded several of its medium-term growth targets.

    These include a revised UK revenue target of £125 million, higher EBITDA ambitions and continued international expansion across Germany and the Netherlands. Management also reiterated its focus on disciplined capital allocation and responsible employment practices as part of its broader growth strategy.

    The company’s outlook is supported by strong financial performance and recent operational progress, although technical indicators currently suggest weaker short-term momentum. Valuation metrics remain moderately attractive, while the absence of updated earnings call guidance limits visibility into longer-term expectations.

    More about Angling Direct Plc

    Angling Direct Plc is the UK’s largest omni-channel fishing tackle retailer, operating both physical stores and digital sales platforms across the UK and Europe. Headquartered in Norfolk, the company sells more than 25,000 fishing products from major third-party brands alongside its own Advanta and Discover ranges. Angling Direct also operates the MyAD Fishing Club platform and maintains dedicated e-commerce websites in markets including Germany, France and the Netherlands.

  • Marston’s (MARS) Improves Margins and Profitability as Refurbishment Strategy Gains Traction

    Marston’s (MARS) Improves Margins and Profitability as Refurbishment Strategy Gains Traction

    Marston’s (LSE:MARS) reported resilient interim results for the 26 weeks ended 28 March 2026, delivering improved profitability and stronger margins despite a slight decline in revenue.

    Group revenue fell 1.1% to £422.7 million during the period, while underlying EBITDA remained stable at £85.9 million. The pub operator said tighter cost management and improved labour efficiency helped offset softer sales and supported margin expansion across the business.

    Underlying profit before tax increased 7.9% to £20.5 million, while leverage improved modestly to 4.7 times. Net asset value per share also rose by almost 20% year-on-year, reflecting continued progress in strengthening the balance sheet and improving overall financial performance.

    A key part of the company’s growth strategy has been the rollout of refreshed pub concepts and upgraded venue formats. Marston’s completed 60 refurbishments during the first half, bringing the total number of completed projects since FY2025 to 91.

    Management said the refurbished sites have generated average returns on invested capital of around 35% and delivered like-for-like sales growth close to 20%, supporting plans for further expansion of the programme.

    The group is increasing capital investment and continuing to develop digital initiatives such as its Order & Pay platform. Management also said the estate is well positioned for the important summer trading period, including expected demand linked to the World Cup, while signalling confidence in achieving full-year expectations and exploring a broader rollout of new pub formats from FY2027 onward.

    The company’s outlook continues to improve as profitability, cash flow and deleveraging trends strengthen. Valuation metrics remain supportive due to a relatively low price-to-earnings ratio, although mixed technical indicators and weaker short-term share price momentum continue to weigh slightly on sentiment.

    More about Marston’s PLC

    Marston’s is a major UK hospitality group operating more than 1,300 pubs across managed, franchised and tenanted formats. The company focuses on community-led venues and has increasingly invested in differentiated pub concepts, digital ordering systems and customer experience initiatives to support long-term growth and operational efficiency.

  • Renew Holdings (RNWH) Delivers Record Half-Year Results as Acquisitions Strengthen Growth Pipeline

    Renew Holdings (RNWH) Delivers Record Half-Year Results as Acquisitions Strengthen Growth Pipeline

    Renew Holdings (LSE:RNWH) reported record interim results for the six months ended 31 March 2026, with revenue increasing 3.5% to £589 million and adjusted operating profit rising 4.4% to £33.4 million. The improvement also led to a modest increase in operating margins and helped the group move into a pre-IFRS 16 net cash position of £10.6 million.

    The company’s order book reached a record £945 million during the period, reflecting strong demand across its infrastructure markets. Renew also increased its interim dividend to 7.0p per share, supported by solid cash generation and improved visibility over future workloads.

    Operationally, the group continued to strengthen its position across core sectors. Renew retained its status as Network Rail’s largest infrastructure services supplier while also delivering record activity levels within its water operations. Management highlighted increasing collaboration between the company’s subsidiaries as part of its broader growth strategy.

    The business also expanded through targeted acquisitions, completing the purchase of Emerald Power during the reporting period and subsequently acquiring Edwards Diving Services and PWR-X after the period end. The deals broaden Renew’s capabilities across specialist water services, overhead line infrastructure and high-voltage power markets.

    Management said the acquisitions support the group’s active M&A strategy, which is intended to complement organic growth and expand exposure to long-term regulated infrastructure spending programmes. Organic growth during the first half reached 2.2%, with the company expecting stronger momentum in the second half of the year.

    Over the five years to September 2025, Renew has delivered consistent compounded growth through a combination of operational expansion and seven strategic acquisitions, reinforcing its position as a relatively low-risk provider of essential infrastructure maintenance and renewal services.

    The company’s outlook remains supported by steady revenue growth, disciplined cash management and resilient demand across regulated end markets. While technical indicators suggest some near-term share price weakness, valuation metrics remain broadly reasonable and are complemented by a moderate dividend yield.

    More about Renew Holdings plc

    Renew Holdings plc is a UK engineering services group specialising in the maintenance and renewal of critical national infrastructure. Through a portfolio of independently branded subsidiaries, the company provides non-discretionary services across regulated sectors including rail, energy, environmental services and infrastructure, benefiting from long-term funding commitments and recurring maintenance demand.

  • Imperial Brands (IMB) Increases Shareholder Returns as Strategic Transformation Gains Momentum

    Imperial Brands (IMB) Increases Shareholder Returns as Strategic Transformation Gains Momentum

    Imperial Brands (LSE:IMB) reported modest revenue growth for the six months ended 31 March 2026, with tobacco and next-generation product (NGP) net revenue rising 1.8% as pricing strength in traditional cigarettes and continued expansion in reduced-risk products helped offset lower sales volumes.

    Adjusted operating profit increased 0.6% during the period, while adjusted earnings per share climbed 5.3%, supported by strong cash generation and a cash conversion rate of 98%. However, reported operating profit declined significantly due to costs associated with the Delaware legal settlement and investment tied to the company’s long-term 2030 Strategy.

    Imperial Brands continued to expand its next-generation portfolio, delivering double-digit NGP growth across Europe and the company’s AAACE region, which covers Africa, Asia, Australasia, Central and Eastern Europe, and the Middle East. The group also reported market share gains for its heated tobacco products and newly launched reusable vape systems in several key territories.

    Management reaffirmed full-year guidance and highlighted progress toward its target of delivering £320 million in annual cost savings by 2030. The company is also continuing manufacturing rationalisation initiatives and recently entered into a strategic partnership with Capgemini to strengthen its data analytics and artificial intelligence capabilities.

    Shareholder returns were further enhanced through an expanded share buyback programme and a 4% increase in the interim dividend.

    The company’s outlook remains supported by resilient operational performance, constructive technical indicators and an attractive valuation profile. While debt management, regulatory risks and cash flow discipline remain important considerations, ongoing strategic execution and operational efficiency measures are viewed positively by the market.

    More about Imperial Brands

    Imperial Brands is an international tobacco and next-generation nicotine products group operating across Europe, the United States and a range of growth markets in Africa, Asia and the Middle East. Its portfolio includes combustible cigarettes, heated tobacco products, vaping devices and oral nicotine offerings. The company is focused on strengthening its position as a challenger brand through consumer-led innovation, supply chain efficiency and data-driven operational strategies.

  • Wickes (WIX) Delivers Revenue Growth as TradePro and Installation Services Drive Performance

    Wickes (WIX) Delivers Revenue Growth as TradePro and Installation Services Drive Performance

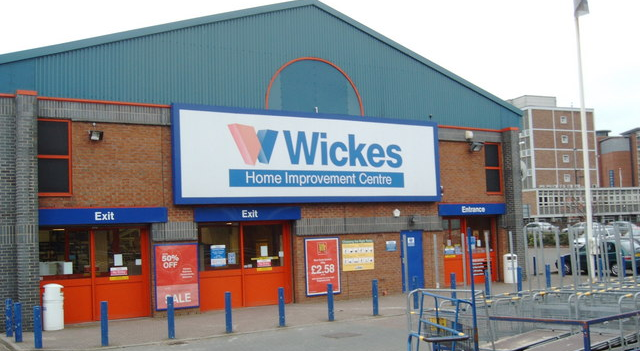
    Wickes (LSE:WIX) reported group revenue of £537 million for the 17 weeks to 25 April 2026, representing growth of 1.3% year-on-year as strong performances in Design & Installation and TradePro helped offset weaker DIY demand linked to poor weather conditions.

    Retail revenue remained broadly unchanged during the period, although the company said it continued to gain market share across several core categories, including interior paint, tiling, flooring and timber products. Management attributed part of this performance to deflationary pricing strategies and continued growth in active TradePro membership.

    The Design & Installation division recorded revenue growth of 6.4%, supported by ongoing strength in bathroom products and the Lifestyle Kitchens range. However, demand for higher-value Bespoke Kitchens softened as customers became more cautious with discretionary spending.

    Wickes said it remains focused on expanding its store network toward a long-term target of 300 locations. The company plans to open as many as five new stores this year while also completing up to 20 store refits across the existing estate.

    Management stated that the group’s value-focused offering, operational productivity initiatives and lower business rates provide confidence that full-year 2026 profit expectations will be achieved despite continuing uncertainty in the consumer environment.

    The company’s outlook reflects a mixed financial profile, with improving cash flow performance partially offset by relatively high leverage and narrow profit margins. Technical indicators currently point to weaker near-term momentum, while valuation support comes from a moderate earnings multiple and a solid dividend yield.

    More about Wickes Group

    Wickes Group is a UK home improvement retailer serving trade professionals, DIY customers and project-based Design & Installation clients. The company operates approximately 230 stores alongside digital sales channels, offering products and services across kitchens, bathrooms, flooring, decorating and general home improvement, supported by nationwide fulfilment capabilities.

  • RUA Life Sciences (RUA) Spins Out Structural Heart Division Following £3m Funding Round

    RUA Life Sciences (RUA) Spins Out Structural Heart Division Following £3m Funding Round

    RUA Life Sciences (LSE:RUA) has completed the spin-out of its subsidiary RUA Structural Heart alongside securing a £3 million convertible funding round led by the Leducq organisation. The transaction also included the conversion of £4.8 million of intercompany debt into equivalent loan stock.

    Although RUA continues to retain full equity ownership of the subsidiary at present, the company said RUA Structural Heart will now be accounted for as an investment rather than a directly funded operating division. Management expects the move to strengthen the group’s balance sheet, improve annual profitability and allow greater focus on the company’s contract development and manufacturing (CDMO) operations.

    The newly raised funding will support further development of the company’s AurTex-based surgical mitral valve programme, including optimisation work, durability testing, animal studies and expansion of the specialist development team.

    The valve technology is primarily aimed at treating rheumatic heart disease patients in low- and middle-income countries, where access to durable and affordable valve replacements remains limited. RUA Structural Heart said the programme has backing from leading heart valve specialists and is designed to attract specialist healthcare investors as development progresses.

    Management believes the AurTex platform has the potential to address a significant unmet medical need while improving the durability and cost profile of polymer-based heart valves on a global scale.

    The company’s outlook continues to be affected by ongoing operating losses and negative operating and free cash flow despite strong revenue growth and a relatively low-leverage balance sheet. Technical indicators remain supportive, with positive momentum trends and a favourable MACD signal, although overbought conditions may create some near-term volatility. Valuation metrics appear more attractive due to the company’s comparatively low price-to-earnings ratio.

    More about RUA Life Sciences

    RUA Life Sciences is a medical technology company focused on implantable biostable polymers and cardiovascular devices. The group provides contract development and manufacturing services while also developing proprietary medical implants using its AurTex polymer composite platform. Its RUA Structural Heart business is focused on next-generation heart valve technologies targeting rheumatic heart disease in emerging markets as well as future applications in aortic valve treatment in developed healthcare systems.

  • Frontier Developments (FDEV) Raises FY26 Guidance Following Strong Game Performance

    Frontier Developments (FDEV) Raises FY26 Guidance Following Strong Game Performance

    Frontier Developments (LSE:FDEV) has upgraded its outlook for the financial year ending 31 May 2026 after stronger trading across its games portfolio and improved tax credit expectations.

    The company now expects annual revenue of approximately £103 million, while adjusted operating profit is forecast to reach around £16 million. Management attributed the improved guidance primarily to the successful launch and performance of Jurassic World Evolution 3, alongside steady sales from the wider catalogue of existing titles.

    Frontier also benefited from higher-than-expected tax relief after transitioning to the UK’s Video Games Expenditure Credits regime, providing an additional boost to profitability.

    The business continued to generate strong cash flow during the year, reporting a cash balance of £44.9 million at the end of April despite allocating £15.4 million toward share repurchases.

    Through its ongoing buyback programme, Frontier has repurchased and cancelled nearly four million shares, reducing total voting rights by approximately 10%. The company expects the reduced share count to improve earnings per share by around 11% from FY27 onward, reflecting management’s confidence in the group’s long-term prospects and commitment to shareholder returns.

    The company’s outlook is supported by improving profitability, robust cash generation and relatively low leverage levels. Valuation metrics also remain favourable due to a comparatively low price-to-earnings ratio. However, technical indicators continue to show weaker momentum, with the share price trading below key moving averages.

    More about Frontier Developments

    Frontier Developments is a Cambridge-based video game developer and publisher specialising in management simulation and strategy titles. The company develops games using its proprietary COBRA technology platform and is known for franchises including Planet Coaster, Planet Zoo and Jurassic World Evolution. Frontier’s business model combines new releases with recurring revenue from downloadable content and long-term catalogue sales.

  • Wizz Air (WIZZ) Targets Break-even Performance as Fleet Efficiency Supports Growth Strategy

    Wizz Air (WIZZ) Targets Break-even Performance as Fleet Efficiency Supports Growth Strategy

    Wizz Air (LSE:WIZZ) said it expects to deliver a break-even to slightly positive net profit for the financial year ending 31 March 2026, supported by stronger-than-expected revenue trends and a favourable macroeconomic backdrop. The airline also finished the period with a solid cash position of €2.1 billion.

    The carrier continues to benefit from its modern, fuel-efficient fleet, with Airbus A321neo aircraft now accounting for around 75% of operations. Management said the newer aircraft provide substantial fuel savings compared with previous-generation models, helping to support margins during a volatile operating environment.

    Wizz Air acknowledged that ongoing conflict in the Middle East is contributing to uncertainty around fuel prices and travel demand in the near term. However, the company noted that approximately 70% of its summer fuel requirements are hedged at roughly $720 per metric tonne, providing some protection against market fluctuations.

    The airline plans to operate around 51 million seats during the first half of the year, representing growth of 28% compared with the previous year. Expansion is being supported by strong forward bookings and the continued use of promotional pricing strategies as Wizz shifts capacity toward its core European markets.

    Management said the company remains focused on strengthening its position in leisure-oriented routes across Central and Eastern Europe, where it continues to see long-term growth opportunities.

    The company’s outlook is supported by improving profitability trends, recovering free cash flow and a relatively low earnings valuation. However, these positives are partially offset by weaker technical indicators, with the share price trading below key moving averages and momentum remaining negative. Investors are also monitoring execution risks tied to the company’s break-even guidance, pressure on unit revenues and ongoing transitional cost challenges.

    More about Wizz Air Holdings

    Wizz Air Holdings is a European low-cost airline operating a fleet primarily composed of Airbus A320 and A321 aircraft, including a large proportion of fuel-efficient A321neos. Listed in London under the ticker WIZZ, the airline focuses heavily on Central and Eastern Europe and carried more than 63 million passengers during its 2025 financial year. The company positions itself as a sustainability-focused airline through lower emissions intensity and continued investment in next-generation aircraft technology.