Author: Fiona Craig

  • FTSE 100 Holds Steady as Tech Weakness Offsets Easing Middle East Concerns

    FTSE 100 Holds Steady as Tech Weakness Offsets Easing Middle East Concerns

    UK equities traded in a narrow and volatile range on Wednesday as investors balanced improving conditions in the Middle East against a broad global sell-off in technology and semiconductor stocks, while also monitoring the political transition following Keir Starmer’s resignation.

    By 07:25 GMT, the FTSE 100 was up 0.09%, having moved between modest gains and losses during the session. Elsewhere in Europe, Germany’s DAX fell 0.65%, while France’s CAC 40 added 0.20%. Sterling weakened 0.05% against the US dollar to $1.3188.

    Political developments remained in focus in the UK. Starmer has continued discussions with expected successor Andy Burnham as part of a planned leadership handover and is due to meet European leaders in Berlin later in the day to discuss Ukraine, NATO defence spending and developments in Iran ahead of next month’s NATO summit.

    Meanwhile, geopolitical tensions appeared to ease further as shipping activity through the Strait of Hormuz gradually returned towards normal levels. Tanker movements increased as concerns over disruption from the Iran-Israel conflict moderated, helping reduce pressure on energy markets.

    The improvement followed comments from US officials rejecting suggestions that Iran could impose fees on vessels using the waterway. Diplomatic efforts continued throughout the region, although conflicting statements from Washington and Tehran highlighted the fragile nature of the current situation.

    Energy markets reflected the calmer backdrop. Brent crude declined 1.22% to $75.86 per barrel, while West Texas Intermediate crude fell 1.35% to $72.22. Precious metals also weakened, with gold futures down 1.14% at $4,102 and spot gold falling 0.61% to $4,084 per ounce.

    Technology stocks remained under pressure globally as investors reassessed valuations across the sector, contributing to a more cautious tone in equity markets despite the reduction in geopolitical risk.

    UK Corporate Highlights

    Berkeley misses profit expectations

    Berkeley Group (LSE:BKG) reported annual pre-tax profit below market forecasts as higher construction costs, slower development activity and cautious buyer demand weighed on profitability.

    SEGRO rejects Prologis approach

    SEGRO (LSE:SGRO) confirmed it had rejected an all-share takeover proposal from Prologis (NYSE:PLD) that valued the logistics property group at approximately £12.6 billion.

    B&M appoints new finance chief

    B&M (LSE:BME) named Asda executive Atheeq Akbar as its incoming Chief Financial Officer. He is expected to join the discount retailer in February 2027 as the company continues efforts to strengthen its UK operations.
  • Big Yellow Shares Jump as Property Sector Sentiment Improves Following SEGRO Developments (BYG)

    Big Yellow Shares Jump as Property Sector Sentiment Improves Following SEGRO Developments (BYG)

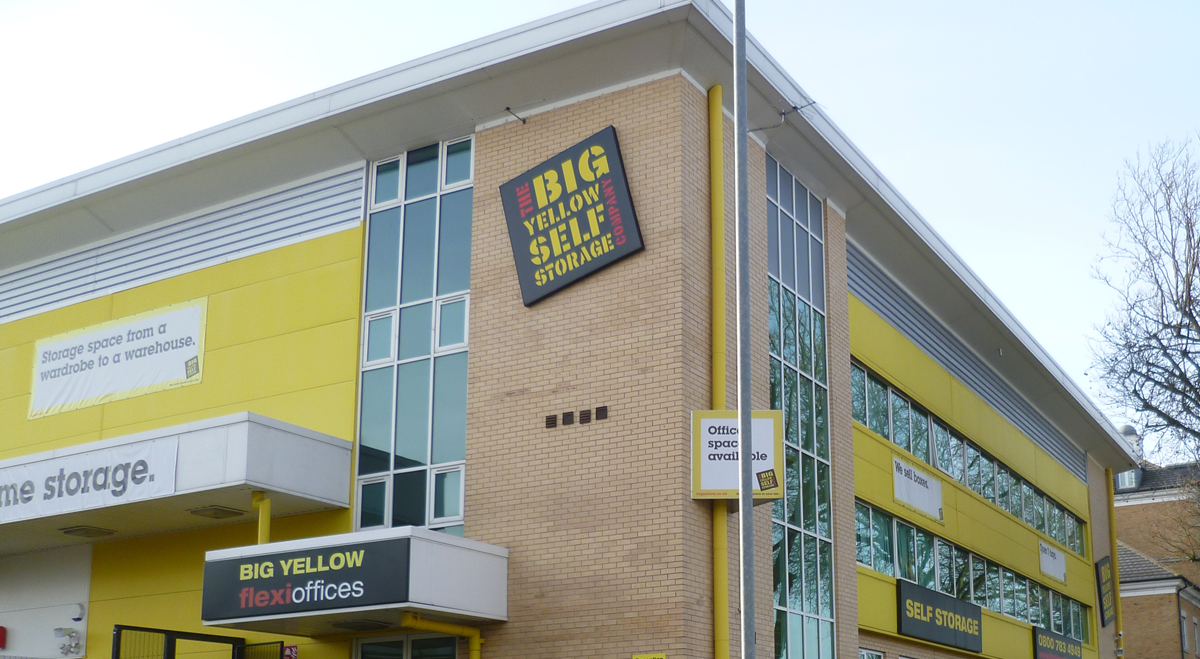
    Big Yellow Group (LSE:BYG) shares climbed 4.2% during Wednesday’s trading session, reaching 895.82p and touching an intraday high of 897.5p as investors returned to UK-listed real estate stocks following renewed takeover interest in the sector.

    The self-storage REIT benefited from stronger sentiment across property names after SEGRO rejected a takeover proposal from Prologis, a development that prompted investors to reassess valuations across the UK real estate market and highlighted the appeal of income-generating property assets.

    Despite the rally, Big Yellow remains significantly below its 52-week high of 1,208p, while trading only modestly above its 52-week low of 800.5p. This gap has attracted attention from value-focused investors who believe the company’s share price does not fully reflect the underlying value of its property portfolio and long-term earnings potential.

    As a property owner with substantial real estate assets, Big Yellow’s valuation is closely linked to expectations for UK interest rates. With the Bank of England base rate currently at 3.75%, investors continue to monitor the outlook for future monetary policy decisions, as lower borrowing costs would generally be supportive for property valuations and real estate investment trusts.

    The wider UK equity market has faced pressure in recent sessions amid domestic political uncertainty and weakness in global technology stocks. Against this backdrop, Big Yellow’s performance stood out, suggesting investors were willing to selectively re-enter parts of the property sector viewed as offering attractive value and defensive characteristics.

    Market participants also continue to watch developments across the self-storage industry, where demand trends have remained relatively resilient despite broader economic uncertainty. Combined with improving expectations for interest rates and a discounted valuation relative to recent highs, these factors helped drive renewed buying interest in the stock.

    More about Big Yellow Group

    Big Yellow Group is one of the UK’s largest self-storage operators, owning and managing a nationwide portfolio of storage facilities serving both individual and business customers. The company generates recurring rental income from its network of purpose-built sites and benefits from long-term structural demand for flexible storage solutions. As a real estate investment trust, Big Yellow combines property ownership with operational expertise in the growing self-storage sector, providing investors with exposure to both property assets and service-based revenues.

  • Tritax Big Box Jumps as SEGRO Rejection Fuels Renewed Interest in UK Logistics Property Sector (BBOX)

    Tritax Big Box Jumps as SEGRO Rejection Fuels Renewed Interest in UK Logistics Property Sector (BBOX)

    Shares in Tritax Big Box REIT (LSE:BBOX) climbed 5.6% to 160.28p, rebounding strongly after weakness in the previous session as investors reacted positively to developments in the UK logistics property market following SEGRO’s rejection of a takeover approach from Prologis.

    The move reflected renewed confidence across the sector, with investors reassessing the value of major UK logistics landlords after the proposed acquisition highlighted the attractiveness of high-quality industrial and warehouse assets. Tritax benefited from the improved sentiment, with its shares advancing toward the upper end of the day’s trading range.

    Analyst opinion remains firmly supportive of the company. Tritax continues to hold a strong consensus among market commentators, with eleven buy recommendations and no sell ratings. The average 12-month target price of around 180p suggests analysts see meaningful upside from current levels.

    The company’s valuation appeal is further supported by its relatively conservative balance sheet and largely fixed-rate debt structure, which reduces exposure to interest-rate volatility. As a result, the stock is particularly sensitive to any improvement in expectations for borrowing costs or a more supportive rate environment.

    The rally follows a difficult trading session on 23 June, when UK equities came under pressure amid political uncertainty and a broader technology-led global market sell-off. The FTSE 100 declined by around 0.6%, while the FTSE 250, of which Tritax is a constituent, also moved lower.

    Improved market stability on 24 June created conditions for a recovery in domestically focused and income-generating sectors, including real estate investment trusts. Investors continue to monitor interest-rate expectations closely, with the Bank of England base rate currently at 3.75% and the next Monetary Policy Committee decision scheduled for 30 July.

    A combination of recovering sentiment, attractive valuation metrics and continued demand for long-term logistics assets helped drive Tritax’s strong performance. Despite the sharp advance, the shares remain below their 52-week high of 174p, leaving room for further gains should sector conditions continue to improve.

    More about Tritax Big Box REIT

    Tritax Big Box REIT is a UK-focused real estate investment trust specialising in large-scale logistics and distribution properties. The company owns and develops strategically located warehouse assets leased to major retailers, e-commerce operators and logistics businesses under long-term agreements. Its portfolio is designed to generate stable rental income while benefiting from structural growth trends in online retail, supply chain modernisation and demand for high-quality logistics infrastructure.

  • B&M Names Asda Executive Atheeq Akbar as Incoming Finance Chief (BME)

    B&M Names Asda Executive Atheeq Akbar as Incoming Finance Chief (BME)

    B&M (LSE:BME) has appointed Asda executive Atheeq Akbar as its next Chief Financial Officer, strengthening its senior leadership team as the discount retailer continues efforts to enhance performance across its UK operations.

    Akbar is scheduled to join the company in February 2027 and will succeed interim CFO Pete Waterhouse. He currently serves as Vice President of Commercial Finance at Asda and brings extensive experience from senior finance and commercial roles within the retail sector.

    The appointment comes as Chief Executive Tjeerd Jegen advances a turnaround programme introduced in October to improve operational performance and reinforce B&M’s competitive position. The retailer has faced increasing pressure from supermarket loyalty schemes and ongoing constraints on consumer spending, particularly among lower-income households.

    Commenting on the appointment, Jegen said: “(Akbar’s) strong commercial background in UK retail will be a great asset as we bring about change to deepen the financial foundations of our business.”

    Before joining Asda, Akbar held senior positions at several major organisations, including Morrisons, Tesco and Etihad Airways, providing him with broad experience across retail, finance and commercial strategy.

    The announcement follows B&M’s recent full-year results, where the company reported pre-tax profit ahead of market expectations. Management said earlier this month that its turnaround initiatives were beginning to gain momentum and expressed confidence in its ability to manage higher operating costs linked to recent geopolitical developments.

    With a permanent finance leader now identified, B&M aims to continue strengthening its financial discipline, operational efficiency and long-term growth prospects as it executes its transformation strategy.

    More about B&M

    B&M is one of the UK’s leading discount retailers, operating a nationwide network of value-focused stores offering groceries, household goods, general merchandise and seasonal products. The company serves value-conscious consumers across the UK and France and focuses on delivering competitive pricing through a high-volume, low-cost operating model. As part of its ongoing strategy, B&M is investing in operational improvements and leadership enhancements to support sustainable long-term growth.

  • ITM Power and DB Systemtechnik Launch Green Hydrogen Initiative for Rail Applications (ITM)

    ITM Power and DB Systemtechnik Launch Green Hydrogen Initiative for Rail Applications (ITM)

    ITM Power (LSE:ITM) has signed a Letter of Intent with DB Systemtechnik to establish a research and innovation partnership focused on the development of green energy solutions for transport networks and critical infrastructure.

    The agreement expands ITM Power’s existing relationship with the wider Deutsche Bahn group and will initially focus on evaluating the role of green hydrogen in reducing emissions across rail operations and associated vehicle fleets while enhancing long-term energy resilience.

    As part of the collaboration, the companies will undertake a Front-End Engineering Design (FEED) study to examine how ITM Power’s electrolyser technology could be integrated into Deutsche Bahn facilities. The study will assess both the technical and commercial viability of deploying green hydrogen production systems at railway sites and other infrastructure locations.

    The partnership reflects growing interest in hydrogen as a decarbonisation tool for transport sectors where electrification may be more challenging or where additional energy flexibility is required. By combining ITM’s electrolyser expertise with Deutsche Bahn’s transport infrastructure capabilities, the companies aim to identify practical applications for hydrogen production and usage within the rail industry.

    Management believes the initiative supports ITM Power’s strategy of expanding the adoption of green hydrogen technologies across industrial and transport markets, while strengthening relationships with major infrastructure operators. The collaboration also provides an opportunity to showcase the commercial potential of the company’s electrolyser systems in large-scale, real-world applications.

    The project is expected to generate valuable technical and operational insights that could support future hydrogen deployment opportunities across rail networks and related transport systems.

    More about ITM Power

    ITM Power is a UK-based developer and manufacturer of industrial-scale electrolysers used to produce green hydrogen through proton exchange membrane (PEM) technology. The AIM-listed company designs and manufactures its systems in-house and supplies standardised hydrogen production plants to customers seeking to decarbonise industrial processes, energy systems and transportation networks. In addition to equipment sales, ITM offers hydrogen solutions through its Hydropulse build-own-operate model, supporting the wider adoption of clean hydrogen infrastructure.

  • THG Reports Stronger Growth and Cash Generation as Beauty and Nutrition Momentum Builds (THG)

    THG Reports Stronger Growth and Cash Generation as Beauty and Nutrition Momentum Builds (THG)

    THG (LSE:THG) returned to revenue growth during the first half of the year, with group sales increasing by approximately 6.5% and adjusted EBITDA for the 12 months to May rising 36% to around £94 million. The improvement was supported by disciplined cost management, stable gross margins and stronger performances across the company’s core Beauty and Nutrition divisions.

    Management reaffirmed its full-year outlook and highlighted the strongest first-half free cash flow performance since 2021, reflecting ongoing operational improvements and a greater focus on efficiency. The company also noted that its Term Loan B is currently trading above par value, which it believes demonstrates increasing confidence among lenders in the group’s financial position and long-term prospects.

    THG Beauty continued to deliver strong growth, led by a near 10% increase in skincare sales and ongoing momentum at Lookfantastic. The platform is outperforming the wider UK prestige beauty market and has established itself as the leading multi-brand beauty retailer on TikTok Shop, helping to drive customer acquisition and brand engagement.

    Within THG Nutrition, growth continued despite inflationary pressures affecting whey protein costs. Myprotein expanded further into adjacent health and wellness categories, increased volumes in its licensed ready-to-drink products and continued transitioning its Asian operations towards a higher-margin licensing model designed to improve profitability and scalability.

    The company is also awaiting a decision regarding £78 million of retrospective VAT claims. Management believes the outcome could have significant implications not only for THG but also for the broader sports nutrition industry.

    Looking ahead, THG remains focused on driving profitable growth through its global consumer brands, strengthening cash generation and leveraging its scale in digital commerce. Management believes the continued progress of its Beauty and Nutrition businesses provides a solid foundation for further operational and financial improvement.

    More about THG

    THG PLC is a Manchester-based global e-commerce company and brand owner operating primarily through its THG Beauty and THG Nutrition divisions. THG Beauty manages online platforms including Lookfantastic, Dermstore and Cult Beauty, offering access to more than 1,000 owned and third-party brands. THG Nutrition is led by the Myprotein brand and operates across sports nutrition, health and wellness categories, distributing products through online channels and a growing network of retail and licensing partners around the world.

  • Primary Health Properties Explores Joint Venture for Private Hospital Portfolio (PHP)

    Primary Health Properties Explores Joint Venture for Private Hospital Portfolio (PHP)

    Primary Health Properties (LSE:PHP) has confirmed that it is engaged in advanced discussions with a prospective investment partner regarding the creation of a new joint venture centred on its private hospital portfolio.

    The healthcare-focused real estate investment trust said the proposal forms part of an ongoing strategic review aimed at identifying opportunities to enhance long-term shareholder value and optimise the management of its assets. Under the potential arrangement, PHP would contribute its private hospital holdings as the cornerstone assets of the new venture.

    Management stressed that discussions remain ongoing and that no binding agreement has been reached. Any transaction would remain subject to final negotiations, regulatory and corporate approvals, and the completion of customary due diligence processes.

    The company noted that it continues to assess a range of strategic alternatives as it evaluates the most effective structure for its private hospital assets. The review reflects a broader effort to improve capital allocation, strengthen financing flexibility and unlock additional value from its portfolio.

    If completed, the joint venture could provide PHP with access to additional investment capital while maintaining exposure to the long-term growth potential of the private healthcare market. The move may also create opportunities to accelerate portfolio expansion and support future investment across the healthcare real estate sector.

    Management reiterated that all available options remain under consideration and that there can be no certainty a transaction will ultimately be completed.

    More about Primary Health Properties

    Primary Health Properties plc is a UK-based real estate investment trust specialising in healthcare infrastructure. The company owns and manages a portfolio of healthcare properties across the UK and Europe, including primary care centres, medical facilities and private hospitals. Its strategy focuses on generating long-term, inflation-linked rental income through partnerships with both public and private healthcare providers, positioning the group as a specialist investor in healthcare real estate and social infrastructure assets.

  • Jadestone Expands Malaysian Drilling Programme After Strong Early Well Results (JSE)

    Jadestone Expands Malaysian Drilling Programme After Strong Early Well Results (JSE)

    Jadestone Energy (LSE:JSE) has delivered a successful start to its 2026 infill drilling campaign in Malaysia, with the first well on the PM323 production sharing contract entering production at approximately 3,000 barrels of oil per day. The well was completed around 20% below budget despite being the longest horizontal well drilled to date in the East Belumut field, highlighting the company’s focus on operational efficiency and cost control.

    Encouraged by the performance of the first well and positive subsurface results from the second well in the programme, Jadestone has approved the drilling of a third well. The additional activity will be undertaken without changing the company’s previously announced 2026 capital expenditure guidance of US$50 million to US$80 million.

    The results reinforce Jadestone’s strategy of increasing production from existing assets while maintaining disciplined investment across its portfolio. Management noted that the Malaysian programme is benefiting from supportive Brent crude prices and premium pricing achieved for its Malaysian oil production.

    The campaign follows other operational milestones achieved across the group’s Asia-Pacific portfolio, including progress in Vietnam and the completion of a recent refinancing initiative that strengthened the company’s financial flexibility.

    Jadestone continues to pursue a growth strategy centred on maximising value from mature producing assets through targeted development activity, operational improvements and selective acquisitions. The strong performance of the Malaysian wells demonstrates the company’s ability to enhance production while managing costs, providing improved visibility over near-term cash flow generation.

    Management believes the latest drilling success further strengthens Jadestone’s position as a leading independent upstream producer in the Asia-Pacific region and supports its broader objective of delivering sustainable production growth and long-term shareholder value.

    More about Jadestone Energy

    Jadestone Energy is an independent oil and gas producer focused on the Asia-Pacific region, with producing and development assets across Australia, Malaysia, Indonesia and Vietnam. Headquartered in Singapore, the company specialises in acquiring and optimising mature upstream assets, using operational expertise to increase production, improve efficiency and extend field life. Jadestone is also expanding its gas exposure as part of its long-term strategy and has committed to achieving Net Zero Scope 1 and Scope 2 emissions by 2040.

  • Liontrust Pursues Expansion Through River Global Deal Despite Profit Decline (LIO)

    Liontrust Pursues Expansion Through River Global Deal Despite Profit Decline (LIO)

    Liontrust Asset Management (LSE:LIO) reported lower profitability for the year ended 31 March 2026 as challenging market conditions continued to affect earnings, although the company maintained its commitment to shareholder returns with a full-year dividend of 19 pence per share.

    Gross profit declined to £123 million, while adjusted profit before tax fell to £30.5 million. Despite the reduction in profitability, Liontrust highlighted improving business momentum, with fund flow trends strengthening over the past nine months. Assets under management and advice stood at £21.4 billion as of 19 June 2026, supported by robust institutional inflows, although overall net outflows remained a feature of the year.

    A major strategic development was the receipt of regulatory approval from the Financial Conduct Authority for Liontrust’s acquisition of River Global Holdings. The transaction is expected to complete on 30 June 2026 and will add approximately £3 billion of assets under management to the group.

    Management believes the acquisition will enhance Liontrust’s investment offering by introducing additional multi-style and recovery-focused strategies, while also strengthening the firm’s investment talent and broadening its distribution capabilities. The deal forms part of a wider strategy aimed at accelerating growth through selective acquisitions and expanding the company’s reach across domestic and international markets.

    Alongside the acquisition, Liontrust continues to invest in operational improvements, including the increased use of artificial intelligence and technology to support efficiency, client engagement and business scalability. The company has also reinforced its capital allocation framework through ongoing share buybacks and plans to strengthen board expertise through targeted appointments.

    Management sees the combination of an expanded product range, enhanced distribution capabilities and a more diversified investment platform as key drivers of future growth, while continuing to focus on improving fund flows and building long-term shareholder value.

    More about Liontrust Asset Management

    Liontrust Asset Management is an independent UK-based investment management group specialising in active fund management across a range of asset classes and investment styles. The company serves both retail and institutional clients and has been expanding its international distribution network while investing in technology and AI-driven solutions to improve operational efficiency and client service. Through a combination of organic growth and strategic acquisitions, Liontrust aims to broaden its investment capabilities and strengthen its position within the global asset management industry.

  • Blue Star Investee SatoshiPay Expands Vortex Platform Through Base Migration and New Payment Corridors (BLU)

    Blue Star Investee SatoshiPay Expands Vortex Platform Through Base Migration and New Payment Corridors (BLU)

    Blue Star Capital (LSE:BLU) has provided an update on portfolio company SatoshiPay, highlighting continued progress in the development of its Vortex fiat-to-crypto infrastructure and Pendulum’s decentralised foreign exchange platform.

    A key milestone has been the migration of Pendulum’s FX decentralised exchange and related liquidity pools to the Base blockchain. The move has helped streamline liquidity management for SatoshiPay’s SEPA-to-crypto services while supporting monthly foreign exchange volumes of approximately US$3 million. Pendulum also plans to phase out its Spacewalk bridge, freeing collateral and allowing additional liquidity to be directed into the growing Vortex ecosystem.

    SatoshiPay is simultaneously broadening the commercial reach of Vortex by introducing new fiat-to-crypto payment corridors in Mexico, Argentina, Colombia and the United States through its partnership with Alfredpay. In Europe, the company has relaunched its SEPA ramp with Mykobo, enabling API-based EURC on-ramping and off-ramping capabilities designed to improve accessibility for businesses and financial service providers.

    The company is also investing in the next generation of payment automation tools. Current development work includes programmable transaction workflows, integrations designed for AI-driven agents and pilot programmes that connect traditional banking infrastructure with decentralised finance applications. These initiatives include solutions for direct onboarding into DeFi services and automated stablecoin settlement triggered by conventional bank transfers.

    Management believes these developments strengthen Vortex’s position as a scalable infrastructure platform capable of supporting both traditional payment networks and emerging decentralised finance ecosystems. The strategy is focused on creating institutional-grade solutions that bridge fiat and digital asset markets while expanding the practical use cases for blockchain-based financial services.

    More about Blue Star Capital

    Blue Star Capital is an AIM-listed investment company focused on emerging technology sectors, with particular emphasis on blockchain, payments and digital infrastructure. Its portfolio includes investments in companies such as SatoshiPay, Dynasty Media & Gaming and Paidia, providing exposure to decentralised finance, digital payments, gaming ecosystems and other high-growth technology markets. Through these investments, Blue Star seeks to participate in the development of next-generation financial and digital platforms.