Author: Fiona Craig

  • Cavendish Strengthens Profitability and Expands AI Capabilities to Support Future Growth (CAV)

    Cavendish Strengthens Profitability and Expands AI Capabilities to Support Future Growth (CAV)

    Cavendish (LSE:CAV) delivered modest revenue growth for the year ended 31 March 2026, with revenue increasing to £56.9 million as the investment bank continued to benefit from resilient activity across its public and private market operations. The group reported core profit before tax of £3.5 million and maintained a strong financial position, ending the year debt-free with cash reserves of £19.2 million while holding its dividend steady at 0.8 pence per share.

    Performance was supported by stronger securities income, growth in the average market capitalisation of its client base and stable transaction activity. While retainer and transaction revenues softened during the year, management noted that overall results remained resilient despite a more challenging fee environment and changing deal mix.

    The company continues to invest in expanding its platform, including the recruitment of senior professionals, regional growth initiatives and the wider deployment of data analytics and artificial intelligence technologies across the business. These investments are intended to improve operational efficiency, strengthen client engagement and increase the conversion of relationships into advisory and capital markets mandates.

    Cavendish also reported growth in its quoted client base despite a contracting UK listed company universe, while activity in private markets remained relatively robust even as larger transactions became less frequent. Management believes the group is well positioned to benefit from any recovery in UK small and mid-cap capital markets activity due to its diversified business model and strong balance sheet.

    Looking ahead, the company plans to continue enhancing client quality, deepen collaboration between its public and private markets teams, strengthen its equity distribution capabilities and further integrate AI-driven tools throughout the client lifecycle. Management believes these initiatives will improve scalability, support long-term growth and enhance shareholder value.

    While acknowledging ongoing economic and political uncertainty, Cavendish remains focused on selective investment in origination, distribution and technology, alongside taking advantage of regulatory and policy measures aimed at improving the competitiveness of UK capital markets.

    More about Cavendish

    Cavendish plc is a UK-based investment banking and corporate advisory group specialising in services for ambitious small and mid-cap companies. The firm provides a broad range of capabilities including corporate broking, mergers and acquisitions advisory, capital raising, equity research, sales and trading. Increasingly, the company is incorporating data analytics and artificial intelligence tools into its operations to enhance client insight, business development and transaction execution across both public and private markets.
  • Empire Metals Divests Eclipse Gold Asset to Prioritise Pitfield Titanium Development (EEE)

    Empire Metals Divests Eclipse Gold Asset to Prioritise Pitfield Titanium Development (EEE)

    Empire Metals (LSE:EEE) has completed the sale of its 75% interest in the Eclipse Mining Lease, a non-core gold asset located near Kalgoorlie in Western Australia, for total cash proceeds of A$750,000. The transaction was completed through the company’s Australian subsidiary following the fulfilment of all conditions contained within the previously announced sale agreement.

    The disposal forms part of Empire’s broader strategy to streamline its asset portfolio and direct resources toward projects considered central to its long-term growth plans. Management intends to use the proceeds and management focus generated by the sale to accelerate development activities at the Pitfield Titanium Project, which has become the company’s primary strategic priority.

    By exiting Eclipse and continuing to assess additional non-core assets, Empire is concentrating capital allocation and operational efforts on advancing Pitfield, which it believes has the potential to become a globally significant titanium development project. The company sees increasing demand for critical minerals as a major opportunity and views Pitfield as a key asset capable of benefiting from these long-term market trends.

    Management believes the transaction strengthens the company’s strategic focus while simplifying its project portfolio, allowing greater attention to be directed towards resource expansion, technical studies and future development planning at Pitfield.

    More about Empire Metals

    Empire Metals is an AIM-quoted and OTCQX-traded resource exploration and development company with a primary focus on Western Australia. Its flagship Pitfield Titanium Project hosts a globally significant titanium resource estimated at 2.2 billion tonnes grading 5.1% TiO₂. Test work has demonstrated the potential to produce high-purity titanium products suitable for both titanium metal and pigment markets.

    The mineralisation at Pitfield begins at surface, exhibits strong continuity and currently occupies only a portion of the known mineralised system. Supported by established infrastructure and favourable logistics, the project is positioned to capitalise on growing global demand for titanium and other critical minerals, forming the cornerstone of Empire’s long-term development strategy.

  • Georgina Energy Advances Mt Winter Project with Landmark Land Access Agreement (GEX)

    Georgina Energy Advances Mt Winter Project with Landmark Land Access Agreement (GEX)

    Georgina Energy (LSE:GEX) has reached agreement on an Aboriginal Land Rights Agreement with the Central Land Council, a significant step towards securing exploration permit EP155, which contains the company’s highly prospective Mt Winter helium and hydrogen project in Australia’s Amadeus Basin.

    The agreement will now be presented to Traditional Owners for consideration and approval before being submitted to the Northern Territory Minister, who will determine the formal granting of the exploration permit. Completion of this process would provide Georgina with access to one of its key development assets.

    The Mt Winter prospect is located close to the long-established Mereenie oil and gas field and is believed to host substantial prospective recoverable resources of helium, hydrogen and natural gas. The project forms a central part of Georgina’s strategy to build exposure to markets where long-term demand is expected to grow, particularly for helium and hydrogen.

    Management intends to accelerate plans for the re-entry and development of Mt Winter once permitting is secured. At the same time, the company continues to advance preparatory drilling activities at its Hussar project in Western Australia, creating a parallel development pathway across its two flagship assets.

    The progress at Mt Winter marks an important milestone in Georgina’s efforts to establish a presence in emerging helium and hydrogen supply chains. By advancing both projects simultaneously, the company aims to strengthen its position within sectors that are increasingly viewed as strategically important for industrial applications, energy transition initiatives and advanced technologies.

    More about Georgina Energy

    Georgina Energy plc is a UK-listed energy exploration company focused on the development of helium and hydrogen resources alongside associated hydrocarbon opportunities. Through its wholly owned Australian subsidiary, Westmarket O&G, the company holds interests in the Hussar prospect in Western Australia and is progressing the Mt Winter project in the Amadeus Basin. Its strategy is centred on supplying critical gases that are expected to play an increasingly important role in global energy, industrial and technology markets.

  • Prologis Reveals Rejected £12.6bn Share-Based Approach for SEGRO

    Prologis Reveals Rejected £12.6bn Share-Based Approach for SEGRO

    Prologis (NYSE:PLD) has disclosed that it submitted a preliminary all-share proposal to acquire SEGRO (LSE:SGRO) on 16 June 2026, valuing the UK logistics property group at approximately £12.6 billion. The proposal equated to 925 pence per SEGRO share, representing a premium of around 25% to 31% compared with recent market prices and broadly matching SEGRO’s latest reported EPRA Net Tangible Assets value.

    According to Prologis, SEGRO’s board rejected the proposal on 23 June. Despite the rejection, the global logistics real estate specialist is encouraging SEGRO shareholders to support further discussions, arguing that a combination would provide investors with ownership in a larger, more diversified business. Under the proposed terms, SEGRO shareholders would hold approximately 10.5% of the enlarged group.

    Prologis believes a merger would create one of the leading logistics real estate platforms in Europe, combining two substantial portfolios and generating benefits through greater scale and operational efficiencies. The company also argues that its larger balance sheet and broader access to capital would help accelerate development opportunities across SEGRO’s portfolio.

    Management highlighted what it views as the potential to unlock additional value from SEGRO’s development pipeline, including projects linked to logistics infrastructure, power capacity and data centre opportunities. Prologis contends that its financial resources and global operating platform could help bring these projects to market more efficiently.

    The US-based REIT also pointed to its long-term shareholder return record and capital strength as key advantages, suggesting that a combined business would be better positioned to pursue growth opportunities across major logistics markets.

    While Prologis has made its intentions public, there is currently no certainty that a formal offer will be submitted. Under UK takeover regulations, the company has until 22 July to either announce a firm intention to make an offer or walk away from the process.

    More about Prologis

    Prologis, Inc. is the world’s largest logistics-focused real estate investment trust, with a market capitalisation of approximately $140.9 billion. The company owns, develops and manages industrial and logistics properties across major global markets, serving customers involved in e-commerce, distribution, supply chain management and data infrastructure. Its portfolio spans warehouse, fulfilment and logistics facilities that support global trade and digital economy growth.

  • Light Science Technologies Wins Up to £1.66m of New Fire Safety Business Following Injectaclad Acquisition (LST)

    Light Science Technologies Wins Up to £1.66m of New Fire Safety Business Following Injectaclad Acquisition (LST)

    Light Science Technologies Holdings (LSE:LST) has reported a strong start for its passive fire protection division following the acquisition of RLUK Injection, the owner of the Injectaclad system, in April. The business has secured two installation contracts with a combined value of between £390,000 and £775,000, while also accelerating work on a major remediation project in Hull.

    Since completing the acquisition, the company has also received approximately £885,000 of orders for Injectaclad materials through its network of approved installers. Combined, the new installation and product supply contracts represent between £1.28 million and £1.66 million of additional business, providing early evidence of the commercial benefits expected from the transaction.

    Management believes the performance validates its strategy of creating a vertically integrated passive fire protection business that combines installation services with the supply of proprietary fire remediation products. This model is designed to improve margins, strengthen customer relationships and create additional revenue opportunities across the building safety market.

    The company also expects to benefit from improving conditions within the UK remediation sector as the Building Safety Regulator works through a backlog of project approvals. Growing engagement with industry stakeholders and increasing market awareness of Injectaclad’s cavity fire barrier solutions are contributing to a strengthening pipeline of opportunities.

    Injectaclad technology is designed to enhance fire safety without requiring the full removal of building façades, offering a potentially faster and more cost-effective solution for remediation projects. Management believes demand for such systems will continue to increase as regulatory requirements and building safety standards evolve.

    The group remains focused on securing larger contracts, expanding recurring revenue streams and improving cash generation as it scales its passive fire protection operations.

    More about Light Science Technologies Holdings

    Light Science Technologies Holdings plc operates across three core divisions: passive fire protection, agricultural technology (AgTech) and contract electronics manufacturing (CEM). Through its passive fire protection business, the company supplies and installs Injectaclad fire-resistant systems designed to improve building safety and support remediation projects. Its AgTech division develops technologies for controlled-environment agriculture, while its electronics manufacturing operation provides specialist PCB-based solutions to a range of industrial customers.

  • Berkeley Group Prioritises Cash Generation as It Calls for Reform in London Housing Market (BKG)

    Berkeley Group Prioritises Cash Generation as It Calls for Reform in London Housing Market (BKG)

    Berkeley Group (LSE:BKG) delivered a solid financial performance during the year despite challenging market conditions, reporting pre-tax profit of £451.4 million and increasing its net cash position to £363 million. Net asset value per share climbed 9% to £39.17, while ongoing share buy-back activity continued to return capital to shareholders. However, operating margin eased to 18.7% and forward sales declined, prompting management to place greater emphasis on cash preservation, operational efficiency and maximising value from its existing land portfolio rather than pursuing significant new land acquisitions.

    The housebuilder completed 4,203 homes during the period, with around 90% constructed on brownfield regeneration sites. Berkeley also contributed £530 million towards affordable housing, infrastructure and community investment, underlining its long-standing focus on urban regeneration and sustainable development.

    Management expressed concern over the state of London’s housing market, arguing that a combination of elevated taxation, increasing regulation and lengthy planning and building-safety approval processes is severely restricting new housing supply. The company noted that housing delivery in the capital is currently running at less than 10% of official targets.

    To address these challenges, Berkeley called for measures including reductions in Stamp Duty Land Tax (SDLT), full implementation of the Homes for London programme, faster planning decisions and additional resources for regulatory bodies. The group believes such reforms would help unlock investment, increase housing delivery and support long-term growth across London’s residential property sector.

    Despite near-term market headwinds, management remains focused on maintaining financial discipline while positioning the business to benefit from any improvement in planning conditions and housing supply policies.

    More about Berkeley Group

    The Berkeley Group Holdings plc is one of the UK’s leading residential property developers, with a primary focus on London and the South East of England. The company specialises in large-scale urban regeneration projects and the redevelopment of brownfield land, creating mixed-use communities that incorporate housing, commercial space, infrastructure and public amenities. Berkeley is recognised for its emphasis on sustainable development and its significant contribution to affordable housing delivery in some of the UK’s most supply-constrained markets.

  • Velocity Composites Maintains Positive EBITDA as Cash Position Improves Despite Revenue Decline (VEL)

    Velocity Composites Maintains Positive EBITDA as Cash Position Improves Despite Revenue Decline (VEL)

    Velocity Composites (LSE:VEL) reported first-half revenue of £8.4 million, compared with £10.4 million in the prior year period, as the timing of programme transfers in the United States and customer ordering patterns impacted sales performance. Despite the lower revenue base, the company delivered its third consecutive reporting period of positive adjusted EBITDA, generating £0.1 million during the half year.

    Gross margin remained stable at 28%, demonstrating resilience in the underlying business, although loss before tax increased to £1.0 million. The result was partly affected by exceptional costs associated with the closure of the company’s Fareham facility as part of its ongoing operational restructuring programme.

    Financially, Velocity strengthened its balance sheet, ending the period with net cash of £0.5 million. The company also retained access to a £3.0 million invoice discounting facility, which remained fully undrawn at the reporting date.

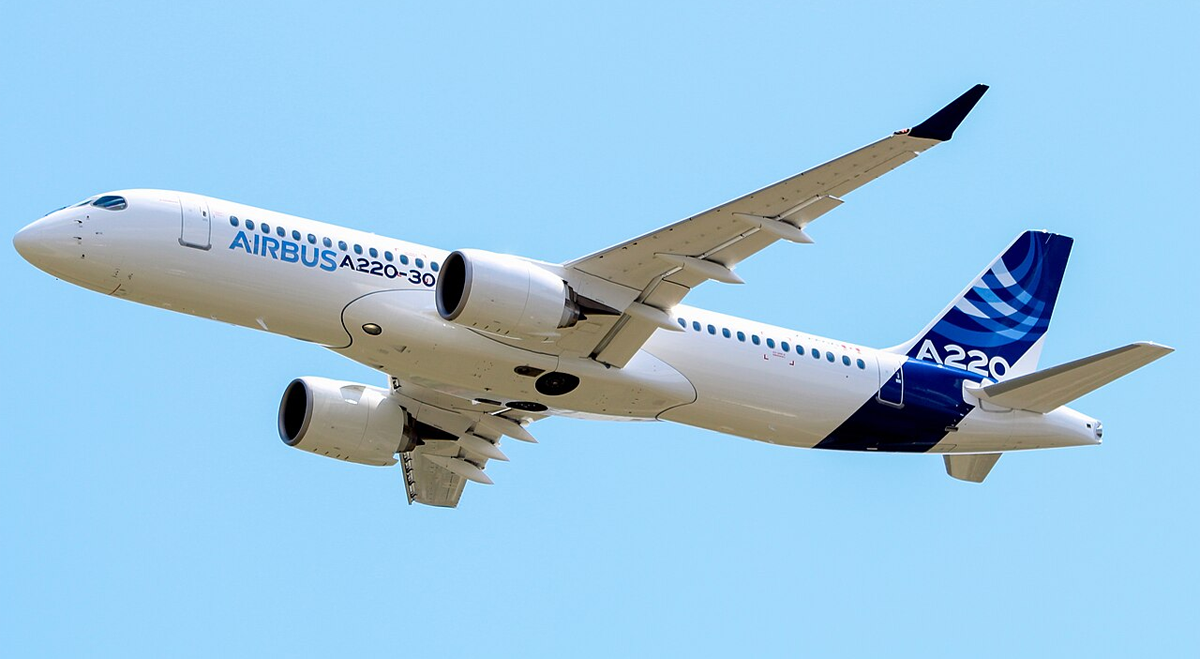
    Operational progress continued across several areas of the business. Additional Airbus A350 programmes have now transitioned into sustained production, while UK operations have been consolidated into the Burnley facility to improve efficiency and reduce overhead costs. The company also reported stronger-than-anticipated demand from established UK customers and secured a number of smaller contract awards during the period.

    Management highlighted improving production rates across major commercial aerospace platforms, including the Airbus A350, Boeing 737 and Boeing 787 programmes, while demand from the US defence sector remains robust. However, the company cautioned that an unfavourable product mix is expected to weigh on second-half margins.

    As a result, Velocity now expects full-year adjusted EBITDA of approximately £0.5 million, with results anticipated to come in below current market forecasts. Nevertheless, management remains confident in the longer-term outlook as the company continues to expand its presence in the US market and pursue opportunities within the growing defence sector.

    More about Velocity Composites

    Velocity Composites plc is a UK-based supplier of advanced composite material kits and logistics solutions for the aerospace industry. Working with major manufacturers including Airbus, Boeing and GKN, the company helps customers improve manufacturing efficiency, reduce material waste and lower production costs through its proprietary technologies and services. In addition to aerospace, Velocity is exploring growth opportunities in sectors such as defence, wind energy, urban air mobility and electric vehicles.

  • Vertu Motors Upgrades FY27 Expectations as Trading Momentum and Network Changes Support Growth (VTU)

    Vertu Motors Upgrades FY27 Expectations as Trading Momentum and Network Changes Support Growth (VTU)

    Vertu Motors (LSE:VTU) has raised its outlook for FY27 after delivering positive trading across multiple areas of its business during the three months to 31 May 2026. The automotive retailer reported like-for-like volume growth in new vehicle retail sales, Motability, used vehicles, and fleet and commercial operations, highlighting the continued strength of its diversified model.

    The group also reported year-on-year profit growth within its aftersales division, with stable margins and disciplined cost management helping to support overall performance despite ongoing challenges across the wider automotive sector.

    As part of its strategic development plans, Vertu continues to optimise and reposition its dealership portfolio. The company is preparing to open its first Omoda and Jaecoo dealership in Burton on 1 July 2026 and plans to convert an additional site to represent the two Chinese automotive brands later in the year. Following these changes, Vertu will operate 15 outlets representing Chinese vehicle manufacturers, increasing its exposure to one of the fastest-growing segments of the market.

    The group is also pursuing operational efficiencies through selective site restructuring. One example is the relocation of its Sheffield Mazda dealership into a larger multi-franchise facility, a move expected to generate cost savings and improve operational effectiveness.

    Supported by stronger trading and the benefits of its portfolio initiatives, the board now expects FY27 financial performance to exceed current market forecasts. Management believes the combination of growing sales volumes, expanding brand partnerships and ongoing efficiency measures will strengthen the company’s competitive position while enhancing profitability.

    More about Vertu Motors

    Vertu Motors is one of the UK’s largest automotive retail groups, operating 191 sales and aftersales locations nationwide. Established in 2006, the company has grown through a combination of acquisitions and organic expansion, building a broad dealership network representing multiple vehicle manufacturers. Its strategy focuses on operational excellence, customer service and long-term growth through both portfolio development and efficiency improvements.

  • Haydale Accelerates Clean-Tech Transformation Following SaveMoneyCutCarbon Acquisition (HAYD)

    Haydale Accelerates Clean-Tech Transformation Following SaveMoneyCutCarbon Acquisition (HAYD)

    Haydale (LSE:HAYD) delivered a significant increase in revenue during the first half of FY26 as the acquisition of SaveMoneyCutCarbon (SMCC) reshaped the business and accelerated its transition towards clean technology and sustainability-focused solutions. Revenue rose 463% to £2.25 million, while net assets increased to £14.64 million, reflecting the addition of goodwill and intangible assets associated with the acquisition.

    The enlarged group is investing in the integration and development of its expanded platform, with management targeting positive EBITDA within approximately twelve months of completing the transaction. While the inclusion of SMCC’s delivery and service activities has reduced overall margins, the company believes the broader business model provides a stronger foundation for long-term growth. Adjusted operating losses increased during the period as investment continued across the platform.

    Haydale has now completed its strategic repositioning toward technologies aimed at improving energy efficiency, water management and carbon reduction across commercial and residential buildings. Key growth initiatives include the JustHeat heating platform and the development of graphene-enhanced thermal transfer fluids designed for use in data centres and industrial cooling applications.

    The acquisition of SMCC has also expanded Haydale’s operational capabilities, providing access to a nationwide delivery network, a growing base of Impact Partners and new commercial agreements across water efficiency and electric mobility markets. Management believes these additions strengthen the company’s ability to generate recurring revenues while accelerating the adoption of its proprietary technologies in infrastructure and building-performance applications.

    The group sees substantial opportunities to scale its clean-technology offering as organisations increasingly focus on reducing energy consumption, improving sustainability performance and meeting environmental targets.

    More about Haydale Graphene

    Haydale plc is an advanced materials and clean-technology company focused on delivering solutions that improve energy efficiency, water usage and carbon performance. Through its proprietary HDPlas technology platform and the capabilities gained through SaveMoneyCutCarbon, the company develops and commercialises graphene-enabled products while providing nationwide implementation and delivery services. Its strategy is centred on helping organisations improve building performance and sustainability outcomes across a wide range of sectors.

  • Kodal Minerals Retains Bougouni Expertise as Long-Serving Director Moves to Advisory Role (KOD)

    Kodal Minerals Retains Bougouni Expertise as Long-Serving Director Moves to Advisory Role (KOD)

    Kodal Minerals (LSE:KOD) has announced that non-executive director Steve Zaninovich will retire from the board following the company’s annual general meeting on 24 June 2026, marking the end of a tenure that spanned the development of the Bougouni Lithium Project from exploration through to production.

    While stepping down from his board position, Zaninovich will remain closely involved with the business through a consultancy role. In this capacity, he will continue supporting operations at the Bougouni mine and provide advice on future development and growth initiatives, helping to ensure continuity as the project progresses through its next phase.

    The company highlighted Zaninovich’s significant contribution to Bougouni’s advancement, including his involvement in the project’s feasibility studies, financing arrangements and construction programme. His experience has been instrumental in transforming Bougouni into a producing lithium operation.

    Chairman Robert Wooldridge acknowledged the importance of Zaninovich’s role in the mine’s development and welcomed his continued involvement as an adviser. The move allows Kodal to retain valuable technical and strategic expertise while potentially creating scope for future changes to the board’s composition.

    Management believes the transition provides stability as Bougouni continues to ramp up production and strengthen its position within the growing West African lithium industry.

    More about Kodal Minerals

    Kodal Minerals is an AIM-listed mining company focused on lithium exploration, development and production in West Africa, alongside a portfolio of early-stage gold interests. Its flagship Bougouni Lithium Project in southern Mali, developed in partnership with Hainan Mining, entered production in 2025 and currently produces spodumene concentrate. The company is also evaluating a planned second-stage flotation plant designed to process finer-grained lithium resources and enhance the project’s long-term production profile.