Author: Fiona Craig

  • Seraphim Space Investment Trust invests further into Xona Space Systems as Next Generation Infrastructure expands

    Seraphim Space Investment Trust invests further into Xona Space Systems as Next Generation Infrastructure expands

    Seraphim Space Investment Trust (LSE:SSIT) has increased its investment in Xona Space Systems, making the company its second-largest portfolio holding after ICEYE. Xona is developing next-generation satellite navigation technology designed to deliver greater accuracy, security and resilience as demand for reliable positioning data continues to grow.

    The global space economy is evolving beyond traditional launch services and satellite communications into a broader range of critical infrastructure applications. Defence and national security, autonomous vehicles, robotics and industrial automation are among the sectors increasingly reliant on advanced space technology.

    For Seraphim Space Investment Trust, Xona represents an opportunity to gain exposure to a business developing technology with potential applications across multiple large and expanding markets.

    Xona Becomes a Major Portfolio Holding

    Following SSIT’s latest investment, its existing holding in Xona was valued at $106 million, equivalent to approximately £80.6 million at the exchange rate used for the valuation. A further $15 million investment through SSIT’s C share class brought the combined holding to $121 million, or approximately £91.9 million on the same basis.

    This makes Xona SSIT’s second-largest portfolio company, highlighting the growing importance of positioning, navigation and timing technology within the global space economy.

    Satellite navigation underpins a wide range of modern applications, from everyday transport and logistics to advanced industrial systems and defence capabilities. However, conventional GPS typically provides accuracy within approximately one to 10 metres, depending on conditions, and can be vulnerable to interference and spoofing.

    These limitations create demand for alternative technologies capable of delivering greater precision and resilience, particularly in applications where dependable positioning information is essential.

    Xona is developing a low Earth orbit satellite constellation designed to deliver centimetre-level positioning accuracy alongside enhanced resilience. Its technology aims to address the requirements of markets where increasingly sophisticated systems depend on precise, secure and reliable navigation.

    Potential applications include autonomous vehicles, drones, robotics, defence modernisation, advanced mobility and industrial automation. As these technologies develop, accurate positioning data is becoming an increasingly important component of the infrastructure supporting them.

    For SSIT, Xona illustrates the potential of investing in space technology businesses whose capabilities can serve several substantial markets rather than relying on a single application.

    Seraphim’s Investment Approach Supports Long-Term Growth

    Xona also demonstrates Seraphim’s approach to identifying promising space technology companies and supporting their development as they mature.

    Seraphim identified Xona at an early stage, supported the business through its accelerator programme and subsequently provided funding through its private space venture funds. As Xona progressed and reached a more advanced stage of development, Seraphim began investing through SSIT.

    This approach enables Seraphim to build familiarity with businesses as they develop, with the objective of gaining exposure to companies that have demonstrated their technical capabilities and are increasingly focused on commercial growth.

    SSIT’s investment strategy provides exposure to space technology companies at different stages of development, with an emphasis on businesses that Seraphim believes can address substantial market opportunities.

    The progression of Xona highlights how early engagement and continued investment can provide exposure to companies developing technologies with the potential to become increasingly important to the wider economy.

    C Share Portfolio Targets Mission-Critical Technologies

    Beyond Xona, Seraphim continues to identify opportunities across an expanding space technology market.

    Key areas of interest include defence and national security, resilient communications, positioning and navigation, Earth observation, climate intelligence and autonomous systems.

    These markets reflect the growing recognition that space technology is no longer simply experimental or supplementary. Increasingly, it is becoming essential infrastructure for governments, businesses and critical industries.

    SSIT is concentrating on later-stage, higher-growth companies that have demonstrated their technical capabilities and reduced much of their underlying technology risk. The focus is on businesses with the potential to translate technological progress into commercial traction and expansion.

    Xona provides an example of this opportunity, combining a significant potential addressable market with technology designed to support several major growth trends.

    As demand for resilient infrastructure increases, companies capable of delivering practical solutions across multiple applications could play an important role in the next phase of space sector development.

    Continued Investment Across the Space Economy

    SSIT’s C share portfolio is playing an important role in expanding the trust’s exposure to emerging opportunities.

    Since May, SSIT has made significant investments through its C share class, with further capital deployment expected over the following quarter.

    The emphasis remains on businesses considered strategically important, with growth potential and the ability to establish positions within the global space economy.

    Governments and businesses are increasingly focused on improving resilience across navigation, communications and national security. At the same time, advances in autonomous systems, Earth observation and other space-enabled technologies are creating new commercial applications.

    This combination of technological development and growing demand is broadening the range of potential investment opportunities across the sector.

    For SSIT, continued capital deployment provides an opportunity to back businesses developing technologies that could become increasingly important to the global economy.

    Positioning for the Next Phase of Space Technology

    The developments at Xona highlight the expanding role of space infrastructure in everyday life and critical economic activity.

    With SSIT’s combined Xona holding valued at $121 million following the latest investment, the trust has established a substantial position in a company developing technology for more precise and secure satellite navigation.

    Alongside this investment, the continued deployment of capital through SSIT’s C share portfolio reflects the trust’s ambition to identify and support the next generation of space technology businesses.

    As the sector expands across defence, autonomous systems, communications and Earth observation, SSIT is seeking to provide investors with exposure to companies developing technologies that could help shape the future of the global space economy.

    For more information about Seraphim Space Investment Trust and its portfolio, visit https://investors.seraphim.vc/.
  • MAX Power Strengthens Leadership as Natural Hydrogen Commercialisation Moves into Focus

    MAX Power Strengthens Leadership as Natural Hydrogen Commercialisation Moves into Focus

    MAX Power Mining Corp. (CSE:MAXX), (USOTC:MAXXF) (FSE:89N) is strengthening its leadership team as it prepares for a pivotal phase of natural hydrogen testing at its Lawson discovery in Saskatchewan. With a large-scale geological system identified, independent technical modelling underway, a proprietary AI-assisted exploration platform in development and US capital markets opportunities under evaluation, the company is advancing its strategy to assess the commercial potential of natural hydrogen.

    MAX Power is entering a significant new chapter in its development, appointing former Saskatchewan cabinet minister Rob Norris as Chief Executive Officer as it moves towards the next stage of technical evaluation and potential commercialisation.

    The appointment comes as the company prepares to begin completions testing at its Lawson and Bracken discoveries in the second half of October 2026. The programme is intended to provide important information about the characteristics and potential commercial viability of the natural hydrogen systems identified through drilling.

    Alongside the technical work, MAX Power is advancing its proprietary MAXX LEMI exploration platform, evaluating a potential US stock exchange listing and exploring strategic partnerships to support further development.

    The company’s wider proposition combines a substantial permitted land position, a confirmed subsurface natural hydrogen system, associated helium potential and a technology-led approach to identifying additional exploration targets.

    Experienced Leadership for the Next Phase

    Rob Norris brings experience in government, energy policy, innovation and international partnerships to his new role. A former Saskatchewan cabinet minister, he has held responsibilities spanning SaskPower, innovation, advanced education and employment, giving him relevant experience as MAX Power seeks to develop its natural hydrogen opportunity within the province.

    Norris has served on the company’s board since June 2025. His appointment as CEO follows Ran Narayanasamy’s transition to the newly created position of Managing Director, Innovation and International Strategy.

    The move allows MAX Power to maintain continuity in its technical and strategic development while placing increased emphasis on commercialisation, partnerships and capital markets.

    The company has also strengthened its technical leadership with the appointments of Tom Kishchuk as Chief Technology Officer and Dr Brendan Bishop as Chief Geochemist.

    Kishchuk brings more than 30 years of technical and business leadership experience, while Bishop contributes specialist expertise in geochemistry and hydrogen and helium isotopes.

    Together, the appointments strengthen the team’s commercial, technical and scientific capabilities as MAX Power prepares to evaluate the next stage of its discoveries.

    Lawson: From Discovery Towards Commercial Evaluation

    MAX Power’s flagship Lawson project represents the central focus of its natural hydrogen strategy.

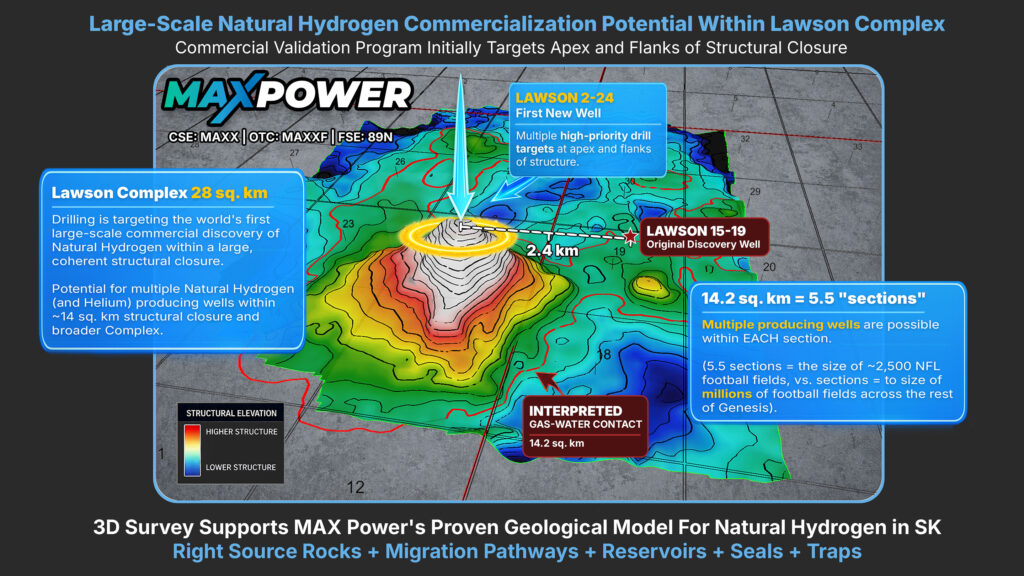
    The company has confirmed a subsurface natural hydrogen system through deep drilling, with data validated by three independent laboratories. Subsequent three-dimensional seismic work has helped define the underlying geological structure, providing a framework for follow-up drilling and further assessment.

    According to the company’s IBN profile, seismic interpretation has identified a 14.2-square-kilometre structural closure within a broader 28-square-kilometre system.

    These findings provide a more detailed geological picture of the opportunity, moving the project beyond an isolated drilling result towards the evaluation of a larger subsurface system.

    The next important milestone is completions testing, which is expected to help establish how the system performs under test conditions. Key considerations include hydrogen concentrations, flow rates, reservoir characteristics and deliverability.

    The results will be important in assessing whether Lawson could support commercially viable production.

    MAX Power has also reported significant natural hydrogen readings from its third and fourth Lawson wells, with the drilling programme aimed at understanding the scale and continuity of the system.

    The company has engaged GLJ Ltd., an independent energy consulting firm, to undertake reservoir characterisation, modelling and development scenario analysis. This work is intended to help assess the broader Lawson Complex’s resource potential and provide a stronger technical foundation for future development decisions.

    While commercial production has not yet been established, the combination of drilling, seismic interpretation and independent technical analysis represents an important stage in evaluating the discovery.

    A 475-Kilometre Exploration Trend Creates Further Potential

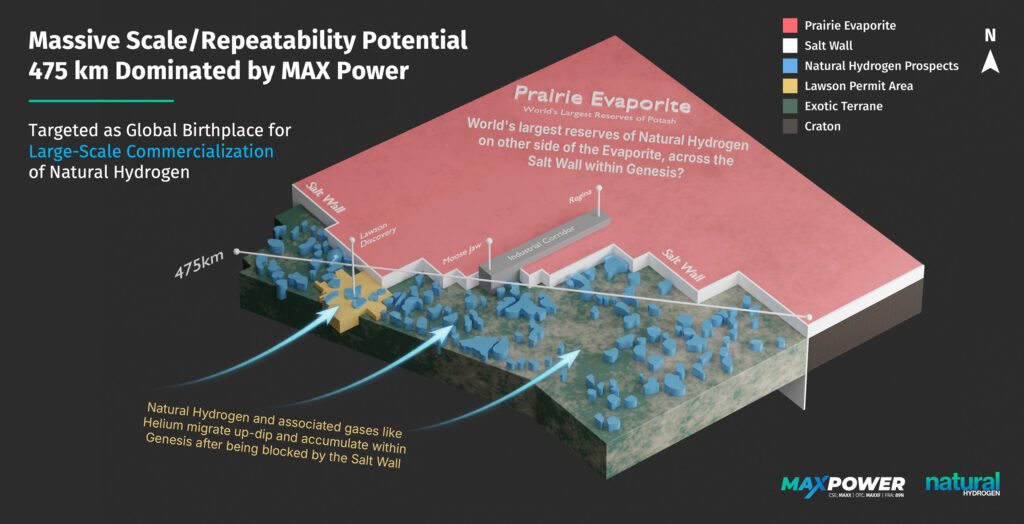
    Beyond Lawson itself, MAX Power is investigating the potential of the broader Genesis Trend, a geological corridor extending approximately 475 kilometres through Saskatchewan towards North Dakota.

    The company’s permitted land position has expanded to approximately 2.5 million acres, giving it a substantial area in which to investigate additional natural hydrogen targets.

    The wider exploration strategy is based on determining whether geological features identified at Lawson can be recognised elsewhere along the trend and across other parts of the company’s acreage.

    One important element is the Bracken target, located approximately 325 kilometres southwest of Lawson. Drilling at Bracken has identified multiple prospective natural hydrogen and helium zones, with further completions and testing planned.

    Investigating both Lawson and Bracken provides an opportunity to assess natural hydrogen systems in different geological settings and determine whether the wider Saskatchewan land position could host additional discoveries.

    MAX Power is also evaluating other targets, including Lawson South, as it continues to build its understanding of the region’s geology.

    The potential significance is that successful follow-up work could expand the company’s opportunity beyond a single discovery. However, the scale, continuity and commercial viability of any additional accumulations will need to be established through further technical work.

    Natural Hydrogen and the Emerging Energy Opportunity

    Natural hydrogen is attracting increasing interest as energy users explore alternative sources of lower-emission energy for industrial applications and infrastructure.

    Unlike manufactured hydrogen, which requires an industrial production process, natural hydrogen is generated through geological processes and may accumulate within the subsurface. If it can be discovered, extracted and delivered economically, it could offer an alternative source of energy for selected applications.

    The potential economics are a key part of the industry’s appeal. Natural hydrogen could avoid some of the energy-intensive production requirements associated with manufactured hydrogen, although actual costs will depend on geology, extraction, processing, infrastructure and other project-specific factors.

    MAX Power’s Lawson discovery is strategically positioned near Saskatchewan’s industrial corridor, where existing industrial activity and proposed hydrogen infrastructure could provide potential future demand.

    The region is also attracting interest in energy-intensive infrastructure, including proposed AI and data-centre developments. Such projects could increase the importance of reliable energy supplies, although any future supply relationship involving MAX Power would depend on successful technical validation, commercial arrangements and the development of suitable infrastructure.

    For MAX Power, the immediate priority remains demonstrating the performance of its natural hydrogen systems. Establishing commercially viable production would be a critical step towards turning the broader energy opportunity into a development proposition.

    MAXX LEMI: Applying AI to Natural Hydrogen Exploration

    A further differentiator is MAX Power’s proprietary MAXX LEMI platform, an AI-assisted geological exploration framework designed to integrate seismic information, drilling results, structural interpretation and historical subsurface datasets.

    The objective is to improve the identification and assessment of potential drilling targets by bringing multiple sources of geological information into a unified analytical framework.

    This approach could support the company’s exploration strategy by helping refine target selection, improve understanding of subsurface structures and assess similarities between known discoveries and prospective areas.

    MAX Power has engaged global technology services provider Kyndryl to develop a commercialisation strategy and go-to-market plan for the platform.

    The potential applications extend beyond the company’s own acreage. If the technology proves effective, MAXX LEMI could potentially have applications across other natural hydrogen exploration districts, creating opportunities for partnerships, licensing or broader commercial adoption.

    The platform was also recognised as a runner-up in the Digital Innovator category at the 2026 Canadian Hydrogen Convention in Edmonton, according to the IBN company profile.

    That recognition provides additional visibility for the technology as MAX Power explores how data-led targeting could contribute to a developing natural hydrogen industry.

    The commercial opportunity remains to be demonstrated, but the platform adds a technology dimension to the company’s exploration strategy.

    A Second Asset in Critical Minerals

    MAX Power also holds a portfolio of critical minerals properties, including the Willcox Playa Lithium Project in southeast Arizona.

    The company’s US subsidiary owns the project, where earlier diamond drilling identified lithium-rich clays over a broad area.

    The asset provides exposure to a separate sector linked to battery materials and US critical minerals supply chains.

    MAX Power is considering a proposed spinout of its critical minerals portfolio. If progressed, such a transaction could allow the company to sharpen its strategic focus on natural hydrogen while giving the separate assets a more dedicated development pathway.

    Any potential spinout, its structure and its implications for shareholders would depend on the company’s plans and the relevant approvals and conditions.

    The portfolio nevertheless represents an additional component of MAX Power’s asset base as it works to define its longer-term priorities.

    Expanding Investor Reach and US Market Opportunities

    Alongside its operational programme, MAX Power is evaluating a potential dual listing on a US stock exchange.

    The objective would be to broaden the company’s investor base, improve visibility among US investors and potentially increase trading liquidity. Any listing would remain subject to exchange requirements, regulatory considerations and the company’s final decision.

    The company has also entered into a syndicated communications agreement with InvestorBrandNetwork (IBN), effective 9 October 2026 for an initial 90-day period ending 7 January 2027.

    The agreement is valued at US$500,000, payable in cash from working capital. The services include content creation and syndication, press release enhancement, recap-style coverage, a CEO podcast interview, social media support and monthly reporting.

    The campaign is intended to raise awareness of MAX Power among investors as it progresses its natural hydrogen programme and evaluates capital markets opportunities. It is an investor communications initiative rather than evidence of technical progress or commercial validation, and the associated expenditure is a relevant consideration for shareholders.

    Taken together, the company’s investor outreach and potential US listing form part of a broader effort to increase market awareness as the operational programme advances.

    The Next Milestones

    MAX Power’s latest leadership changes reflect a shift in emphasis towards commercial evaluation, with Lawson completions testing expected to provide an important next set of technical information.

    The company is also progressing work at Bracken, assessing the wider Genesis Trend, developing its MAXX LEMI platform and considering how its capital markets strategy can support its ambitions.

    The combination of a confirmed natural hydrogen system, a substantial permitted land position, associated helium potential and additional exploration targets gives MAX Power several avenues through which to pursue its strategy.

    The key test now is whether the upcoming work can demonstrate the technical performance and commercial characteristics required to advance Lawson towards potential development.

    For investors following the emerging natural hydrogen sector, the coming months could be important in determining how the company’s exploration results translate into a clearer picture of resource potential and possible commercial applications.

    With a strengthened leadership team and several technical and corporate initiatives progressing in parallel, MAX Power is positioning itself for the next phase of its natural hydrogen journey.

    The opportunity remains at the exploration and evaluation stage, and commercial production has not yet been established. Future progress will depend on testing results, technical assessments, financing, infrastructure and the ability to develop commercially viable projects.

  • UBS Downgrades Greggs to Neutral After 26% Share Price Rally, Maintains 2,200p Target

    UBS Downgrades Greggs to Neutral After 26% Share Price Rally, Maintains 2,200p Target

    UBS has downgraded British bakery chain Greggs PLC (LSE:GRG) from Buy to Neutral, citing valuation concerns following a 26% increase in the company’s share price since the beginning of 2026.

    The investment bank maintained its price target of 2,200 pence, indicating that its revised recommendation reflects the stock’s valuation rather than a deterioration in its earnings outlook.

    According to UBS, Greggs’ recent share price performance has already incorporated much of the improvement in its trading prospects, including stronger third-quarter sales growth, cost-saving initiatives and an upgraded profit outlook.

    The downgrade comes despite continued progress in the company’s operational performance and its longer-term expansion strategy.

    Greggs Valuation Returns to Historical Levels

    UBS highlighted the bakery chain’s valuation as the principal reason for changing its investment recommendation.

    Following the 26% year-to-date share price increase, Greggs trades at approximately 17 times estimated earnings for fiscal 2026.

    This compares with the company’s long-term average price-to-earnings multiple of around 16 times, excluding the periods affected by the COVID-19 pandemic.

    At the beginning of 2026, the stock traded at approximately 14 times forward earnings.

    UBS said the subsequent increase in the valuation multiple largely reflects growing confidence in Greggs’ business outlook.

    The bank believes that the improvement in investor expectations is now substantially reflected in the share price, reducing the potential for further valuation-driven gains.

    Although the recommendation has been lowered, UBS has not changed its earnings forecasts for the company.

    Third-Quarter Sales Growth Supported by Higher Volumes

    Greggs reported an acceleration in like-for-like sales growth during the third quarter, supported by improvements in customer volumes.

    The stronger performance addressed one of the main concerns previously raised by investors about the bakery chain’s trading momentum.

    Like-for-like sales measure revenue growth at comparable existing locations, providing an indication of underlying business performance without the contribution from newly opened stores.

    For Greggs, the improvement suggests that customer demand strengthened during the quarter.

    The company also upgraded its profit outlook, supported by a combination of sales performance, menu innovation and continued operational discipline.

    UBS acknowledged these developments as positive factors but indicated that the market had already responded to the improving trading environment.

    The bank’s decision to move to Neutral therefore reflects a reassessment of the balance between the company’s operating prospects and its current valuation.

    Cost Savings Remain Central to Profitability Plans

    Greggs continues to focus on controlling operating expenditure and improving efficiency across its business.

    The company is targeting £11 million in cost savings during fiscal 2026, compared with £13 million achieved or targeted for fiscal 2025, according to the figures cited by UBS.

    These initiatives form part of the bakery chain’s efforts to support profitability while continuing to invest in its store network and manufacturing infrastructure.

    Menu innovation is another component of the strategy, with the company seeking to maintain customer interest and support sales growth through product development.

    UBS identified these operational measures as contributors to the company’s improved earnings outlook.

    However, the bank did not revise its existing earnings estimates following its latest assessment.

    Manufacturing Consolidation Expected to Deliver £20 Million in Savings

    Greggs is also pursuing longer-term efficiency improvements through the consolidation of its manufacturing operations.

    The company expects the programme to generate approximately £20 million in annualised savings across fiscal 2028 and 2029.

    Manufacturing consolidation is intended to improve the efficiency of the production network and support the bakery chain’s wider operational requirements.

    The projected savings could provide an additional contribution to profitability as the programme progresses.

    However, the anticipated benefits remain subject to successful implementation and the company’s ability to achieve the targeted efficiencies.

    The savings programme forms part of Greggs’ broader strategy to strengthen its cost structure while expanding its national presence.

    Greggs Maintains Long-Term Target of 3,500 Stores

    Alongside its cost-reduction initiatives, Greggs continues to identify opportunities to expand its retail network.

    The company maintains a long-term ambition of operating approximately 3,500 stores across the UK.

    This target represents a potential opportunity for further growth through new store openings and an expanded customer base.

    The strategy is supported by investment in manufacturing capacity, distribution infrastructure and operational efficiency.

    UBS continues to recognise the company’s expansion potential, although its revised rating suggests that the current share price already reflects a significant portion of the expected improvement.

    The investment bank did not identify any change to Greggs’ long-term store opportunity in its latest assessment.

    Investor Positioning Becomes More Balanced

    UBS also pointed to changes in investor positioning as a factor in its revised view of the stock.

    The bank said positioning in Greggs shares is now broadly neutral, while short interest has declined from previously elevated levels.

    Short selling involves investors taking positions that may benefit if a company’s share price falls.

    A reduction in short interest can indicate that fewer investors are positioning for a decline in the stock.

    However, it can also mean there is less potential for additional buying pressure from investors closing bearish positions.

    UBS indicated that the change in positioning, alongside the share price rally and higher valuation, has reduced the attractiveness of the stock at current levels.

    UBS Maintains Earnings Forecasts Despite Rating Change

    The downgrade to Neutral does not reflect a reduction in UBS’s expectations for Greggs’ financial performance.

    The bank retained its existing earnings estimates and maintained its 2,200p price target.

    Its assessment acknowledges the company’s improving sales momentum, upgraded profit outlook, operational savings and long-term expansion plans.

    However, with the shares having gained 26% since the start of the year and the valuation returning to approximately its historical average, UBS believes the investment case is now more balanced.

    For investors, the key developments to monitor will include the sustainability of like-for-like sales growth, delivery of planned cost savings and progress towards the company’s long-term store expansion target.

    The latest rating change highlights the distinction between an improving business outlook and the valuation investors are being asked to pay for that growth.

  • NatWest Shares Rise 3.3% as Barclays Upgrades Rating and Lifts Price Target to 850p

    NatWest Shares Rise 3.3% as Barclays Upgrades Rating and Lifts Price Target to 850p

    NatWest (LSE:NWG) shares advanced on Tuesday after Barclays upgraded the UK banking group to “overweight” from “equal weight” and increased its price target, citing stronger earnings prospects supported by higher interest rates, business expansion and potential benefits from the acquisition of Evelyn.

    The shares gained 3.3% to 675.20p in London trading, outperforming the FTSE 100, which rose approximately 0.7%.

    Barclays raised its price target for NatWest to 850p from 740p, an increase of nearly 15%. The revised target represents potential upside of approximately 26% from the quoted share price.

    Higher Interest Rates Expected to Support Earnings

    Barclays identified NatWest as a potential beneficiary of higher UK interest rates and a steeper yield curve, which could improve the bank’s revenue and profitability over the coming years.

    The analysts increased their long-term Bank Rate assumption by 50 basis points to 4.25%, estimating that the change could lift NatWest’s earnings per share by approximately 5% in 2028.

    The positive effect could eventually reach 10% as the bank’s structural hedge matures and higher interest rates are progressively reflected in returns.

    Barclays also increased its earnings-per-share forecasts by as much as 7% across 2026 to 2028, primarily reflecting expectations of stronger revenue generation.

    However, the analysts acknowledged that increased competition for customer deposits could partially offset the benefits of higher interest rates.

    Despite this risk, Barclays does not anticipate a repeat of the significant shift towards more expensive deposit products experienced in 2023.

    The bank suggested that households may be approaching the point at which further transfers of savings into higher-cost fixed-term deposits become less likely, potentially limiting additional pressure on NatWest’s funding costs.

    Evelyn Acquisition Offers Additional Revenue Opportunities

    Barclays also highlighted potential earnings benefits from NatWest’s integration of Evelyn, the wealth management business acquired by the lender.

    According to the analysts, the integration is progressing positively and could create opportunities to expand relationships with existing wealth management clients.

    In particular, NatWest may be able to offer additional banking products and services to Evelyn customers, supporting revenue growth across the combined business.

    Barclays suggested that these cross-selling opportunities could allow NatWest to generate revenue synergies above its existing expectations over time.

    The acquisition represents another potential source of earnings growth alongside the bank’s core lending and deposit operations.

    UK Banking Tax Risks Remain Ahead of Budget

    While Barclays adopted a more positive outlook for NatWest, it acknowledged uncertainty surrounding possible changes to UK banking taxation ahead of the forthcoming Budget.

    Any increase in taxes affecting the banking sector could create additional costs and place pressure on profitability.

    However, Barclays expects the potential financial impact to remain manageable.

    The analysts also suggested that much of the uncertainty surrounding possible tax changes is already reflected in NatWest’s current share price.

    As a result, Barclays considers the bank’s valuation relatively attractive despite the outstanding policy risks.

    Valuation Discount Supports Barclays’ Positive Outlook

    Barclays pointed to NatWest’s valuation discount relative to European banking peers as another reason for its upgraded recommendation.

    The analysts argued that the combination of stronger earnings forecasts, potential benefits from higher interest rates and additional revenue opportunities from Evelyn was not fully reflected in the lender’s market valuation.

    The revised 850p price target incorporates Barclays’ more favourable expectations for NatWest’s earnings performance and longer-term growth prospects.

    Although deposit competition and potential tax changes remain risks, Barclays considers the bank well positioned to benefit from its existing operations and wealth management expansion.

    Tuesday’s share price increase reflected a positive market response to the upgrade, with NatWest outperforming the broader London equity market.

  • European Luxury Shares Decline as LVMH Fashion Sales Miss Expectations

    European Luxury Shares Decline as LVMH Fashion Sales Miss Expectations

    European luxury stocks moved lower on Tuesday after LVMH (EU:MC) reported a sharper-than-expected decline in sales at its fashion and leather goods division, raising concerns about the pace of recovery in the luxury goods sector, particularly in China.

    By 09:09 GMT, LVMH shares had fallen 1.6%, while Hermès (EU:RMS) declined 2.4% and Kering (EU:KER) lost 2%. Moncler (BIT:MONC) dropped 1.5%, Dior (EU:CDI) retreated 1.4% and Richemont (TG:RITN) weakened 1.1%.

    The broad decline followed LVMH’s third-quarter trading update, which highlighted continued pressure on demand for Louis Vuitton products in China and slower growth in its watches and jewellery business.

    LVMH Fashion Division Records Larger-Than-Expected Sales Decline

    LVMH reported a 5% organic decline in sales at its fashion and leather goods division, compared with the 1.8% contraction expected by analysts surveyed by Visible Alpha.

    The division, which accounts for nearly half of the group’s revenue, includes Louis Vuitton and other major luxury fashion brands.

    The company attributed part of the weakness to a “less favourable trading environment” in China, where demand for high-end products has remained subdued.

    Group organic revenue increased 1% in the third quarter to €18.5 billion ($20.68 billion), excluding currency movements. The result was below market expectations for growth of 1.3%.

    For the first nine months of the year, LVMH generated revenue of €57.1 billion, representing a reported decline of 2% but organic growth of 2%.

    The difference between reported and organic performance reflected the impact of currency movements and other adjustments included in the company’s organic growth measure.

    The weaker fashion performance renewed concerns about the ability of European luxury companies to restore growth following an extended period of slower consumer spending.

    Louis Vuitton Recovery Expected to Take Time

    LVMH’s management indicated that an improvement in demand for Louis Vuitton products may be gradual rather than immediate.

    Asked about the brand’s recovery prospects, Chief Financial Officer Cécile Cabanis said: “Recovery takes time, and I do not believe there are many shortcuts.”

    Her comments suggested that the company does not expect a rapid improvement in trading conditions.

    The outlook for Louis Vuitton is particularly important because the brand is a major contributor to LVMH’s fashion and leather goods division.

    Weakness in Chinese consumer spending has remained a significant challenge for luxury manufacturers, with the country’s demand influencing the performance of leading European brands.

    The latest figures indicated that the sector’s recovery remains uneven, despite stronger results in some other business categories.

    Watches and Jewellery Growth Slows

    LVMH’s watches and jewellery division, which includes Bulgari and Tiffany, also recorded slower growth during the third quarter.

    Organic sales increased 6%, compared with growth of 9% during the first half of the year.

    The moderation was notable because watches and jewellery had been among the stronger categories within the luxury market.

    Although the division continued to expand, the slowdown suggested that demand conditions were becoming less supportive across additional product segments.

    The result added to concerns about the durability of the broader luxury sector’s recovery.

    Sephora Leads Growth Across LVMH Divisions

    Despite weakness in fashion and slower growth in jewellery, several LVMH businesses reported positive trading performances.

    Selective retailing was the group’s strongest division, generating organic revenue growth of 8%.

    Beauty retailer Sephora continued gaining market share in several countries, supported by exclusive product introductions, including launches associated with Rhode.

    The business also expanded its international presence by entering Belgium and Croatia.

    LVMH’s wines and spirits division recorded organic growth of 6%, benefiting from an ongoing recovery in champagne sales, particularly in Europe.

    Hennessy cognac also delivered positive momentum in Asian markets.

    Meanwhile, perfumes and cosmetics revenue increased 1%, supported by new product introductions, including Dior’s J’adore Intense and Sauvage Extrait fragrances.

    The differing performances across divisions highlighted the uneven nature of consumer demand within the luxury industry.

    Luxury Sector Faces Continued Valuation Pressure

    European luxury companies have experienced a prolonged slowdown over the past three years, with weaker demand and uncertainty surrounding Chinese consumer spending weighing on investor sentiment.

    The sector’s leading groups have collectively lost approximately €330 billion in market value since the beginning of the year.

    LVMH alone has recorded a decline of roughly 40% over that period.

    The scale of the losses reflects concerns about the sector’s earnings outlook and the pace at which demand for high-end fashion and accessories may recover.

    Tuesday’s share price declines demonstrated how disappointing results from a major industry participant can affect valuations across the wider luxury market.

    Investors will continue monitoring Chinese consumer demand, brand-level sales trends and the performance of other European luxury companies for evidence of a more sustained recovery.

  • Gold Recovers as Oil Prices Ease and Markets Await Key US Inflation Figures

    Gold Recovers as Oil Prices Ease and Markets Await Key US Inflation Figures

    Gold prices edged higher on Tuesday as softer crude oil prices and a weaker US dollar supported demand for precious metals ahead of closely watched American inflation data.

    Spot gold (XAU/USD) rose 0.4% to $4,189.12 an ounce at 04:47 ET (08:47 GMT), while gold futures advanced 0.5% to $4,213.25 an ounce.

    The gains followed a decline in oil prices after Russia indicated that diesel exports could exceed the quantities previously outlined in a supply agreement with the United States.

    Although the prospect of additional fuel supplies helped ease some inflation concerns, oil prices remained elevated amid continuing geopolitical tensions in the Middle East.

    Recent attacks attributed to Iran-backed Houthi forces against Saudi Arabia’s international airport in Riyadh have reinforced concerns about the security of regional energy infrastructure and shipping routes.

    These developments have left gold investors balancing the potential benefits of geopolitical uncertainty against the risk that higher energy prices could prolong inflation and encourage further interest-rate increases.

    Energy Market Volatility Complicates Gold’s Safe-Haven Appeal

    Gold has traditionally attracted interest during periods of political instability and financial uncertainty, but its performance during the Middle East conflict has reflected the competing effects of geopolitical risk and monetary policy expectations.

    According to the reported market figures, bullion has fallen approximately 20% since the United States and Israel launched a joint military operation against Iran in late February.

    The decline has been associated with concerns that higher oil prices could increase inflation and prompt the Federal Reserve to maintain restrictive borrowing conditions.

    Gold does not provide interest payments, meaning its relative appeal can diminish when yields on government bonds and other interest-bearing investments increase.

    As a result, expectations for additional monetary tightening can outweigh some of the support normally provided by geopolitical uncertainty.

    Tuesday’s decline in crude oil offered temporary relief by reducing immediate concerns about the effect of energy prices on inflation.

    However, risks to oil shipments from the Gulf remain elevated, particularly following attacks affecting Saudi Arabia and concerns about regional transport routes.

    The possibility of increased Russian diesel exports could help ease global fuel market pressures, although uncertainty surrounding the conflict continues to influence energy prices.

    For gold investors, the key issue is whether inflationary pressures begin to moderate or remain sufficiently persistent to require further action from central banks.

    Central Bank Reserve Diversification Supports Bullion Demand

    Despite recent market weakness, central bank purchases continue to provide an important source of longer-term demand for gold.

    Analysts at The Gold Bullion Company noted that monetary authorities have continued expanding their gold reserves as part of broader efforts to diversify international holdings.

    The strategy is intended to reduce dependence on individual reserve assets and limit exposure to changes in the value of major currencies.

    According to the analysts, central banks are seeking to “spread their reserves across different assets and reduce reliance on any single reserve holding”, including the US dollar.

    Gold remains an established component of official reserves because of its international marketability and its role in diversifying currency-related exposures.

    Continued institutional buying may help support demand over longer periods, even when short-term prices are affected by higher interest rates or movements in the dollar.

    However, reserve purchases do not eliminate the metal’s sensitivity to changes in monetary policy expectations.

    US Consumer Price Report Takes Centre Stage

    Investors were looking ahead to Wednesday’s US consumer price inflation report, which could influence expectations for the Federal Reserve’s next policy decisions.

    The central bank increased interest rates in September for the first time since 2023, citing the need to contain inflation.

    Nevertheless, financial markets have increasingly anticipated that policymakers will leave rates unchanged at their October meeting.

    Interest-rate swaps suggested an approximately 20% probability of another increase during the October gathering.

    Markets continued to price in one additional rate rise before the end of 2026.

    The inflation figures will be particularly important given the recent increase in energy prices, which could contribute to broader consumer price pressures.

    An unexpectedly strong inflation reading could strengthen expectations for further monetary tightening and weigh on non-yielding assets such as gold.

    Alternatively, evidence that inflation is moderating could reduce expectations for additional rate increases, potentially providing support for bullion.

    Federal Reserve Bank of Cleveland President Beth Hammack said on Monday that smaller and more frequent adjustments to monetary policy could help prevent inflation expectations from becoming unanchored.

    She did not, however, explicitly advocate raising interest rates at the central bank’s October meeting.

    Her remarks reinforced the importance of incoming economic indicators as policymakers consider how to balance inflation risks against broader economic conditions.

    Silver and Platinum Rise Alongside Gold

    Other precious metals also strengthened during Tuesday’s trading session.

    Spot silver gained 0.3% to $60.4830 an ounce, while spot platinum climbed 0.7% to $1,704.03 an ounce.

    The advances coincided with weakness in the US currency.

    The US Dollar Index, which measures the greenback against a basket of major currencies, declined 0.3% to 102.33.

    Because precious metals are generally priced in dollars, a decline in the currency can make them less expensive for buyers holding other currencies.

    This relationship can support international demand, although actual price movements also depend on investment flows, interest rates and broader market conditions.

    Dollar weakness therefore provided an additional source of support for precious metals during the session.

    Inflation Outlook Remains Central to Gold Prices

    Gold’s modest recovery reflected improving sentiment following the decline in oil prices, together with a weaker dollar and continued demand for precious metals.

    Nevertheless, the outlook remains complicated by the interaction between geopolitical developments and monetary policy.

    Further disruption to Middle Eastern energy supplies could increase inflation risks, potentially strengthening expectations for additional Federal Reserve tightening.

    At the same time, geopolitical uncertainty may continue to encourage some investors to maintain exposure to gold as a defensive asset.

    Wednesday’s US inflation report will provide a clearer indication of whether recent energy market developments are contributing to persistent price pressures.

    Investors will also be monitoring Federal Reserve commentary, movements in government bond yields and central bank gold purchases for further signals about the metal’s near-term and longer-term prospects.

  • Crude Oil Prices Decline as Russian Diesel Export Plans Ease Supply Concerns

    Crude Oil Prices Decline as Russian Diesel Export Plans Ease Supply Concerns

    Oil futures moved lower on Tuesday as the prospect of additional Russian diesel exports weighed on prices, partially offsetting concerns about attacks on shipping routes and energy infrastructure in the Middle East.

    Brent crude declined $1.62, or 1.52%, to $105.03 a barrel by 08:20 GMT. US West Texas Intermediate (WTI) fell $1.66, equivalent to 1.77%, to $92.08 a barrel.

    Both benchmarks had risen by almost $2 a barrel on Monday, with Brent recording its highest settlement since 15 September.

    The reversal followed an announcement from US President Donald Trump concerning Russian fuel supplies, raising expectations that more diesel could become available to international buyers.

    However, uncertainty surrounding Russia’s refining capacity and continuing geopolitical risks limited confidence in a sustained improvement in supply conditions.

    Russian Fuel Agreement Faces Production and Political Obstacles

    Trump said Russia had agreed to provide diesel to global markets after his administration temporarily relaxed US sanctions affecting Russian fuel.

    The sanctions were intended to restrict Moscow’s energy revenues during its military campaign against Ukraine.

    Additional Russian exports could help ease shortages in international fuel markets, potentially reducing pressure on refined product prices and the broader crude oil market.

    Nevertheless, analysts questioned whether Russia would be capable of delivering the proposed volumes.

    Tamas Varga, an associate analyst at PVM Oil, highlighted the difficulties facing the country’s refining industry.

    “Russia is unlikely to meet its pledge to supply 3 million to 3.5 million tonnes a month by year-end, given the serious problems affecting its refining sector,” Varga said.

    The assessment suggests that operational constraints could limit the amount of diesel Russia can supply, regardless of changes to sanctions or export arrangements.

    Political opposition in Washington has introduced another complication.

    Lawmakers from both major US parties criticised the agreement between Trump and Russian President Vladimir Putin, arguing that it appeared inconsistent with legislation restricting Russian energy imports until Moscow ends its aggression against Ukraine.

    The dispute raises questions about the legal and practical implementation of the arrangement.

    Investors will therefore be monitoring whether the agreement results in actual increases in fuel shipments rather than relying solely on announced export targets.

    Gulf Shipping Attacks Sustain Geopolitical Risk Premium

    The potential expansion of Russian supply comes at a time when energy markets remain concerned about security conditions in the Middle East.

    Iran-aligned Houthi forces reportedly struck Riyadh’s international airport over the weekend, while attacks involving tankers were also reported near the Strait of Hormuz.

    The incidents heightened concerns about the vulnerability of energy infrastructure and maritime transport routes across the Gulf region.

    The Strait of Hormuz is a major passage for international oil shipments, and disruptions can affect the movement of crude oil and refined products to global consumers.

    Security threats can also increase shipping insurance premiums, freight charges and delivery times.

    Varga said the absence of meaningful progress towards reducing tensions in Eastern Europe and the Middle East was keeping the geopolitical risk premium in crude oil prices elevated.

    He also warned that increased attacks on commercial tankers and continuing tensions between Houthi forces and Saudi Arabia could prevent regional exports from returning to September’s elevated levels.

    These risks complicate the outlook for global oil availability, particularly when shipping constraints prevent producers from delivering their output efficiently.

    Transport and Insurance Expenses Reach Exceptional Levels

    Ministers representing OPEC and non-OPEC producers involved in the Declaration of Cooperation reported a substantial increase in shipping and insurance costs.

    According to the ministers, combined expenses have risen to unprecedented levels exceeding one-third of the value of the oil and petroleum products being transported.

    The increase has created additional difficulties for the international movement of crude and refined fuels.

    Even when producers have sufficient volumes available for export, high transportation costs can make shipments more expensive and reduce the efficiency of supply chains.

    Importers may face higher delivered fuel costs despite declines in benchmark oil prices.

    The pressure is particularly significant for routes exposed to military activity, attacks on commercial vessels or other security threats.

    The situation demonstrates how maritime disruption can affect international energy prices independently of production levels.

    OPEC Slashes Oil Demand Growth Estimate

    In addition to supply developments, traders are assessing a weaker outlook for global oil consumption.

    OPEC has lowered its forecast for demand growth this year to 400,000 barrels per day, compared with 1.4 million barrels per day at the beginning of the year.

    Secretary General Haitham Al Ghais said on Monday that the reduction reflected developments throughout the year.

    The revised estimate represents a decrease of one million barrels per day in anticipated demand growth.

    Slower consumption growth could reduce upward pressure on oil prices, particularly if Russian diesel exports increase or other producers maintain sufficient supply.

    However, the effect will depend on actual export volumes and the extent of any disruptions affecting energy shipments from the Middle East.

    The downgrade also adds uncertainty to the outlook for producers seeking to balance supply against changing global demand conditions.

    Oil Market Faces Competing Supply and Demand Pressures

    Tuesday’s price decline highlighted the competing forces influencing international energy markets.

    Expectations of additional Russian diesel exports offered some relief from concerns about tight fuel supplies, but doubts over refining capacity and political opposition in the United States remain unresolved.

    Meanwhile, attacks on maritime transport and energy infrastructure in the Middle East continue to threaten the reliability of regional exports.

    Higher shipping and insurance expenses could also restrict the movement of petroleum products, even where physical production remains available.

    OPEC’s lower demand growth forecast adds a potentially bearish influence, suggesting that global consumption may expand more slowly than previously expected.

    The direction of crude prices will depend on whether additional Russian supplies materialise, how security conditions develop around the Strait of Hormuz and whether global oil demand continues to weaken.

    For now, the market remains exposed to rapid changes in supply expectations, geopolitical developments and international shipping conditions.

  • Wall Street Futures Diverge as AI Investment Doubts, LVMH Weakness and Bank Results Drive Trading: Dow Jones, S&P, Nasdaq

    Wall Street Futures Diverge as AI Investment Doubts, LVMH Weakness and Bank Results Drive Trading: Dow Jones, S&P, Nasdaq

    US equity futures showed contrasting movements on Tuesday as investors prepared for major bank earnings, assessed disappointing sales from luxury group LVMH and reconsidered the financial outlook for companies exposed to artificial intelligence.

    Energy market developments and geopolitical tensions added to uncertainty, while upcoming US inflation figures remained an important consideration for expectations surrounding Federal Reserve interest rate policy.

    At 02:48 ET (06:48 GMT), Dow Jones Industrial Average futures were up 225 points, or 0.4%. S&P 500 futures edged down six points, equivalent to 0.1%, while Nasdaq 100 futures dropped 237 points, or 0.8%.

    The relative weakness of Nasdaq futures followed renewed selling among technology companies, particularly semiconductor manufacturers and businesses associated with large-scale AI infrastructure investment.

    The main US stock indices had ended Monday’s session mixed, with investors responding to higher energy prices, questions about technology valuations and weaker-than-expected trading figures from LVMH.

    Semiconductor Losses Highlight Uncertainty Over AI Spending

    Artificial intelligence remained a significant influence on market sentiment after US semiconductor shares declined sharply at the beginning of the week.

    A sector index tracking chip manufacturers lost 2.7% on Monday, reflecting growing investor caution about the relationship between substantial AI-related expenditure and future profitability.

    Technology shares in South Korea subsequently experienced considerable selling pressure.

    Reports of advances by Chinese memory chip producer ChangXin Memory Technologies contributed to concerns about the competitive position of established semiconductor manufacturers.

    The developments raised questions about whether Chinese companies could make further progress in narrowing the technological gap with US suppliers.

    Investor uncertainty has also been influenced by scrutiny of revenue expectations surrounding OpenAI, the company behind ChatGPT.

    Demand for AI services and infrastructure remains strong, but investors are increasingly examining the returns that technology businesses may generate from their capital expenditure programmes.

    Large technology companies are investing heavily in data centres, computing equipment and networking infrastructure, with debt financing contributing to some projects.

    The scale of these commitments has prompted closer examination of future cash generation, operating margins and the period required for investments to become profitable.

    Technology sector valuations may therefore remain sensitive to evidence of whether commercial AI adoption can generate sufficient revenue to support continued expansion.

    LVMH Revenue Misses Forecasts as Fashion Division Contracts

    LVMH (USOTC:LVMUY) came under pressure in Paris after reporting third-quarter sales that fell short of analysts’ estimates.

    The luxury goods group generated revenue of €18.5 billion, representing a 1% organic increase from the corresponding quarter of the previous year.

    The performance was below the 1.3% growth forecast in the Visible Alpha consensus cited by Reuters.

    Results from the company’s fashion and leather goods division were particularly weak.

    Organic revenue in the segment declined 5%, compared with expectations for a 1.8% fall.

    The division accounts for approximately half of LVMH’s total revenue, making its performance an important measure of demand for the group’s core luxury brands.

    Growth in watches and jewellery also slowed.

    Regional figures showed a 5% year-on-year decline in Asian sales, with China remaining a significant source of weakness.

    Luxury spending in the Chinese market has been affected by weaker consumer demand and increased tax scrutiny of wealthy individuals.

    Higher costs associated with geopolitical developments have added further challenges for the sector.

    The results raised questions about the strength of demand for premium products and the pace at which Chinese luxury consumption might recover.

    LVMH’s performance could also influence market expectations for other European luxury companies preparing to publish financial updates.

    US Banks Begin Quarterly Reporting Season

    A series of earnings announcements from major US financial institutions was scheduled to begin later on Tuesday.

    JPMorgan Chase (NYSE:JPM), Goldman Sachs (NYSE:GS), Wells Fargo (NYSE:WFC) and Citigroup (NYSE:C) were due to report third-quarter results.

    Bank of America (NYSE:BAC), Morgan Stanley (NYSE:MS) and BlackRock (NYSE:BLK) were expected to follow on Wednesday.

    The releases will provide investors with updated information about the profitability of lending activities, deposit costs, credit performance and investment banking revenue.

    Higher government bond yields have become an important consideration for financial institutions because of their potential effect on asset valuations and net interest margins.

    Analysts at Vital Knowledge indicated that banking results could broadly match expectations, while identifying several possible sources of pressure.

    These included increased funding costs, volatility in financial markets and slower securities issuance, which could reduce fee income from capital markets activities.

    The analysts also highlighted potential weakness in revenue associated with residential mortgages.

    Investors will examine whether merger and acquisition activity, initial public offerings and other corporate financing transactions are contributing to investment banking earnings.

    The results will also provide evidence about household and corporate borrowing conditions, particularly through credit loss provisions and loan performance.

    Separately, Deutsche Bank forecast third-quarter earnings growth of 34% for the S&P 500.

    Its analysts argued that market expectations may underestimate corporate earnings resilience.

    “The consensus is once again assuming too sharp a slowdown, leaving room for another quarter in which companies exceed forecasts more frequently than usual,” the analysts said.

    The start of the earnings season will therefore be an important test of whether corporate profitability can support current US equity market valuations.

    Crude Oil Falls Following Russian Diesel Export Comments

    Oil futures declined on Tuesday as the possibility of increased Russian diesel exports partially offset concerns about disruptions to energy supplies in the Middle East.

    Brent crude fell 1.5% to $105.09 per barrel by 03:54 ET, while West Texas Intermediate dropped 1.8% to $92.08.

    The retreat followed gains on Monday, when Brent reached its highest closing level since 15 September.

    Russian Deputy Prime Minister Alexander Novak said the country could increase diesel exports beyond the volumes outlined in a supply agreement announced by US President Donald Trump.

    The comments followed a temporary easing of US restrictions on Russian fuel.

    Trump also announced an “energy ceasefire” between Russia and Ukraine, although reports of further strikes against Ukrainian energy infrastructure raised questions about the arrangement’s effectiveness.

    Elsewhere, tensions in the Middle East continued to threaten regional energy transport.

    Attacks attributed to Iran-backed Houthi forces against Saudi Arabia’s international airport and strikes involving tankers in the Strait of Hormuz contributed to concerns about the security of oil shipments.

    The waterway is a critical route for international crude exports, making any interruption potentially significant for global supply.

    While expectations of additional Russian exports weighed on prices, uncertainty surrounding Middle Eastern shipping routes continued to support a geopolitical risk premium.

    The competing supply developments left oil markets sensitive to further announcements and regional security developments.

    For equity investors, attention will remain divided between the start of the US earnings season, forthcoming inflation data and the financial outlook for artificial intelligence investment.

    Bank results will provide an early indication of corporate earnings conditions, while LVMH’s weaker sales and volatility in semiconductor stocks have highlighted potential risks to market valuations.

    Oil prices and geopolitical developments will remain additional factors influencing inflation expectations and the broader direction of financial markets.

  • European Stocks Advance Despite Global Technology Sell-Off as Bank Earnings Take Centre Stage: DAX, CAC, FTSE100

    European Stocks Advance Despite Global Technology Sell-Off as Bank Earnings Take Centre Stage: DAX, CAC, FTSE100

    European stock markets moved higher on Tuesday, resisting broader weakness in global technology shares as investors focused on the start of the third-quarter earnings season and continued strength in energy-related stocks.

    The pan-European Stoxx Europe 600 index gained 0.3% in early trading, outperforming technology-heavy markets in Asia and the United States, where concerns about artificial intelligence valuations weighed on investor sentiment.

    European equity markets have relatively less exposure to the largest AI-focused technology companies than the Nasdaq and several Asian semiconductor markets, helping to limit the impact of the latest sector sell-off.

    Germany’s DAX rose 0.2%, while France’s CAC 40 advanced 0.5%. London’s FTSE 100 gained 0.8%, and Spain’s IBEX 35 increased 0.4%, supported by its substantial exposure to banking stocks.

    The gains reflected a more favourable performance among financial and energy companies, which helped offset weakness in technology, industrial and consumer-related shares.

    Energy Shares Supported by Elevated Oil and Gas Prices

    European energy stocks attracted investor interest as crude oil and natural gas prices remained close to their highest levels in two weeks.

    Concerns about shipping security in the Middle East, particularly around the Strait of Hormuz, continued to influence energy markets.

    Attacks on commercial vessels and uncertainty surrounding maritime transport routes have contributed to higher perceived supply risks, supporting oil and gas prices.

    European natural gas futures remained above €82 per megawatt-hour, while crude oil prices also held firm.

    Higher energy prices can support revenues and earnings expectations for oil and gas producers, although their effect varies depending on production costs, contractual arrangements and market conditions.

    Energy companies listed in London, Oslo and other European markets consequently helped support regional equity indices.

    Utilities also attracted attention, although the impact of higher energy prices on individual companies depends on their generation portfolios, fuel purchasing arrangements and regulatory exposure.

    The strength of energy-related shares provided some protection against declines elsewhere in the market, particularly among industrial and consumer discretionary businesses.

    US Banking Results Set to Influence Market Sentiment

    Investors were also preparing for the start of the third-quarter earnings season, with several major US banks scheduled to publish their financial results.

    JPMorgan Chase (NYSE:JPM), Goldman Sachs Group (NYSE:GS), Citigroup (NYSE:C) and Wells Fargo (NYSE:WFC) were among the institutions expected to report during Tuesday’s session.

    Their results will provide investors with information about profitability, lending conditions, credit quality and activity across financial markets.

    Particular attention will be paid to net interest income and the relationship between lending yields and deposit funding costs.

    Elevated interest rates can support returns on certain banking assets, but competition for deposits and higher funding expenses may limit the benefits.

    Investors will also examine provisions for credit losses and loan charge-off rates to assess whether households and businesses are experiencing greater difficulty servicing debt.

    These indicators could provide insight into the effects of higher borrowing costs on the wider US economy.

    Investment banking revenue will be another area of focus, including advisory fees, underwriting activity and the outlook for mergers and acquisitions.

    Changes in dealmaking activity can offer an indication of corporate confidence and companies’ willingness to pursue investment or expansion plans.

    Given the international operations of major US banks, their results may also influence expectations for European financial institutions and broader equity markets.

    ASML and EQT Among Upcoming European Earnings Reports

    Alongside US banking results, investors are preparing for important European corporate updates later in the week.

    Dutch semiconductor equipment manufacturer ASML (EU:ASML) is scheduled to report third-quarter earnings on Wednesday.

    The company’s results will provide information about demand for advanced semiconductor manufacturing equipment and capital expenditure trends among global chip producers.

    ASML’s performance is closely followed because of its role in supplying lithography systems used in semiconductor production.

    Investors will be assessing order intake, revenue trends and management commentary on demand from customers investing in advanced chip manufacturing.

    The results may also help clarify whether spending associated with artificial intelligence infrastructure is translating into sustained demand for semiconductor production equipment.

    Swedish investment group EQT is also expected to publish a corporate update later in the reporting period.

    Its figures will provide insight into private equity investment activity, fundraising conditions and the deployment of institutional capital.

    Investors will be monitoring developments in portfolio valuations, transaction activity and private credit markets, particularly as financing conditions continue to influence corporate transactions.

    The upcoming reports will offer additional information about business confidence and investment trends across European and international markets.

    European equities began Tuesday’s session on a positive footing despite the global technology sell-off, supported by gains in banking and energy-related shares.

    However, market direction will remain sensitive to corporate earnings, geopolitical developments and changes in expectations surrounding artificial intelligence investment.

    The results from major US banks and European companies, including ASML, will provide further evidence of how businesses are performing against a backdrop of elevated energy prices and uncertain global market conditions.

  • Eurozone Bond Yields Hold Near Multi-Year Highs Amid French Debt Concerns and AI-Related Corporate Issuance

    Eurozone Bond Yields Hold Near Multi-Year Highs Amid French Debt Concerns and AI-Related Corporate Issuance

    Eurozone government bond yields were broadly stable on Tuesday, remaining close to multi-year highs as investors assessed France’s fiscal outlook, elevated energy prices and increased competition from corporate debt issuance linked to artificial intelligence infrastructure investment.

    Germany’s benchmark 10-year government bond yield was little changed at approximately 3.477%, while the two-year Bund yield edged lower to 3.099%.

    French government bonds continued to face pressure, with the benchmark 10-year OAT yield trading near 4.888%, reflecting investor concerns about the country’s public finances and political uncertainty.

    The difference between French and German borrowing costs remained a focus for fixed-income investors, as markets assessed the additional risk associated with holding French sovereign debt.

    France’s public debt is approaching 120% of gross domestic product, while its projected budget deficit stands at approximately 5.4% of GDP.

    The fiscal position has raised questions about the government’s ability to reduce borrowing requirements while maintaining political support for spending reforms.

    Prime Minister Sébastien Lecornu faces challenges in securing parliamentary approval for approximately €54 billion in proposed budget reductions.

    Political divisions within the National Assembly have complicated the outlook for fiscal consolidation, particularly ahead of France’s presidential election in 2027.

    Investors are monitoring whether the government can implement the proposed measures and establish a credible path towards reducing the deficit.

    Uncertainty over the budget could continue to influence demand for French government bonds and the premium investors require relative to German debt.

    Energy markets have added another source of pressure for European fixed-income markets.

    Crude oil and European natural gas futures remained close to two-week highs, raising concerns about the potential effect of energy costs on inflation.

    Higher energy prices can contribute to consumer price pressures and influence expectations for monetary policy across the eurozone.

    For the European Central Bank, persistent inflation risks could limit the scope for substantial interest rate reductions in the coming months.

    Government bond yields are sensitive to these expectations, particularly when investors anticipate that borrowing costs may remain elevated for longer.

    Alongside fiscal and monetary policy developments, eurozone sovereign debt markets are facing increased competition from corporate bond issuance.

    Large US technology companies and semiconductor infrastructure businesses have been raising capital to finance substantial investment programmes associated with artificial intelligence.

    These projects include data centres, computing infrastructure and networks required to support increasingly demanding AI applications.

    Some companies have accessed euro-denominated debt markets through so-called reverse-Yankee bond issuance, allowing US borrowers to raise financing from European investors.

    The additional supply of corporate bonds has increased competition for institutional investment capital, particularly among investors allocating funds across government and corporate fixed-income securities.

    As the volume of available debt increases, investors may require higher yields to absorb new issuance.

    This can influence borrowing costs across bond markets, although the effect depends on investor demand, credit quality and broader monetary conditions.

    The expansion of AI-related capital expenditure has therefore become an additional factor for fixed-income markets, alongside traditional influences such as inflation, government borrowing and central bank policy.

    For European government bonds, the combination of elevated sovereign debt issuance and substantial corporate financing requirements could maintain pressure on yields.

    France remains particularly exposed to investor scrutiny because of its fiscal position and uncertainty surrounding proposed budget measures.

    Germany’s government bonds continue to serve as the principal eurozone benchmark, with movements in Bund yields influencing pricing across other sovereign markets.

    Tuesday’s relatively stable trading suggests investors are assessing these competing pressures rather than making substantial changes to their bond holdings.

    Looking ahead, developments in French budget negotiations, energy prices, ECB policy expectations and corporate debt issuance will remain important influences on eurozone borrowing costs.