Author: Fiona Craig

  • Market Open: BP Impairments, Whitbread Profit Decline

    Market Open: BP Impairments, Whitbread Profit Decline

    FTSE 100 rises as BP flags impairments and Whitbread reports lower profit. European markets are mixed, while Brent crude and gold decline.

    Market Overview

    The FTSE 100 opened higher on Tuesday, rising 0.86 per cent to 10,748.00, with commodity-related stocks providing support despite broader concerns over global technology shares. European markets were mixed, with the Euronext 100 slipping 0.13 per cent to 1,864.14, while Germany’s DAX gained 0.30 per cent to 25,353.91. On Wall Street, the Nasdaq closed lower at 27,245.90, while the S&P 500 declined to 7,807.24, reflecting continued pressure on technology stocks. European investors are also monitoring the start of the US bank earnings season.

    Commodity markets showed mixed performance, with copper advancing while gold and natural gas declined. Brent crude edged lower as prospects for additional Russian diesel supplies counterbalanced concerns about disruptions to Middle Eastern energy exports. Bitcoin strengthened against sterling, while the pound weakened against the US dollar, Swiss franc and Australian dollar but strengthened against the euro and Japanese yen. Energy supply uncertainty and corporate earnings remain important influences on market sentiment.


    Market Numbers

    FTSE 100: Up (+0.86%), 10,748.00

    Euronext 100: Down (-0.13%), 1,864.14

    DAX: Up (+0.30%), 25,353.91

    NASDAQ: Down, 27,245.90

    S&P 500: Down, 7,807.24


    In the Headlines

    Q3 Impairments and Debt Reduction – BP (LSE:BP.)
    Energy major BP expects third-quarter post-tax impairment charges of between $3.0 billion and $4.5 billion, primarily affecting its gas and low-carbon businesses. Net debt is expected to fall to between $13.5 billion and $14.5 billion from $22.3 billion at the end of June, with the reduction providing an important balance sheet development ahead of its quarterly results.

    First-Half Profit Decline – Whitbread (LSE:WTB)
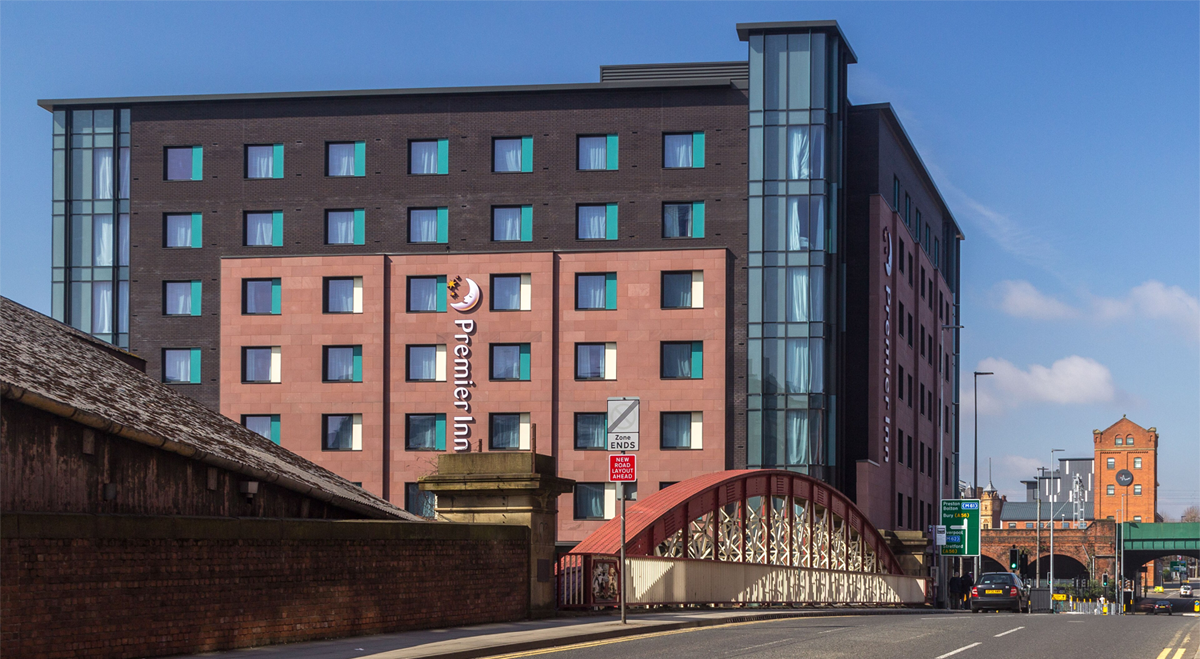
    Hotel operator Whitbread reported a decline in first-half FY27 statutory profit as it continued expanding its Premier Inn business and implementing cost-saving measures. Investors are assessing the impact of its expansion strategy and operating efficiencies on future profitability.


    Currencies (vs GBP)

    USD: Up (+0.18%), $1.3234

    CHF: Up (+0.05%), Fr.1.1024

    EUR: Down (-0.11%), €1.1824

    JPY: Down (-0.04%), ¥209.3315

    AUD: Up (+0.01%), $1.8993

    Bitcoin (BTC/GBP): Up, £63,307.00


    Commodities

    Copper: Up

    Gold: Down

    Brent Crude: Down

    Natural Gas: Down

  • LVMH Shares Decline as Fashion and Leather Goods Sales Fall 5% Amid Weaker Chinese Demand

    LVMH Shares Decline as Fashion and Leather Goods Sales Fall 5% Amid Weaker Chinese Demand

    LVMH (EU:MC) shares fell more than 1% on Tuesday after the French luxury goods group reported a decline in third-quarter sales at its fashion and leather goods division, reflecting weaker demand in China despite growth across several other business segments.

    The company reported third-quarter revenue of €18.5 billion, slightly exceeding analyst consensus expectations of €18.46 billion. Organic revenue increased 1% during the period, supported by growth in the United States, Europe and Japan.

    For the first nine months of the year, group revenue reached €57.1 billion, representing a 2% decline on a reported basis but a 2% increase at constant exchange rates and scope.

    The group’s fashion and leather goods division, its largest business segment, recorded a 5% decline in organic revenue during the third quarter.

    Divisional revenue fell to €8.25 billion from €8.5 billion in the corresponding period last year, as slower spending in China offset continued demand in the US market.

    The performance of the division weighed on investor sentiment, given its substantial contribution to LVMH’s overall revenue.

    The decline also highlighted differences in luxury consumer demand across geographical markets, with stronger trading in Western markets and Japan contrasting with weaker conditions in China.

    Other LVMH divisions reported positive organic growth during the quarter.

    Watches and jewellery revenue increased 6% organically, supported by demand for jewellery collections.

    Tiffany & Co. continued developing its HardWear, Knot and Sixteen Stone product lines, while Bvlgari reported record revenue from its new Eclettica high jewellery and watch collection.

    Selective retailing delivered the strongest divisional performance, with organic revenue increasing 8%.

    Sephora gained market share in several countries, supported by exclusive product introductions, including the Rhode brand.

    The beauty retailer also expanded its geographical presence by entering Belgium and Croatia during the period.

    LVMH’s wines and spirits division reported organic revenue growth of 6%, reflecting improvements in demand across selected markets.

    Champagne sales continued to recover, particularly in Europe, while Hennessy cognac recorded positive momentum in Asia.

    The perfumes and cosmetics business generated organic revenue growth of 1%, supported by new product launches.

    These included Dior’s J’adore Intense and Sauvage Extrait fragrances, which contributed to activity within the division.

    The results demonstrated varying performance across LVMH’s portfolio, with growth in selective retailing, watches and jewellery, wines and spirits, and perfumes and cosmetics offsetting part of the decline in fashion and leather goods.

    However, the weakness in the group’s largest division remained a significant factor in the overall quarterly performance.

    LVMH’s geographical results also reflected different consumer spending conditions, with growth in the US, Europe and Japan helping compensate for softer demand in China.

    The company continues to operate across a broad range of luxury categories, including fashion, leather goods, jewellery, watches, fragrances, cosmetics, wines and spirits, and specialist retailing.

    Looking ahead, LVMH acknowledged continued uncertainty in the global economic and geopolitical environment.

    The group said it remained confident in its strategy, which focuses on strengthening the appeal of its brands, maintaining product quality and developing its retail operations.

    Management also highlighted the importance of organisational flexibility as it responds to changing market conditions.

    The third-quarter figures indicate that LVMH continues to generate growth across several business areas, although weaker Chinese demand remains a challenge for its fashion and leather goods operations.

    Investors will continue to assess the pace of recovery in Chinese luxury spending, the sustainability of demand in the US and Europe, and the contribution from the group’s other divisions.

    About LVMH

    LVMH Moët Hennessy Louis Vuitton is a French multinational luxury goods group operating across fashion and leather goods, watches and jewellery, perfumes and cosmetics, wines and spirits, and selective retailing.

    Its portfolio includes Louis Vuitton, Dior, Tiffany & Co., Bvlgari, Hennessy and Sephora, among other international brands.

    The company operates globally through boutiques, retail networks and distribution channels serving customers across major luxury markets.

  • FTSE 100 Rises 0.8% as Energy, Mining and Banking Stocks Support London Shares

    FTSE 100 Rises 0.8% as Energy, Mining and Banking Stocks Support London Shares

    London’s FTSE 100 outperformed major European equity benchmarks on Tuesday, rising 0.8% as gains among energy producers, mining companies and banks helped offset weaker sentiment across international stock markets.

    The UK’s blue-chip index benefited from its substantial exposure to commodity-related businesses and financial services, while technology shares faced selling pressure in the United States and Asia.

    Higher energy prices provided support for London-listed oil and gas producers, while major UK banks advanced ahead of third-quarter earnings announcements from leading US financial institutions.

    The gains contrasted with a more cautious backdrop across global equity markets, where declines in technology stocks contributed to broader concerns about valuations and market positioning.

    The FTSE 100’s composition played a significant role in its relative performance, with energy, mining and banking companies accounting for a substantial proportion of the index.

    These sectors responded to different market factors from those affecting technology-heavy benchmarks, allowing London shares to advance despite weakness elsewhere.

    Energy companies were among the contributors to the FTSE 100’s gains as crude oil and European natural gas prices remained elevated.

    Shell (LSE:SHEL) and BP (LSE:BP.) attracted buying interest as Brent crude traded close to two-week highs.

    European natural gas futures also remained above €82 per megawatt-hour, providing additional support for sentiment towards energy producers.

    Higher commodity prices can influence revenue and earnings expectations for oil and gas companies, although the eventual financial impact depends on production levels, operating costs and individual companies’ trading arrangements.

    The performance of Shell and BP was particularly relevant to the FTSE 100 because of their significant index weightings.

    Mining stocks also contributed to the benchmark’s advance, supported by relatively stable industrial metals prices.

    Rio Tinto (LSE:RIO) and Glencore (LSE:GLEN) moved higher as investors assessed commodity market conditions and adjusted their exposure to different equity sectors.

    The gains came amid a broader rotation away from some highly valued technology shares, with investors showing increased interest in companies linked to physical commodities and established cash-generating businesses.

    Mining companies remain sensitive to changes in global industrial activity, demand for raw materials and movements in metals prices.

    Financial services provided another source of support for London’s equity market.

    Shares in HSBC (LSE:HSBA), Barclays (LSE:BARC) and Lloyds Banking Group (LSE:LLOY) advanced ahead of the publication of third-quarter results from major Wall Street banks.

    Investors were assessing the outlook for banking profitability, particularly the ability of lenders to maintain net interest margins as interest rate expectations evolve.

    Net interest margins measure the difference between interest income generated by banks and the cost of funding their lending activities, relative to interest-earning assets.

    The upcoming US bank results were expected to provide further information about lending conditions, profitability and financial market activity.

    UK banking shares benefited from expectations that interest income could remain relatively resilient, although the outlook continues to depend on monetary policy, funding costs and credit demand.

    In currency markets, sterling strengthened modestly against the US dollar.

    The pound rose approximately 0.14% to trade around $1.322, supported by stabilising UK government bond yields.

    Currency traders continued to assess the Bank of England’s near-term monetary policy outlook ahead of forthcoming inflation figures.

    Movements in gilt yields and expectations for UK interest rates remained important influences on sterling, particularly as investors evaluated the timing and scale of potential monetary policy changes.

    The relative strength of the pound came alongside gains in UK equities, although currency movements can have different implications for companies depending on the geographical distribution of their earnings.

    Many FTSE 100 constituents generate substantial revenue outside the UK, making exchange rate fluctuations an additional consideration for investors.

    Tuesday’s market performance highlighted the influence of sector composition on major equity benchmarks.

    While technology-related selling affected markets in the United States and Asia, London’s greater exposure to energy, mining and banking companies provided support.

    The FTSE 100’s 0.8% advance reflected gains across several of its largest sectors, rather than a broad improvement in international investor sentiment.

    Attention will now turn to upcoming corporate earnings announcements, developments in commodity prices and UK inflation data, which could influence expectations for interest rates and the outlook for listed companies.

    For London equities, the immediate market direction will remain sensitive to energy prices, banking sector results and changes in global risk appetite.

  • UK Grocery Price Inflation Rises to 2.5% in October as Supermarket Sales Growth Slows

    UK Grocery Price Inflation Rises to 2.5% in October as Supermarket Sales Growth Slows

    British grocery price inflation increased to 2.5% in the four weeks ended 4 October 2026, according to figures released on Tuesday by market research firm Worldpanel by Numerator, as consumers faced renewed price pressures across selected food and household product categories.

    The latest data showed differing price trends across supermarket products, with water, cordials and skincare items recording the largest increases during the reporting period.

    By contrast, butter, cheese and chocolate experienced the steepest price declines, reflecting variations in pricing conditions across grocery categories.

    The figures provide an early indication of UK grocery price movements in October, ahead of the publication of official September inflation statistics by the Office for National Statistics on 21 October.

    Food price inflation has remained below earlier industry forecasts during 2026, supported by competition among major supermarket chains, consumer resistance to higher prices and improvements in retailers’ and suppliers’ hedging arrangements.

    Competition in the UK grocery sector has continued to influence pricing decisions, with retailers balancing the need to recover operating costs against pressure to maintain sales volumes and customer loyalty.

    Despite the relatively contained inflation rate recorded in October, industry groups have warned that food price pressures could increase substantially during 2027.

    Forecasts suggest UK food inflation could approach 7% next year, with potential increases linked to disruption in the Middle East, higher production and distribution costs, and extreme weather associated with El Niño.

    These projections remain subject to uncertainty, particularly regarding commodity prices, supply chain conditions and the extent to which retailers pass additional costs on to consumers.

    Worldpanel’s latest figures also indicated slower growth in overall grocery spending.

    Total UK grocery sales increased by 1.0% year on year during the four weeks ended 4 October, below the reported grocery price inflation rate of 2.5%.

    The difference suggests that the quantity of groceries purchased declined on an inflation-adjusted basis, although changes in product mix and shopping patterns can also affect the relationship between spending and volumes.

    The figures indicate that households remain sensitive to grocery prices, with spending growth failing to keep pace with the overall increase in prices.

    For supermarket operators, this environment creates competing pressures as retailers seek to protect sales volumes while managing costs and maintaining profitability.

    Among the major listed grocery retailers, Tesco (LSE:TSCO) reported sales growth of 1.0% over the 12 weeks ended 4 October.

    However, the UK’s largest supermarket chain recorded a decline in market share for the fifth consecutive reporting period.

    The figures suggest Tesco continued to generate sales growth, although its relative position within the grocery market weakened during the period covered by the research.

    Marks & Spencer (LSE:MKS) recorded considerably stronger food sales growth, with grocery revenue increasing 14.9%.

    The retailer remained the UK’s fastest-growing food operator according to the reported figures, although Worldpanel noted that Marks & Spencer is not fully represented in its dataset.

    This difference in coverage should be considered when comparing its performance directly with other supermarket groups.

    The contrast between Tesco’s 1.0% sales growth and Marks & Spencer’s 14.9% increase highlights the varying performance of major retailers within the broader grocery market.

    While the overall sector recorded modest spending growth, individual operators experienced different outcomes as consumers adjusted their shopping habits and purchasing decisions.

    Looking ahead, grocery inflation will remain an important indicator for both retailers and consumers, particularly as businesses assess the potential effects of higher input costs and international supply disruptions.

    The October Worldpanel figures suggest that supermarket competition has continued to moderate price increases, although the outlook for 2027 remains uncertain.

    Further information on UK inflation trends will become available with the release of official September consumer price data on 21 October.

    For the grocery sector, the latest figures point to continued pressure on inflation-adjusted sales volumes, alongside differences in performance between leading supermarket chains.

  • Michael Page Shares Hit Nine-Week Low Despite Return to Quarterly Gross Profit Growth

    Michael Page Shares Hit Nine-Week Low Despite Return to Quarterly Gross Profit Growth

    Michael Page (LSE:PAGE) shares fell to a nine-week low on Tuesday despite the recruitment group reporting its first quarterly increase in gross profit since late 2022, as continued weakness in European markets weighed on the outlook.

    The shares declined 1.8% to 190.47 pence, their lowest level since 7 August, while the FTSE 250 advanced 0.5%. In Frankfurt, the company’s shares dropped 8.1% to €2.26.

    Michael Page reported third-quarter gross profit of £190.5 million, an increase of 1.5% in constant currencies compared with the previous year. The result exceeded company-compiled analyst expectations of £187.9 million and marked the first quarterly increase since the fourth quarter of 2022.

    Growth in the Americas and Asia Pacific helped offset weaker recruitment activity across Europe, where economic uncertainty continued to affect hiring decisions.

    Gross profit in Europe, the Middle East and Africa declined 3.8% in constant currencies. Within the region, the UK recorded a 5.5% decrease, while France and Germany reported declines of 11% and 7%, respectively.

    The company described recruitment conditions in France, Northern Europe and the UK as challenging but stable, with employers continuing to exercise caution over hiring commitments.

    Despite the improvement in group gross profit, Michael Page maintained its full-year operating profit expectations at approximately £29 million, in line with company-compiled analyst consensus.

    The unchanged forecast reflects the continued differences in performance across the group’s international markets, with growth in some regions yet to translate into a higher annual profit outlook.

    Michael Page also reported improved productivity during the quarter, with gross profit per fee earner increasing 6% year on year.

    The company reduced its fee-earner workforce by 63 employees during the period, bringing the total to 4,851. Management said the adjustment reflected its continuing efforts to align staffing levels with recruitment activity.

    The group’s Page Executive division, which specialises in senior management and executive recruitment, delivered 15% growth during the quarter.

    The increase contrasted with weaker performance in several European markets and contributed to the group’s return to overall gross profit growth.

    Chief Executive Nicholas Kirk indicated that recruitment conditions were improving and becoming more normalised in a number of markets, although uncertainty remained a significant factor affecting the business.

    The company continues to operate in an environment where corporate recruitment decisions are influenced by economic conditions, business confidence and employers’ willingness to commit to additional staffing.

    Michael Page’s third-quarter performance showed an improvement in trading compared with the prolonged period of declining gross profit that began after 2022.

    However, the recovery remained uneven, with continued contractions in the UK, France and Germany offsetting some of the growth achieved elsewhere.

    The company’s decision to maintain its full-year operating profit forecast suggests management remains cautious about the pace at which improving recruitment activity will contribute to earnings.

    For the remainder of the financial year, Michael Page will continue to focus on managing costs, maintaining fee-earner productivity and responding to changes in recruitment demand across its international operations.

    The group’s latest trading update indicates a return to modest gross profit growth, while the share price decline reflects investor caution over persistent European weakness and the absence of an upgrade to annual profit expectations.

    About Michael Page

    Michael Page is an international specialist recruitment company operating as part of PageGroup, providing permanent, temporary and contract recruitment services across a range of professional sectors.

    The business serves employers and jobseekers in Europe, the Middle East, Africa, the Americas and Asia Pacific, with recruitment activities covering finance, technology, engineering, sales, marketing and other professional disciplines.

    Its operations include Page Executive, which specialises in senior management and executive-level appointments.

    The company is listed on the London Stock Exchange under the ticker LSE:PAGE and is a constituent of the FTSE 250 index.

  • BP Expects Up to $4.5 Billion in Q3 Impairments as Net Debt Falls to $13.5–$14.5 Billion

    BP Expects Up to $4.5 Billion in Q3 Impairments as Net Debt Falls to $13.5–$14.5 Billion

    BP (LSE:BP.) expects to recognise post-tax impairment charges of between $3.0 billion and $4.5 billion in the third quarter of 2026, primarily related to its gas and low-carbon energy businesses, according to a trading update released on Tuesday.

    The oil and gas company also forecast a substantial reduction in net debt during the three months ended 30 September, alongside improved refining performance and stronger gas marketing and trading results.

    BP expects net debt to be between $13.5 billion and $14.5 billion at the end of September, compared with $22.3 billion at 30 June.

    The projected reduction represents a decline of approximately $7.8 billion to $8.8 billion over the quarter.

    The company identified several factors affecting its debt position and cash movements during the period, including the redemption of hybrid securities, higher income tax payments, working capital releases and capital expenditure.

    BP did not provide a detailed reconciliation of the expected net debt reduction in the supplied trading update.

    The anticipated impairment charges relate to changes within the company’s gas and low-carbon energy operations.

    These non-cash accounting charges are expected to affect BP’s reported third-quarter earnings, although they do not necessarily represent equivalent cash expenditure during the period.

    The company expects to recognise the impairments as part of its financial results for the quarter, with the final amounts subject to its reporting process.

    In upstream operations, BP narrowed its third-quarter production guidance to between 2.190 million and 2.240 million barrels of oil equivalent per day (boe/d).

    This compares with production of 2.201 million boe/d in the second quarter.

    The company maintained its full-year production guidance of between 2.180 million and 2.270 million boe/d, indicating no change to its annual output expectations.

    BP also reported a reduction in realised crude oil prices during the quarter.

    The company’s average realised Brent price was $96.99 per barrel in the third quarter, compared with $103.85 per barrel in the preceding three-month period.

    The decline in realised prices represents a reduction of approximately 6.6% quarter on quarter.

    Despite the lower average realised Brent price, BP expects improved performance from its refining operations.

    The company indicated a third-quarter refining margin contribution in the range of $1.9 billion to $2.1 billion, alongside expected refinery throughput of between 1.375 million and 1.405 million barrels per day.

    The anticipated refining performance reflects conditions in global fuel markets, where supply disruptions have supported refining margins.

    Energy markets have experienced significant volatility during 2026, with disruptions linked to the conflict involving the United States and Iran affecting oil supplies and refining operations in the Middle East.

    Additional pressure on refining capacity has followed Ukrainian attacks on Russian energy infrastructure in recent months.

    These developments have contributed to changes in crude oil and refined product markets, influencing trading conditions for international energy companies.

    BP’s downstream business includes refining and marketing activities, which are affected by movements in crude oil prices, product prices and refinery operating margins.

    The company also expects a stronger contribution from its gas marketing and trading activities during the third quarter.

    BP said the result from this business is expected to be significantly higher than in the second quarter, although it did not provide a specific earnings estimate.

    Gas marketing and trading performance can vary between reporting periods, reflecting changes in commodity prices, market volatility and trading activity.

    The expected improvement represents another factor influencing BP’s third-quarter earnings alongside its upstream production, refining performance and impairment charges.

    The company’s trading update provides preliminary operational and financial indicators ahead of the publication of its complete quarterly results.

    BP is scheduled to release its third-quarter earnings on 30 October 2026, when it will provide further information on profitability, cash flow, debt and performance across its operating businesses.

    The results will also provide additional detail on the impairment charges associated with its gas and low-carbon energy operations.

    For the third quarter, BP’s financial performance is expected to reflect contrasting developments, including significant impairment charges, lower realised Brent prices, improved refining margins and a stronger gas trading contribution.

    The company enters its earnings announcement with net debt expected to have fallen substantially from the end of June, while maintaining its full-year upstream production guidance.

    About BP

    BP is an international energy company engaged in the exploration, production, refining, trading and marketing of oil, natural gas and related energy products.

    Its operations include upstream oil and gas production, refining, fuel marketing and energy trading, alongside activities in lower-carbon energy.

    The company’s financial performance is influenced by global commodity prices, production volumes, refining margins, trading conditions and capital investment requirements.

    BP operates across international energy markets and reports financial results covering its upstream, downstream and other energy-related businesses.

    The company is listed on the London Stock Exchange under the ticker LSE:BP. and on the New York Stock Exchange under NYSE:BP.

  • Bellway FY26 Revenue Rises 13.6% to £3.16 Billion as Housebuilder Announces £150 Million Share Buyback

    Bellway FY26 Revenue Rises 13.6% to £3.16 Billion as Housebuilder Announces £150 Million Share Buyback

    Bellway (LSE:BWY) reported a 13.6% increase in full-year revenue to £3.16 billion for the year ended 31 July 2026, supported by higher housing completions, while underlying profit before tax rose 5.7% to £305.7 million.

    The UK housebuilder completed 9,695 homes during FY2026, representing an increase of 10.8% compared with the previous financial year.

    Bellway also reported a 36% increase in adjusted operating cash flow to £868.6 million, reflecting cash generation from its development activities and supporting further shareholder distributions.

    The board increased the annual dividend by 7.1% to 75p per share and announced plans for a £150 million share buyback programme during FY2027.

    The company ended the financial year with net cash of £157.7 million and low adjusted gearing, providing financial capacity to support its development programme and planned capital returns.

    Despite the improvement in annual revenue and profitability, Bellway expects a reduction in housing completions during FY2027 as market conditions remain challenging.

    Management has set a completion target of between 9,000 and 9,400 homes for the new financial year, compared with the 9,695 properties delivered in FY2026.

    The guidance represents a potential reduction of approximately 3% to 7% in annual completions.

    Bellway said customer demand continues to be affected by economic uncertainty and elevated mortgage rates, which have placed pressure on housing affordability.

    The company also expects operating margins to face pressure from construction cost inflation, increased use of sales incentives and a higher proportion of bulk sales.

    Bulk sales, which involve transactions covering multiple properties, are expected to account for a greater share of Bellway’s completions during FY2027.

    Management said these transactions would help support sales volumes and cash generation, although their contribution to the overall sales mix is expected to affect margins.

    The group is responding to these conditions through tighter cost controls and further standardisation of its operating processes.

    Bellway has been implementing measures intended to improve efficiency across its regional divisions, including changes to construction methods and procurement activities.

    The company is also developing its timber frame manufacturing capabilities through a new facility, which forms part of its efforts to improve construction efficiency and support future housing delivery.

    Management expects greater operational consistency and the use of standardised processes to contribute to longer-term improvements in margins and returns.

    Bellway maintains a substantial land bank comprising owned development sites and strategic land interests, providing capacity for future construction activity.

    The group intends to manage investment in new land alongside its existing development commitments, with capital allocation remaining a priority as it balances operational expenditure and shareholder returns.

    The increase in adjusted operating cash flow to £868.6 million during FY2026 contributed to the company’s year-end net cash position.

    This financial performance has enabled Bellway to increase its dividend and introduce a £150 million share repurchase programme for FY2027.

    The proposed buyback will operate alongside the company’s ongoing investment in land, construction and development activities.

    Bellway also highlighted the potential implications of government measures intended to improve access to home ownership.

    The company welcomed the proposed Your First Home scheme, which is intended to support first-time buyers entering the housing market.

    Management believes measures addressing affordability could support demand for newly built homes, although the timing and scale of any benefit will depend on the final policy arrangements and broader market conditions.

    Bellway continues to operate across the private and affordable housing markets, delivering properties through its nationwide network of regional divisions.

    The company has maintained a five-star customer satisfaction rating from the Home Builders’ Federation for ten consecutive years, reflecting its performance against the organisation’s customer recommendation criteria.

    Looking ahead, Bellway expects FY2027 to be affected by lower completion volumes and margin pressures associated with construction costs and its anticipated sales mix.

    The group is focusing on cash generation, cost management and operational efficiency while maintaining investment in its development pipeline.

    Its priorities include delivering between 9,000 and 9,400 homes, progressing improvements to construction processes and managing its land portfolio in response to market demand.

    Bellway also intends to continue returning capital to shareholders through dividends and the planned £150 million buyback.

    The company’s longer-term strategy remains focused on increasing housing output and improving financial returns when market conditions and affordability allow.

    About Bellway plc

    Bellway plc is a UK residential property developer specialising in the construction and sale of private and affordable new homes.

    The company operates through a nationwide network of regional divisions, developing residential properties across a range of locations and price categories.

    Its activities include land acquisition, planning, residential construction and property sales.

    Bellway maintains an extensive portfolio of owned and strategic land interests to support future development and housing delivery.

    The group is investing in operational improvements, including standardised construction processes and timber frame manufacturing capabilities, to support efficiency and development capacity.

    Bellway has retained a five-star rating from the Home Builders’ Federation for ten consecutive years.

    The company is listed on the London Stock Exchange under the ticker LSE:BWY.

    Its financial strategy focuses on cash generation, capital discipline, low gearing and shareholder distributions through dividends and share repurchases.
  • Whitbread Reports Lower H1 FY27 Statutory Profit as Premier Inn Expansion and Cost Savings Continue

    Whitbread Reports Lower H1 FY27 Statutory Profit as Premier Inn Expansion and Cost Savings Continue

    Whitbread (LSE:WTB) reported modest revenue growth but a decline in statutory profit for the first half of FY2027, as higher accommodation sales across its hotel operations were offset by restructuring costs and inflationary pressures.

    The Premier Inn owner said performance reflected continued demand for accommodation in the UK, Ireland and Germany, alongside expenditure associated with its Accelerating Growth Plan and wider Five-Year Plan.

    Despite the reduction in statutory profitability, Whitbread reported an improvement in return on capital and maintained its dividend, while delivering £39 million of cost savings during the reporting period.

    The company reaffirmed its confidence in its full-year outlook as it continued implementing changes intended to simplify its operating model and increase the proportion of earnings generated by its hotel business.

    Whitbread has been moving towards a hotel-focused operating structure, reducing its exposure to branded restaurants and concentrating investment on accommodation capacity and operational efficiency.

    The transition forms part of the group’s strategy to improve returns from its existing property portfolio while expanding its hotel network in selected markets.

    During the first half, Whitbread continued optimising its UK estate, including the closure of its remaining branded restaurants.

    The programme is designed to shift the group’s operating activities towards accommodation, with management seeking to reduce costs and improve the financial performance of its hotel properties.

    Whitbread also reported progress with the disposal of 173 sites as part of its portfolio restructuring.

    The company has been pursuing these sales to release capital from properties that no longer fit its intended operating model.

    Proceeds from the disposal programme are expected to contribute to the group’s capital allocation priorities, although the supplied update did not disclose the total expected consideration or the number of sales completed during the period.

    The restructuring programme has contributed to transition costs affecting statutory profitability, while inflation has continued to place pressure on operating expenses.

    Whitbread said these factors partly offset the contribution from higher accommodation sales.

    The group nevertheless achieved £39 million of cost savings during the first half, reflecting progress with its efficiency initiatives.

    Management expects operational simplification and changes to its property portfolio to support its longer-term financial objectives.

    Alongside its UK restructuring activities, Whitbread continued expanding its Premier Inn operations in Germany.

    The company opened 1,771 new rooms in the German market during the period, contributing to double-digit growth in accommodation sales.

    Whitbread also reported that its German business continued to outperform the wider market, although the supplied update did not provide the comparative market figures.

    Germany remains an important area of expansion for the group as it develops its hotel network outside the UK.

    The company has been increasing its room capacity to establish a larger presence in the German budget accommodation market, while continuing to operate its established Premier Inn business in the UK and Ireland.

    Whitbread’s Five-Year Plan combines international room expansion with UK estate optimisation, cost reductions and changes to capital allocation.

    The group is targeting £2 billion of cash available for shareholder returns by FY2031.

    This target forms part of its longer-term financial objectives and remains dependent on future operating performance, investment requirements and cash generation.

    The company maintained its dividend for the first half, continuing its existing approach to shareholder distributions during the restructuring programme.

    Whitbread also addressed a shareholder resolution proposed by Corvex, with the board recommending that investors vote against the proposal.

    The supplied update did not specify the resolution’s terms or the board’s detailed reasons for opposing it.

    The shareholder matter comes as Whitbread continues implementing its current strategy, including property disposals, hotel expansion and measures intended to improve returns on invested capital.

    Looking ahead, management maintained its confidence in the group’s full-year outlook despite the impact of transition costs and inflation during the first half.

    The company expects its ongoing restructuring and efficiency measures to contribute to the development of a more hotel-focused business, although the timing of financial benefits will depend on the completion of planned changes.

    Whitbread’s priorities include progressing the sale of the 173 identified sites, completing its exit from branded restaurants, expanding accommodation capacity and continuing its cost reduction programme.

    The group is also working towards its longer-term objective of generating £2 billion of cash available for shareholder returns by FY2031.

    With accommodation revenue increasing across its principal markets, Whitbread is continuing its operational transition while managing the associated costs and maintaining investment in its Premier Inn network.

    About Whitbread PLC

    Whitbread PLC is a UK-based hospitality company and the owner of Premier Inn, a budget hotel brand operating across the UK, Ireland and Germany.

    The group provides accommodation services through its hotel network, serving business and leisure customers in a range of locations.

    Whitbread is implementing a strategy to concentrate its operations on hotels, including the closure of branded restaurants and the disposal of selected properties.

    Its development programme includes expanding room capacity, improving operational efficiency and optimising returns from its existing estate.

    The company is also investing in its German hotel operations as part of its international expansion strategy.

    Whitbread is listed on the London Stock Exchange under the ticker LSE:WTB.

  • YouGov FY26 Revenue Rises 2% to £396.6 Million as Company Forecasts 7%–12% Profit Growth in FY27

    YouGov FY26 Revenue Rises 2% to £396.6 Million as Company Forecasts 7%–12% Profit Growth in FY27

    YouGov (LSE:YOU) reported a 2% increase in full-year revenue to £396.6 million for FY2026, with financial performance broadly in line with management guidance despite lower adjusted operating profit and margins.

    The international research and data analytics company said stronger trading during the second half supported its annual revenue performance, while investment in its operations and non-cash impairment charges affected reported profitability.

    YouGov also outlined plans to continue its cost reduction programme, expand its artificial intelligence capabilities and return up to £15 million to shareholders through a share buyback programme.

    The company expects adjusted operating profit to increase by between 7% and 12% in FY2027, supported by operational changes and its ongoing Value Delivery Plan.

    During FY2026, performance varied across YouGov’s three principal business divisions: Data Products, Research and Shopper.

    The Data Products division reported higher profits and improved margins, reflecting performance across its established data and analytics offerings.

    The division provides clients with research datasets and analytical products designed to support commercial decision-making, brand monitoring and consumer understanding.

    YouGov’s Research division reported improvements in its pipeline of strategic projects, as the company continued developing relationships with corporate and institutional clients.

    The business provides customised research services, including studies designed to assess consumer behaviour, market conditions and brand performance.

    Meanwhile, the Shopper division delivered relatively stable revenue but experienced a reduction in profitability.

    The company attributed the division’s performance partly to targeted investment and confirmed that a strategic review of the business was under way.

    The review forms part of YouGov’s broader assessment of its operations and allocation of resources across the group.

    Management said the company was progressing ahead of schedule with its Value Delivery Plan, which is intended to simplify operations, reduce costs and improve financial performance.

    The programme has already delivered savings, although the supplied update did not specify their total value.

    YouGov has been implementing operational changes alongside investment in technology and product development, seeking to improve efficiency while maintaining its research and analytics capabilities.

    Artificial intelligence remains an area of investment for the company, with management highlighting the development of AI-enabled products and services.

    During the year, YouGov launched YouGov Voices, a new offering incorporating AI technology into its research and data capabilities.

    The company said the product had already contributed to new business generation, although it did not disclose the associated revenue or contract values.

    YouGov is continuing to integrate AI tools into its products and internal processes, using its research panels and existing datasets to support the development of new analytical services.

    Management sees opportunities to expand its product portfolio as clients seek data and research services that can be incorporated into AI-supported business processes.

    Alongside its operational initiatives, YouGov reported improvements in cash conversion and extended its debt facilities.

    The extension provides additional financing arrangements as the company continues implementing its operational and investment plans.

    The board also announced a change to its approach to shareholder distributions.

    Instead of paying a dividend for FY2026, YouGov intends to undertake a share buyback programme of up to £15 million.

    The proposed repurchases will provide a mechanism for returning capital to shareholders, with the amount ultimately deployed dependent on the programme’s execution.

    Looking ahead, YouGov expects adjusted operating profit growth of 7% to 12% in FY2027.

    The forecast reflects management’s expectations for the contribution from cost savings, operational improvements and continued development of the company’s data and research offerings.

    The group is also preparing for a leadership transition as it implements its next phase of operational changes.

    Details of the incoming leadership arrangements were not provided in the supplied update.

    YouGov’s priorities for FY2027 include continuing its Value Delivery Plan, expanding AI-enabled products, progressing the Shopper division’s strategic review and improving profitability.

    The company will also focus on converting its Research division’s project pipeline into revenue while maintaining the performance of its Data Products business.

    With annual revenue reaching £396.6 million, YouGov enters FY2027 targeting improved adjusted operating profitability following a year of investment, restructuring activity and mixed divisional performance.

    About YouGov plc

    YouGov plc is an international research and data analytics company providing market intelligence, consumer insights and research services to businesses and institutions.

    The group operates across data products, customised research and shopper analytics, supporting clients with information about consumer behaviour, brand performance and market developments.

    Its services include brand tracking, audience analysis, consumer research and strategic research projects.

    YouGov uses its international research panels and data resources to collect and analyse information for clients across different industries and geographical markets.

    The company is also developing AI-enabled research products, incorporating artificial intelligence into its analytical services and product development activities.

    Its business model combines recurring data product revenue with customised research projects and other analytics services.

  • Aptamer Group FY Revenue Rises 28% to £1.5 Million as Cash Reaches £4.4 Million

    Aptamer Group FY Revenue Rises 28% to £1.5 Million as Cash Reaches £4.4 Million

    Aptamer Group (LSE:APTA) reported a 28% increase in full-year revenue to £1.5 million, supported by demand for its Optimer technology and repeat development contracts with pharmaceutical customers.

    The AIM-listed biotechnology company also reported a year-end cash balance of £4.4 million following a £4.1 million equity fundraising, while its adjusted EBITDA loss widened slightly to £2.3 million as administrative expenses increased.

    The company said the additional funding provides visibility over its financing requirements into 2028, based on the board’s current expectations.

    Revenue growth reflected activity across Aptamer’s development services and commercial partnerships, including projects involving several of the world’s 20 largest pharmaceutical companies.

    The group develops synthetic binding molecules known as Optimers, which are designed for applications in drug development, diagnostics, therapeutic delivery and industrial biotechnology.

    During the financial year, Aptamer entered into royalty-bearing licensing agreements with Twist Bioscience and Alphazyme covering enzyme-modulating Optimer technology.

    The agreements provide a framework for potential royalty income associated with the licensed technology, although the supplied update did not disclose their financial terms or expected revenue contributions.

    The company also advanced work on folic acid testing technology supported by the Gates Foundation, targeting applications in food fortification testing.

    The programme forms part of Aptamer’s diagnostics activities, which use synthetic binders to identify and measure specific biological or chemical targets.

    Aptamer additionally completed a second development programme with Unilever, extending its work with the consumer goods company.

    The group has been developing commercial opportunities across pharmaceutical, diagnostic, enzyme and cosmetics applications, combining customer-funded research with licensing arrangements.

    Alongside these activities, Aptamer continued investing in its artificial intelligence-assisted discovery platform.

    The company said it accelerated development of the technology to support the identification and optimisation of Optimer binders for customer projects and internal development programmes.

    Additional automation was introduced to increase binder manufacturing capacity and support a greater volume of development and production activities.

    Aptamer also reported progress across several therapeutic delivery programmes, including work involving fibrotic liver tissue, kidney-targeting delivery vehicles and targeted radiotherapeutic applications.

    These programmes are intended to investigate the use of Optimer technology in directing therapeutic compounds towards specific biological targets.

    The company is developing these applications alongside its established fee-for-service activities, with the aim of creating technologies that could be licensed to commercial partners.

    Following the financial year-end, Aptamer reported an increase in its sales pipeline from £4.8 million to £7.0 million.

    The £2.2 million increase represents growth of approximately 45.8% in the value of prospective commercial opportunities identified by the company.

    The pipeline figure represents potential business opportunities rather than contracted revenue, and the timing and value of future agreements will depend on customer decisions and contract negotiations.

    Aptamer said it is working to establish multi-year master service agreements with several pharmaceutical customers.

    These arrangements are intended to provide a framework for recurring development work and potentially improve visibility over future project activity.

    The company is also pursuing the development of its own intellectual property assets in enzyme and cosmetics applications, with the intention of securing additional licensing opportunities.

    Management has identified a combination of service revenue, technology licensing and product supply as the basis of its commercial strategy.

    Aptamer continues to target adjusted EBITDA break-even, although the supplied update did not specify a timetable for achieving that objective.

    The company also appointed Cavendish Capital Markets as joint corporate broker following the year-end, adding to its capital markets advisory arrangements.

    With revenue increasing to £1.5 million and cash of £4.4 million at the reporting date, Aptamer is continuing to invest in its discovery technology, manufacturing capabilities and commercial development programmes.

    The group’s financial performance will depend on the conversion of prospective contracts into revenue, progress under existing customer agreements and the contribution from licensing and supply activities.

    About Aptamer Group Plc

    Aptamer Group plc is a UK-based biotechnology company listed on AIM under the ticker LSE:APTA.

    The company develops synthetic binding molecules known as Optimers, which are designed to recognise and bind to specific biological and chemical targets.

    Its technology is used in applications including pharmaceutical research, therapeutic delivery, diagnostics, enzyme modulation and cosmetics.

    Aptamer provides customised binder development services to biotechnology and pharmaceutical companies while also developing proprietary technologies for potential commercial licensing.

    The group’s business model combines fee-for-service research and development contracts, royalty-bearing licensing agreements and product supply activities.

    Its development programmes include targeted therapeutic delivery, radiotherapeutic applications and diagnostic testing technologies.

    Aptamer is also investing in artificial intelligence-assisted discovery methods and automated manufacturing processes to support binder development and production.

    The company works with commercial and research partners across the life sciences industry, including pharmaceutical businesses and organisations developing diagnostic and industrial biotechnology applications.