Author: Fiona Craig

  • Seeing Machines Accelerates Driver-Monitoring Expansion Ahead of EU Safety Rules

    Seeing Machines Accelerates Driver-Monitoring Expansion Ahead of EU Safety Rules

    Seeing Machines Limited (LSE:SEE) reported expected first-half FY2026 revenue in the range of US$23.4 million to US$24.0 million, slightly below the previous year as non-recurring engineering revenues declined. However, annualised recurring revenue increased to US$14.0 million, while adjusted EBITDA losses narrowed due to reduced operating costs.

    Cash balances stood at US$3.4 million as of 31 December 2025. Liquidity was subsequently strengthened by a US$14.1 million royalty payment received after the reporting period. Management is targeting positive adjusted EBITDA in the third quarter and the second half of FY2026, supported by cost efficiencies and growing recurring income.

    The automotive segment continued to expand in advance of the July 2026 implementation of the EU General Safety Regulation. The number of vehicles on the road equipped with the company’s Driver Monitoring System (DMS) and Occupant Monitoring System (OMS) rose 67% year on year. Production volumes increased 62%, while automotive royalty revenue climbed 43% to US$9.0 million.

    The company also secured new and expanded automotive programs in Europe and Japan. Additional growth initiatives include the rollout of impairment detection technology and a next-generation cabin perception platform. Meanwhile, rising Guardian aftermarket orders and the establishment of a new Future Mobility Group are expected to position Seeing Machines to benefit from increasing regulation-driven demand and expanding royalty streams.

    Despite operational progress, the outlook remains constrained by ongoing losses and negative operating cash flow, alongside weak short-term technical momentum. These challenges are partially balanced by management’s forward guidance, which highlights anticipated regulatory tailwinds and cost measures aimed at achieving cash-flow breakeven.

    More about Seeing Machines

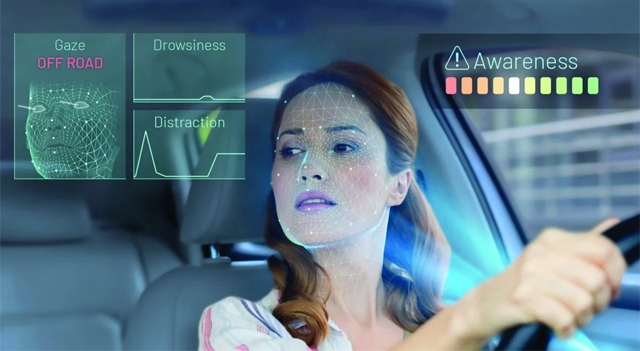
    Seeing Machines is an AIM-listed company headquartered in Australia, specialising in AI-powered, vision-based monitoring systems designed to enhance transport safety. Its technology integrates artificial intelligence, embedded processing and advanced optics to monitor driver gaze and cognitive state in real time. The company serves automotive manufacturers, commercial fleets, off-road operators and aviation customers with safety-focused monitoring solutions.

  • AFC Energy Cleared to Commercialise Hydrogen Output from Pilot Ammonia Cracker

    AFC Energy Cleared to Commercialise Hydrogen Output from Pilot Ammonia Cracker

    AFC Energy Plc (LSE:AFC) has obtained approval from the UK Environment Agency to amend its research and development permit, enabling the company to export and sell low-carbon hydrogen produced at its pilot ammonia cracking facility in Dunsfold.

    The updated permit confirms that the plant can generate ISO 14687 Grade D hydrogen at 99.97% purity and recognises the site’s safety standards, allowing operational staff to receive hands-on training in a live production environment.

    The regulatory change is expected to bring forward hydrogen-related revenues by several months and offers greater flexibility regarding the potential relocation of the Dunsfold pilot site, which has capacity to produce up to 300 kilograms of hydrogen per day.

    At the same time, AFC Energy is collaborating with joint venture partner Industrial Chemicals Group to roll out multiple Hy-5 ammonia cracker units at Port Clarence in Middlesbrough. The partners are also working to establish a permitting framework intended to streamline the future deployment of Hy-5 systems across the UK.

    By enabling commercial hydrogen sales from its demonstration facility and progressing plans for scaled deployment through its joint venture, AFC Energy is transitioning from development-stage activity toward revenue-generating operations. The milestone strengthens its positioning within the emerging low-carbon hydrogen sector and supports its ambition to build recurring income streams while assisting industrial and power users in reducing reliance on fossil fuels.

    The company’s outlook continues to be shaped by financial headwinds, particularly around profitability and cash flow. While technical indicators point to improving momentum, valuation concerns persist due to a negative price-to-earnings ratio and the absence of a dividend.

    More about AFC Energy

    AFC Energy Plc is a UK-based developer of ammonia-based low-carbon hydrogen production systems and hydrogen-to-power solutions, listed on AIM and headquartered in Dunsfold, Surrey. Its modular ammonia cracker technology and fuel cell generators are designed to provide scalable hydrogen supply and off-grid power for industrial, transport and temporary energy markets.

    The company’s product range includes ammonia crackers capable of producing between 0.5 and 4 tonnes of hydrogen per day, as well as fuel cell generators rated at 30 kW and 200 kW. These solutions are intended to replace diesel generators and contribute to decarbonisation in sectors such as heavy industry, transport, construction, EV charging, maritime, data centres and rail.

  • Petro Matad Unlocks Withheld Payments and Progresses Oil and Renewable Energy Projects in Mongolia

    Petro Matad Unlocks Withheld Payments and Progresses Oil and Renewable Energy Projects in Mongolia

    Petro Matad Limited (LSE:MATD) has settled a revenue dispute with PetroChina, securing $1.03 million in production payments from 2025 that had previously been withheld. The company said it is nearing completion of its 2026 Oil Sales Agreement while continuing stable production from its Heron-1 and Gazelle-1 wells on Block XX.

    Alongside its oil operations, Petro Matad is advancing discussions to farm out interests in Blocks XX and VII. It is also moving forward with a 200MW hybrid renewable energy project combining wind, solar and battery storage, in addition to developing green hydrogen and energy storage initiatives that could expand its footprint in Mongolia’s developing clean-energy export market.

    Its renewable subsidiary, SunSteppe Renewable Energy, has completed key feasibility assessments, environmental studies and grid connection work for the 200MW hybrid project in Tuv Province. The project is targeting Ready-to-Build status in 2026, with reported interest from international partners.

    Work continues on green hydrogen developments at Oyu Tolgoi and a 50MW battery energy storage system (BESS) project in Choir, although progress has been slower than initially anticipated. Cross-border collaboration with Chinese and Saudi partners is also underway, supporting Mongolia’s positioning as a potential regional exporter of renewable electricity.

    The company’s financial outlook remains pressured by weak profitability and persistently negative—and deteriorating—free cash flow, despite strong revenue growth. However, Petro Matad maintains a low-debt balance sheet that provides some resilience. Technical indicators appear mixed to neutral, and valuation remains constrained due to ongoing losses and the absence of dividend data.

    More about Petro Matad

    Petro Matad Limited is an AIM-listed oil exploration and production company focused on Mongolian assets, particularly Block XX and Block VII. Through its SunSteppe Renewable Energy division, the group is also developing a portfolio of large-scale renewable power, green hydrogen and battery storage projects aimed at serving Mongolia’s domestic demand and potential cross-border energy exports.

  • Beacon Energy Plans Reverse Takeover of LNEnergy and £3.79m Capital Raise

    Beacon Energy Plans Reverse Takeover of LNEnergy and £3.79m Capital Raise

    Beacon Energy plc (LSE:BCE) has released an admission document detailing a proposed reverse takeover involving the acquisition of a substantial strategic stake in LNEnergy Limited. The transaction is paired with a conditional equity fundraising of £3.79 million through the issuance of 97,191,443 new shares priced at 3.9 pence each.

    If completed, the enlarged share capital would total 124,790,040 shares, implying a post-admission market capitalisation of approximately £4.87 million. The company said the move is designed to secure access to proven reserves and accelerate its path toward production, representing a significant milestone in its expansion strategy.

    The proposal is subject to shareholder approval at an extraordinary general meeting scheduled for 5 March 2026. Subject to approval, the readmission of the expanded share capital to AIM is expected on 6 March 2026, with definitive share certificates anticipated by 13 March.

    Management cautioned that failure to pass the interdependent resolutions relating to both the acquisition and the fundraising would result in the transaction being abandoned. In such a scenario, the company warned that securing alternative financing or an alternative transaction in the near term would be unlikely, and its existing AIM listing could be cancelled, potentially leading to administration.

    More about Beacon Energy plc

    Beacon Energy plc is an AIM-listed oil and gas exploration and production company focused on upstream energy assets. The group seeks strategic acquisitions capable of delivering proven reserves, near-term production and value-enhancing catalysts, positioning itself as a small-cap energy player pursuing growth through deal-making and capital markets activity.

  • NextEnergy Solar Fund Maintains Dividend Target as Lower Power Prices Weigh on NAV

    NextEnergy Solar Fund Maintains Dividend Target as Lower Power Prices Weigh on NAV

    NextEnergy Solar Fund Limited (LSE:NESF) reported a drop in its unaudited third-quarter net asset value, with NAV per ordinary share declining to 84.9p. The decrease was mainly attributed to softer third-party power price assumptions and weaker winter irradiation, which left UK generation 12.9% below budget.

    Taking into account the forthcoming impact of the UK government’s decision to shift Renewable Obligation Certificates (ROC) and Feed-in Tariff (FiT) inflation indexation from RPI to CPI, year-end NAV would have stood at 82.9p. Despite these pressures, the board reaffirmed its full-year dividend target of 8.43p per share, with forecast dividend cover of between 1.1x and 1.3x, highlighting its continued focus on delivering income amid challenging market conditions.

    The fund’s capital recycling strategy and recent asset disposals have generated £72.5 million to date, contributing a positive uplift to NAV and supporting efforts to manage leverage. Gearing currently sits just under the 50% debt-to-GAV threshold, although a depressed share price has pushed the enterprise value (EV) gearing ratio above 50%.

    Management intends to further reduce leverage through additional asset sales and repayment of its revolving credit facility (RCF). A broader strategic review, scheduled to be presented to investors in March, is aimed at strengthening long-term value. This will be underpinned by the fund’s Article 9 sustainability classification and its ongoing commitment to biodiversity initiatives and strong ESG standards across its supply chain.

    The outlook remains constrained by sharply weaker operating performance, including falling revenues and two consecutive years of net losses, alongside negative technical indicators, with the share price trading below key moving averages and a bearish MACD signal. These headwinds are partly offset by improving operating cash flow, a debt-free balance sheet expected in 2025, and a high dividend yield, though these positives do not fully counterbalance earnings pressure and weak momentum trends.

    More about NextEnergy Solar Fund Limited

    NextEnergy Solar Fund Limited is a publicly listed specialist investor in utility-scale solar and energy storage assets, primarily located in the UK. The portfolio comprises more than 100 operating solar projects with significant installed capacity and long remaining asset lives, generating inflation-linked income from government-backed subsidies and electricity sales into the UK power market.

  • Centaur’s Influencer Intelligence Partners With Smartzer to Launch Shoppable Influencer Video Solution

    Centaur’s Influencer Intelligence Partners With Smartzer to Launch Shoppable Influencer Video Solution

    Centaur Media plc (LSE:CAU) announced that its Influencer Intelligence division has formed a strategic alliance with Smartzer, bringing together influencer analytics capabilities with interactive shoppable video technology to help brands drive measurable sales from social media engagement.

    The partnership is aimed at companies looking to translate influencer-driven content into trackable revenue streams as social commerce continues to expand.

    Under the agreement, the two firms will introduce a new offering enabling creators to quickly transform their content into shoppable video landing pages that can be shared across leading social platforms. By combining data-driven influencer selection, scalable interactive video formats and comprehensive performance tracking, the initiative seeks to convert influencer campaigns into fully integrated, measurable commerce experiences.

    Centaur Media’s overall outlook reflects a mixed profile. Financial performance has been under pressure, though this is partially offset by constructive technical signals and ongoing strategic initiatives. While valuation remains challenged due to negative earnings, the company’s elevated dividend yield offers some investor appeal. Recent corporate actions, including asset disposals and plans to return capital to shareholders, have supported sentiment by underscoring management’s focus on enhancing shareholder value.

    More about Centaur Media

    Centaur Media plc is a UK-based media and information group. Its portfolio includes Influencer Intelligence, a data-led platform specialising in influencer and talent analytics for brands and marketers. The company supports advertisers, agencies and brand owners seeking to optimise creator partnerships and measure campaign performance in the rapidly growing digital and social commerce sectors.

  • Galliford Try Awarded Spot on £15.4bn Education Construction Framework

    Galliford Try Awarded Spot on £15.4bn Education Construction Framework

    Galliford Try (LSE:GFRD) has been appointed to the Department for Education’s new £15.4 billion Construction Framework 25, securing positions for its Building division across multiple project categories.

    The framework covers major schemes valued above £12 million throughout England, as well as smaller-scale projects in London, the South East and South West. Spanning six years, with options to extend, the agreement reinforces Galliford Try’s presence in the UK education sector and aligns with its strategy of sustainable, long-term growth.

    The award strengthens the group’s partnership with the Department for Education and enhances visibility over its future pipeline of school and college developments.

    The appointment highlights Galliford Try’s ongoing role in delivering large-scale education infrastructure and builds on its track record of providing high-quality learning environments nationwide. By securing places on both higher- and lower-value lots, the company positions itself to compete for a broad range of upcoming projects, supporting revenue stability and reinforcing its standing among public-sector contractors.

    Galliford Try’s outlook reflects supportive technical trends and a sound financial base, despite pressures on revenue expansion and margins. Its ongoing share buyback programme further underpins shareholder returns, appealing to investors seeking dependable income and relative stability.

    More about Galliford Try

    Galliford Try is a UK-based construction group listed on the London Stock Exchange and a constituent of the FTSE 250. Operating under the Galliford Try and Morrison Construction brands, the company delivers building and infrastructure projects for public, private and regulated-sector clients across the UK. Education remains a key and long-established segment within its construction portfolio.

  • Great Southern Copper Expands High-Grade Copper-Silver Footprint at Cerro Negro

    Great Southern Copper Expands High-Grade Copper-Silver Footprint at Cerro Negro

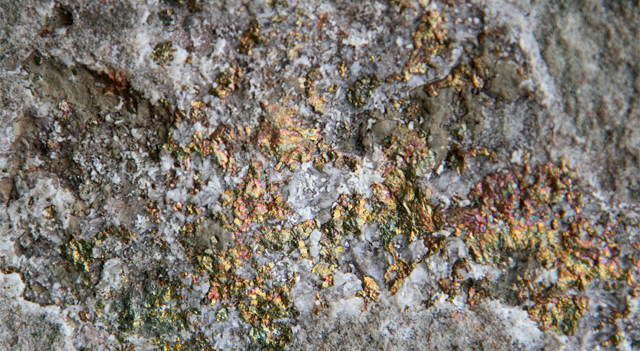
    Great Southern Copper PLC (LSE:GSCU) announced new Phase III drilling results from its Cerro Negro prospect in Chile, confirming the presence of multiple stacked high-grade copper-silver lenses at the Mostaza deposit and indicating that mineralisation continues to widen both at depth and along strike.

    Recent diamond drill holes DD033, DD036 and DD034 delivered notable copper-silver intersections within a broader zone of lower-grade material. The presence of associated lead-zinc mineralisation supports the interpretation of a zoned system that may extend beyond 80 metres in overall thickness.

    The latest findings significantly increase the perceived scale and copper potential of the Mostaza discovery. The results point to both high-grade lens-style mineralisation and larger bulk-tonnage opportunities, potentially strengthening the long-term economic prospects of the project.

    The company is now preparing for a Phase IV drilling campaign focused on resource definition and further exploration. Additional Phase III assay results, along with metallurgical testing, are still pending and are expected to help refine the geological model and prioritise the most prospective drill targets.

    The company’s near-term outlook remains influenced by its financial profile, characterised by pre-revenue operations, expanding losses and ongoing negative free cash flow, although it carries no reported debt. Technical indicators appear mixed to weak, with the share price trading below its 20-day moving average and momentum signals subdued. Valuation metrics such as P/E ratio and dividend yield are not currently applicable.

    More about Great Southern Copper PLC

    Great Southern Copper is a London-listed exploration company focused on copper, gold and silver assets in Chile. Its flagship Especularita project includes the Cerro Negro prospect and the historic Mostaza mine. The project benefits from low elevation and proximity to established mining infrastructure. The company holds an option to acquire a 100% interest in the Cerro Negro project.

  • Carrefour Unveils New Strategy to Lift Cash Flow and Margins

    Carrefour Unveils New Strategy to Lift Cash Flow and Margins

    Carrefour (EU:CA), Europe’s largest retailer, announced plans on Monday to enhance cash generation and improve profitability under a fresh strategic roadmap led by Chief Executive Alexandre Bompard.

    The group is targeting an operating margin of 3.2% by 2028, rising to 3.5% by 2030, as part of a broader effort to sharpen its focus on core markets including France, Spain and Brazil.

    Ahead of a scheduled investor presentation, Carrefour said it expects to generate cumulative net free cash flow of €5 billion over the 2026–2028 period.

    Bompard, who is set to outline his third strategic plan since assuming leadership in July 2017, said: “Carrefour is today adopting an ambitious new strategic plan, radically focused on growth and improving profitability.”

    The CEO now faces the task of steering the company through another turnaround phase, as the French retail market remains intensely competitive and consumer demand continues to be subdued in both France and Brazil.

    Carrefour’s operating margin has steadily eroded since the onset of the pandemic, slipping from 3.1% in 2021 to 2.6% in 2025.

    Despite two earlier strategic overhauls, Carrefour’s share price remains nearly 29% below its level when Bompard took charge of the company in July 2017.

  • Fed Minutes Loom; Palo Alto Networks Drops – What’s Driving Markets: Dow Jones, S&P, Nasdaq, Wall Street Futures

    Fed Minutes Loom; Palo Alto Networks Drops – What’s Driving Markets: Dow Jones, S&P, Nasdaq, Wall Street Futures

    U.S. stock futures ticked higher early Wednesday as investors awaited the release of the Federal Reserve’s January meeting minutes and reviewed the latest corporate updates. Shares of cybersecurity firm Palo Alto Networks (NASDAQ:PANW) declined after issuing softer-than-expected earnings guidance. Meanwhile, Warren Buffett’s final quarter at the helm of Berkshire Hathaway (NYSE:BRK.B) featured significant portfolio adjustments, including reductions in major technology and banking holdings.

    Futures edge up

    By 02:43 ET, Dow Jones futures were up 55 points, or 0.1%. S&P 500 futures gained 12 points, or 0.2%, while Nasdaq 100 futures slipped 35 points, or 0.1%.

    Wall Street’s main indices closed higher in the prior session, helped by a modest recovery in technology stocks that had recently been under pressure. Strength in Nvidia (NASDAQ:NVDA) and Apple (NASDAQ:AAPL) offset weakness in Microsoft (NASDAQ:MSFT) and Oracle (NYSE:ORCL), lifting the S&P 500 information technology sector by 0.5%.

    However, uncertainty continues to surround the tech sector following the rollout of new artificial intelligence tools. Some investors are concerned that AI advancements could disrupt industries spanning software, financial services, real estate, and logistics.

    There are also lingering questions about when heavy spending on AI-focused data centers will begin to generate meaningful returns, especially as large-cap tech companies have outlined substantial capital commitments to infrastructure supporting AI systems.

    “Tech investors remain traumatized by the volatility of the last several weeks and the shifting AI conversation, although there is growing anticipation for Nvidia’s earnings report next week (which most people expect will be strong) while software is still firmly in the penalty box despite the extremely oversold price action,” analysts at Vital Knowledge said.

    Focus on Fed minutes

    The minutes from the Federal Reserve’s January policy meeting, scheduled for release later Wednesday, are expected to provide additional insight into the central bank’s rate outlook.

    At that meeting, two officials—Stephen Miran and Christopher Waller—voted against the decision to keep rates unchanged, effectively pausing the easing cycle that began in mid-2024.

    Policymakers pointed to a resilient labor market and inflation that remains above target but is stabilizing as reasons to hold rates within the 3.5% to 3.75% range.

    Markets widely expect the Fed to maintain this range at least through June, adopting a cautious stance as it evaluates incoming data on jobs and inflation.

    Fed Chair Jerome Powell is nearing the end of his term, and President Donald Trump has nominated former Fed Governor Kevin Warsh as his successor. Investors are assessing how a leadership change might influence future rate decisions.

    Oil rebounds on US–Iran developments

    Oil prices posted modest gains after sliding nearly 2% in the prior session, as signs of progress in U.S.–Iran nuclear talks helped ease concerns over potential supply disruptions.

    As of 02:58 ET, Brent crude futures for April delivery rose 0.3% to $67.61 per barrel, while West Texas Intermediate (WTI) crude futures gained 0.2% to $62.40 per barrel.

    Brent had fallen almost 2% on Tuesday, while WTI dropped 1%.

    Reports suggested that U.S. and Iranian negotiators agreed on key “guiding principles” during talks in Switzerland, raising hopes for a deal that could eventually bring additional Iranian oil to global markets.

    Still, Iran’s foreign minister cautioned that the understanding does not signal that a comprehensive agreement is close.

    Palo Alto Networks declines on guidance

    Palo Alto Networks (NASDAQ:PANW) shares fell in after-hours trading despite posting better-than-expected quarterly results, as investors reacted to weaker profit guidance.

    The Santa Clara-based cybersecurity company reported fiscal second-quarter earnings of $1.03 per share on revenue of $2.59 billion, beating analyst forecasts of $0.94 per share on $2.58 billion in revenue.

    However, the company revised its fiscal 2026 earnings per share outlook to a range of $3.65 to $3.70, down from a previous forecast of $3.80 to $3.90. The consensus estimate had been $3.87.

    Berkshire trims Apple and Bank of America stakes

    Berkshire Hathaway (NYSE:BRK.B) reduced its holdings in Apple and Bank of America (NYSE:BAC) and initiated a new investment in New York Times (NYSE:NYT) during Warren Buffett’s final quarter as chief executive.

    A regulatory filing showed that Berkshire sold about 10.3 million Apple shares in the quarter ended December 31, marking the third consecutive quarter of reductions in its stake. The conglomerate also cut its position in Bank of America by 50.8 million shares.

    At the same time, Berkshire purchased roughly 5.1 million shares of New York Times, backing a company that has expanded beyond traditional news publishing into digital subscription offerings such as games and recipes.

    Buffett, 95, stepped down as CEO at the end of 2025, handing over leadership to his chosen successor, Greg Abel, who is set to deliver his first annual shareholder letter later this month.