Man Group (LSE:EMG) shares advanced on Thursday after Citigroup upgraded the investment manager to Buy from Neutral and increased its price target to 390 pence from 335 pence, citing improving investment performance and expectations of higher earnings.
The shares gained 0.9% to 329.86 pence, outperforming the broader UK mid-cap market, with FTSE 250 futures declining approximately 0.8%.
Citi said Man Group’s investment fundamentals had strengthened despite the company’s valuation multiple declining during the year. According to the broker, Man was the only traditional asset manager within its coverage to experience a valuation de-rating in 2026 while earnings estimates and underlying business indicators improved.
The bank identified increasing demand for liquid alternative investment strategies as a potential source of growth for Man Group, particularly as market volatility creates opportunities for investment managers operating across different asset classes.
Citi expects improved fund performance to support client inflows, management fee margins and profitability.
The broker forecast adjusted profit before tax of £899 million for the 2026 financial year, approximately 33% above market consensus estimates.
For 2027, Citi projected adjusted pre-tax profit of £742 million, representing an 8% premium to consensus expectations.
Revenue for 2026 is forecast to reach £2.16 billion, around 15% above consensus, with performance-related fees expected to contribute significantly to the company’s financial results.
Citi also projected continued growth in assets under management, forecasting €273.8 billion for 2026, approximately 3% ahead of consensus estimates.
For 2027, the bank expects assets under management to increase to €305.2 billion, exceeding current market forecasts by approximately 5%.
The broker anticipates that net client flows will remain stronger than consensus expectations, supported by investment performance and demand for alternative investment products.
Citi highlighted Man Group’s comparative investment performance, noting that 96% of its assets measured over a three-year period were invested in funds ranking within the top two performance quartiles as of September 2026.
According to the bank, this represented the strongest investment performance among the traditional asset managers included in its research coverage.
The upgrade reflects Citi’s assessment that Man Group’s earnings potential is not fully reflected in its current valuation, particularly given the expected contribution from performance fees and continued growth in assets under management.
Man Group is a London-listed global investment management company specialising in active investment strategies, including quantitative, discretionary and alternative investment approaches. The group manages assets for institutional and private investors across international markets.
Standard Life (LSE:SDLF) shares declined 5% on Thursday after Aberdeen Group (LSE:ABDN) announced plans to sell approximately half its holding in the UK insurer through an institutional share placing.
The insurer’s shares initially fell as much as 7.7% before recovering part of their losses, as investors assessed the potential impact of the proposed disposal on the market.
Aberdeen intends to sell approximately 52 million ordinary shares in Standard Life, representing around 5.2% of the insurer’s issued share capital.
Before the transaction, Aberdeen held approximately 104.1 million Standard Life shares, equivalent to a 10.3% ownership interest. Following the proposed sale, the asset manager expects to retain approximately 52.1 million shares, representing a stake of around 5.2%.
The disposal is being conducted through an accelerated bookbuild, allowing institutional investors to submit orders for the shares over a shortened marketing period.
The bookbuilding process commenced immediately following Aberdeen’s announcement, with the results expected to be published on Thursday before the London Stock Exchange opened.
Completion of the placing remains dependent on investor demand, the final sale price and prevailing market conditions.
Aberdeen said the proceeds would be allocated in accordance with its existing capital management policy, which prioritises maintaining a strong balance sheet, selective investment in its operations, debt optimisation and shareholder distributions.
The group has previously announced plans to redeem £210 million of Additional Tier 1 debt at its first available call date in December 2026.
That planned redemption was disclosed alongside Aberdeen’s half-year results for 2026 and forms part of the company’s wider approach to managing its capital structure.
Despite the reduction in its shareholding, Aberdeen intends to maintain its commercial relationship with Standard Life.
The two companies have maintained a strategic partnership since 2018, with the arrangement subsequently simplified and extended in February 2021.
Aberdeen will continue to act as an asset management partner to Standard Life following the proposed share disposal.
Aberdeen Chief Executive Jason Windsor said the transaction represents further progress in simplifying the group’s structure as it pursues its objective of becoming a leading UK wealth and investments business.
The planned sale reduces Aberdeen’s direct equity exposure to Standard Life while preserving the asset management relationship between the two companies.
Standard Life is a UK insurance, pensions and retirement savings business, while Aberdeen Group provides investment management and wealth services. Both companies are listed on the London Stock Exchange.
Next 15 Group (LSE:NFG) shares declined approximately 10% on Thursday after the marketing and technology consultancy reported a reduction in first-half revenue and a pre-tax loss, compared with a profit in the corresponding period last year.
The company recorded net revenue of £214.9 million for the six months ended 31 July 2026, down 6.9% from £230.8 million a year earlier. On a like-for-like basis at constant exchange rates, revenue declined 1.3%.
Next 15 reported a pre-tax loss of £1.5 million, compared with a profit of £15.8 million in the prior-year period. The company attributed the change principally to ongoing litigation expenses and acquisition accounting-related costs.
Diluted earnings per share moved to a loss of 3.4 pence from earnings of 10.4 pence a year earlier.
Adjusted operating profit was £32.1 million, compared with £32.7 million in the previous year. Despite the reduction in profit, the adjusted operating margin increased to 14.9% from 14.2%, which the company attributed to cost management measures.
Net debt increased to £57.3 million from £45.3 million, reflecting payments relating to acquisition earn-outs, taxation and capital expenditure.
The board maintained the interim dividend at 4.75 pence per share, payable on 20 November 2026 to shareholders registered on 16 October.
Next 15 also provided an update on the arbitration proceedings concerning its former Mach49 business. The arbitration hearing has concluded, and the company is awaiting a decision.
The group continues to dispute payment of the remaining acquisition earn-out and has submitted a counterclaim seeking recovery of earn-out amounts previously paid.
Chief Executive Officer Sam Knights said the company expects a ruling “within this financial year.”
Looking ahead, Next 15 expects to deliver like-for-like revenue growth for the full financial year, with total revenue and adjusted operating profit anticipated to remain in line with market expectations.
However, the company said the composition of its financial performance is expected to differ from earlier assumptions. Growth in digital transformation has exceeded expectations, while business disposals and a slower recovery in certain other segments have affected the overall revenue mix.
The group reported three consecutive months of organic revenue growth between June and August, marking its first such period in three years.
Within its portfolio, the six businesses classified as Track 1 generated like-for-like revenue growth of 1.8%, with an operating margin of 18.4%.
Digital transformation was the principal contributor to growth in this category, recording a 26.8% increase in revenue.
Next 15 has also continued restructuring its business portfolio, reducing the number of operating businesses from 22 to 10.
Group headcount declined 5% to 3,198 employees as part of the changes to its operating structure.
The company additionally stated that it had not experienced any material adverse impact from the conflict in the Middle East.
Next 15 Group is a London-listed marketing and technology consultancy providing services across digital transformation, marketing, communications and business consulting. The company operates through a portfolio of specialist businesses serving corporate clients across international markets.
Wise (LSE:WISE) shares declined 2.6% on Thursday following a Financial Times report that the financial technology company plans to cover potential customer tax liabilities arising from incorrect statements issued through its Wise Asset investment service.
According to the report, Wise contacted approximately 4,000 UK customers this week after identifying errors in tax statements covering the period from 2021 to 2025.
The inaccuracies resulted from calculations produced by third-party software used to determine capital gains and investment income from stocks and funds. These figures are relevant to customers’ tax declarations to HM Revenue & Customs (HMRC).
The Financial Times reported that Wise is negotiating a bulk settlement with HMRC to address any tax shortfalls resulting from the incorrect statements. The company also intends to compensate customers who paid more tax than required because of the errors.
Wise indicated that receiving an incorrect statement did not necessarily mean a customer had submitted an inaccurate tax return, as individual tax liabilities depend on personal circumstances.
The company said it has corrected the software issue and provided revised statements to affected customers.
According to the report, Wise stated that it had resolved the problem and was taking steps to address potential customer liabilities. The company also said there was no continuing risk to customers from the identified issue.
Wise Asset, which allows customers to invest in stocks and funds through the company’s platform, has attracted approximately US$9 billion in customer investments globally.
The tax reporting issue follows separate regulatory developments involving Wise during 2026.
In June, Belgian authorities opened an investigation into potential money laundering offences involving the company, including whether its accounts had been used by international criminal organisations. The investigation concerns possible offences, and the supplied report does not establish any finding of wrongdoing by Wise.
In July, US regulators rejected Wise’s application for a banking licence, citing deficiencies in its anti-money laundering controls.
The latest disclosure concerns the accuracy of historical customer tax statements rather than the underlying investment holdings within Wise Asset.
Wise is a London-listed financial technology company providing international money transfers, multicurrency accounts and investment services. Its Wise Asset offering enables eligible customers to invest through the company’s digital platform.
Pennon Group (LSE:PNN) shares rose 1.5% in London trading on Thursday, recovering part of the previous session’s decline of more than 20%, after the UK water utility announced a fully underwritten rights issue of approximately £550 million and a reduction in its dividend.
The fundraising forms part of a revised investment programme under the company’s new chief executive, with Pennon planning approximately £1 billion in additional capital expenditure across its regulated water businesses.
Total investment during the AMP8 regulatory period is now expected to reach approximately £3.6 billion, around £1 billion above the company’s original spending plan.
Pennon said it intends to identify operational efficiencies during the investment programme and reinvest the resulting savings into its regulated businesses. Full details of the rights issue are provided in a separate announcement and offering circular.
Alongside the fundraising, the company announced plans to reduce its total dividend for the 2026/27 financial year to approximately £125 million, compared with £138 million previously.
The reduction will apply to both interim and final dividend payments. After accounting for the lower total distribution and the additional shares issued through the rights issue, Pennon estimates an underlying reduction in dividend per share of approximately 30%.
The company expects the revised dividend to amount to around 18 pence per share and intends to increase future payments in line with the Consumer Prices Index including owner occupiers’ housing costs (CPIH), using the reduced dividend as the starting point.
Part of the additional capital expenditure could be reflected in an increase in Pennon’s regulatory capital value through Ofwat’s cost change assessment process.
In its draft decision for the 2026 assessment round, the water regulator provisionally approved £230 million of additional expenditure, equivalent to 76% of the amount requested by Pennon.
Ofwat is expected to publish its final decision by 15 December 2026.
Pennon also anticipates seeking approval for approximately £170 million of further investment through the 2027 and 2028 regulatory assessment rounds. These amounts remain subject to regulatory approval.
The company is targeting a total increase of £400 million in regulatory capital value through the cost change process.
Separately, Pennon plans to dispose of its Pennon Power business as part of its capital management programme.
The group intends to allocate approximately £25 million of the disposal proceeds towards renewable electricity generation at its operational sites, using behind-the-meter installations designed to supply power directly to those facilities.
The remaining proceeds are expected to be used to reduce group debt.
Pennon has also outlined its leverage objectives for the AMP8 period, targeting debt within its regulated water businesses at no more than 65% of regulatory capital value.
This remains within the company’s long-term policy range of 55% to 65%.
At group level, debt measured against regulatory capital value is expected to remain several percentage points higher than the regulated business measure, although Pennon considers it unlikely to exceed approximately 70%.
The revised investment programme, dividend policy and asset disposal plans form part of Pennon’s operational and financial restructuring as it increases spending on its regulated water infrastructure.
Pennon Group is a UK-listed water utility company operating regulated water businesses. Its activities include water supply, wastewater services and infrastructure investment, with capital expenditure and financial performance subject to regulatory oversight.
Greenland Mines Ltd (NASDAQ:GRML), (FSE: HK6) is bringing together two significant critical minerals opportunities in Greenland, combining its established Skaergaard palladium-gold-platinum project with the newly acquired Sarfartoq neodymium-praseodymium rare earths project.
The combination gives the company exposure to two strategically important areas of the critical minerals market while establishing the foundations of a broader North Atlantic minerals platform.
The strategy has moved forward significantly during 2026. Greenland Mines has advanced technical work at Skaergaard, completed the acquisition of Sarfartoq and continued to develop plans connecting Greenland’s mineral resources with potential downstream processing and industrial markets in Europe and North America.
A Major Palladium, Gold and Platinum Opportunity
At the heart of Greenland Mines’ portfolio is the Skaergaard Project in southeast Greenland, a large-scale mineral system containing palladium, gold and platinum, alongside potential critical-metal by-products.
The company’s 2026 S-K 1300 Mineral Resource Estimate reported 15.0 million ounces of palladium equivalent in the Indicated category and a further 17.49 million ounces in the Inferred category. The Indicated resource includes approximately 7.57 million ounces of palladium, 3.19 million ounces of gold and 0.60 million ounces of platinum.
These figures are from the Skaergaard Technical Report Summary prepared by SLR Consulting (Canada) Ltd., with a Mineral Resource Estimate effective July 3, 2026. Palladium-equivalent (PdEq) is a calculated measure based on the report’s metal-price and recovery assumptions; it is not a quantity of contained palladium.
Importantly, Greenland Mines is continuing to add technical understanding to the resource rather than simply relying on its existing scale.
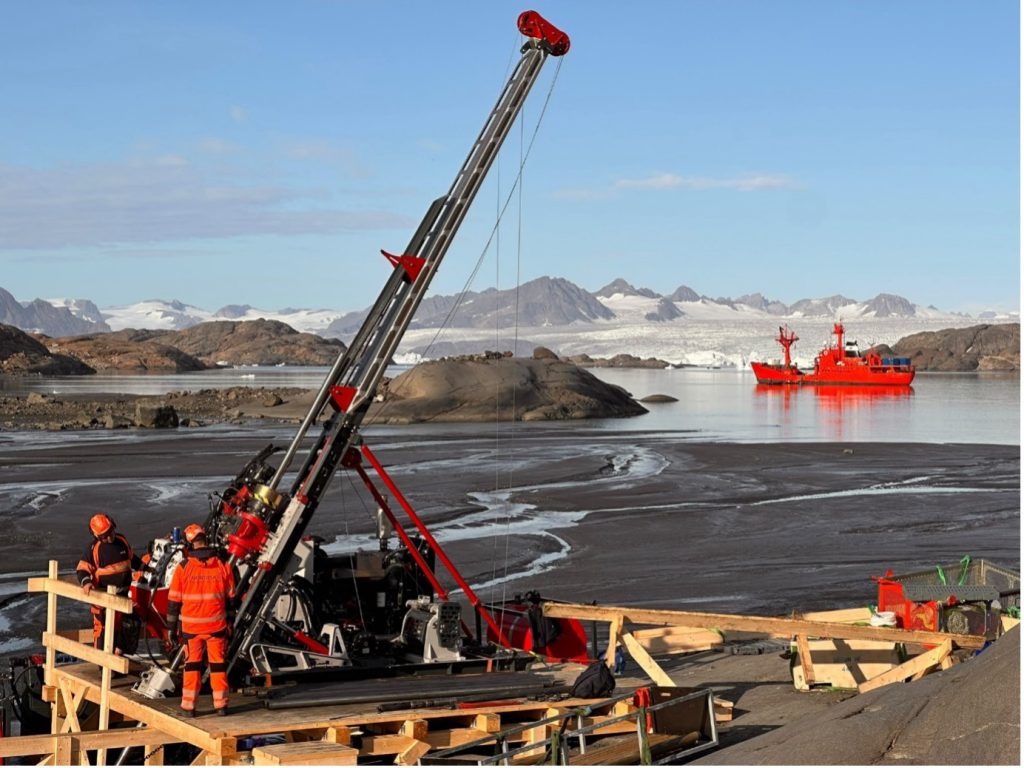
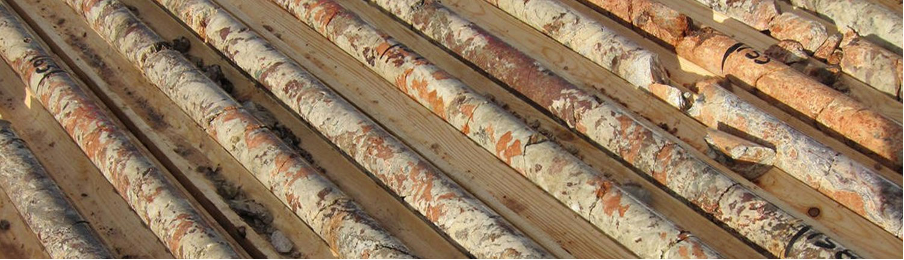
Its 2026 field programme included drilling, geotechnical work, geophysical surveys, environmental studies and bulk sampling. The company completed 4,480 metres of diamond drilling across 17 holes, together with more than nearly 105 tonnes of bulk material, providing materials for advanced metallurgical and process flow-sheet bench and pilot plant test-work.
The bulk-sampling programme itself exceeded the original plan, with 104.8 tonnes of material collected from seven sites. The samples cover different mineralised horizons.
This work represents an important step as Greenland Mines continues to evaluate and advance the Skaergaard Project towards production.
Sarfartoq Adds a Second Critical Minerals Opportunity
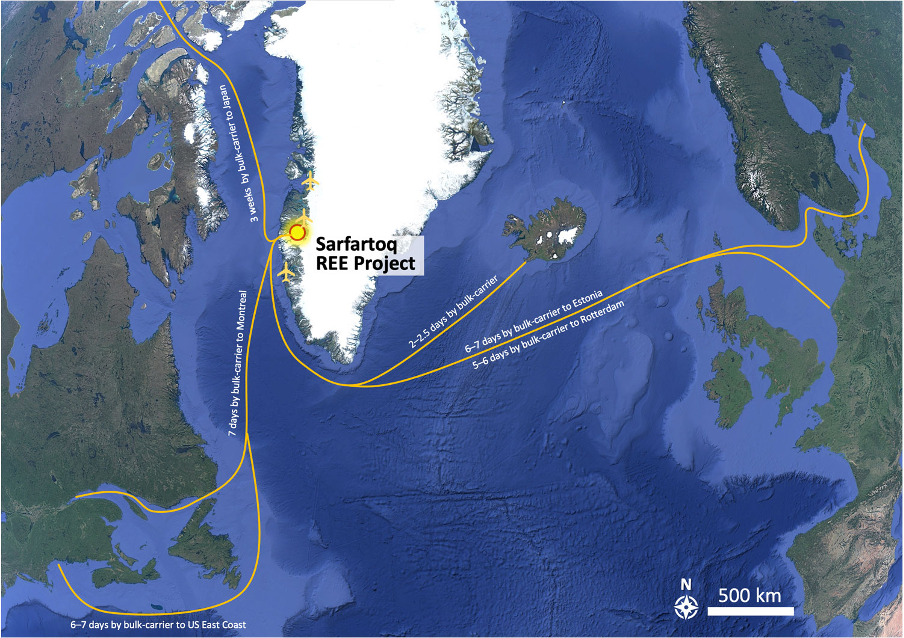
The company’s strategy became considerably broader with its acquisition of the Sarfartoq rare earth project in southwest Greenland, which closed in September 2026.
Sarfartoq is focused particularly on neodymium and praseodymium, two magnet rare earth elements that are important components in permanent magnets used in electric vehicles, wind turbines, robotics, defence systems and other advanced technologies.
The project has an extensive exploration history, with more than 15 years of drilling, metallurgical testing, engineering studies and environmental work.
In August, Greenland Mines announced an independently prepared S‑K 1300 Technical Report Summary for Sarfartoq, effective July 31, 2026, reporting an Indicated Mineral Resource under S‑K 1300 for the first time.
The resource is particularly notable for its concentration of the magnet rare earth elements that are most important to today’s supply chains.
Greenland Mines also has an important strategic relationship with Neo Performance Materials, which retains offtake rights covering up to 60% of future Sarfartoq ore or mineral concentrate production, subject to the relevant project development conditions.
That relationship provides the project with a potential connection into Western rare earth processing and magnet supply chains.
Two Projects, One Broader Strategy
The combination of Skaergaard and Sarfartoq gives Greenland Mines a differentiated portfolio.
Skaergaard provides exposure to palladium, gold and platinum, while Sarfartoq adds exposure to neodymium, praseodymium and other rare earth elements.
This diversification is important because the company is not dependent on a single commodity or project.
Instead, Greenland Mines is building a portfolio around minerals that are increasingly important to energy, technology, defence and advanced manufacturing.
The company is also pursuing a broader North Atlantic critical minerals strategy, seeking to connect Greenland’s resource base with potential processing, logistics and industrial infrastructure in the wider region. Its strategy includes potential downstream opportunities in Iceland, where it has been developing relationships around industrial infrastructure.
Moving Towards the Next Stage
The focus now turns to advancing both projects through their next technical milestones.
At Skaergaard, the completed 2026 field programme provides additional drilling, sampling, geological, metallurgical and engineering information that can feed into the next phase of development work.
At Sarfartoq, Greenland Mines is progressing work around resource upgrading, engineering, infrastructure assessment and metallurgical testing, with the company targeting further advancement towards a Pre-Feasibility Study.
The company is therefore entering the next stage with a substantially broader portfolio than it had at the beginning of 2026.
For investors looking at the critical minerals sector, Greenland Mines offers an interesting combination: a large-scale palladium-gold-platinum resource at Skaergaard and an advanced rare earth opportunity at Sarfartoq, both located in Greenland and supported by a strategy designed to connect resources with Western supply chains.
With the two projects now sitting within a single platform, Greenland Mines is positioning itself around some of the mineral resources that could play an increasingly important role in the future of energy, technology, defence and industrial manufacturing.
Cautionary Note on Project Development Greenland Mines’ projects remain at the exploration and development stage. Neither project is in production, and their advancement depends on further technical studies, metallurgical evaluation, permitting, financing and execution. No Initial Assessment or Pre-Feasibility Study has been completed for Skaergaard. Sarfartoq has an Initial Assessment, but further studies and development work remain necessary, and there is no assurance that either project will reach production.
ITM Power (LSE:ITM) has revised its financial guidance for the year ended 30 April 2026, reducing its expected adjusted EBITDA loss to between £20 million and £21 million while maintaining its previous revenue and cash guidance.
The hydrogen technology company said the revised loss forecast represents a 27% improvement compared with its earlier guidance and a 38% improvement year on year.
The adjustment indicates that ITM expects to report a smaller adjusted operating loss before interest, tax, depreciation and amortisation than previously anticipated. The company has not announced any changes to its revenue or year-end cash expectations.
ITM confirmed that it will publish its preliminary financial results for the year ended 30 April 2026 on 19 October 2026.
The results announcement will provide further details of the company’s financial performance during the reporting period, including its revenue, operating costs and cash position.
The company also plans to engage with analysts and investors in connection with the results publication, providing an opportunity to discuss its financial performance and operational developments.
The revised guidance follows ITM’s ongoing activities in the development and manufacture of proton exchange membrane (PEM) electrolysers, which use electricity to separate water into hydrogen and oxygen.
The company’s technology is designed for industrial-scale hydrogen production, with applications across industrial and energy markets seeking alternatives to conventional hydrogen production methods.
ITM also operates through its Hydropulse business model, under which it intends to develop, own and operate hydrogen production facilities rather than solely supplying electrolyser equipment to customers.
The forthcoming preliminary results will provide additional information on the company’s financial position and progress against its operational objectives.
ITM Power is a UK-based manufacturer of hydrogen production equipment listed on London’s AIM market. Its operations include electrolyser manufacturing, engineering and the development of hydrogen supply solutions using proprietary PEM technology.
Jubilee Metals Group (LSE:JLP) has completed legal due diligence for the proposed sale of its Large Waste Project in Zambia, a transaction valued at approximately US$35 million, as the company continues its programme of asset disposals and investment in its Zambian copper operations.
The company expects to receive a deposit of US$2.25 million in the coming days, coinciding with the commencement of a 45-day technical due diligence period.
The proposed disposal remains subject to the completion of the technical review, with the transaction forming part of Jubilee’s strategy to redirect capital towards its existing copper mining, processing and refining activities in Zambia.
Together with approximately US$65 million in remaining cash proceeds from the sale of its South African operations, Jubilee expects potential cash inflows of up to US$100 million from the two transactions.
The anticipated proceeds would provide additional funding for the group’s Zambian copper development programme, although the Large Waste Project disposal has not yet been completed.
Jubilee said the planned sale is intended to reduce its exposure to the development requirements of the Large Waste Project while allowing the company to allocate resources to other assets within its portfolio.
The group is focusing on expanding its existing copper operations, including the Molefe Mine, where results from the second phase of drilling are expected shortly.
According to management, the company’s investment priorities include projects that can utilise its established mining, processing and refining infrastructure in Zambia.
These facilities include the Roan Concentrator, which processes copper-bearing feedstock, and the Sable Refinery, which forms part of Jubilee’s integrated copper production operations.
The company intends to combine processing activities involving third-party feedstock with the development of its own mining and exploration assets.
The proposed Large Waste Project disposal represents a further step in Jubilee’s restructuring of its asset portfolio following the sale of its South African operations.
Completion of the transaction and receipt of the remaining consideration will depend on the outstanding due diligence process and applicable transaction requirements.
Jubilee Metals Group is a copper producer and resource developer listed on London’s AIM market and the Johannesburg Stock Exchange’s AltX market. The company is focused on developing an integrated copper business in Zambia through mining, processing, refining and exploration activities.
MedPal AI (LSE:MPAL) has reported a record day of prescription dispensing at its New Health clinic, processing more than 2,300 private prescription orders with a combined value of approximately £300,000, as the company expands its medication inventory following a £5 million equity placing.
The digital healthcare and pharmacy group said the placing, which was predominantly supported by existing and institutional investors, is being used primarily to increase medication stock levels to meet demand across its operations.
As of 6 October 2026, MedPal reported approximately £6.4 million in combined cash, near-cash assets and stock. The company also identified VAT receivables, NHS prescription income and manufacturer rebates as components supporting its working capital position.
Alongside the recent equity financing, MedPal has received an indicative £8 million working capital financing term sheet from a non-bank lender. The proposal remains indicative, and the company is continuing discussions with banking institutions regarding additional funding arrangements.
The group has also called a general meeting to seek shareholder approval for resolutions primarily relating to its authority to issue shares and the provision of broker warrants.
According to MedPal, the proposed resolutions are intended to restore routine corporate authorities following its recent financing activities. The company reiterated that it does not currently plan to undertake a further equity fundraising.
The trading update follows increased prescription activity at New Health, the group’s private clinic focused on GLP-1 weight management treatments. The reported daily order volume represents a record for the business, although the company has not provided comparative figures for earlier periods in the supplied update.
MedPal operates a range of digital healthcare and pharmacy services, including NHS Distance Selling Pharmacy hubs, private prescription services and a business-to-business pharmacy supply operation serving care homes.
The company also provides eMARx electronic medication administration software and is developing Juno, an artificial intelligence-based health companion intended to support patient interactions and healthcare management.
These services form part of MedPal’s planned Health OS platform, which aims to integrate prescribing, dispensing, medication delivery and AI-supported patient services.
MedPal AI plc is a London-listed digital health and pharmacy company combining prescription dispensing, healthcare software and artificial intelligence development. Its operations span NHS and private pharmacy services, care home medication supply and digital patient support technologies.
Tesco (LSE:TSCO) reported a 6.3% increase in adjusted operating profit to £1.78 billion for the first half of its 2026/27 financial year, alongside higher sales, earnings and free cash flow.
The supermarket group recorded sales excluding VAT and fuel of £33.8 billion, representing growth of 1.6% at constant exchange rates. The company attributed its performance to changes in its sales mix, cost reductions and contributions from additional revenue streams.
Adjusted diluted earnings per share increased 12.2% compared with the corresponding period last year, while free cash flow rose 21% to £1.57 billion. Tesco also reported a reduction in net debt compared with the prior-year period.
Following the first-half performance, the retailer increased its share repurchase target for the current financial year to £950 million and announced a higher interim dividend.
Tesco said customer satisfaction reached a record level during the reporting period, supported by its pricing strategy, product development and expansion of digital shopping services.
Online sales increased 8%, reflecting continued activity across the group’s grocery delivery operations. Tesco also reported growth in its Whoosh rapid delivery service and expanded its delivery arrangements through partnerships with Uber Eats and Deliveroo.
The company continued to invest in digital capabilities, including the use of artificial intelligence for personalised customer services and product recommendations.
Other areas of development included Tesco’s retail media activities and its range of non-food products and services, which provide additional revenue opportunities alongside its core grocery operations.
Management identified cost savings, operational efficiency and the development of additional income streams as factors contributing to the group’s first-half financial performance.
Tesco’s latest results also reflect its ongoing capital allocation activities, with increased shareholder distributions through the expanded buyback programme and interim dividend.
Tesco plc is a multinational grocery and general merchandise retailer operating primarily in the UK, Ireland and Central Europe. Its activities include supermarket retailing, online grocery services, rapid delivery and wholesale distribution through Booker.
The group also operates across clothing, pharmacy, financial services and telecommunications, alongside its principal food retailing business.