Author: Fiona Craig

  • European stocks tread cautiously as oil rally and US inflation take centre stage: DAX, CAC, FTSE100

    European stocks tread cautiously as oil rally and US inflation take centre stage: DAX, CAC, FTSE100

    European equities were subdued on Wednesday, holding close to record highs as a six-session advance in crude oil and worsening tensions in the Middle East kept investors cautious ahead of a crucial US inflation report.

    The pan-European Stoxx Europe 600 Index edged 0.1% higher, with major regional markets showing similarly limited moves. Germany’s DAX gained 0.2%, France’s CAC 40 moved 0.1%, while London’s FTSE 100 was virtually unchanged.

    Economic figures from Europe offered some stability before attention shifted towards the US data. Final inflation readings for July confirmed annual headline consumer price growth of 2.8% in both Germany and Italy. However, those figures were overshadowed by renewed volatility in energy markets, with crude oil recording its longest run of consecutive gains since late April.

    Brent crude climbed towards $89 a barrel as the conflict involving Iran and shipping routes through the Persian Gulf showed little sign of easing. Despite repeated claims from U.S. President Donald Trump that a peace agreement was close, negotiations appeared to have reached a deadlock.

    Prospects for a diplomatic breakthrough weakened further after Trump introduced tougher counter-conditions, including a demand for Tehran to pay direct compensation related to the conflict. Iran responded by warning that the Strait of Hormuz would remain closed until Washington satisfied its demands.

    Tensions at sea also intensified after Yemen’s Iran-aligned Houthis carried out fresh attacks against military supply vessels.

    The continued increase in energy and other input costs adds another challenge to an already uncertain economic environment, with investors now turning their attention to Wednesday’s US Consumer Price Index report.

    The inflation figures are particularly important because of the increasingly difficult policy decision facing the Federal Reserve. Last week’s unexpectedly weak US employment report showed the economy lost 23,000 jobs in July and included substantial downward revisions to previous figures. Following the report, market-implied expectations for a September Fed rate increase fell to around 45%, compared with 67% beforehand.

    A weaker-than-anticipated inflation reading could reinforce expectations that slowing labour demand is helping bring price pressures closer to target, potentially allowing central banks on both sides of the Atlantic to keep interest rates unchanged into the autumn.

    In contrast, stronger inflation driven by persistent energy and services costs could increase concerns about “stagflation,” a scenario in which policymakers are forced to maintain elevated borrowing costs even as economic growth deteriorates.

    Despite Wednesday’s cautious trading, the STOXX 600 has gained approximately 11% since the beginning of the year, highlighting the resilience of European equities following a particularly volatile July.

    The index has advanced 1.75% so far in August, although that trails the roughly 3% rise recorded by the S&P 500 Index over the same period.

    US markets have benefited significantly from gains among mega-cap technology companies and artificial intelligence-related stocks. European indices, by comparison, have greater exposure to industrial, automotive and consumer discretionary companies, leaving them more sensitive to weak regional growth, tariffs and rising raw-material costs.

    The approaching end of the second-quarter earnings season is also reducing one source of support for European equities.

    Corporate results have helped underpin markets during the past month, with aggregate STOXX 600 earnings showing growth of almost 21% year-on-year. Banking groups have benefited from healthy net interest margins, while defence and power-grid infrastructure companies have experienced strong demand.

    However, most European companies have now released their quarterly results. As a result, the flow of positive earnings surprises that helped support equities through late July is fading, increasing the market’s dependence on economic data and geopolitical developments for its next significant move.

    European stocks on the move

    Among individual companies, Vestas (TG:VWSB) surged 15% after upgrading its full-year earnings outlook.

    Bilfinger (TG:GBF) dropped more than 6% following the release of its second-quarter results, while Balfour Beatty (LSE:BBY) climbed almost 10% after raising its profit forecasts.

  • Luxury shares weigh on the CAC 40: Is the pullback a buying opportunity?

    Luxury shares weigh on the CAC 40: Is the pullback a buying opportunity?

    French luxury stocks came under pressure on Wednesday, August 12, dragging on the Paris market. Kering (EU:KER) was the weakest performer on the CAC 40, falling 2.9%, while LVMH (EU:MC) declined 1.81% and Hermès International (LSE:RMS) lost 1.73%. Outside the benchmark, Christian Dior (EU:CDI) also retreated 1.88%. Despite the weakness across the sector, the broader CAC 40 contained its decline to 0.21%.

    The pullback in luxury shares came against a generally cautious market backdrop ahead of the latest US consumer price index figures. The CPI data, scheduled for release at 2:30 PM, is being closely monitored for potential implications for the Federal Reserve’s future interest-rate decisions. Investors are also keeping a close watch on continued geopolitical tensions in the Middle East, particularly developments surrounding the Strait of Hormuz.

    Alongside these short-term macroeconomic concerns, uncertainty over Chinese consumer demand continues to cloud the outlook for the luxury industry. A recent Kearney study forecasts that luxury spending per person in China will fall by around 4% in 2026, with leather goods and watches expected to experience even steeper declines. These categories are particularly important for companies including Kering, LVMH and Hermès.

    With no company-specific announcement appearing to account for Wednesday’s losses, the declines seem to reflect broader caution towards the luxury sector rather than a sudden deterioration in the prospects of individual companies. For investors considering whether the weakness represents a buying opportunity, the outlook for Chinese demand and the wider macroeconomic environment are therefore likely to remain important factors.

  • FTSE 100 slips as US-Iran tensions over Strait of Hormuz escalate

    FTSE 100 slips as US-Iran tensions over Strait of Hormuz escalate

    UK equities moved slightly lower on Wednesday as worsening tensions between the United States and Iran over the Strait of Hormuz took attention away from closely watched US inflation figures due later in the day.

    The FTSE 100 was 0.08% lower as of 03:25 ET (07:25 GMT). Elsewhere in Europe, Germany’s DAX advanced 0.12%, while France’s CAC 40 declined 0.19%. Sterling was broadly steady against the US dollar, with GBP/USD edging 0.03% higher to 1.3510.

    Geopolitical concerns intensified early on Wednesday after U.S. Central Command said American forces had disabled the steering system of the Panama-flagged cargo ship M/V Vela Nova in the Gulf of Oman. According to CENTCOM, the vessel had attempted to breach the US blockade affecting Iran-bound shipping.

    CENTCOM said a US Navy MH-60 helicopter fired two Hellfire missiles into the ship’s engine room after its crew failed to respond to repeated warnings. It added that, as of August 11, US forces had redirected 55 vessels, disabled three and boarded another two.

    U.S. President Donald Trump reinforced Washington’s position on Tuesday, reiterating that the United States had “total control” of the strategic waterway. Trump said, “We have total control over the Strait of Hormuz right now… We own it,” while warning that any Iranian retaliation would face a “forceful” response.

    Iranian foreign ministry spokesperson Esmail Baghaei disputed Washington’s account of the situation, blaming the closure of the Strait on “US-Israeli military aggression”. He also said negotiations between Tehran and Oman over a new transit route were progressing “smoothly and constructively,” although reopening the waterway would depend on the removal of conditions imposed on Iran.

    In a separate development, Trump confirmed reports that his aircraft was secretly changed during his departure from last month’s NATO summit in Turkiye because of an alleged Iranian assassination threat.

    Jefferies strategist Mohit Kumar cautioned that a lasting resolution could prove difficult. In a note to clients, he said “there is no easy way out of the current situation, with Iran unlikely to give up control over the Strait and US unwilling to accept tolls,” adding that any agreement reached in the near term would probably be “more a fudge… rather than a long-lasting peaceful solution.”

    Energy prices moved higher as traders continued to assess potential disruption to oil supplies through the Strait. Brent crude gained 0.66% to $89.50, while WTI crude increased 0.77% to $83.83. Gold futures rose 0.41% to $4,459.47, with spot gold advancing 0.73% to $4,399.69.

    UK round-up

    Balfour Beatty (LSE:BBY) lifted its 2026 operating profit growth guidance to the low double digits, supported by robust demand across its US building operations and UK power infrastructure activities.

  • Primary Health Properties Confirms Compliance With Assura Takeover Commitments

    Primary Health Properties Confirms Compliance With Assura Takeover Commitments

    Primary Health Properties (LSE:PHP) has confirmed that it has fulfilled the post-offer intention statements made as part of its acquisition of Assura plc, providing formal regulatory confirmation that the healthcare property group has followed through on commitments associated with the transaction.

    PHP confirms compliance with takeover obligations

    Primary Health Properties has submitted confirmation to the U.K. Takeover Panel that it complied with all post-offer intention statements relating to its recommended shares and cash acquisition of Assura.

    The Assura transaction became unconditional in August 2025, creating a significantly enlarged healthcare property portfolio for PHP.

    The latest announcement was made in accordance with Rule 19.6(c) of the City Code on Takeovers and Mergers, which requires companies to report on compliance with certain intentions stated during an offer process.

    The confirmation does not introduce new financial targets or strategic initiatives but closes an important regulatory requirement associated with the acquisition.

    Assura integration remains central to PHP strategy

    For investors, the announcement provides additional reassurance around execution following a major corporate transaction.

    By confirming that its stated post-offer intentions have been followed, PHP demonstrates that the integration has proceeded in accordance with the commitments communicated during the takeover process.

    The Assura acquisition increased the scale of PHP’s exposure to primary healthcare real estate, making successful integration an important component of the group’s longer-term investment case.

    Management’s broader focus following the combination includes capturing synergies, refinancing and maintaining earnings and dividend coverage across the enlarged business.

    Balance sheet remains an area to monitor

    PHP’s financial profile presents a more mixed picture following the expansion of the business.

    Strong revenue and profitability in 2025 provide support, while post-merger performance has included earnings per share growth, a covered dividend, synergy progress and refinancing activity.

    However, higher leverage and a significant deterioration in free cash flow remain important considerations for investors. These factors increase the importance of disciplined capital management as PHP integrates the enlarged property portfolio.

    Continued progress on refinancing and synergies could help strengthen the financial position, but leverage will remain a key metric to watch following the Assura transaction.

    Dividend and valuation provide support

    PHP’s market position is supported by a relatively high dividend yield and moderate price-to-earnings valuation.

    The shares are also trading above major moving averages, providing a constructive technical backdrop.

    For an income-focused healthcare REIT, maintaining dividend coverage will be particularly important. The combination of integration benefits, rental income and financing costs will help determine the sustainability of shareholder distributions as the enlarged group develops.

    The latest Takeover Panel confirmation removes one element of regulatory uncertainty, leaving operational integration, leverage and cash generation as more significant factors for the investment outlook.

    More about Primary Health Properties plc R.E.I.T

    Primary Health Properties plc is a U.K.-listed real estate investment trust specialising in primary healthcare properties.

    The group owns and manages medical centres, GP surgeries and other healthcare facilities, with its portfolio designed to generate long-term rental income from assets supporting NHS and community healthcare services.

    Following the Assura acquisition, PHP operates an enlarged healthcare property platform, with its strategy focused on portfolio management, integration, financial discipline and generating sustainable income from primary care real estate.

  • IQE Sets 7 September Date for H1 2026 Results as Semiconductor Demand Comes Into Focus

    IQE Sets 7 September Date for H1 2026 Results as Semiconductor Demand Comes Into Focus

    IQE plc (LSE:IQE) will publish its unaudited results for the six months ended 30 June 2026 on 7 September, giving investors a fresh opportunity to assess trading, margins and demand across the compound semiconductor specialist’s key markets.

    IQE schedules H1 2026 results

    IQE has confirmed that its first-half results will be released on 7 September 2026, followed by a management webcast at 9:00 a.m. the same day.

    The update will provide investors with the latest picture of the company’s financial and operational performance across the first six months of the year.

    Attention is likely to centre on demand for IQE’s advanced wafer products and whether conditions across its major end markets are translating into improved financial performance.

    The company supplies compound semiconductor materials used across smart connected devices, communications infrastructure, automotive and industrial applications, as well as aerospace and security markets.

    Compound semiconductor demand comes into focus

    IQE’s upcoming results will provide an opportunity to assess trends across markets where compound semiconductor technologies are increasingly important.

    The company’s epitaxy wafers serve as critical inputs for semiconductor manufacturers and equipment producers, giving IQE exposure to areas including communications, connectivity, sensing and automotive electronics.

    Its manufacturing operations span the U.K., U.S. and Taiwan, providing a global production footprint from which to serve customers.

    IQE also relies on its intellectual property, patents and proprietary manufacturing expertise to differentiate its products in a market where technical requirements create significant barriers to entry.

    Margins and financial performance will be key

    While demand trends will be closely followed, the more important question for investors is whether IQE can translate its market position into stronger profitability and cash generation.

    The company’s recent financial performance has remained challenging, with persistent losses, negative gross profit in 2025 and negative free cash flow.

    Rising debt and declining equity have added further pressure to the balance sheet, increasing the importance of any evidence of improving margins or financial discipline in the September results.

    The interim announcement could therefore provide greater clarity on whether operational performance is beginning to strengthen and how effectively IQE is competing across its targeted semiconductor applications.

    Share price momentum provides some support

    IQE’s technical picture has been more constructive than its underlying financial performance.

    The shares have been trading above key moving averages, while positive MACD indicates supportive market momentum.

    However, valuation remains difficult to assess through conventional earnings measures because the company is loss-making and therefore carries a negative price-to-earnings ratio. There is also no dividend data to provide additional income support.

    That leaves financial improvement and operational execution as important factors in determining whether recent share-price momentum can be sustained.

    More about IQE plc

    IQE plc is an AIM-listed global supplier of advanced compound semiconductor wafers and materials solutions headquartered in Cardiff.

    Its products are used across smart connected devices, communications infrastructure, automotive and industrial systems, and aerospace and security applications. The company serves semiconductor manufacturers and OEMs through production facilities in the U.K., U.S. and Taiwan.

    IQE’s business is supported by a portfolio of patents, proprietary expertise and a scaled epitaxy manufacturing footprint. These capabilities are designed to deliver the wafer quality, manufacturing yields and economics required by customers across advanced semiconductor applications.

  • Georgina Energy Advances Hussar Pre-Drill Works Ahead of September 2026 Spud

    Georgina Energy Advances Hussar Pre-Drill Works Ahead of September 2026 Spud

    Georgina Energy plc (LSE:GEX) is progressing pre-drill construction work at its Hussar EP513 prospect in Western Australia, keeping the exploration well on schedule for a September 2026 spud as the company prepares to test a large subsalt helium, hydrogen and hydrocarbon target.

    Hussar site preparations move forward

    Civil engineering contractors are completing several activities required before the Ensign 970 drilling rig can be mobilised to Hussar.

    Current work includes drilling a water well, preparing for conductor pipe installation, establishing the camp and constructing infrastructure to manage drilling fluids.

    Completion of these activities represents an important operational milestone ahead of rig mobilisation and supports Georgina Energy’s planned September drilling timetable.

    The next stage will shift attention from site preparation towards execution of the exploration programme and the geological results generated by the well.

    Georgina targets 3,200-metre exploration well

    The Hussar well is designed to reach a depth of approximately 3,200 metres and test both fractured basement formations and overlying reservoirs.

    Georgina describes Hussar as one of Australia’s largest untested onshore subsalt prospects targeting helium, hydrogen and hydrocarbons, with significant certified prospective resources.

    Drilling will therefore provide important information about whether the geological potential identified at Hussar can be demonstrated through direct subsurface testing.

    For investors, keeping the September spud on schedule reduces near-term timing uncertainty, although the ultimate significance of the project will depend on drilling results and subsequent evaluation.

    September spud becomes key catalyst

    The approaching Hussar drilling programme represents a potentially important catalyst for Georgina Energy because exploration success could increase confidence in the scale of its resource base.

    The company’s strategy is built around developing helium, hydrogen and natural gas resources as it seeks exposure to markets where management sees growing Australian and international demand.

    However, Hussar remains an exploration-stage project. The presence and commercial viability of targeted resources will need to be established through drilling, testing and further development work.

    Investors can therefore watch for completion of site works, mobilisation of the Ensign 970 rig and confirmation that drilling begins according to the September schedule.

    Financial position increases importance of drilling execution

    Georgina Energy’s financial profile remains a significant risk as it advances its exploration programme.

    The company currently generates no revenue and has reported losses and negative cash flow. Negative equity and rising debt add further balance-sheet pressure.

    That financial position increases the importance of disciplined execution at Hussar, as delays or additional development requirements could place further demands on available capital.

    Technical momentum is comparatively positive and provides some support to the shares. Traditional valuation measures remain less useful, however, given Georgina’s ongoing losses and absence of a stated dividend yield.

    With Hussar approaching the drilling stage, operational milestones and eventual well results are likely to remain central to the company’s near-term investment narrative.

    More about Georgina Energy plc

    Georgina Energy plc is a helium, hydrogen and natural gas exploration and development company with onshore projects in Australia.

    Its portfolio includes the Hussar Prospect in Western Australia’s Officer Basin and the Mt Winter Prospect in the Northern Territory’s Amadeus Basin. Through subsidiary Westmarket O&G, the company holds or expects to hold 100% working interests in these projects.

    Georgina targets subsalt and fractured basement reservoirs with prospective helium, hydrogen and gaseous hydrocarbon resources. Its strategy is focused on advancing these assets through exploration and development as it seeks to establish a position in helium, hydrogen and natural gas markets.

  • Seeing Machines Expands Human-Centred AI Into Robotics With Factory Automation Contract

    Seeing Machines Expands Human-Centred AI Into Robotics With Factory Automation Contract

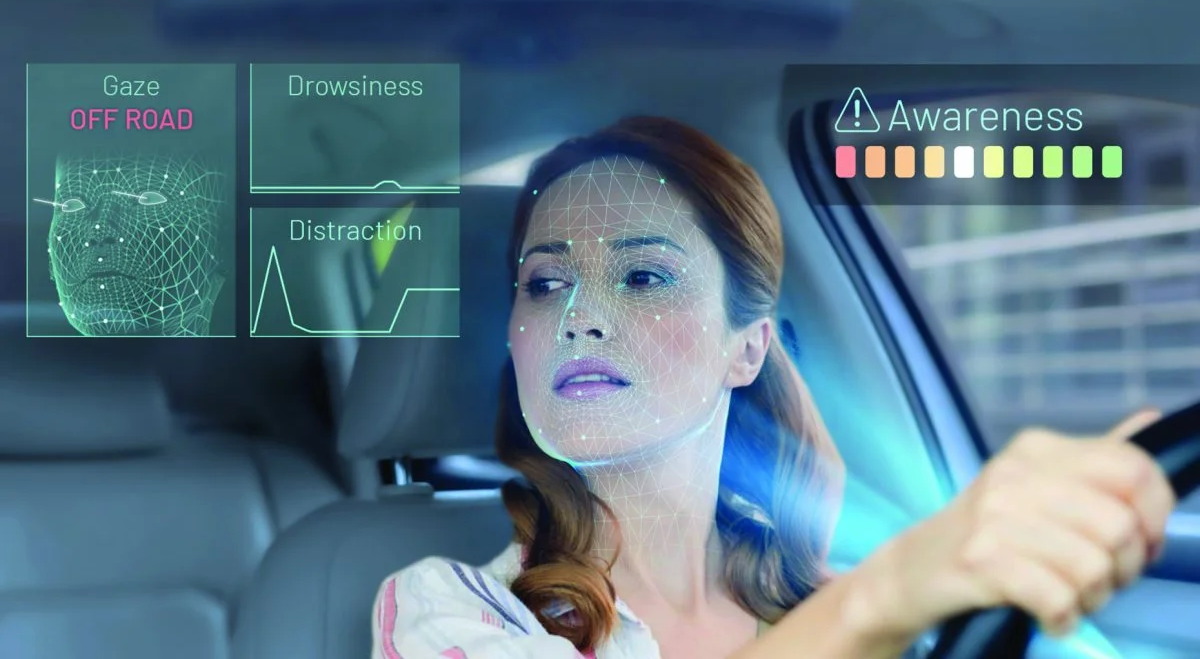
    Seeing Machines (LSE:SEE) has secured an advanced development contract with a global industrial technology company, extending its Human-Centred AI technology beyond transport safety and into factory automation and human-robot interaction.

    Seeing Machines secures robotics development contract

    The agreement will initially focus on developing a robotics proof-of-concept for use in a factory environment.

    Seeing Machines will apply its Perception Map technology to the programme, exploring how its human-monitoring and perception capabilities can be integrated into industrial robotics.

    The project represents a new application for technology that Seeing Machines has primarily deployed across automotive, commercial fleet, off-road and aviation markets.

    While the initial scope is a proof-of-concept rather than a large-scale commercial deployment, the programme is intended to establish a foundation for potential broader collaboration in industrial automation.

    Human-Centred AI moves beyond transport markets

    Seeing Machines’ technology is designed to help machines understand human behaviour and respond more effectively to people operating around them.

    Within a factory environment, the company’s expertise in human factors and AI could potentially be applied to improve interactions between workers and automated systems, including identifying behaviour and anticipating risks in safety-critical settings.

    Management sees the contract as evidence that its Human-Centred AI capabilities can address applications beyond driver and operator monitoring.

    This diversification could become strategically important if Seeing Machines can adapt its existing intellectual property and expertise for additional industrial markets without losing focus on its established transport businesses.

    Robotics contract opens a potential new growth vertical

    For investors, the significance of the agreement lies primarily in the potential expansion of Seeing Machines’ addressable markets.

    Factory automation introduces the company to a different category of customers and applications from its established transport safety operations. Successful completion of the proof-of-concept could potentially lead to deeper collaboration with the unnamed industrial technology partner.

    However, the announcement does not disclose the contract’s financial value, expected revenue contribution or any commitment to commercial-scale deployment.

    The immediate catalyst is therefore technical validation rather than a material change to current earnings. Evidence that the programme progresses from proof-of-concept into broader deployment would provide a stronger indication of its commercial significance.

    Financial performance remains an important consideration

    Seeing Machines continues to deliver strong revenue growth, but its broader financial profile remains constrained by ongoing losses, a negative net margin and negative operating cash flow.

    That makes the development of additional commercially viable revenue streams particularly relevant to the company’s longer-term outlook.

    Technical indicators offer a more supportive picture, with the shares trading above major moving averages and momentum ranging from neutral to positive.

    Traditional valuation measures remain less useful because Seeing Machines is loss-making, resulting in a negative price-to-earnings ratio, while the absence of a dividend means the investment case continues to depend largely on growth and progress towards sustainable profitability.

    More about Seeing Machines

    Seeing Machines Limited is an Australian-headquartered Human-Centred AI technology company listed on AIM.

    Its vision-based monitoring systems combine computer vision, embedded processing, optics and more than 25 years of human factors expertise to allow machines to detect and interpret human attention and cognitive states.

    The technology is primarily used across automotive, commercial fleet, off-road and aviation applications, where it is designed to improve safety and reduce risks associated with driver and operator behaviour.

    Seeing Machines operates across Australia, the U.S., Europe and Asia. The latest factory automation project expands the potential application of its technology into industrial robotics and human-machine interaction.

  • Titon Holdings Targets FY26 Revenue Growth as Ventilation Delays Pressure Margins

    Titon Holdings Targets FY26 Revenue Growth as Ventilation Delays Pressure Margins

    Titon Holdings Plc (LSE:TON) expects revenue to increase by around 7.5% in FY26, supported by strong demand for Mechanical Ventilation Systems, although project delays, weaker hardware sales and an unfavourable product mix are weighing on profitability.

    Titon expects FY26 revenue to reach around £17m

    Titon is forecasting revenue of approximately £17 million for the year ending 30 September 2026, representing growth of around 7.5%.

    Mechanical Ventilation Systems is driving much of that expansion, with the division expected to achieve mid-to-high-teens percentage revenue growth.

    However, some ventilation projects have moved into FY27, limiting the contribution they will make to the current financial year. An unfavourable sales mix has also put pressure on margins.

    As a result, Titon expects underlying EBITDA of approximately £0.3 million despite the anticipated increase in group revenue.

    Ventilation project delays shift potential revenue into FY27

    The delayed MVS projects create a mixed picture for investors. They reduce near-term earnings momentum but could provide additional activity during FY27 once work begins.

    Management remains positive about the medium- and longer-term outlook, with delayed projects and higher-value re-engineered products expected to contribute during the next financial year.

    The key issue will be whether Titon can convert continued MVS revenue growth into stronger margins as the mix of projects changes.

    With FY26 underlying EBITDA expected to remain modest relative to revenue, margin recovery is likely to be an important measure of operational progress.

    Hardware division faces weaker construction demand

    Trading has been more difficult within Titon’s Window and Door Hardware division, where sales have declined more sharply than expected amid subdued residential construction activity.

    Management is responding with several initiatives designed to improve performance, including new product launches and the integration of G-Pack Manufacturing Limited.

    Titon is also bringing more production into its Haverhill facility. The insourcing strategy is intended to support greater operational efficiency as the company works to improve the division’s performance.

    The success of these measures will be important in determining whether hardware can recover from the current weakness and provide a stronger contribution alongside the faster-growing ventilation business.

    Debt-free balance sheet provides financial flexibility

    Titon enters this period of margin pressure with a relatively conservative financial position.

    The company remains debt-free and has approximately £2.2 million in cash, reducing financial risk while management invests in operational improvements.

    Recent cash generation has also improved, providing some support despite Titon’s inconsistent profitability and historically volatile earnings.

    Technical momentum is constructive, although overbought readings suggest some caution following recent share-price strength. Traditional valuation measures provide less support because Titon currently has a negative price-to-earnings ratio and no stated dividend yield.

    For investors, the next stage of the story will depend on whether revenue growth can translate into improved profitability as delayed ventilation projects begin and restructuring measures within the hardware division take effect.

    More about Titon Holdings

    Titon Holdings Plc is an international manufacturer and supplier of ventilation systems and window and door hardware for residential and commercial construction markets.

    Its operations include Mechanical Ventilation Systems alongside Window and Door Hardware, giving the company exposure to both ventilation demand and broader construction activity.

    Titon has expanded its hardware operations through the acquisition of G-Pack Manufacturing Limited and is pursuing product development, integration and manufacturing initiatives intended to improve efficiency and support longer-term growth.

  • NatWest Group Releases H1 2026 Pillar 3 Disclosures Across Major Banking Subsidiaries

    NatWest Group Releases H1 2026 Pillar 3 Disclosures Across Major Banking Subsidiaries

    NatWest Group plc (LSE:NWG) has published its first-half 2026 Pillar 3 disclosures for several of its principal banking subsidiaries, providing investors with updated regulatory information covering areas including capital, risk and financial resilience.

    NatWest publishes H1 regulatory disclosures

    The latest Pillar 3 reports cover NatWest Holdings Limited, NatWest Markets Plc, National Westminster Bank Plc, The Royal Bank of Scotland plc and Coutts & Company.

    Pillar 3 reporting forms part of the prudential disclosure framework for banks, providing market participants with information that can be used to assess regulatory capital and risk exposures.

    Publishing the reports across NatWest’s major entities gives investors and other stakeholders greater visibility into the regulatory position of individual businesses within the wider group.

    The documents have been made available through NatWest Group’s investor website.

    Disclosures provide additional view of capital and risk

    The announcement itself does not represent a change in NatWest’s operating strategy or financial guidance. Instead, its significance lies in providing another layer of regulatory transparency following the first half of 2026.

    The disclosures allow investors to examine risk and capital metrics across businesses ranging from retail and commercial banking to markets and private banking.

    For bank investors, these measures can complement conventional earnings results by providing additional information about capital strength and the risks supporting the group’s balance sheet.

    The coordinated publication also demonstrates NatWest’s continued compliance with prudential reporting requirements across its principal regulated subsidiaries.

    Financial outlook remains supportive

    NatWest’s broader outlook is supported by solid recent financial performance and an upgraded earnings outlook from its latest results.

    Valuation also provides support, with the shares carrying a relatively low price-to-earnings multiple alongside a healthy dividend yield.

    However, cash flow remains an area requiring attention despite the stronger earnings picture. Investors will need to assess this alongside NatWest’s capital position, profitability and shareholder distributions when evaluating the group’s financial resilience.

    Technical indicators have also been positive, with the shares showing strong near-term momentum. Some indicators suggest the stock has become relatively overheated, potentially increasing the risk of shorter-term volatility following its recent performance.

    Why Pillar 3 reporting matters for NatWest investors

    For a major banking group such as NatWest, regulatory capital and risk management are central to the investment case because they influence financial flexibility and the capacity to withstand economic or market stress.

    The H1 Pillar 3 disclosures provide investors with more granular information across NatWest’s principal subsidiaries rather than introducing a new corporate catalyst.

    They can therefore help investors assess whether the group’s underlying regulatory position remains consistent with its earnings outlook and broader financial strategy.

    Future capital distributions, profitability and balance-sheet resilience will remain more direct drivers of shareholder returns, but Pillar 3 reporting provides important supporting information for evaluating those areas.

    More about NatWest Group

    NatWest Group plc is a major U.K. banking group providing retail, commercial, investment banking and wealth-management services.

    Its principal businesses include NatWest Holdings, NatWest Markets, National Westminster Bank, The Royal Bank of Scotland and Coutts & Company.

    Through these operations, NatWest serves individual consumers, businesses, corporate clients and wealth-management customers while maintaining regulatory capital and risk-management frameworks across its banking subsidiaries.

  • Foresight Environmental Infrastructure Raises Dividend as Portfolio Performance Supports NAV

    Foresight Environmental Infrastructure Raises Dividend as Portfolio Performance Supports NAV

    Foresight Environmental Infrastructure Limited (LSE:FGEN) delivered a positive quarterly NAV return and raised its dividend as renewable generation outperformed expectations, while growth investments recorded operational progress despite weaker power price forecasts.

    FGEN reports £652.4 million net asset value

    FGEN reported an unaudited net asset value of £652.4 million at 30 June 2026, equivalent to 104.7 pence per share.

    The portfolio generated a NAV total return of 1.4% during the quarter, while total shareholder return reached 28.2%.

    Positive asset valuation movements and operational performance helped offset lower short- to medium-term power price forecasts, which reduced NAV per share by 1.3 pence.

    The company believes its diversified exposure to environmental infrastructure provides some protection against individual market pressures while creating opportunities for value growth from operational improvements.

    Quarterly dividend rises to 2.01 pence

    The board declared a quarterly dividend of 2.01 pence per share and remains on course for its full-year target of 8.04 pence.

    Based on FGEN’s closing share price on 11 August 2026, the targeted annual distribution represents a 9.4% dividend yield.

    Portfolio cash generation is expected to maintain dividend cover within the company’s target range of 1.2 to 1.3 times after project debt amortisation.

    Gearing remained relatively modest at 29.2%, providing balance-sheet flexibility as management considers investment opportunities and capital recycling.

    Renewable generation beats budget

    FGEN’s renewable energy portfolio generated 3.8% more electricity than budgeted during the period.

    Anaerobic digestion and biomass assets were among the stronger contributors. The Vulcan facility also received a valuation uplift following increased biomethane volumes.

    Performance across these assets helped counter the negative impact of lower forecast power prices and demonstrated the role operational delivery can play in supporting portfolio valuations.

    The company expects further opportunities for organic NAV growth through asset optimisation and other value-enhancement initiatives.

    Growth investments show operational progress

    Several of FGEN’s growth investments also recorded improved operating metrics.

    CNG Fuels increased gas volumes by 8.1% compared with the previous year, while The Glasshouse delivered EBITDA 27% ahead of budget and 41% higher year-on-year.

    The Rjukan project received additional funding as FGEN works to resolve operational constraints and move the asset towards steady-state performance.

    These investments broaden the portfolio beyond conventional renewable electricity generation and provide exposure to areas including Bio-CNG and low-carbon agritech.

    NAV discount remains a key investor consideration

    Despite the strong quarterly shareholder return, FGEN’s chair-designate highlighted that the shares were trading at an 18.8% discount to NAV.

    The board believes this discount does not fully reflect the quality and diversity of the underlying portfolio. Closing that gap could depend on continued operational delivery, sustainable distributions and evidence that asset valuations remain resilient against changes in power prices and financing conditions.

    Financial risks remain relevant. Historical negative operating and free cash flow and volatile revenue raise questions around earnings quality and the durability of distributions.

    Those concerns are partly balanced by relatively low leverage, positive market momentum and the company’s targeted dividend coverage. The combination of a high dividend yield and NAV discount may attract investor attention, but continued portfolio cash generation will be important in supporting both.

    More about Foresight Environmental Infrastructure Limited

    Foresight Environmental Infrastructure Limited is a listed investor in private environmental infrastructure assets across the U.K. and mainland Europe.

    Its portfolio includes renewable generation assets such as anaerobic digestion and biomass facilities alongside growth investments in areas including Bio-CNG refuelling and low-carbon agritech.

    The company’s strategy is designed to generate long-term cash flows and capital growth while supporting a progressive quarterly dividend. Diversification across environmental infrastructure assets is intended to reduce reliance on individual power markets and create additional opportunities for operational value creation.

    FGEN also incorporates sustainability objectives into its investment approach, including alignment with Article 9 of the EU Sustainable Finance Disclosure Regulation and the U.K.’s Sustainability Disclosure Requirements as a Sustainability Focus fund.