Author: Fiona Craig

  • Capricorn Energy Expects Production Above Guidance Midpoint as Takeover Offers Remain Active

    Capricorn Energy Expects Production Above Guidance Midpoint as Takeover Offers Remain Active

    Capricorn Energy (LSE:CNE) expects full-year production to exceed the midpoint of its guidance range of 18,000 to 22,000 barrels of oil equivalent per day, supported by output from its operations in Egypt.

    The company reported average working interest production of 19,337 barrels of oil equivalent per day during the first half.

    Capricorn said production levels continued through July and August, with new wells contributing to output.

    First-Half Operating Profit Reaches $56.3 Million

    Capricorn reported an operating profit of $56.3 million for the first half, compared with an operating loss of $2 million in the corresponding period a year earlier.

    Revenue from the company’s Egyptian operations totalled $100 million for the six months ended 30 June.

    Capricorn achieved an average realised oil price of $89.5 per barrel during the period, up from $73.6 per barrel a year earlier.

    DNO and Genel Offers Remain Active

    Capricorn remains the subject of competing takeover proposals from DNO (OSE:DNO) and Genel Energy (LON:GENL).

    Earlier in September, Capricorn accepted a $396 million offer from DNO after the Norwegian oil company submitted a higher proposal than the competing offer from Genel Energy.

    According to Capricorn, both takeover offers remain active.

    The competing proposals remain subject to their respective terms and applicable takeover processes.
  • CVS Group FY26 Revenue Rises 5.9% to £712.8 Million as UK Acquisitions Resume

    CVS Group FY26 Revenue Rises 5.9% to £712.8 Million as UK Acquisitions Resume

    CVS Group (LSE:CVSG) reported a 5.9% increase in full-year revenue to £712.8 million for the year ended 30 June 2026, supported by growth in Australia and an improvement in like-for-like sales.

    Like-for-like sales increased 2.1%, compared with growth of 0.2% in the previous financial year.

    The veterinary group said consumer confidence and extreme heat during May and June affected customer footfall in the fourth quarter.

    Adjusted EBITDA Increases 5.1%

    Adjusted EBITDA rose 5.1% to £141.5 million, while the adjusted EBITDA margin remained unchanged at 19.9%.

    The company recorded the increase despite higher employer National Insurance contributions and wage inflation.

    Adjusted earnings per share increased 6.9% to 85.6 pence.

    Statutory profit before tax, however, declined to £32 million from £32.6 million. CVS attributed this to factors including higher depreciation following investment, costs associated with the Competition and Markets Authority investigation and expenses related to the group’s move from AIM to the London Stock Exchange’s Main Market in January.

    CVS Resumes UK Acquisition Activity

    The Competition and Markets Authority published its final remedies order on 22 September, enabling CVS to resume acquisition activity in the UK.

    CVS said it has exchanged contracts to acquire a two-site veterinary practice for an initial consideration of £15 million and has identified further potential acquisition opportunities.

    In Australia, revenue increased to £79.1 million from £52.1 million.

    The number of Australian practices increased to 57 from 43, with the country accounting for approximately 11% of group revenue.

    Net Bank Borrowings Rise to £199.6 Million

    Net bank borrowings increased to £199.6 million from £131.4 million, while leverage rose to 1.63 times from 1.18 times.

    The increase followed expenditure on acquisitions, capital investment and share buybacks.

    CVS completed a £20 million share buyback in January 2026 and launched a further £50 million programme in May, which remained in progress at the reporting date.

    Final Dividend Increased to 9 Pence

    The board recommended a final dividend of 9 pence per share, compared with 8.5 pence for the previous year.

    Subject to the applicable approval process, the dividend is due to be paid on 4 December.

    CVS is also progressing its search for a successor to chief executive Richard Fairman, who announced in March that he planned to retire. The company said the search process was well underway.

  • Raspberry Pi H1 Revenue Rises 90% to $256.9 Million as Shipments Reach 4.2 Million Units

    Raspberry Pi H1 Revenue Rises 90% to $256.9 Million as Shipments Reach 4.2 Million Units

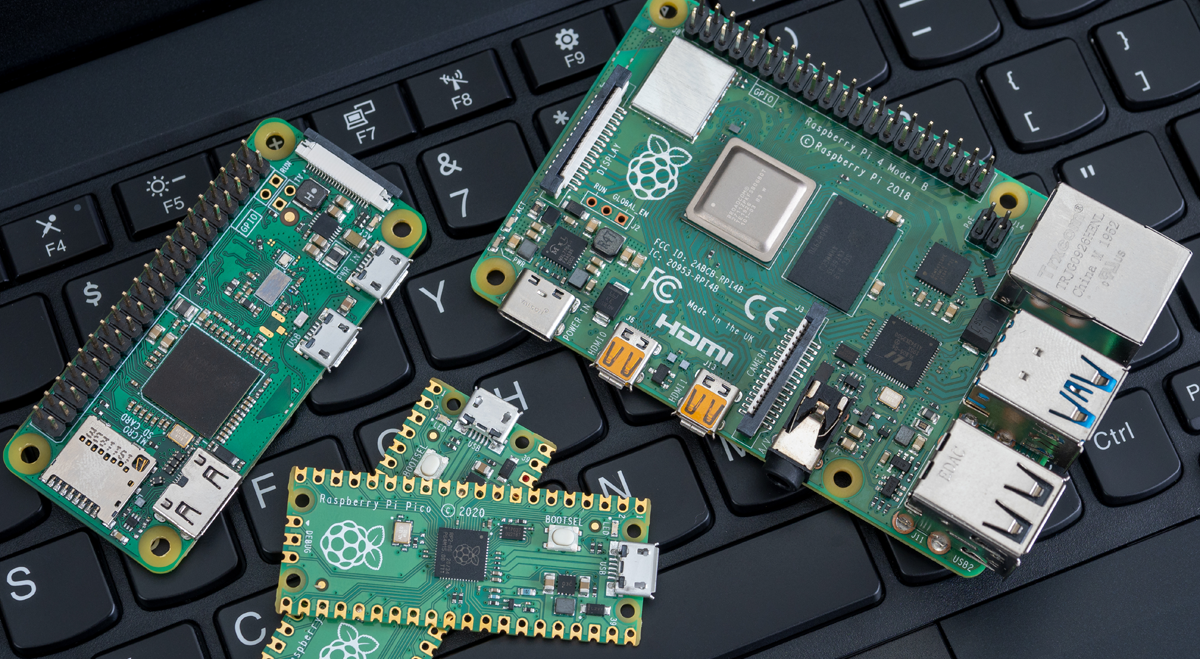
    Raspberry Pi Holdings (LSE:RPI) reported revenue of $256.9 million for the first half of 2026, an increase of 90% from the corresponding period a year earlier, as unit shipments and demand from OEM and reseller customers increased.

    Adjusted EBITDA more than doubled to $40.3 million, while profit before tax rose 216% to $19.6 million.

    Gross profit increased 79% to $59.4 million, with gross profit per board rising 53% to $12.2.

    Gross Margin Declines as Memory Costs Increase

    Raspberry Pi reported a slight decline in gross margin during the period as higher memory costs were passed through to customers.

    The company shipped 4.2 million units during the first half, representing an increase of 17% year on year.

    Direct shipments increased 26% to 3.4 million units.

    Raspberry Pi said demand came from both OEM and reseller customers, with applications including smart home products and the aerospace and defence sectors.

    Order Backlog Doubles to 2.6 Million Units

    The company’s order backlog increased to 2.6 million units, twice the level reported previously.

    Raspberry Pi increased inventory and diversified its supplier base as it sought to maintain product availability during disruption in the memory market.

    Management expects unit volumes to increase during the second half of the year and is expanding production capacity to support anticipated demand.

    The company also reported an OEM pipeline covering applications including industrial computing and edge artificial intelligence. These expectations remain subject to future demand and operating conditions.

    About Raspberry Pi Holdings

    Raspberry Pi Holdings is a Cambridge-based computing company supplying general-purpose computing platforms to industrial, embedded, enthusiast and education customers.

    Its engineering activities cover semiconductor intellectual property, hardware design, software engineering and compliance.

    The company also operates in the semiconductor market and said more than 77 million Raspberry Pi units have been sold to date.

  • Vistry Group Reports First-Half Loss as Strategic Review Reduces Regional Structure

    Vistry Group Reports First-Half Loss as Strategic Review Reduces Regional Structure

    Vistry Group (LSE:VTY) reported a loss for the first half of 2026 as revenue and housing completions declined and the company recognised exceptional charges during the period.

    The charges included a goodwill impairment and an increase in provisions associated with building safety.

    Net debt also increased during the period amid pressure on cash generation. Vistry discounted certain open-market housing inventory and recorded approximately £50 million of impacts associated with the early stages of its strategic review.

    Strategic Review Reduces Regions From 25 to 12

    Chief executive Adam Daniels has completed a strategic review of the business, resulting in plans to operate Vistry as a smaller and more geographically focused mixed-tenure housebuilder.

    Under the revised structure, the number of operating regions will be reduced from 25 to 12.

    The company also plans to simplify its products and operating processes and reduce and reshape its owned land bank.

    In the South East, Vistry intends to move to a fully pre-sold operating model.

    Vistry Targets 12,000 Annual Completions

    As part of the revised strategy, Vistry is targeting annual housing completions of 12,000 units.

    The company plans for approximately 60% of completions to be partner-funded, with the remaining 40% allocated to the open market.

    Vistry is also targeting annual overhead savings of £50 million as it implements the restructuring.

    The company intends to participate in the UK government’s new Social and Affordable Housing Programme as part of its mixed-tenure strategy.

    Strategy Targets Lower Leverage and Cash-Backed Earnings

    Vistry said the revised strategy is intended to produce more consistent, cash-backed earnings and reduce leverage.

    Implementation will involve changes to the group’s regional structure, land holdings, product range and mix between partner-funded and open-market housing.

    The targets remain management objectives and are subject to execution of the restructuring and future market conditions.

    About Vistry Group

    Vistry Group is a UK housebuilder operating a mixed-tenure model across open-market, affordable and private rented sector housing.

    The company works with housing associations and institutional partners and operates across regions including the North, Midlands, West and South East of England.

  • ASOS Reports Gross Margin Above 50% as GMV Returns to Growth in Fourth Quarter

    ASOS Reports Gross Margin Above 50% as GMV Returns to Growth in Fourth Quarter

    ASOS (LSE:ASC) reported an adjusted gross margin of more than 50% for its 2026 financial year, while adjusted EBITDA finished above the midpoint of the company’s guidance range.

    The online fashion retailer said profitability was supported by changes to sourcing, lower product returns and cost controls.

    Full-year gross merchandise value declined 5%, although ASOS reported a return to GMV growth during the fourth quarter, when it increased at a low single-digit rate.

    Womenswear GMV Increases 3%

    ASOS reported positive fourth-quarter trading in markets including the UK, Germany and the U.S.

    Its priority Womenswear category recorded GMV growth of 3% over the full financial year.

    The company ended the year with 16.4 million active customers and reported its first quarter of year-on-year active customer growth since 2022, supported by new customer acquisition.

    ASOS said changes to its app and the use of AI-based personalisation are being used to increase customer engagement and conversion.

    Net Debt Reduced to Around £110 Million

    ASOS ended FY26 with net debt of approximately £110 million.

    The company also generated approximately £116 million from the disposal of warehouses it classified as non-core.

    ASOS said the transactions released capital and reduced associated annual costs, with the company planning to reinvest in initiatives intended to support future growth.

    About ASOS

    ASOS is an online fashion retailer serving customers across more than 100 markets.

    Its offering includes own and associated brands such as ASOS DESIGN, Topshop and ARRANGE alongside products from third-party fashion brands.

    The company had 16.4 million active customers at the end of the 2026 financial year and operates primarily through its digital and app-based retail platforms.

  • Empire Metals Produces 99.2% TiO2 Rutile Pigment From Pitfield Ore

    Empire Metals Produces 99.2% TiO2 Rutile Pigment From Pitfield Ore

    Empire Metals (LSE:EEE) has produced an uncoated rutile titanium dioxide pigment from weathered ore at its Pitfield Titanium Project in Western Australia as it continues metallurgical testwork on potential end products from the deposit.

    The company used a tailored processing flowsheet known as the Empire Process to convert material from Pitfield into a high-purity anatase TiO2 intermediate and subsequently into rutile pigment.

    Recent testwork produced rutile pigment with a calculated purity of approximately 99.2% TiO2.

    Testwork Targets Coated Rutile Pigment

    Following production of the uncoated material, Empire is progressing testwork aimed at producing coated rutile pigment for use in architectural coatings.

    The company said it is working to optimise impurity rejection and finishing parameters to meet specifications required for architectural paint applications.

    Empire has also engaged specialist advisers to assist with the design of finishing facilities required for coated pigment production.

    According to the company, Tier 1 coated rutile pigments currently command prices of approximately US$3,250 per tonne. This figure relates to the referenced market and does not represent a forecast selling price for future Pitfield production.

    Pitfield Ore Contains Low Levels of Certain Impurities

    Empire said testwork has identified low levels of deleterious elements, including radionuclides and heavy metals, in the weathered Pitfield material being evaluated.

    The company is assessing whether these characteristics could simplify impurity removal during processing compared with conventional sulphate processing of ilmenite.

    Further optimisation and testwork are being undertaken as Empire develops the proposed processing route.

    Empire Evaluates Titanium Pigment and Metal Feedstock Markets

    Empire is working with TiPMC Consulting on a marketing strategy focused on supplying coated rutile pigment to the architectural coatings and paint sector.

    The company is also evaluating the potential production of high-purity titanium material suitable for use as feedstock for titanium sponge and metal production.

    Empire Metals is an exploration and development company whose principal asset is the Pitfield Titanium Project in Western Australia.

  • Living REIT Net Rental Income Rises 2.3% as Senior Living Acquisition Expands Portfolio

    Living REIT Net Rental Income Rises 2.3% as Senior Living Acquisition Expands Portfolio

    Living REIT (LSE:LIVE) reported a 2.3% increase in net rental income to £20.2 million for the six months ended 30 June 2026, while adjusted earnings per share rose 2.2% to 3.42 pence.

    The company said its performance was supported by inflation-linked rent reviews and a stabilised property portfolio.

    Dividend cover for the period was 1.20 times, while Living REIT increased its annual dividend target by 3%. EPRA net tangible assets were broadly unchanged at 95.36 pence per share.

    Senior Living Acquisition Adds 2,163 Homes

    Following the end of the reporting period, Living REIT broadened its investment mandate and completed the acquisition of a senior living portfolio comprising 2,163 homes.

    The transaction increased the group’s pro-forma gross asset value to approximately £825 million.

    The company said the acquisition also reduced its exposure to individual counterparties by expanding and diversifying its portfolio.

    Living REIT expects the acquired portfolio to deliver high single-digit earnings accretion. This remains a company expectation rather than an achieved financial result.

    Debt Costs Average 3.16%

    Living REIT reported a weighted average cost of debt of 3.16%, with its borrowings predominantly fixed-rate and long-dated.

    The company also made changes to its sustainability governance during the period and reported improvements in external ESG assessments, alongside being shortlisted for several industry awards.

    About Living REIT

    Living REIT is a UK-listed real estate investment trust focused on residential property assets.

    Its portfolio includes specialised supported housing, senior living and care homes, with rental arrangements designed to generate long-term income, including inflation-linked rents.

  • 80 Mile Extends Jameson Exploration Well Deadlines to 2028 Under Revised Greenland JV

    80 Mile Extends Jameson Exploration Well Deadlines to 2028 Under Revised Greenland JV

    80 Mile plc (LSE:80M) has amended the joint venture arrangements covering its Jameson liquid hydrocarbon project in Greenland, extending deadlines for the first two exploration wells to 31 December 2028.

    Under an extension letter, March GL Company will transfer its rights and obligations under the joint venture to Greenland Energy Company as part of an internal reorganisation.

    Greenland Energy Company will assume responsibility for obtaining and maintaining the permits required for the Jameson projects and will bear the associated costs.

    80 Mile to Receive £500,000 Cash Payment

    As part of the revised arrangements, 80 Mile will receive a £500,000 cash payment upon signing the extension letter.

    The deadlines for drilling both the first and second exploration wells have been moved to 31 December 2028.

    The revised terms provide additional time for the joint venture to progress permitting and other work associated with the Jameson project.

    Company Cites Greenland Strategic Developments

    80 Mile also referred to a new trilateral security and defence agreement involving Greenland, Denmark and the United States.

    The company said it believes increased international cooperation could support investor confidence and investment in Greenland’s energy and critical mineral sectors.

    However, decisions regarding permits for the Jameson project remain with the relevant Greenlandic authorities and are subject to applicable environmental and community requirements.

    About 80 Mile

    80 Mile is an exploration and development company with mining and liquid hydrocarbon projects in Greenland.

    Through its Jameson joint venture, the company is pursuing exploration activities in East Greenland. Its wider portfolio includes projects targeting energy and mineral resources in the country.

  • On the Beach Expects FY26 Adjusted Pre-Tax Profit of £22-23 Million as Bookings Reach £1.3 Billion

    On the Beach Expects FY26 Adjusted Pre-Tax Profit of £22-23 Million as Bookings Reach £1.3 Billion

    On the Beach Group (LSE:OTB) said adjusted pre-tax profit for the 2026 financial year is expected to be between £22 million and £23 million, placing the result in the upper half of its previous guidance range.

    The online package holiday provider reported its fifth consecutive year of record total transaction value, with bookings increasing 9% to £1.3 billion.

    The group ended the financial year debt-free and with approximately £60 million in cash.

    Shareholder Returns Total Around £67 Million Over Two Years

    On the Beach said it returned approximately £67 million to shareholders through dividends and share buybacks over the past two years.

    The company reported continued booking growth during Summer 2026 and into the beginning of the 2027 financial year.

    Bookings during the most recent eight-week period increased 17%, while bookings from repeat customers rose 18%.

    The company attributed the performance to factors including investment in technology, expansion of its product range and its brand activities.

    FY27 Profit Guidance Set at £28-35 Million

    On the Beach expects adjusted pre-tax profit of between £28 million and £35 million for FY27.

    The guidance represents an increase from the £22 million to £23 million expected for FY26, although the FY27 figure remains a company forecast and is subject to future trading conditions.

    The group continues to expand its operations across beach and city holidays, the Republic of Ireland and cruise products.

    On the Beach also identified macroeconomic conditions and geopolitical developments in travel destinations as factors affecting the operating environment.

    About On the Beach Group

    On the Beach Group is an online package holiday provider serving customers in the UK and Republic of Ireland.

    The company offers beach, city and cruise holidays and operates through an asset-light business model supported by its proprietary technology platform and relationships with travel suppliers.

  • Poolbeg Pharma POLB 001 Trial to Continue Unchanged Following Interim Safety Review

    Poolbeg Pharma POLB 001 Trial to Continue Unchanged Following Interim Safety Review

    Poolbeg Pharma (LSE:POLB) has reported interim safety data from its ongoing TOPICAL clinical trial of POLB 001, with an independent review recommending that the study continue without changes.

    The trial is evaluating POLB 001 as a preventative treatment for Cytokine Release Syndrome in patients with relapsed or refractory multiple myeloma receiving the bispecific antibody teclistamab.

    Following the safety review, patient recruitment will continue at participating UK clinical sites, while Poolbeg plans to activate additional centres.

    Independent Review Recommends Trial Continue Without Changes

    The interim review assessed safety data generated during the ongoing TOPICAL study.

    Based on the data reviewed, the independent assessment recommended that the trial proceed without modifications.

    The update relates to safety and does not establish the efficacy of POLB 001 in preventing Cytokine Release Syndrome. The clinical trial remains ongoing.

    Poolbeg Continues POLB 001 Development

    POLB 001 is being developed to prevent Cytokine Release Syndrome, a complication that can occur with certain cancer immunotherapies.

    Poolbeg is evaluating whether preventing the condition could support the use of treatments such as bispecific antibodies in a broader range of clinical settings.

    The company said it intends to share emerging data from the programme with prospective partners as development progresses.

    Poolbeg Pharma Pipeline

    Poolbeg Pharma is a clinical-stage biopharmaceutical company developing treatments in cancer immunotherapy and other therapeutic areas.

    POLB 001 is its lead clinical asset and is being evaluated for the prevention of Cytokine Release Syndrome associated with cancer immunotherapies.

    The company’s development pipeline also includes an oral GLP-1 programme targeting obesity.