Category: Market News

  • System1 Rejects Fourth Brave Bison Takeover Offer as Shareholders Representing 23% Oppose Bid

    System1 Rejects Fourth Brave Bison Takeover Offer as Shareholders Representing 23% Oppose Bid

    System1 Group PLC (LSE:SYS1) has unanimously rejected a fourth takeover proposal from Brave Bison Group (LSE:BBSN), stating that the revised cash-and-share offer materially undervalues the company and does not provide a premium for control.

    The System1 board said the latest proposal values the company below its prevailing market price when calculated using Brave Bison’s most recent share price. It also noted that the proposed transaction relies partly on System1’s existing cash reserves.

    System1 has received written commitments from shareholders representing approximately 23% of its issued share capital confirming that they will not accept the offer. These include Lord Ashcroft, BGF and Crucible.

    The board has also questioned the strategic rationale behind the proposed combination and raised concerns about Brave Bison’s governance. System1 characterised the approach as opportunistic and suggested that Brave Bison’s acquisition-led expansion strategy does not establish a sufficient strategic fit between the two businesses.

    System1 further stated that the extended takeover process has diverted management attention from day-to-day operations and generated additional costs for shareholders.

    The company continues to support its independent strategy, citing its cash position and existing operations as factors in its assessment of the proposal.

    System1 provides advertising effectiveness measurement and analytics services, helping brands assess and predict the performance of marketing campaigns.

    The latest rejection leaves Brave Bison’s fourth proposal without the support of System1’s board or the shareholders who have provided written commitments opposing the offer.

  • Winkworth H1 Revenue Falls 10% to £4.7 Million as Exceptional Costs Weigh on Full-Year Outlook

    Winkworth H1 Revenue Falls 10% to £4.7 Million as Exceptional Costs Weigh on Full-Year Outlook

    Winkworth (LSE:WINK) reported a 10% decline in company revenue to £4.7 million for the six months ended 30 June 2026, while operating profit before exceptional costs increased 9%. The estate agency franchisor also warned that exceptional legal and advisory expenses are expected to leave full-year reported profit before tax materially below market expectations.

    Network revenue declined 1% to £31.6 million, reflecting a 5% reduction in property sales revenue, partly offset by a 3% increase in lettings and management revenue. The results reflected a greater contribution from rental activities amid uneven conditions in the UK property market.

    The company attributed the decline in its own revenue primarily to the winding down of its Development and Commercial Investment division and the deconsolidation of its Crystal Palace office.

    Cash generation improved during the period, with Winkworth reporting a cash balance of £3.73 million and no debt at the end of June.

    Trading varied across the network, with central London and country markets contributing to performance. Management cited interest rate uncertainty and geopolitical tensions as factors affecting property market conditions.

    Winkworth also reported that franchisees had adapted to changes associated with the Renters’ Rights Act. The company said its London sales market share had increased in recent years.

    Network expansion continued during the first half, with four new offices added. Assisted acquisitions also supported the establishment of a new regional hub, while the company maintained investment in technology and artificial intelligence.

    Despite the increase in operating profit before exceptional costs, Winkworth expects legal and advisory expenses to reduce reported full-year profit before tax materially below market forecasts.

    The company operates a network of 104 offices across the UK, focusing on residential property sales, lettings and management. Its franchise model is supplemented by selectively owned offices and an assisted acquisition programme designed to support franchisee expansion.

  • Cora Gold Moves Closer to Construction as Sanankoro Development Advances

    Cora Gold Moves Closer to Construction as Sanankoro Development Advances

    For a gold developer, the journey from feasibility through to construction is where a project’s potential starts to become increasingly tangible. At this stage, investors begin to focus not only on the geological opportunity and project economics, but also on the practical milestones required to turn a development into a producing mine.

    For Cora Gold (LSE:CORA), that transition is now firmly underway at its Sanankoro Gold Project in Mali, with the company progressing key pre-construction activities while continuing exploration aimed at expanding its resource base.

    In a recent Watch List interview, Bert Monro, CEO of Cora Gold, provided an update on the company’s progress and outlined the key milestones investors should be watching as Sanankoro moves towards construction.

    Sanankoro Prepares for Mine Construction

    Cora Gold completed its Definitive Feasibility Study (DFS) for Sanankoro at the end of last year, marking a significant milestone in the project’s development.

    According to Monro, Sanankoro is an open-pit oxide gold project with a payback period of less than one year at the current gold price — an attractive feature as the company progresses towards development.

    The immediate priority is now the completion of the Front-End Engineering Design (FEED) process, which represents a critical part of the preparation required before construction can begin.

    “We’re currently completing our FEED process on the project,” Monro explained, describing it as a “really critical path” ahead of construction.

    The work is therefore focused on taking Sanankoro from a defined development plan towards a project that is increasingly construction-ready.

    Drilling Offers Further Resource Upside

    Alongside the engineering work, Cora Gold is continuing an active drilling programme at Sanankoro.

    The programme has a dual purpose: supporting the FEED process while also providing the company with an opportunity to grow its existing resources.

    Cora has recently released further drill results, with additional results expected to provide continued news flow over the coming weeks and months.

    For investors, this creates an interesting combination of development progress and exploration upside. While the company works through the technical requirements for construction, drilling continues to test the potential for additional resources.

    Monro highlighted the ongoing programme and the prospect of further results, indicating that there should be plenty of potential news flow from the drilling campaign in the months ahead.

    Permitting Is Now a Key Catalyst

    While FEED and drilling remain important areas of activity, Cora Gold is also making progress on what Monro described as the major pre-construction milestone: permitting.

    The company recently secured the renewal of its main exploration permit, representing an important step forward as it works through the remaining permitting requirements.

    Cora is now progressing through the final stages of permitting, including additional renewals and reshaping work, before ultimately seeking the award of its mining permit.

    For Cora, securing the mining permit would represent a major milestone in the development of Sanankoro and provide further clarity on the pathway towards construction.

    Monro was particularly encouraged by the recent progress, with the company now looking to advance the remaining stages as quickly as possible over the coming months.

    Multiple Catalysts Ahead

    The significance of Sanankoro’s current phase is that Cora Gold is moving beyond simply demonstrating the geological potential of the project. The company is now working through the engineering, permitting and exploration activities required to advance the project towards development.

    With the DFS completed, FEED underway, drilling continuing and permitting progressing, Cora has several potential catalysts ahead.

    The completion of FEED, further drill results, continued permitting progress and the award of the mining permit will be important milestones for investors to monitor.

    This combination of development and exploration activity could make the coming months an important period for Cora Gold as Sanankoro continues its transition towards construction.

    A Project Entering an Important Stage

    Cora Gold’s progress at Sanankoro comes at a time when the gold sector continues to benefit from a strong gold-price environment. For developers, this can potentially improve the economics and attractiveness of projects that are approaching the construction decision.

    Sanankoro’s open-pit oxide development model, combined with the sub-one-year payback highlighted by Monro at the current gold price, gives the project an interesting economic proposition as Cora continues to advance it.

    The focus now is firmly on execution: completing the FEED work, progressing the permitting process, continuing exploration and ultimately securing the mining permit.

    As Cora Gold moves through these milestones, Sanankoro is steadily transitioning from a feasibility-stage project towards a potential development opportunity.

    For investors watching Cora Gold, the next few months could therefore prove significant, with a combination of engineering progress, permitting milestones and exploration results providing a steady stream of potential catalysts.

    With Bert Monro and the Cora Gold team focused on advancing the project, Sanankoro is entering an important stage in its journey towards construction.

    For more information visit – https://www.coragold.com/

  • First Development Resources: Lander West Drilling Confirms Gold-Bearing System as Exploration Momentum Builds

    First Development Resources: Lander West Drilling Confirms Gold-Bearing System as Exploration Momentum Builds

    First Development Resources (LSE:FDR) has taken an important step forward at its Selta Project in Australia’s Northern Territory, with initial drilling at the Lander West gold target confirming primary gold mineralisation in bedrock and providing the company with a significantly clearer roadmap for the next phase of exploration.

    For an exploration company, drilling is ultimately about turning geological concepts into evidence. At Lander West, First Development Resources has now achieved an important part of that process.

    The company’s initial Reverse Circulation programme comprised eight holes totalling 1,593 metres and confirmed gold mineralisation in bedrock, with gold anomalism encountered in six of the eight holes.

    The headline result came from hole 26LWR08 at the Red Handed target, which returned 7 metres at 0.40 g/t gold from 50 metres, including 2 metres at 0.98 g/t gold, with a peak 1-metre assay of 1.11 g/t gold.

    For FDR, however, the significance of the programme extends beyond a single drill intercept.

    Building the geological picture

    One of the most encouraging aspects of the latest results is the amount of new geological information generated by the programme.

    FDR has combined the new drilling results with surface geochemistry, modern geophysics and its reconstruction of historical exploration data. That integrated approach has identified multiple priority areas across the wider Lander West target.

    These include Red Handed, Red Hackle, Auraria, L1 and Giles, giving the company a pipeline of targets to investigate rather than relying on a single area of interest.

    This is particularly relevant because the company’s review of historical exploration has highlighted significant gaps between previous drill fences and across prospective magnetic and structural features.

    In other words, Lander West has not yet been comprehensively tested by modern exploration techniques.

    That leaves FDR with considerable scope to systematically build on what it has learned from the first drilling campaign.

    Gold and copper add further interest

    Gold is not the only encouraging element emerging from the programme.

    Drillhole 26LWR02 intersected 8 metres at 0.32% copper from 47 metres, including 5 metres at 0.39% copper and a peak 1-metre assay of 0.58% copper. The company is now assessing the significance of this copper mineralisation within the broader mineralising system.

    Surface exploration has also added another layer to the geological picture.

    FDR’s 2026 reconnaissance and rock-chip sampling programme covered 243 samples/sites across Lander West, with gold values reaching 0.64 g/t Au alongside elevated pathfinder elements including arsenic, tungsten, antimony, bismuth and copper.

    Taken together, the drilling, surface sampling and geophysical information are helping the company develop a much stronger understanding of the system.

    Historical results now provide an additional exploration vector

    FDR has also been able to validate historical drilling at Red Handed.

    Historical RAB hole RHB108, drilled by Normandy NFM in 1997, returned 16 metres at 0.30 g/t gold from 12 metres, including 2 metres at 1.93 g/t gold. FDR’s latest drilling and historical data review provide further evidence that the Red Handed area hosts an underlying gold-bearing system.

    Importantly, the company is not claiming continuity between the historical and modern intersections. Instead, the results provide additional geological evidence supporting further systematic exploration.

    That distinction is important — and potentially encouraging — because the objective of the next phase is now to establish whether the system develops into zones with better grade, greater width and stronger continuity.

    October exploration programme provides the next catalyst

    FDR is already preparing for the next phase of work, with field crews expected to return to Lander West in October.

    The company plans to refine and rank the priority targets identified through the latest integrated review before progressing to further Aircore and Reverse Circulation drilling.

    The staged approach is also designed to remain capital disciplined, with targets required to justify further expenditure.

    For investors following the story, this creates a potentially interesting sequence of exploration catalysts: additional work at Red Handed, testing of the wider target areas, and further drilling aimed at determining whether the initial gold-bearing system can develop into something more substantial.

    From geological concept to a defined exploration story

    The latest results should therefore be viewed as an important step in FDR’s exploration journey rather than the conclusion of it.

    The company has now demonstrated primary gold mineralisation in bedrock at Lander West, identified gold anomalism across multiple drill holes, confirmed copper mineralisation in one hole, validated historical exploration results and established a pipeline of priority targets for follow-up work.

    As CEO Tristan Pottas highlighted, the initial programme has established that the company is dealing with a genuine gold-bearing system and, perhaps just as importantly, has provided a much stronger dataset to determine where the next drilling should be focused.

    The next question is therefore not simply whether there is gold at Lander West — that has now been demonstrated.

    The focus moves to whether continued exploration can identify higher-grade, wider and more continuous zones of mineralisation.

    With exploration set to resume in October and multiple targets now in the pipeline, First Development Resources enters its next phase with considerably more geological information — and potentially a much clearer path towards unlocking the wider potential of the Selta Project.

    For more information visit – https://firstdevelopmentresources.com/
  • Wall Street Futures Slip Ahead of Fed Decision as 10-Year Yield Reaches 5%: Dow Jones, S&P, Nasdaq

    Wall Street Futures Slip Ahead of Fed Decision as 10-Year Yield Reaches 5%: Dow Jones, S&P, Nasdaq

    US equity futures traded modestly lower on Tuesday as Treasury yields climbed and investors prepared for Wednesday’s Federal Reserve interest-rate decision.

    The benchmark 10-year Treasury yield moved above 5%, reaching its highest level since July 2007. The increase comes as markets assess the outlook for inflation and monetary policy.

    A Federal Reserve rate increase is widely expected. CME Group’s FedWatch Tool showed markets assigning a 92.5% probability to a 25-basis-point increase.

    AJ Bell head of markets Dan Coatsworth said, “Market commentators have long argued that Treasuries hitting 5% is the trigger for an equity market correction. At this level, investors might wonder what’s the point in holding risky equities when they can get 5% on low-risk government bonds.”

    Coatsworth added, “It is a psychological level and can sometimes act as a warning sign for a market correction rather than be a guaranteed tipping point for equities to slump.”

    Middle East Supply Concerns Support Oil Prices

    Crude prices remained another factor for markets on Tuesday, with reports of additional Houthi attacks on Saudi Arabia adding to uncertainty over Middle East energy supplies.

    October crude futures finished Monday 1.3% higher after initially rising almost 5%.

    The earlier increase followed Saudi Arabia’s closure of a pipeline used to bypass the Strait of Hormuz after a drone attack. A planned meeting in Oman involving Iran and Gulf states over reopening the strait was also postponed.

    US President Donald Trump said on Truth Social that Russia and Ukraine had agreed to stop targeting each other’s energy infrastructure.

    Trump separately repeated his claims that Iran wants to “make a deal, quickly and badly” and that “oil is flowing through the Hormuz Strait.”

    Semiconductors Lead Monday’s Technology Declines

    Monday’s US session ended lower despite the major averages recovering substantially from their intraday lows.

    The Nasdaq Composite closed 0.6% lower at 26,186.41, after falling as much as 1.3%. The S&P 500 declined 0.5% to 7,619.98 and the Dow Jones Industrial Average finished 0.3% lower at 52,421.20.

    Semiconductor shares recorded larger declines, sending the Philadelphia Semiconductor Index down 5.9% to its lowest close in more than a month.

    Computer hardware stocks also fell, with the NYSE Arca Computer Hardware Index losing 4.8%. The Philadelphia Oil Service Index dropped 4%, while networking, gold and banking shares also declined.

    Software stocks outperformed, with the Dow Jones U.S. Software Index advancing 3.3%.

    Anthropic CEO Calls for Slower AI Development

    Concerns surrounding artificial intelligence development also drew attention to technology stocks.

    Anthropic CEO Dario Amodei wrote, “We must slow the pace at which we improve the capabilities of AI models. Progress will still seem fast, and we must make wise use of the time we gain.”

    “The measures I propose to advance the frontier at a safe pace will not be easy,” Amodei added. “But I believe we owe it to humanity to try.”

    With Treasury yields, oil prices and technology-sector developments contributing to market uncertainty, investors are awaiting the Federal Reserve’s Wednesday announcement for further guidance on the interest-rate outlook.

  • European Stocks Fall as Oil Prices and Bond Yields Remain Elevated: DAX, CAC, FTSE100

    European Stocks Fall as Oil Prices and Bond Yields Remain Elevated: DAX, CAC, FTSE100

    European equities traded mostly lower on Tuesday as higher oil prices and elevated government bond yields remained in focus, while investors awaited monetary policy decisions from several major central banks.

    The UK’s FTSE 100 fell 0.4%, France’s CAC 40 declined 0.3% and Germany’s DAX was down 0.1%.

    Banking stocks were among the sectors trading lower as investors assessed the potential inflation implications of higher energy prices amid continued tensions in the Middle East.

    Central Bank Decisions in Focus

    Investors were also awaiting monetary policy decisions from the US Federal Reserve, Bank of England and Bank of Japan this week, with inflation and interest-rate expectations remaining a focus for markets.

    The British pound extended its decline from the previous session following the release of UK labour-market data.

    Figures from the Office for National Statistics showed job vacancies had fallen to a four-year low, while wage growth moderated over the summer.

    Deutz Falls After Capital Increase

    Among individual stocks, German engine manufacturer Deutz (TG:DEZ) moved lower after completing a capital increase.

    In London, City of London Investment Group (LSE:CLIG) shares advanced after the asset manager reported increases in funds under management, fees and earnings for 2026.

    Kier Group (LSE:KIE) also moved higher after the infrastructure and construction company reported its FY2026 results and raised its guidance for FY2027.

    Market attention remains focused on energy prices, bond yields and the upcoming central bank decisions as investors assess the outlook for inflation and interest rates.

  • Centrica and X-energy Advance UK Nuclear Plans as Xe-100 Begins Design Assessment

    Centrica and X-energy Advance UK Nuclear Plans as Xe-100 Begins Design Assessment

    Plans by Centrica (LSE:CAN) and X-Energy (NASDAQ:XE) to deploy Xe-100 nuclear reactors in Britain have reached the regulatory assessment stage after the reactor design was accepted into the UK’s Generic Design Assessment.

    The process is expected to last around three years and will assess the Xe-100 design before any site-specific licensing and permitting.

    The Office for Nuclear Regulation, Environment Agency and Natural Resources Wales will administer the assessment.

    Hartlepool Proposed for First UK Development

    The regulatory milestone follows a partnership signed by Centrica and X-energy in September 2025 under which the companies intend to develop as much as 6 GW of new nuclear generating capacity across the UK.

    Depending on the size and configuration of individual developments, the companies estimate the programme could comprise between 10 and 20 Xe-100 power stations.

    Hartlepool is the proposed location for the first development. Work undertaken since the partnership was announced includes site assessments, planning activities and workforce initiatives.

    A Nuclear and Electrical Trades Academy has also been launched as part of the companies’ activities in the area.

    Regulatory Cooperation Could Support Assessment

    The Xe-100 uses high-temperature gas-cooled reactor technology and is designed to supply either electricity or industrial heat.

    An individual reactor is engineered for 80 MW of electrical output or 200 MW of thermal heat. Multiple units can be combined into plants with planned generating capacities ranging from 320 MW to 960 MW.

    Centrica and X-energy said cooperation between UK authorities and the US Nuclear Regulatory Commission is expected to allow reviewed technical documentation and safety analyses to be shared between the regulatory systems.

    Acceptance into the GDA does not itself provide approval for construction at Hartlepool, with site-specific licensing and permitting required separately.

    Xe-100 Projects Also Progressing in United States

    Alongside its UK programme, X-energy is advancing the first planned Xe-100 installation with Dow Inc. on the Texas Gulf Coast.

    A further project is being developed with Energy Northwest in collaboration with Amazon.

    Michael Shanks, the UK’s Minister of State for Energy, called the latest development “another important step towards bringing advanced nuclear technologies to the UK”.

    Shanks said the projects could provide “clean, secure and homegrown energy” and bring investment and employment to Hartlepool.

  • Fever-Tree Shares Rise 4% as Kepler Cheuvreux Upgrades Stock to Buy

    Fever-Tree Shares Rise 4% as Kepler Cheuvreux Upgrades Stock to Buy

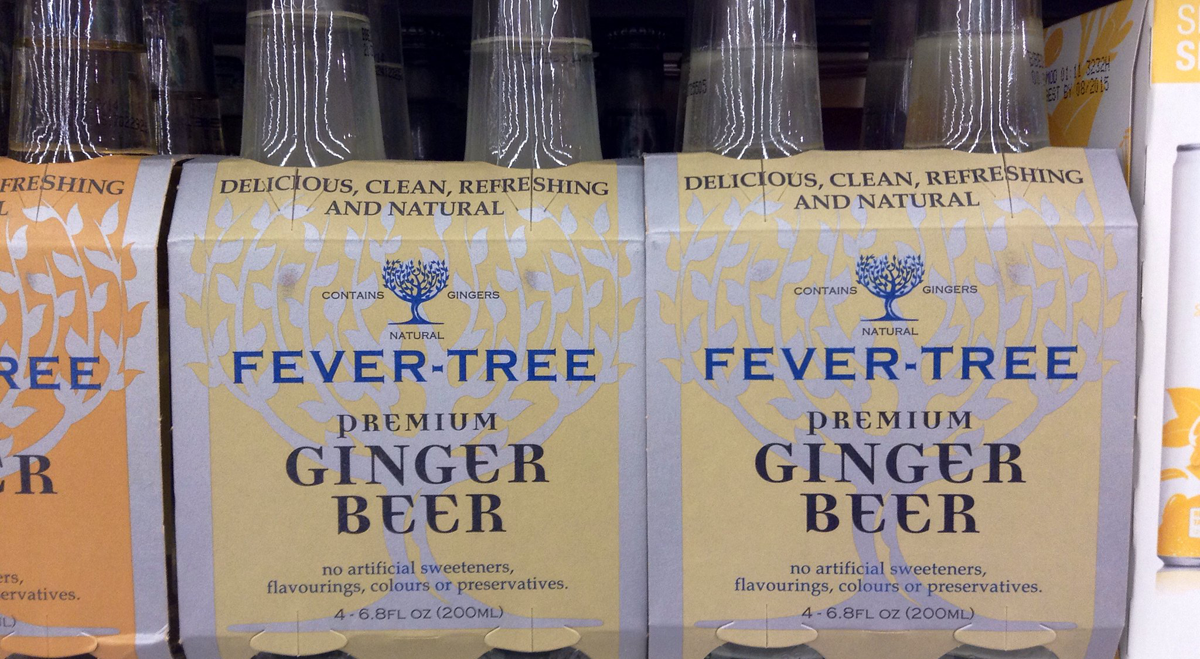
    Fever-Tree Drinks (LSE:FEVR) shares rose on Tuesday after Kepler Cheuvreux upgraded the drinks company to “buy” from “hold” and increased its price target.

    The shares gained 4.2% to 828 pence, while the FTSE 250 was down approximately 0.4%.

    Kepler raised its price target for Fever-Tree to 910 pence from 900 pence, representing potential upside of about 14.5% from the broker’s reference price.

    The broker cited accelerating growth in the US and increased earnings visibility among the reasons for its revised recommendation.

    Kepler Points to Faster US Growth

    Kepler said Fever-Tree’s US performance has improved as Molson Coors expands distribution, merchandising and marketing activities.

    According to the broker, US off-trade growth accelerated to 16% in July and August from 6% in the first quarter of 2026.

    Kepler also said conditions in the UK had stabilised, while products outside Fever-Tree’s core tonic-water range now account for 32% of sales.

    The broker said the company’s input-cost hedging and profit guarantee with Molson Coors provide greater visibility over EBITDA. It also expects free cash flow to support potential dividends and share buybacks.

    Earnings Estimates Raised

    Kepler increased its adjusted EBITDA forecast for Fever-Tree by 5.8% for 2026 and 8.5% for 2027.

    The broker also raised its adjusted earnings-per-share estimates by 2.2% for 2026 and 11% for 2027.

    The revised forecasts accompanied Kepler’s decision to move its recommendation to “buy”.

    Fever-Tree Reports Higher First-Half Revenue

    The broker’s upgrade follows Fever-Tree’s first-half results, which showed revenue rising 14% to £165.1 million.

    Pre-tax profit increased 30% to £14.6 million.

    Fever-Tree’s chair also purchased approximately £348,000 of the company’s shares last week, according to a regulatory filing.

  • Market Open: Wickes Sales Rise, MJ Gleeson Revenue Up

    Market Open: Wickes Sales Rise, MJ Gleeson Revenue Up

    FTSE 100 opens flat as oil supply concerns weigh on markets, while Wickes and MJ Gleeson report higher revenue and Brent crude rises.

    Market Overview

    The FTSE 100 opened broadly unchanged at 10,697.76, as higher oil prices and Middle East supply concerns remained in focus ahead of the Federal Reserve meeting. In Europe, the Euronext 100 slipped 0.01 per cent to 1,879.22 and Germany’s DAX fell 0.44 per cent to 25,329.75, with geopolitical tensions, elevated bond yields and caution ahead of the Fed weighing on sentiment. In the US, the Nasdaq closed lower at 26,186.41, while the S&P 500 fell to 7,619.98.

    Commodity markets were mixed, with copper and gold moving lower while Brent crude and natural gas edged higher. Oil remained supported by concerns over Middle East supplies following further Houthi attacks on Saudi Arabia and delays to talks over reopening the Strait of Hormuz. Against sterling, the US dollar, Swiss franc, euro, Japanese yen and Australian dollar weakened marginally, while Bitcoin fell.


    Market Numbers

    FTSE 100: Down (0.001%), 10,697.76
    Euronext 100: Down (-0.01%), 1,879.22
    DAX: Down (-0.44%), 25,329.75
    NASDAQ: Down, 26,186.41
    S&P 500: Down, 7,619.98


    In the Headlines

    Revenue Growth – Wickes Group (LSE:WIX)
    Home improvement retailer Wickes reported a 2.1% increase in first-half revenue, with Design & Installation sales rising 5.7%. The figures highlight growth in the division alongside the group’s wider first-half trading performance.

    Revenue Rises – MJ Gleeson (LSE:GLE)
    Housebuilder and land developer MJ Gleeson reported a 12.1% increase in FY26 revenue, while adjusted profit declined. The results show higher annual sales alongside pressure on underlying profitability.


    Currencies (vs GBP)

    USD: Down (-0.001%), $1.3501
    CHF: Down (-0.001%), Fr.1.1034
    EUR: Down (-0.01%), €1.1691
    JPY: Down (-0.01%), ¥208.4675
    AUD: Down (-0.001%), $1.8916
    Bitcoin (BTC/GBP): Down, £57,234.11


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Up

  • Saudi Pipeline Shutdown Could Create 6 Million Bpd Oil Deficit, HSBC Says

    Saudi Pipeline Shutdown Could Create 6 Million Bpd Oil Deficit, HSBC Says

    HSBC estimates that the temporary shutdown of Saudi Arabia’s East-West crude pipeline could push the global oil market into a deficit of approximately 6 million barrels per day during part of September and October.

    The pipeline, which transports Saudi crude from the Gulf to the Red Sea without passing through the Strait of Hormuz, is expected to remain mostly offline for three to five weeks for repairs following an attack last week.

    Oil prices moved higher on Monday following reports about the expected duration of the shutdown.

    Analysts led by Kim Fustier called the outage “a negative surprise” compared with HSBC’s base-case assumptions. The bank had expected Saudi Arabia’s East-West pipeline and the UAE’s ADCOP system to provide alternative export capacity while shipping through the Strait of Hormuz remained disrupted.

    Saudi Export Volumes Had Already Declined

    According to HSBC, Saudi oil exports fell to around 3 million barrels per day in August from between 4 million and 4.5 million bpd previously as more exports were routed through the country’s west coast.

    The analysts calculated that losing 3 million bpd for one month would remove approximately 90 million barrels from supply.

    HSBC said cumulative global oil inventory draws since February have exceeded 500 million barrels.

    Based on these factors, the bank estimates that the global market could temporarily face a deficit of around 6 million bpd between mid-September and mid-October, which it described as “the largest implied deficit since the start of the conflict.”

    HSBC Monitors Potential Early Pipeline Restart

    Saudi west-coast export logistics had already been affected before the pipeline shutdown, according to HSBC.

    Loadings at Yanbu had declined, while some Saudi exports were redirected north through Egypt’s Suez Canal and SUMED pipeline following the announcement of a Houthi blockade on July 20.

    HSBC cited Saudi Aramco’s previous restoration work at the Ras Tanura refinery following an attack in March when assessing the potential repair schedule.

    “A key uncertainty is whether repairs could be completed sooner than 3-5 weeks,” the analysts said.

    An earlier restart could reduce the volume of supply affected by the shutdown.

    Middle East Disruptions Affect Refined-Product Flows

    HSBC also assessed the factors behind higher refined-product prices.

    The bank’s analysis differs from the US administration’s view that Ukrainian attacks on Russian refineries have been the main factor behind record US diesel prices.

    HSBC said it continues to see “the Middle East shock as the dominant driver of the current refining tightness.”

    The bank estimated that refined-product loadings from the Gulf have declined by 3.4 million bpd, including approximately 2.1 million bpd of diesel, jet fuel and gasoline.

    Brent Could Reach $120 in HSBC Scenario

    HSBC said the East-West pipeline outage increases the upside risk to its base-case oil price forecasts.

    The bank also said the disruption raises the probability of its more bearish “Stalemate” scenario, under which Brent crude could potentially reach $120 per barrel.

    HSBC identified three indicators for assessing the impact of the outage: signs of a partial pipeline restart, loading activity at Yanbu and the pace of global inventory declines.