Blog

  • Europa Oil & Gas Extends EG-08 Farm-Out Timeline Pending Final Chinese Approval (EOG)

    Europa Oil & Gas Extends EG-08 Farm-Out Timeline Pending Final Chinese Approval (EOG)

    Europa Oil & Gas (Holdings) plc (LSE:EOG) has agreed with its partners to extend the longstop date for completing the farm-out of a 40% interest in the EG-08 offshore Equatorial Guinea production sharing contract to Fuhai (Beijing) Energy until 31 July 2026.

    The extension is intended to provide additional time for Fuhai to obtain Overseas Direct Investment (ODI) approval from the Shandong provincial authorities, the final regulatory requirement needed to complete the transaction. The farm-out has already received approval from Equatorial Guinea’s Ministry for Mining and Hydrocarbons.

    Final Regulatory Step Before Completion

    Once the outstanding approval is secured, Fuhai will formally join both the production sharing contract and the joint operating agreement governing the licence.

    Following completion, the ownership structure of the project will comprise Antler Global with a 40% working interest and operatorship, Fuhai holding 40%, and state-owned GEPetrol retaining the remaining 20% interest on behalf of Equatorial Guinea.

    Europa holds a 42.9% equity stake in Antler Global, giving it indirect exposure to the offshore exploration project and its future development potential.

    Barracuda-1 Well Remains Key Near-Term Catalyst

    Management continues to target the drilling of the Barracuda-1 exploration well at the earliest practical opportunity, with operations currently expected to commence in early 2027.

    The well represents a significant milestone for the EG-08 licence and forms an important part of Europa’s strategy to expand its presence in West Africa. Success at Barracuda-1 could materially enhance the value of the project and strengthen the company’s position within the region’s offshore exploration sector.

    Outlook

    Europa’s outlook remains constrained by a challenging financial profile, characterised by ongoing losses, declining revenue and negative operating and free cash flow generation. While the company benefits from relatively low leverage, these strengths are currently outweighed by weaker underlying financial performance.

    Technical indicators present a largely neutral picture and do not currently point to a strong directional catalyst for the shares. Valuation metrics are also limited by the company’s negative earnings position, resulting in a negative price-to-earnings ratio, while no dividend yield has been provided.

    More about Europa Oil & Gas

    Europa Oil & Gas (Holdings) plc is an AIM-listed exploration, development and production company with interests spanning West Africa, the UK and Ireland.

    The company’s exposure to the EG-08 licence comes through its 42.9% shareholding in Antler Global, the operator of the offshore Equatorial Guinea production sharing contract. Through this investment, Europa participates in frontier offshore exploration activities alongside national oil company GEPetrol while maintaining a broader portfolio of oil and gas assets across its core operating regions.
  • Eco Buildings Advances Rolling Hills Development With Major Construction Milestone in Albania (ECOB)

    Eco Buildings Advances Rolling Hills Development With Major Construction Milestone in Albania (ECOB)

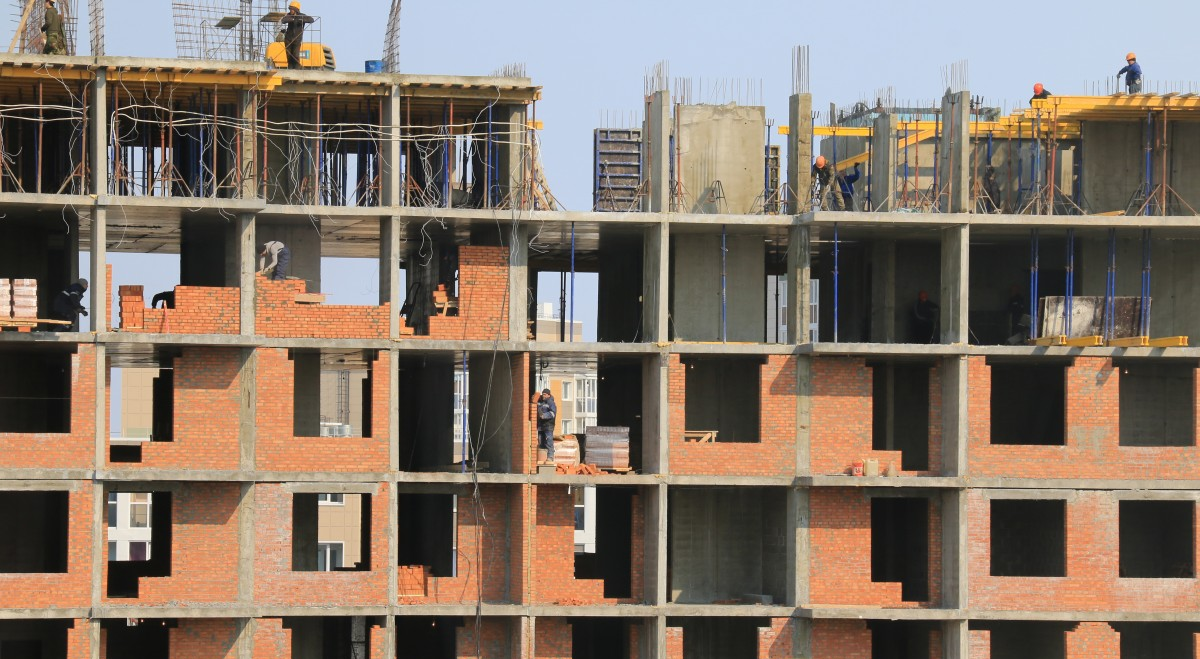
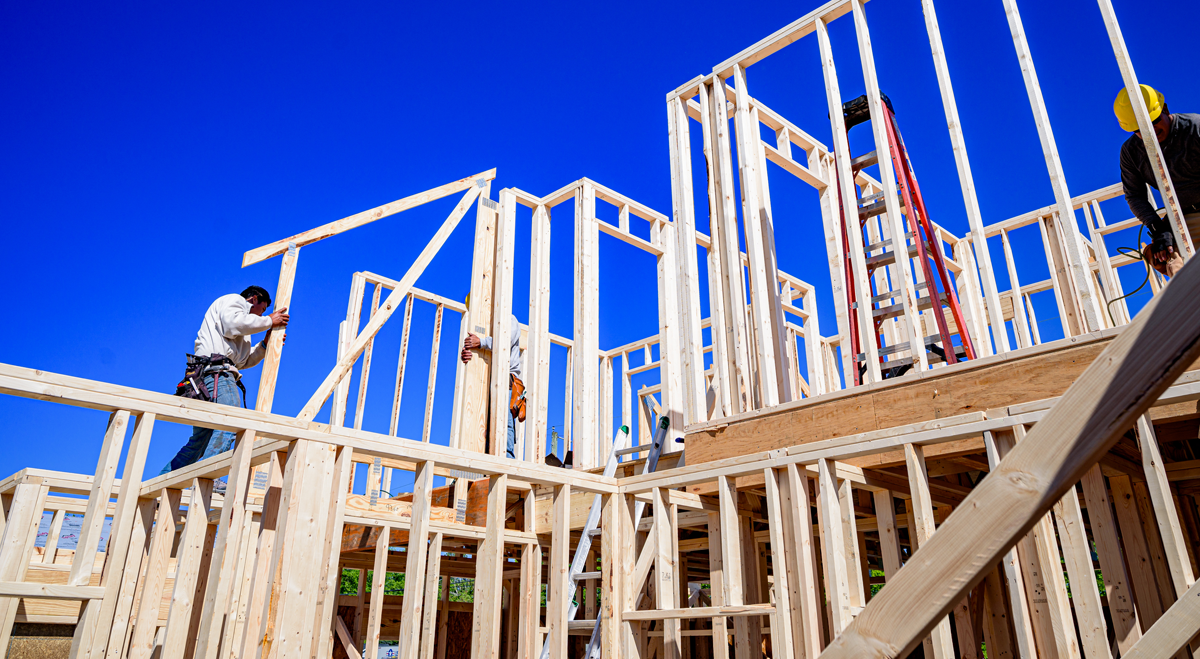
    Eco Buildings Group plc (LSE:ECOB) has achieved an important construction milestone at the Rolling Hills residential project in Tirane, Albania, after completing the second-floor structure of the development’s first apartment building and commencing work on the final storey.

    The block will comprise 18 apartments of approximately 100 square metres each and represents the first of at least six similar residential buildings planned for the site. Management estimates that each apartment block could generate around €2.2 million in revenue and views the development as an important stepping stone ahead of a larger villa project that is currently progressing according to schedule.

    Demonstrating the Scalability of the Business Model

    The Rolling Hills project serves as a practical demonstration of Eco Buildings’ ability to deliver larger-scale residential developments using its proprietary construction technology. The company believes the successful execution of the scheme validates its strategy of creating a repeatable and scalable industrialised housing platform capable of being deployed across different markets and housing segments.

    By applying its Glass Fibre Reinforced Gypsum (GFRG) building system within a premium residential development, Eco Buildings aims to showcase the efficiency, speed and quality of its construction model while building a track record that can support future commercial opportunities.

    Supporting Future Growth Opportunities

    Management believes the progress at Rolling Hills strengthens the company’s position within the evolving housing sector, where demand continues to grow for faster, more cost-effective and environmentally sustainable construction methods.

    The successful delivery of the project could enhance Eco Buildings’ prospects for securing additional contracts and partnerships while supporting its broader objective of expanding the adoption of industrialised housing solutions across multiple geographies.

    Outlook

    Eco Buildings’ outlook continues to be supported by a series of positive corporate developments that highlight potential growth opportunities and commercial progress. However, these strengths are balanced against ongoing challenges related to financial performance and valuation.

    Technical indicators present a mixed picture, with longer-term trends remaining constructive while shorter-term market signals suggest some uncertainty. Management remains focused on executing its development pipeline and demonstrating the commercial viability of its housing technology platform.

    More about Eco Buildings Group

    Eco Buildings Group is a UK-listed technology company specialising in industrialised and prefabricated housing solutions. The business utilises proprietary GFRG panel technology to develop modular residential buildings for both affordable and premium housing markets.

    Its construction system is designed to address key challenges facing the global housing sector, including supply shortages, rising building costs, labour constraints and increasing demand for lower-carbon construction methods. Through scalable manufacturing processes and rapid on-site assembly, Eco Buildings aims to deliver efficient, sustainable and cost-effective housing solutions across a range of residential applications.

  • Kazera Reaches US$10.5 Million Aftan Settlement and Targets Shareholder Cash Distribution (KZG)

    Kazera Reaches US$10.5 Million Aftan Settlement and Targets Shareholder Cash Distribution (KZG)

    Kazera Global plc (LSE:KZG) has entered into a definitive settlement agreement worth US$10.5 million with Hebei Xinjian Construction relating to the long-running dispute over the Aftan asset. The agreement replaces a previous arbitration award and establishes a structured payment programme extending through to December 2029.

    The settlement will become effective once an initial payment of US$500,000 is received from Namibia. It incorporates both loan repayment and share sale elements, with the transfer of ownership in Aftan linked to a series of staged payment milestones supported by security arrangements, pledged assets and default protections.

    Settlement Provides Greater Certainty and Enhanced Value

    When combined with approximately US$4.1 million already received from Hebei, the agreement creates a contractual route for Kazera to receive around US$14.6 million in total proceeds. According to the company, this exceeds the original cash consideration agreed for Aftan in 2022 while reducing the uncertainty, costs and timing risks associated with continued legal enforcement proceedings.

    Management believes the agreement delivers a more predictable outcome and strengthens the company’s financial position by securing a clear framework for future payments.

    Majority of Proceeds Expected to Be Returned to Investors

    Subject to regulatory requirements and other applicable constraints, the board intends to return approximately 80% of the net settlement proceeds to shareholders.

    The initial cash inflows are also expected to strengthen the company’s near-term funding position and support ongoing development activities across its remaining portfolio. These include the advancement of the Whale Head Minerals project, the REMI processing partnership and efforts to secure the important 2A Mining Right.

    Early Settlement Option and Strong Security Protections

    The agreement also provides flexibility through an option allowing Hebei to settle its obligations early for a discounted amount of US$9.0 million if payment is completed by the end of 2026.

    At the same time, Kazera retains significant protection against non-payment through security over Aftan shares and acceleration provisions that can be triggered in the event of a default. Management views the settlement as a key step in resolving legacy issues, unlocking value from historic assets and enabling the company to focus on a more disciplined approach to capital allocation and shareholder returns.

    Outlook

    Kazera’s investment outlook continues to be weighed down by weak financial performance, including the absence of revenue during 2025, ongoing losses and continued cash consumption. These factors contribute to a negative price-to-earnings ratio and reflect the company’s current lack of profitability.

    Technical indicators provide a more balanced picture, with short-term momentum showing signs of improvement, although the longer-term trend remains weak relative to the 200-day moving average. Management believes successful execution of the settlement agreement and progress across its core mining projects could help improve the company’s financial profile over time.

    More about Kazera Global

    Kazera Global plc is an AIM-listed investment company focused on mining and mineral opportunities. The group has previously held interests in African Tantalum (Aftan), a Namibia-based tantalum and lithium operation, and is now concentrating on advancing a streamlined portfolio of resource assets.

    Its current priorities include the development of the Whale Head Minerals project, the processing partnership with REMI at Walviskop and securing the 2A Mining Right. The company aims to generate long-term value through disciplined investment management, project development and strategic capital allocation.

  • Living REIT Adopts New Identity and Targets Growth in Senior Living and Care Homes (SOHO)

    Living REIT Adopts New Identity and Targets Growth in Senior Living and Care Homes (SOHO)

    Living REIT plc (LSE:SOHO), formerly Social Housing REIT PLC, has officially adopted its new corporate name, with the rebranding taking effect on 19 June 2026. The company confirmed that its ISIN, SEDOL, LEI and existing corporate website remain unchanged following the transition. Living REIT continues to trade on the London Stock Exchange’s Main Market and maintains its core focus on UK social housing, particularly specialised supported housing, under the management of Atrato Partners Limited.

    New Ticker and Broader Investment Strategy Planned

    From 23 June 2026, the company will be recognised under its new name on the London Stock Exchange. A change of ticker symbol from SOHO to LIVE, along with the launch of a new corporate website, is expected to follow the company’s general meeting scheduled for 8 July 2026.

    The proposed changes will not affect shareholders’ existing holdings or share certificates. At the same meeting, investors will be asked to approve an expansion of the company’s investment policy to include senior living and care home properties. If approved, the move would represent a significant broadening of the group’s investment remit within the UK housing and social care sectors.

    Outlook

    Living REIT’s investment case continues to be supported by resilient and improving cash-flow generation, although this is partly offset by fluctuations in earnings and net asset value. Market indicators currently point to a mildly negative short-term technical picture, while valuation metrics remain stretched due to a high price-to-earnings ratio.

    However, the company continues to offer an attractive dividend yield, which remains a key component of its shareholder proposition. Management believes that expanding into senior living and care home assets could create additional opportunities for income generation and portfolio diversification over the longer term.

    More about Living REIT

    Living REIT plc is a UK-listed closed-ended investment company focused on acquiring and managing social housing properties. The portfolio is heavily weighted towards specialised supported housing that provides accommodation for vulnerable adults, including individuals with learning disabilities, mental health conditions and physical impairments.

    The company works with regulated Approved Providers, including housing associations and local authorities, to deliver long-term accommodation solutions across the UK. Subject to shareholder approval, Living REIT plans to extend its investment strategy into senior living and care home assets, increasing its exposure to broader areas of the social care and residential property market.

  • Transense Flags Softer Near-Term Performance as Contract Conversions Take Longer Than Expected (TRT)

    Transense Flags Softer Near-Term Performance as Contract Conversions Take Longer Than Expected (TRT)

    Transense Technologies (LSE:TRT), the AIM-listed developer of advanced sensing and measurement technologies, has indicated that trading for the year ended 30 June 2026 will come in slightly below previous expectations as delays in contract progression and softer demand within its Translogik division affected short-term performance.

    The company expects to report revenue of at least £4.6 million, adjusted EBITDA of no less than £0.5 million and an adjusted pre-tax result close to break-even. The revised outlook reflects lower-than-anticipated sales of Translogik products to major global tyre manufacturers, as well as slower customer commitments relating to engineering and development costs.

    SAWsense Growth Offsets Areas of Weakness

    Despite the near-term headwinds, management highlighted continued progress across its SAWsense business, which has delivered increasing revenues and a strengthening commercial pipeline. The company also reported stable royalty income from Bridgestone’s iTrack tyre monitoring system, which continues to provide a recurring revenue stream.

    While several larger commercial opportunities have taken longer to convert than originally expected, Transense said it remains encouraged by ongoing customer engagement and the quality of its pipeline. As a result, expectations for FY27 have been moderated, although management believes the business retains positive operational momentum.

    Medium-Term Confidence Remains Intact

    The board stated that it remains confident in the company’s medium-term growth prospects as it works towards securing a number of significant contracts currently under discussion. Management believes the combination of expanding SAWsense adoption, recurring royalty income and future contract wins positions the business well for longer-term development.

    From an investment perspective, Transense continues to benefit from solid financial fundamentals, including revenue growth, strong gross margins, improving free cash flow generation and minimal leverage. However, these strengths are currently offset by weak technical indicators, with the share price trading well below key moving averages and momentum measures such as RSI and Stochastic indicators remaining at depressed levels. Valuation remains moderately supportive, with the shares trading on a price-to-earnings ratio of approximately 12.16.

    More about Transense Technologies

    Transense Technologies PLC is a UK-based developer of advanced sensing and measurement solutions serving customers across aerospace, automotive, industrial machinery and commercial vehicle markets. The company operates through its SAWsense and Translogik divisions and also receives royalty income from Bridgestone’s iTrack tyre monitoring platform.

    SAWsense specialises in Surface Acoustic Wave sensor technology for mission-critical applications, while Translogik supplies intelligent tyre inspection and management equipment used by leading tyre manufacturers and fleet operators worldwide. Through these complementary businesses, Transense provides data-driven monitoring solutions designed to improve safety, efficiency and operational performance.

  • ValiRx Streamlines Operations and Sharpens Strategy as Auditors Highlight Funding Uncertainty (VAL)

    ValiRx Streamlines Operations and Sharpens Strategy as Auditors Highlight Funding Uncertainty (VAL)

    ValiRx plc (LSE:VAL) has reported its audited results for 2025, outlining the completion of a strategic review that has narrowed the company’s focus to three key priorities while repositioning its Inaphaea BioLabs division to primarily support internal development programmes alongside selected external partnerships. The company also benefited from non-dilutive R&D tax credits and continues to utilise its patient-derived cell (PDC) biobank and collaborative network to advance future pipeline opportunities.

    Cost Reduction and Portfolio Rationalisation

    During the year, ValiRx reduced administrative expenses by more than £300,000 through board and workforce restructuring measures. The company also exited several evaluation and licensing arrangements that were considered outside its strategic focus, while entering new evaluation agreements with organisations including Altus Healthcare and McGill University as part of a more selective commercial approach.

    The group also terminated its TheoremRx agreement, established Blue Ribbon Bio to progress the VAL201 programme, and licensed VAL401 to Ambrose Healthcare in return for an equity interest. In addition, ValiRx expanded its capabilities in AI-driven biomarker discovery and in-silico clinical trials through partnerships with Cellomatics Biosciences and TwinEdge Bioscience.

    Financial Performance and Going-Concern Considerations

    ValiRx recorded a total comprehensive loss of £2.23 million for the year, reflecting substantial goodwill impairments related to VAL401 and VAL201. Excluding these non-cash charges, the company reported an improvement in its underlying loss position.

    Cash resources declined to £0.79 million at the end of 2025, leading management to implement further measures after the reporting period to conserve capital. These actions included voluntary salary reductions and changes to the company’s advisory board structure. Auditors also identified a material uncertainty relating to going concern, citing the group’s dependence on future fundraising activity to support ongoing operations.

    Strategic Outlook

    Management believes the completion of its strategic and operational restructuring has left the business better positioned to navigate the challenging funding environment facing early-stage biotechnology companies. The company is now operating with a leaner cost base and a more selective framework for assessing new opportunities.

    ValiRx intends to focus on advancing higher-quality later-stage assets, extracting greater value from the Inaphaea biobank platform, and expanding targeted academic and commercial collaborations. The company believes this approach could improve its ability to secure partnership agreements, attract non-dilutive funding and generate long-term value for shareholders.

    From an investment perspective, ValiRx continues to face pressure from ongoing losses and its reliance on external financing. Technical indicators point to a generally bearish trend, although some scope for short-term upside remains. Valuation metrics are also challenged by a negative price-to-earnings ratio and the absence of a dividend yield.

    More about ValiRx

    ValiRx plc is a UK-based life sciences company focused on developing early-stage therapies in oncology and women’s health. The business uses its translational research expertise to advance novel drug candidates from pre-clinical development towards clinical readiness and commercial partnering opportunities.

    Through its Inaphaea BioLabs division, which operates a patient-derived cell biobank, and a broad network of academic and industry collaborators, the company aims to reduce development risk and accelerate asset progression. ValiRx typically advances programmes to a value-inflection point before seeking outlicensing or further development through dedicated subsidiary structures and strategic partners.

  • GEO Exploration Flags Strong Early Gold Signs at Western Australia Gorge Project

    GEO Exploration Flags Strong Early Gold Signs at Western Australia Gorge Project

    GEO Exploration Limited (LSE:GEO) has reported positive initial field results from its Gorge Project in Western Australia, where visible and coarse gold has been observed in quartz vein samples at the Gorge Mine, 401 and Central Zone prospects. Geological mapping and structural measurements indicate favourable conditions for orogenic gold mineralisation, supported by extensive historic hard-rock workings and well-exposed metasedimentary rocks.

    The company has collected 35 rock chip samples and 246 orientation soil samples across key target areas, with soils submitted for laboratory analysis to shape a broader geochemistry campaign. Identification of copper-rich gossan and evidence of historic production of lead and silver underscore the project’s multi-commodity potential, while confirmed access, water sources and historic drill collar locations strengthen the groundwork for future systematic follow-up work and potential drilling, subject to approvals.

    More about GEO Exploration Limited

    GEO Exploration Limited is a mineral exploration company listed on London’s AIM market, focused on gold and multi-commodity projects in Western Australia. The company targets orogenic gold systems and associated base metals such as copper, lead and silver, advancing early-stage assets through systematic fieldwork and geochemical programmes.

  • Proteome Sciences Secures New Chemoproteomics Contract Ahead of Planned 2026 Clinical Programme (PRM)

    Proteome Sciences Secures New Chemoproteomics Contract Ahead of Planned 2026 Clinical Programme (PRM)

    Proteome Sciences plc (LSE:PRM) has announced the award of a major new clinical contract tied to its target engagement and chemoproteomics platform, marking another milestone ahead of an anticipated clinical trial programme expected to begin later in 2026. The company said the agreement reflects growing traction for its chemoproteomics offering and follows strong industry engagement at the American Society for Mass Spectrometry conference in San Diego, highlighting increasing demand for its specialist proteomics expertise.

    The contract is expected to strengthen Proteome Sciences’ revenue opportunities while expanding its involvement in clients’ clinical development activities. As programmes advance, the company could benefit from additional follow-on work, reinforcing its position within the contract proteomics sector. Greater exposure among drug development and mass spectrometry professionals may also support future growth in higher-value chemoproteomics projects.

    Outlook and Key Considerations

    Despite positive commercial momentum, Proteome Sciences continues to face financial challenges. The company has been impacted by lower revenues, negative gross margins, ongoing losses and a balance sheet under pressure from increasing debt levels and significantly negative equity.

    From a market perspective, technical indicators provide only limited support. While the shares have experienced a short-term recovery, they remain below the 200-day moving average and the MACD indicator remains negative. Valuation metrics are also constrained by continuing losses, resulting in a negative price-to-earnings ratio, while dividend data remains unavailable.

    More about Proteome Sciences

    Proteome Sciences plc specialises in contract proteomics services designed to support drug discovery, clinical development and biomarker research. The company uses proprietary technologies to analyse tissues, cells and biological fluids, helping researchers identify disease biomarkers and better understand therapeutic targets.

    Its technology portfolio includes SysQuant, TMT MS2 and chemoproteomics platforms such as Solvent Shift and TMTcalibrator, which provide high-sensitivity target identification, mechanism-of-action analysis and biomarker discovery across a broad range of plasma proteins.

    The company also develops targeted mass spectrometry assays that deliver highly accurate biomarker measurements in situations where conventional immunoassays are not available. Through the combination of protein depletion techniques and extensive proteome coverage, Proteome Sciences aims to provide pharmaceutical and biotechnology companies with advanced analytical capabilities for clinical and translational research programmes.

  • Barclays Warns Tighter Monetary Policy Could Test Equity Market Strength

    Barclays Warns Tighter Monetary Policy Could Test Equity Market Strength

    Central Banks Shift Focus Back to Inflation

    Barclays believes a growing number of major central banks are becoming more focused on controlling inflation, a development that could reduce one of the key drivers behind the strong performance of global equity markets in recent years.

    The change comes after a series of policy decisions from leading central banks, many of which cited inflation risks linked to higher energy costs following the Iran conflict and disruptions to shipping through the Strait of Hormuz.

    The European Central Bank delivered its first interest-rate increase since 2023, while the Bank of Japan raised borrowing costs to their highest level since 1995. Both institutions pointed to concerns that energy-related price pressures could spread across broader areas of the economy.

    Federal Reserve Adopts a Firmer Tone

    Although the Federal Reserve left interest rates unchanged this week, policymakers signalled a more hawkish stance than markets had expected.

    Nine Fed officials now anticipate at least one additional rate increase before year-end, compared with none in the central bank’s March projections. Investors also focused on the wording of the Fed’s latest statement under Chair Kevin Warsh, which emphasised the goal of achieving “price stability” while omitting references to maximum employment.

    The Bank of England also kept rates on hold, but Barclays noted that the voting split continued to reflect a hawkish bias despite softer inflation and labour market data.

    Liquidity Could Become a Headwind for Stocks

    Barclays strategist Emmanuel Cau and his team said recent developments represent “a clear shift in the global monetary policy backdrop.”

    They argued: “After a prolonged period of synchronized rate cuts across the Western world, the tailwind from monetary policy easing is behind us. At the same time, uncertainty around the reaction function of central banks, particularly the balance between growth and inflation risks, may contribute to higher bond market volatility.”

    The analysts cautioned that a more aggressive Federal Reserve could eventually begin to undermine one of the main supports for equity markets.

    According to Barclays, if the Fed were to move “more decisively” toward fighting inflation and enter another tightening cycle, “it would start to squeeze liquidity and weaken a key pillar of support that has underpinned bullish equity market returns over the past two years.”

    While the bank stressed that this is not its “base case,” it remains “a risk to monitor.”

    U.S.-Iran Agreement Offers Some Relief

    Despite concerns over monetary policy, Barclays highlighted the positive impact of the interim peace agreement between the United States and Iran.

    The analysts described the deal as “a welcome relief” for investors, noting that lower geopolitical risks have contributed to falling oil prices and eased some inflation concerns.

    Markets are now closely watching the reopening of the Strait of Hormuz, through which around one-fifth of global oil and liquefied natural gas shipments passed before the conflict. Although shipping activity has started to recover, some strategists believe it could take time before traffic returns to pre-war levels.

    Europe May Be Positioned to Benefit

    Barclays sees improving opportunities in Europe as macroeconomic conditions potentially strengthen during the second half of the year.

    The analysts said: “From a regional perspective, the potentially better macro outlook for [the second half] should be supportive of [year-to-date] laggards such as Europe, leading us [to] close our underweight on the region, particularly with positioning still skewed toward a tech/semis-heavy United States.”

    They also highlighted potential opportunities within consumer-focused sectors. “At the sector level, as lower oil prices boost consumer confidence from the lows, the risk-reward for some consumer cyclicals, most notably for luxury, should improve even after their recent short squeeze led bounce,” the Barclays analysts said.

  • Goldman Revises Oil Forecasts Lower as Hormuz Agreement Improves Supply Outlook

    Goldman Revises Oil Forecasts Lower as Hormuz Agreement Improves Supply Outlook

    Goldman Sachs has trimmed its medium-term oil price forecasts after revising its expectations for the recovery of Persian Gulf exports following the announcement of an interim agreement to reopen the Strait of Hormuz.

    The bank now expects regional exports to return to pre-war levels by the end of July, one month earlier than previously forecast, prompting a reassessment of its crude market outlook.

    Under its updated projections, Brent crude is expected to average $80 per barrel in the fourth quarter of 2026, down from the previous forecast of $90, while the 2027 average has been lowered to $75 from $80. Goldman also reduced its WTI estimates, forecasting averages of $75 in late 2026 and $70 in 2027.

    Analysts said the earlier recovery in supply materially reduces the fair value of oil prices over the forecast period. However, they stressed that significant uncertainty remains around the pace and durability of the recovery.

    Goldman described the risks to its assumptions as “two-sided,” noting that stronger Gulf export flows, potential increases in Saudi, UAE and Iranian output, and low global inventories could tighten markets. At the same time, renewed geopolitical tensions, tanker security concerns and the possibility of future disruptions in the Strait of Hormuz could undermine the recovery.

    The bank continues to expect oil prices to remain broadly supported despite forecasting a sizeable market surplus in 2027. Limited storage capacity, recent inventory drawdowns and ongoing strategic stockpiling are expected to help keep prices near long-term equilibrium levels.

    “Some security premium compensating for disruption risk is likely to keep a floor under prices,” the strategists wrote.

    While Goldman’s base case assumes a gradual normalization in exports, it said a prolonged disruption to Hormuz traffic could push Brent above $130 per barrel in late 2026. Conversely, a faster-than-expected recovery in exports combined with weaker demand and stronger production growth could see Brent fall below $60 per barrel during 2027.